
 North America Industrial Silica Sand Market | 2026-2036
North America Industrial Silica Sand Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Silica Sand Market Analytics
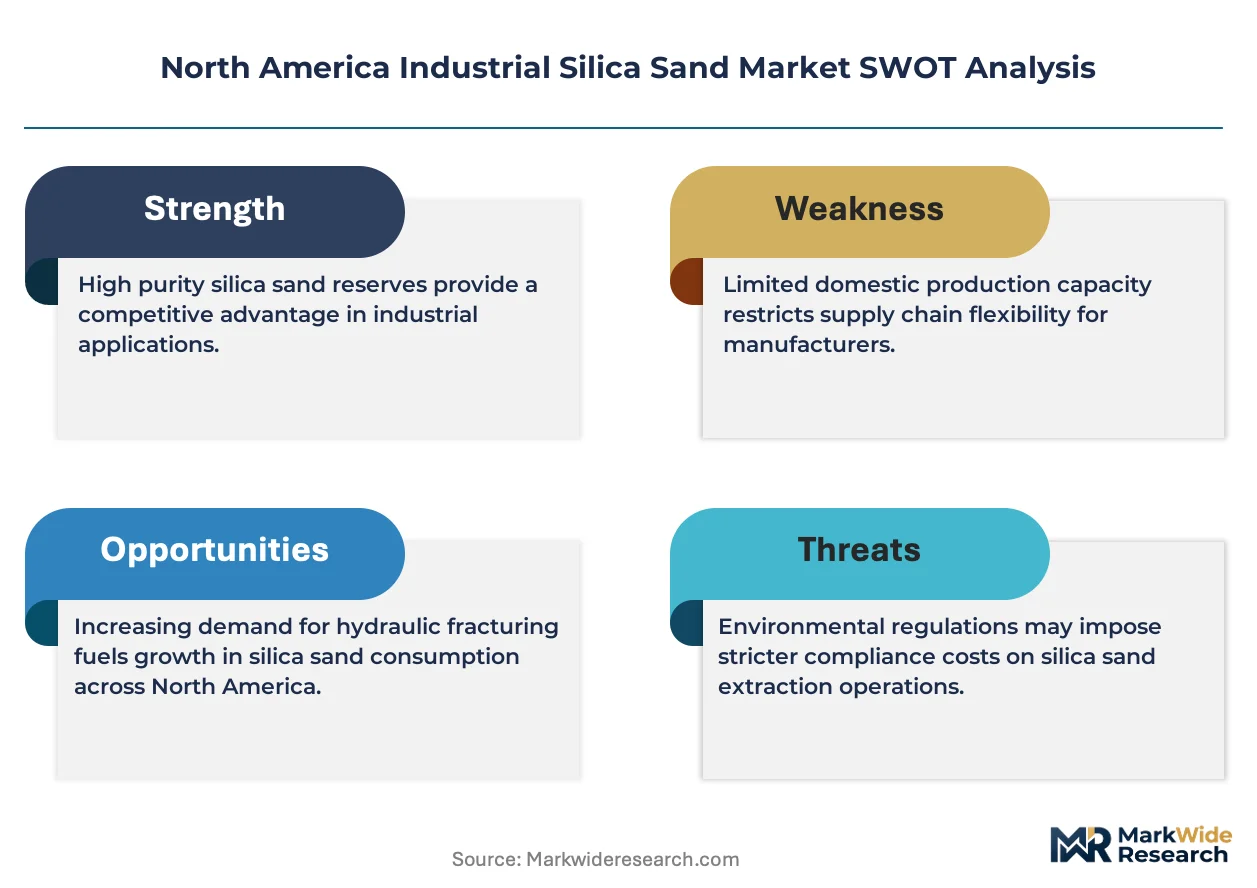
Proppant logistics revenue is rewriting profit distribution across the value chain. U.S. Silica leverages its integrated mine-to-wellhead network to capture margin that previously accrued to third-party haulers. Covia Holdings anchors its position through dense terminal infrastructure in Wisconsin and Illinois. Badger Mining Corporation specializes in coating technologies that extend well performance, allowing it to compete on outcomes rather than tonnage alone.
Industrial silica sand consists of high-purity quartz grains with silica content exceeding 95%, processed through washing, hydraulic classification, and attrition scrubbing to achieve precise sphericity and crush-resistance specifications critical for hydraulic fracturing and glass melt chemistry. The oil and gas application segment dominates volume offtake, with northern white sand from Wisconsin and Minnesota deposits commanding premium placement in deep-basin fracs where closure stress exceeds 8,000 psi. Specialty sand grades for solar glass and semiconductor crucibles represent the fastest-expanding margin pool, though from a smaller base, as domestic solar manufacturing capacity expands.
EPA enforcement of National Ambient Air Quality Standards for respirable crystalline silica constrains greenfield mine permitting timelines, while OSHA's Respirable Crystalline Silica standard mandates engineering controls that elevate capital requirements for surface processing facilities. State-level regulators in Wisconsin, Minnesota, and Texas layer additional reclamation bonding and groundwater monitoring obligations that filter out marginal operators. Stakeholders must weigh exposure to proppant demand cyclicality against the defensive characteristics of construction and container glass segments before committing capital to incremental capacity.
Market Dynamics
Permian Basin operators are demanding finer mesh grades and higher sphericity tolerances, forcing processors to retrofit wet plants with hydrosizer banks and optical sorting lines. This specification creep is compressing margins for legacy dry-screening operations while rewarding capital-intensive upgrades.
Growth Catalysts
- EPA NAAQS enforcement:Stringent particulate matter monitoring is accelerating mine consolidation toward operators with captive processing infrastructure and automated dust suppression systems.
- Texas shale intensity:Multi-mile lateral completions in the Delaware and Midland sub-basins consume 15,000-25,000 tons of northern white sand per well, sustaining offtake volumes despite drilling efficiency gains.
- Solar glass expansion:Domestic photovoltaic manufacturing incentives under the Inflation Reduction Act are pulling ultra-low-iron silica grades into new float-glass furnaces in Ohio and Georgia.
Market Restraints
- Wisconsin-Minnesota supply concentration:Premium northern white sand deposits are geographically locked to the upper Midwest, exposing buyers to rail rate volatility and Great Lakes freeze-thaw logistics constraints.
- OSHA PEL compliance costs:Respirable crystalline silica exposure limits mandate enclosed cab systems and real-time monitoring networks that add $3-5 million per greenfield processing facility.
- Ceramic proppant substitution:High-stress deep-basin wells above 10,000 psi closure stress increasingly specify bauxite-based alternatives, capping northern white sand addressable market at the premium tier.
Strategic Opportunities
- Permian last-mile logistics:Unit train terminals in Monahans and Kermit, Texas enable mine-direct delivery bypassing traditional transload fees, capturing margin from third-party haulers.
- Semiconductor crucible grades:99.99%+ purity silica for polysilicon production represents a nascent but high-margin outlet as domestic chip fabrication capacity expands under CHIPS Act funding.
- Coated sand chemistry:Resin and curable coatings that reduce proppant flowback are commanding 40-60% price premiums over raw sand in extended-reach horizontal completions.
Industry Challenges
- Geological assay talent scarcity:Qualified mining engineers with frac sand sphericity and crush-resistance expertise are concentrated among retiring cohorts in Wisconsin and Minnesota.
- Reclamation bonding escalation:Wisconsin DNR and Minnesota DNR are ratcheting financial assurance requirements for post-closure groundwater monitoring, straining junior operators' balance sheets.
- Real-time quality certification:Wellhead delivery now requires automated sieve analysis and turbidity documentation, forcing legacy plants to integrate X-ray fluorescence and laser diffraction capital equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Silica Sand Market |
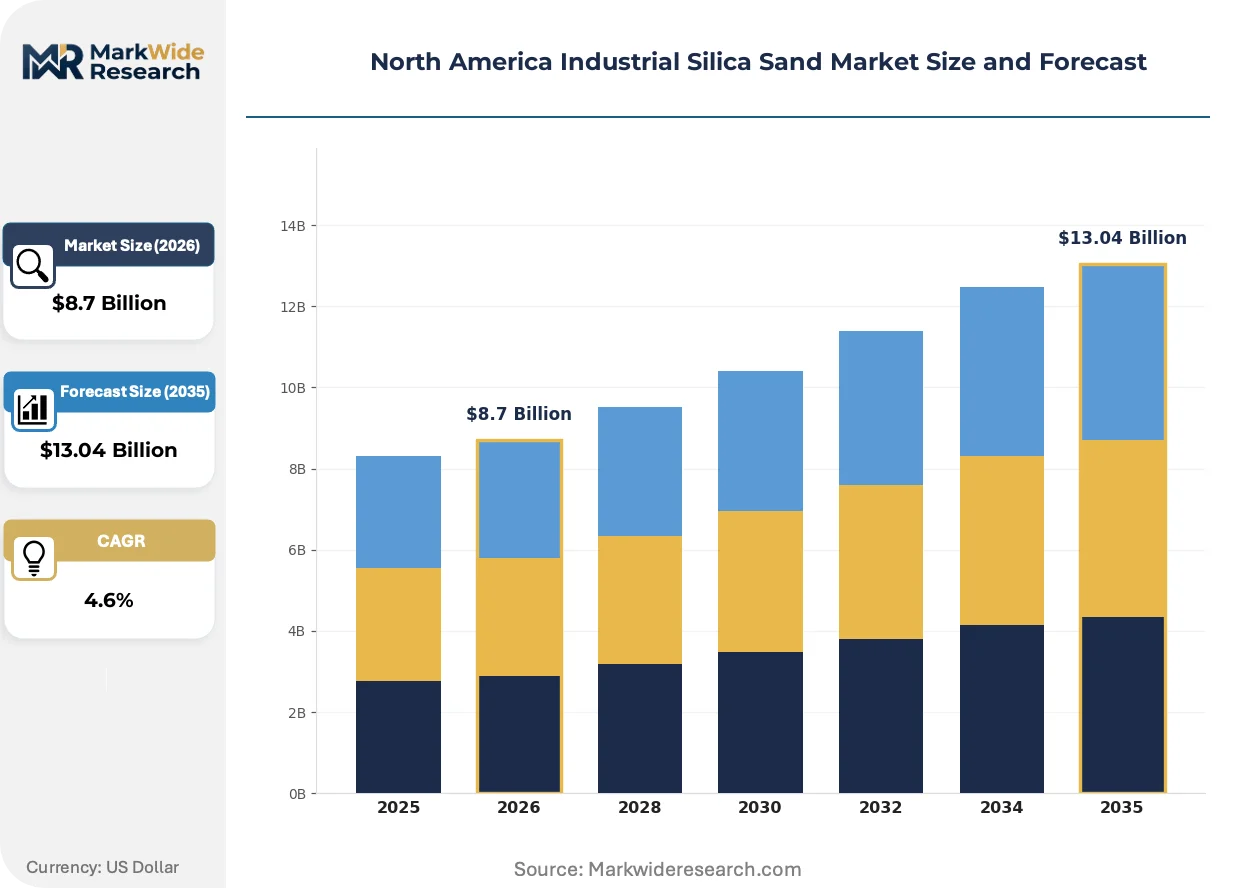
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coarse Sand, Fine Sand, Ultra-Fine Sand, Specialty Sand Application: Glass Manufacturing, Foundry, Oil & Gas, Construction End User: Construction Companies, Oil Producers, Foundries, Glassmakers Distribution Channel: Direct Sales, Online Sales, Retailers, Wholesalers |
| Companies Covered | U.S. Silica, Covia Holdings LLC, Badger Mining Corporation, Hi-Crush Inc., SmartSand, Inc., Atlas Energy Solutions, Source Energy Services, Sibelco, Pattison Sand Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Silica Sand Market Evolving Landscape
Processing technology and logistics automation are compressing the traditional mine-to-wellhead value chain, eliminating intermediary handlers and enabling specification customization at the terminal level rather than the mine mouth.
Automated optical sorting using near-infrared spectroscopy and 3D particle imaging is rendering obsolete manual sieve-stack quality control and batch sampling protocols. E&P procurement teams at Pioneer Natural Resources and Diamondback Energy are specifying real-time sphericity certification as a contract condition. This capability compression is collapsing the traditional 30-45 day lab turnaround into terminal-side minutes, disqualifying non-automated suppliers from premium tier bidding.
OSHA's updated Respirable Crystalline Silica standard is mandating engineering controls that extend beyond personal protective equipment to enclosed cab systems and building pressurization. Surface processing facilities in Texas and Wisconsin are retrofitting baghouses with HEPA final filters and automated shaker cleaning cycles. The oilfield services segment is most exposed, with pressure pumping companies now liable for sand handling exposure at the wellsite, driving specification of pre-conditioned, low-dust coated products.
Buyer concentration among integrated shale operators is consolidating procurement decisions into centralized supply chain functions with direct mine contracting authority. Traditional proppant distributors and regional sand brokers are losing volume to unit train arrangements and mine-direct terminal partnerships. This disintermediation is most advanced in the Permian Basin, where Occidental Petroleum and ExxonMobil have established captive logistics networks linking Wisconsin mine sources to West Texas well pads with minimal intermediary handling.
North America Industrial Silica Sand Market Segmentation
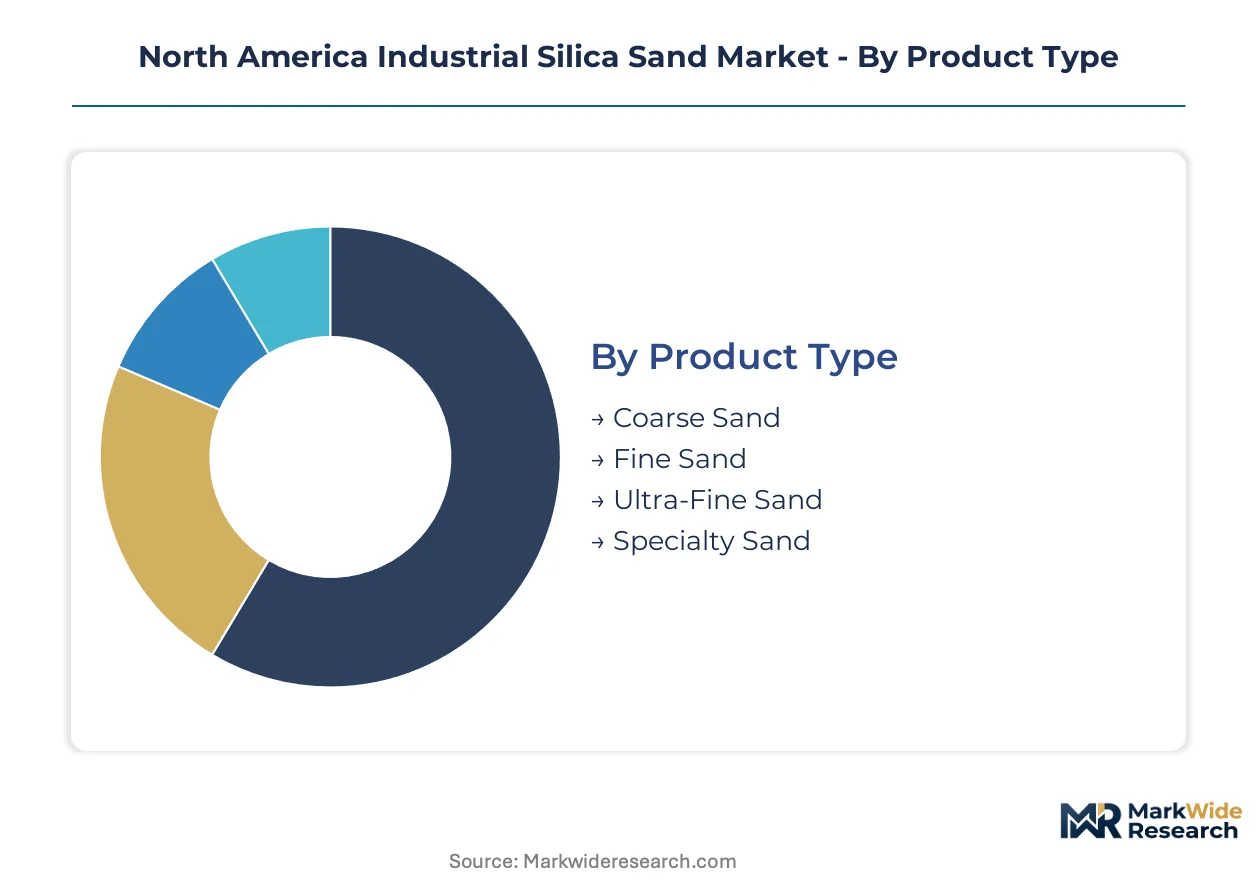
Industrial silica sand markets fragment sharply across specification grades and procurement channels. Each segment carries distinct margin profiles, capital intensity requirements, and exposure to regulatory enforcement patterns across North American jurisdictions.
Product Type:
After-sales technical support intensity varies dramatically by grain specification, with specialty grades demanding ongoing assay certification and frac sand requiring well-performance validation.
- Coarse Sand:Grains retain 0.5-2.0 mm diameter with lower sphericity tolerances. Construction backfill and hydraulic concrete applications in Texas and Florida absorb steady volumes, though pricing remains compressed by regional aggregate competition.
- Fine Sand:Processed to 0.1-0.5 mm with controlled turbidity below 250 FTU. Oil & gas proppant specifications in the Permian Basin and Eagle Ford drive premium placement where crush resistance exceeds 6,000 psi closure stress.
- Ultra-Fine Sand:Sub-100 micron grades for precision foundry molds and ceramic body formulations. Demand clusters around automotive casting operations in Michigan and Ohio.
- Specialty Sand:Ultra-low-iron content below 0.01% Fe2O3 for solar glass and semiconductor crucible applications. Domestic photovoltaic manufacturing expansion in Georgia and Ohio pulls volumes from traditional foundry outlets.
Coarse sand holds the largest share; momentum sits with specialty sand as solar manufacturing incentives redirect procurement patterns.
Application:
Capital deployment intensity separates segments, with oil & gas requiring integrated terminal infrastructure while construction tolerates fragmented supply.
- Glass Manufacturing:Container, flat, and specialty glass furnaces demand consistent chemistry with silica content above 99.5%. Float-glass expansion in Ohio and Georgia under Inflation Reduction Act incentives is expanding ultra-low-iron offtake.
- Foundry:Green sand molding and chemically bonded systems require controlled AFS grain fineness numbers between 50-70. Automotive casting demand in Michigan and Indiana maintains baseline consumption despite foundry consolidation.
- Oil & Gas:Hydraulic fracturing proppant specifications mandate sphericity above 0.6 and acid solubility below 2%. Northern white sand from Wisconsin dominates Permian Basin completions where lateral lengths exceed 10,000 feet.
- Construction:Mortar, grout, and athletic field infill applications accept lower purity thresholds. Infrastructure spending in Texas and California sustains regional quarry competition.
Oil & gas commands the highest revenue per ton; solar glass feedstock requirements are expanding fastest among industrial outlets.
End User:
Procurement sophistication divides buyers, with integrated oil producers negotiating mine-direct contracts while construction firms rely on distributor networks.
- Construction Companies:Regional contractors and national infrastructure builders purchase through aggregate distributors. Volume concentration in Texas, California, and Florida drives logistics optimization toward rail-served terminals.
- Oil Producers:E&P operators and pressure pumping companies specify proppant chemistry directly with mine operators. Pioneer Natural Resources and Diamondback Energy maintain captive logistics networks bypassing traditional proppant brokers.
- Foundries:Automotive and industrial casting facilities require consistent AFS grain distributions and minimal clay content. Midwestern metalcasting clusters in Michigan and Ohio anchor demand.
- Glassmakers:Container glass producers, float-glass operators, and specialty glass manufacturers enforce tight chemical specifications. Solar glass expansion is pulling ultra-low-iron grades from traditional container outlets.
Glassmakers represent the most fragmented buyer base; oil producers are consolidating procurement authority fastest.
Distribution Channel:
Channel selection determines working capital requirements and exposure to rail rate volatility across North American freight corridors.
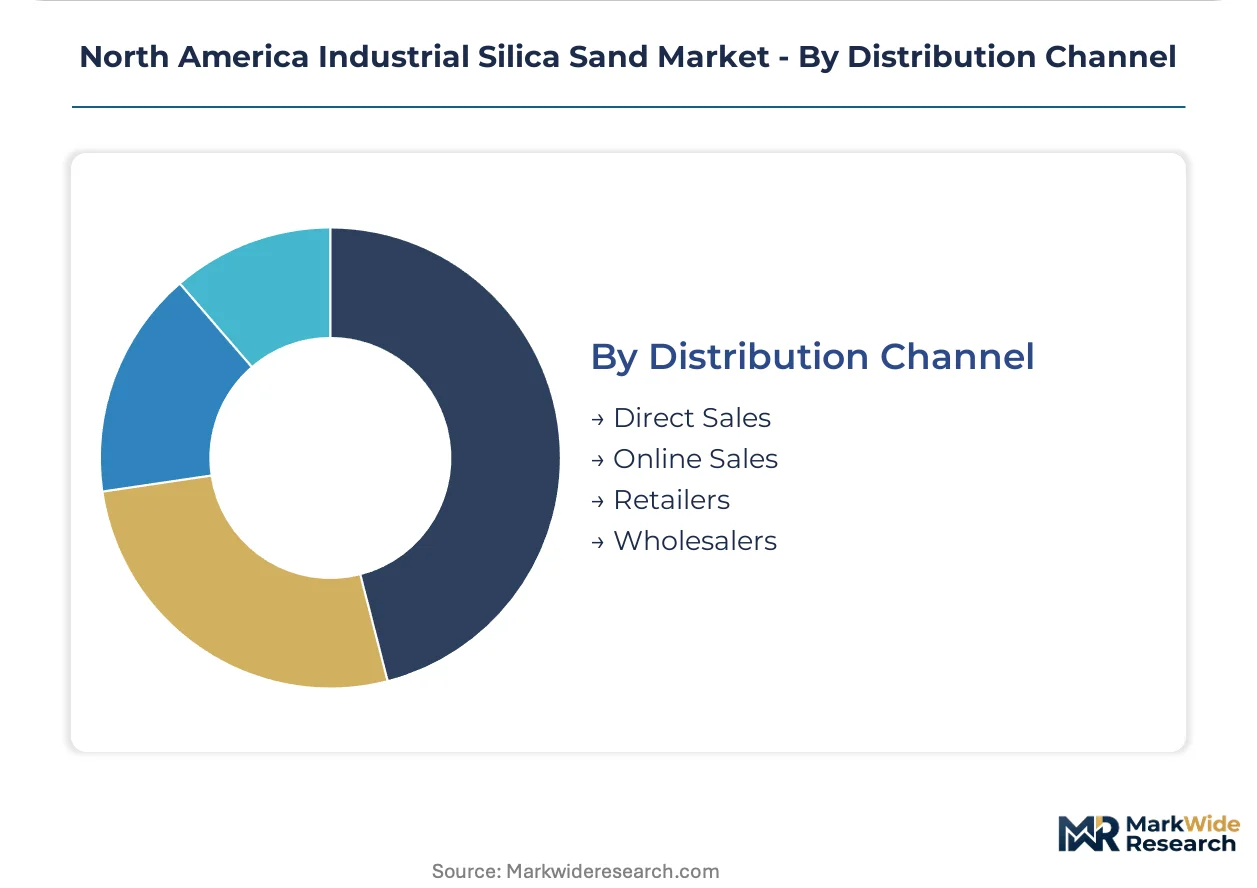
- Direct Sales:Mine-to-wellhead and mine-to-furnace arrangements eliminate intermediary margins. U.S. Silica and Covia Holdings leverage captive terminal networks to serve Permian Basin operators and Midwestern glass plants.
- Online Sales:Digital procurement platforms for construction and foundry grades remain nascent. Bulk commodity logistics constraints limit penetration beyond packaged specialty products.
- Retailers:Regional building material distributors serve renovation and small-scale construction. Geographic fragmentation limits volume concentration.
- Wholesalers:Traditional proppant brokers and aggregate distributors face margin compression as unit train arrangements disintermediate handling. Transload fees at Chicago and Houston hubs are under pressure from mine-direct alternatives.
Direct sales dominate value capture; online platforms are gaining traction slowest due to bulk handling constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin operators exhibit the lowest price elasticity, absorbing rail rate volatility for northern white sand sphericity above 0.6, while construction buyers in Florida and California switch to regional aggregate substitutes when delivered costs rise.
United States
Texas shale intensity drives 60% of regional proppant consumption, with Delaware and Midland sub-basin laterals consuming 15,000-25,000 tons per well. EPA NAAQS enforcement accelerates mine consolidation toward automated dust suppression systems. Wisconsin and Minnesota deposits anchor premium northern white sand supply, with rail corridors linking upper Midwest mines to Monahans and Kermit terminal networks.
Canada
Alberta oil sands and Saskatchewan potash operations sustain steady industrial sand offtake for hydraulic and chemical applications. Health Canada particulate matter guidelines align with OSHA thresholds, elevating capital requirements for surface processing retrofits. Ontario and Quebec glass manufacturing clusters pull ultra-low-iron grades for container and specialty furnace feedstock under federal clean technology investment tax credits.
Mexico
Bajío Region automotive foundries and northern border maquiladora glass plants generate construction and foundry-grade demand. Federal environmental standards under SEMARNAT tighten reclamation bonding for silica extraction concessions. Nuevo León and Coahuila industrial corridors concentrate procurement through rail-served terminals serving Monterrey manufacturing basins.
North America Industrial Silica Sand Market Competitive Landscape
Integrated mine-to-wellhead operators and regional terminal specialists split the market between captive logistics networks and third-party distribution channels. Consolidation favors capital-intensive players with automated processing infrastructure and multi-modal terminal assets. Three archetypes dominate: Wisconsin-Minnesota mine operators with rail dominance, Permian Basin last-mile logistics integrators, and coating technology specialists commanding outcome-based premiums. Competitive moves center on unit train terminal partnerships and hydrosizer plant retrofits for finer mesh specifications.
Within the integrated logistics tier, U.S. Silica and Covia Holdings exemplify mine-to-wellhead archetypes with dense terminal infrastructure spanning Wisconsin, Illinois, and West Texas. Badger Mining Corporation occupies a specialist position in coating technologies that extend well performance. These three entities anchor the competitive structure, representing distinct strategic bets on vertical integration depth versus technical differentiation.
| Leading Market Players |
|---|
| U.S. Silica |
| Covia Holdings LLC |
| Badger Mining Corporation |
| Hi-Crush Inc. |
| SmartSand, Inc. |
| Atlas Energy Solutions |
| Source Energy Services |
| Sibelco |
| Pattison Sand Company |
| Others |
Value Network & Pricing Analysis
Wisconsin's St. Peter sandstone formation anchors premium northern white sand capacity, concentrating sphericity-certified supply among three integrated operators whose mine-direct terminal networks command 15-20% logistics cost advantages over third-party haulers. This geographic lock-in translates to pricing power at the wellhead, where Permian Basin E&P operators absorb rail rate volatility rather than compromise on crush-resistance specifications exceeding 8,000 psi closure stress.
Pricing Analysis
Coated sand service contracts and resin-chemistry warranties now drive lifetime value capture, with curable proppant packages commanding 40-60% premiums over raw sand tonnage. Three-tier pricing structure across premium northern white, regional brown sand, and construction-grade silica separates buyers by well depth and closure stress tolerance. Cost compression in standard mesh grades is intensifying because legacy dry-screening plants cannot retrofit for hydrosizer precision without $8-12 million capital outlays. Integrated shale operators exhibit the lowest price sensitivity, while regional construction contractors in Florida and California switch to limestone aggregate substitutes when delivered silica costs rise above $45 per ton.
Supply Chain Analysis
Rail rate volatility between Wisconsin and West Texas dominates supply chain risk exposure, with BNSF and Union Pacific corridor pricing subject to fuel surcharge fluctuations and crew availability constraints. Mine-mouth concentration in Barron County, Wisconsin and Ottawa County, Illinois feeds from St. Peter and Jordan sandstone deposits with 99.5%+ silica purity. Single-source vulnerability concentrates in hydrosizer equipment supply, with McLanahan and CDE Global controlling 70% of wet-plant retrofit capacity. Distribution runs through unit train terminals at Monahans and Kermit, Texas, bypassing Chicago and Houston transload fees that previously captured 8-12% of delivered cost.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proppant logistics platform economics are concentrating procurement authority into mine-direct terminal networks, with interoperability between automated quality certification systems and E&P supply chain software becoming the decisive competitive moat.
For Market Incumbents: Harden terminal infrastructure in the Permian Basin through captive unit train partnerships with BNSF and Union Pacific, insulating against ceramic proppant substitution above 10,000 psi closure stress. Invest in X-ray fluorescence and laser diffraction equipment for real-time sphericity certification, as Pioneer Natural Resources and Diamondback Energy now mandate automated assay documentation as a contract condition. Backward integration into coating chemistry capabilities protects margin from raw sand commoditization. For New Entrants and Emerging Players: Semiconductor crucible-grade silica for polysilicon production represents the most penetrable entry point, with 99.99%+ purity specifications commanding 300-400% premiums over frac sand and CHIPS Act funding expanding domestic chip fabrication capacity. Solar glass feedstock for Ohio and Georgia float-glass furnaces offers second-mover opportunity as Inflation Reduction Act incentives redirect procurement from container glass outlets. A technical sales model emphasizing assay certification partnerships with polysilicon producers bypasses capital-intensive mine development. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors coating technology specialists with resin-chemistry IP and automated terminal operators with hydrosizer-equipped wet plants over legacy dry-screening assets. Long-term viability hinges on exposure to defensive solar glass and semiconductor segments rather than pure proppant cyclicality. The signal to watch is EPA NAAQS enforcement acceleration in Wisconsin and Minnesota, which would force consolidation toward automated dust suppression systems and strain junior operators' reclamation bonding capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrosizer Wet Plant Retrofit | Enables finer mesh production for Permian Basin lateral completions exceeding 12,000 feet. |
| Unit Train Terminal Partnership | Mine-direct delivery to Monahans and Kermit bypasses $12-18 per ton transload fees. |
| Resin Coating Chemistry Investment | Curable proppant systems reduce flowback and command outcome-based pricing premiums. |
| Automated Quality Certification Integration | Real-time sphericity documentation satisfies Pioneer and Diamondback contract conditions. |
| Semiconductor Crucible Grade Development | 99.99%+ purity silica captures CHIPS Act-funded polysilicon expansion in Arizona and Texas. |
Research Methodology
A standing panel of mine operations managers, E&P supply chain directors, terminal logistics coordinators, and glass furnace procurement leads provided ongoing calibration against operating reality across the analysis window. Primary fieldwork combined structured interviews with Wisconsin and Minnesota mine operators, Permian Basin pressure pumping companies, and Ohio float-glass manufacturers with secondary validation through EPA enforcement records, OSHA compliance databases, FERC rail rate filings, and SEC 10-K disclosures from listed silica sand producers. Bottom-up tonnage estimates by specification grade triangulated against top-down revenue projections from rail carload data and terminal throughput reports.
Scenario-bracketing around EPA NAAQS enforcement intensity, OSHA PEL compliance cost trajectories, and Permian Basin drilling efficiency gains anchored the projection framework across the modeling period. Segmentation dimensions modeled include product grade tier, end-use application, procurement channel structure, and regional production hub. CAGRs derived from weighted average of historical rail carload growth, well completion intensity per lateral foot, and solar glass furnace capacity expansion announcements. Industry-specific forecast inputs incorporated hydrosizer retrofit adoption curves and unit train terminal commissioning timelines.
Macroeconomic conditions sit as an overlay; deviation in shale operator capital discipline, photovoltaic manufacturing investment flows, or rail labor contract outcomes would shift the trajectory. Forecasts reflect assumptions around regulatory enforcement continuity and proppant specification stability that warrant reassessment if ceramic substitution accelerates or EPA particulate standards tighten further. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
3D Glass Substrate Market
Glass
Sapphire Glass Market
Glass
Glass Tableware Market
Glass
Solar Control Glass Market
Glass
United States Flat Glass Market
Glass
Global Ultra-Thin Glass Market
Glass
Glass Mat Market
Glass
Asia Pacific Flexible Glass Market
Glass
Crystalware and Glassware Market
Glass
Antibacterial Glass Market
Glass
Coated Solar Control Glass Market
Glass
Global Vitrification Market
Glass
Fiberglass Window Market
Glass
Europe Sapphire Glass Market
Glass
Antiglare Glass Market
Glass
Glass Forming Machine Market