
 India Flat Glass Market | 2026-2036
India Flat Glass Market Size, Share, and Industry Trends Forecast 2026-2036
India Flat Glass Market Outlook
Energy-performance contracting and building-envelope retrofit services are restructuring how flat glass creates value beyond commodity sales. Saint-Gobain leverages its technical advisory networks to anchor premium specification relationships with large developers. Asahi India Glass sustains manufacturing scale across multiple Indian states, competing on logistics reach and batch flexibility. Borosil Renewables specializes in solar glass formulations, differentiating through tempered coatings that withstand desert thermal cycling.
Flat glass comprises silica sand, soda ash, and limestone melted at approximately 1500°C, then floated on molten tin to produce uniform sheets with optical clarity for architectural glazing, vehicle windshields, and photovoltaic modules. Float glass occupies the dominant volume position due to its cost efficiency in high-rise construction across Indian metros. Tempered glass captures expanding share in automotive and safety applications where fragmentation resistance commands price premiums. Coated glass carries concentrated margins in green-building projects seeking solar heat gain coefficient compliance.
BIS mandates IS 2553 and IS 14900 standards for structural and automotive glazing, while state-level energy conservation building codes in Gujarat and Maharashtra enforce U-value thresholds that filter non-compliant imports. The Bureau of Energy Efficiency's star-rating program for fenestration products redirects procurement toward low-emissivity and double-glazed assemblies. Stakeholders must monitor evolving state-level amendments to the Energy Conservation Building Code and assess captive solar glass capacity before committing to long-term supply agreements.
Market Dynamics
Energy-efficiency mandates from BIS and state building codes are compressing specification windows for commodity glass while amplifying premiums for coated and double-glazed assemblies. This regulatory tightening is redrawing competitive advantage toward technical advisory capabilities and captive solar glass capacity.
Growth Catalysts
- Solar deployment acceleration:Photovoltaic installations across Gujarat and Rajasthan are pulling tempered solar glass volumes. Desert thermal cycling requirements favor domestic suppliers with proven coating durability.
- ECBC amendments:Maharashtra and Gujarat energy conservation building codes now enforce U-value thresholds for fenestration. Non-compliant imports face automatic disqualification from government projects.
- Automotive safety upgrades:Windshield fragmentation standards under IS 2553 are displacing annealed glass in passenger vehicles. Tempered and laminated formulations capture expanding share.
Market Restraints
- Soda ash import dependency:Domestic flat glass production relies on imported soda ash from the United States and Turkey. Currency volatility and shipping disruptions transmit directly into batch cost instability.
- Natural gas price exposure:Float furnaces consume substantial natural gas for 1500°C melting operations. Pipeline infrastructure gaps in eastern states concentrate high-efficiency capacity in Gujarat and Maharashtra.
- Fragmented downstream fabrication:Small-scale tempering and coating operations lack scale for consistent IS 14900 compliance. Quality variance creates liability exposure for primary manufacturers.
Strategic Opportunities
- Eastern state penetration:Odisha and West Bengal construction activity outpaces local flat glass supply. Logistics optimization from existing eastern float lines captures underserved volume.
- Building envelope retrofit services:Energy-performance contracting models bundle glass replacement with guaranteed savings. Large commercial developers in Bengaluru and Hyderabad seek turnkey facade upgrades.
- PLI scheme for solar glass:Production-linked incentives for photovoltaic component manufacturing reduce capital intensity for tempered coating capacity expansion.
Industry Challenges
- Skilled furnace operations talent:Float glass melting requires experienced engineers for tin bath chemistry control and defect minimization. Training pipelines lag capacity expansion timelines.
- BIS certification timelines:IS 2553 and IS 14900 testing protocols extend product launch cycles. Laboratory backlog delays specification approvals for innovative coating formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Flat Glass Market |
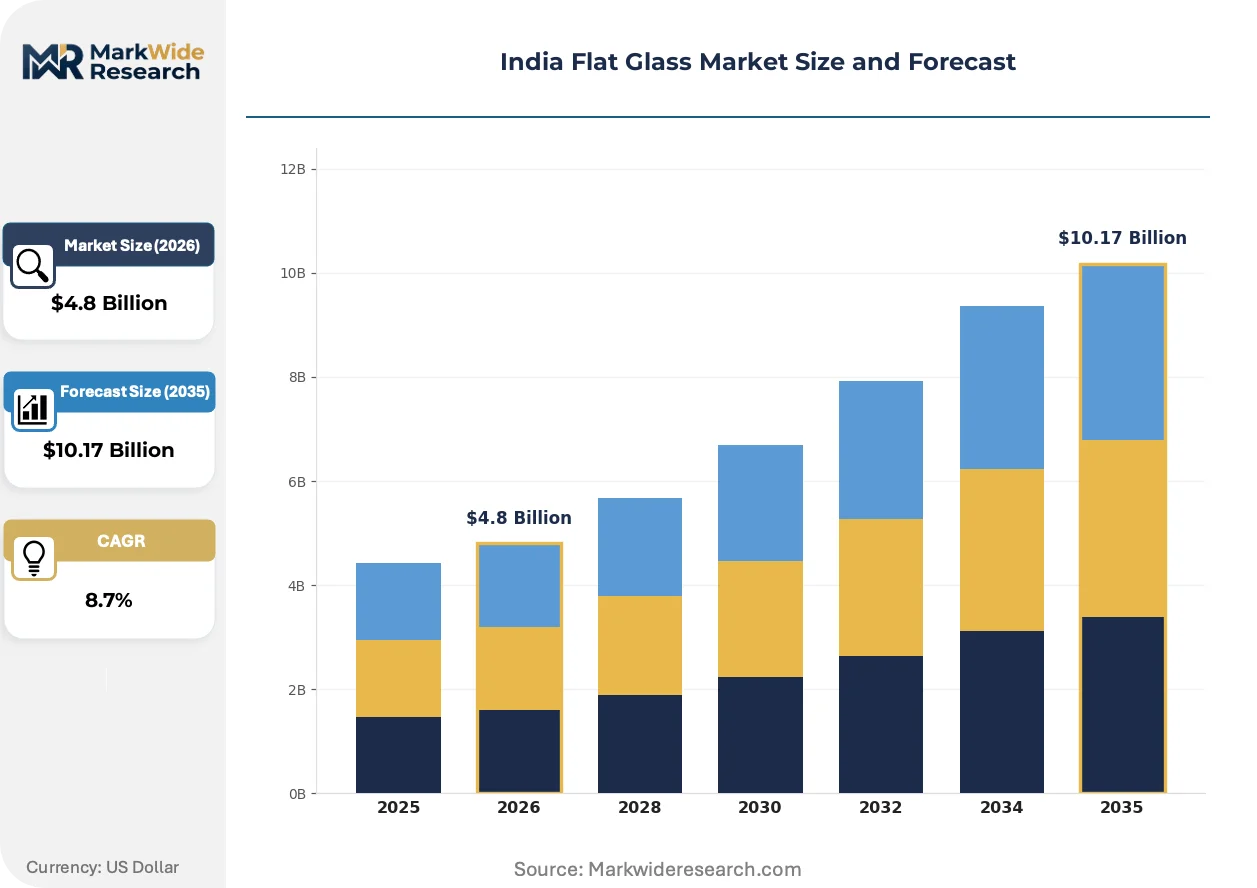
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Float Glass, Laminated Glass, Tempered Glass, Coated Glass Application: Architectural, Automotive, Furniture, Solar Energy End User: Construction, Automotive Manufacturers, Home Decor, Retail Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Asahi India Glass, Saint-Gobain, Gold Plus Float Glass, Gujarat Guardian, Şişecam, Guardian Industries, Nippon Sheet Glass, Borosil Renewables, FUSO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Flat Glass Market Strategic Shifts
Technical differentiation is migrating from glass composition toward integrated facade systems and smart coating architectures. Manufacturers are repositioning from commodity suppliers to building-envelope solution architects.
Low-emissivity coatings with spectrally selective properties are expanding into high-rise residential towers across Mumbai and Delhi NCR. Developers seeking green-building ratings specify double-glazed units with argon fill and warm-edge spacers. Saint-Gobain and Asahi India Glass technical teams now embed directly into architect selection processes, compressing traditional distributor influence.
Bureau of Energy Efficiency star-rating mandates for fenestration products are restructuring procurement qualification criteria. Window and facade contractors must now submit certified U-value and solar heat gain coefficient documentation. This documentation burden filters smaller fabricators from premium project pipelines while concentrating specification authority with integrated glass-and-aluminum system providers.
Large commercial developers are consolidating vendor relationships around energy-performance guarantees rather than unit-price tenders. Long-term service contracts covering glass replacement, coating maintenance, and thermal performance monitoring displace spot purchasing. This contractual evolution is most visible in Bengaluru IT park developments and Hyderabad pharmaceutical campus expansions, where lifecycle cost models override first-cost minimization.
India Flat Glass Market Segmentation
Flat glass specifications in India diverge sharply across end-use applications, with thermal performance mandates and safety codes fragmenting what was historically a commodity market. Understanding these segment boundaries clarifies where technical differentiation commands premium pricing versus where logistics scale determines competitive position.
Product Type:
Upgrade cycles vary dramatically by product category, with architectural retrofit demand pulling advanced formulations while automotive replacement maintains steady volume for safety-rated products.
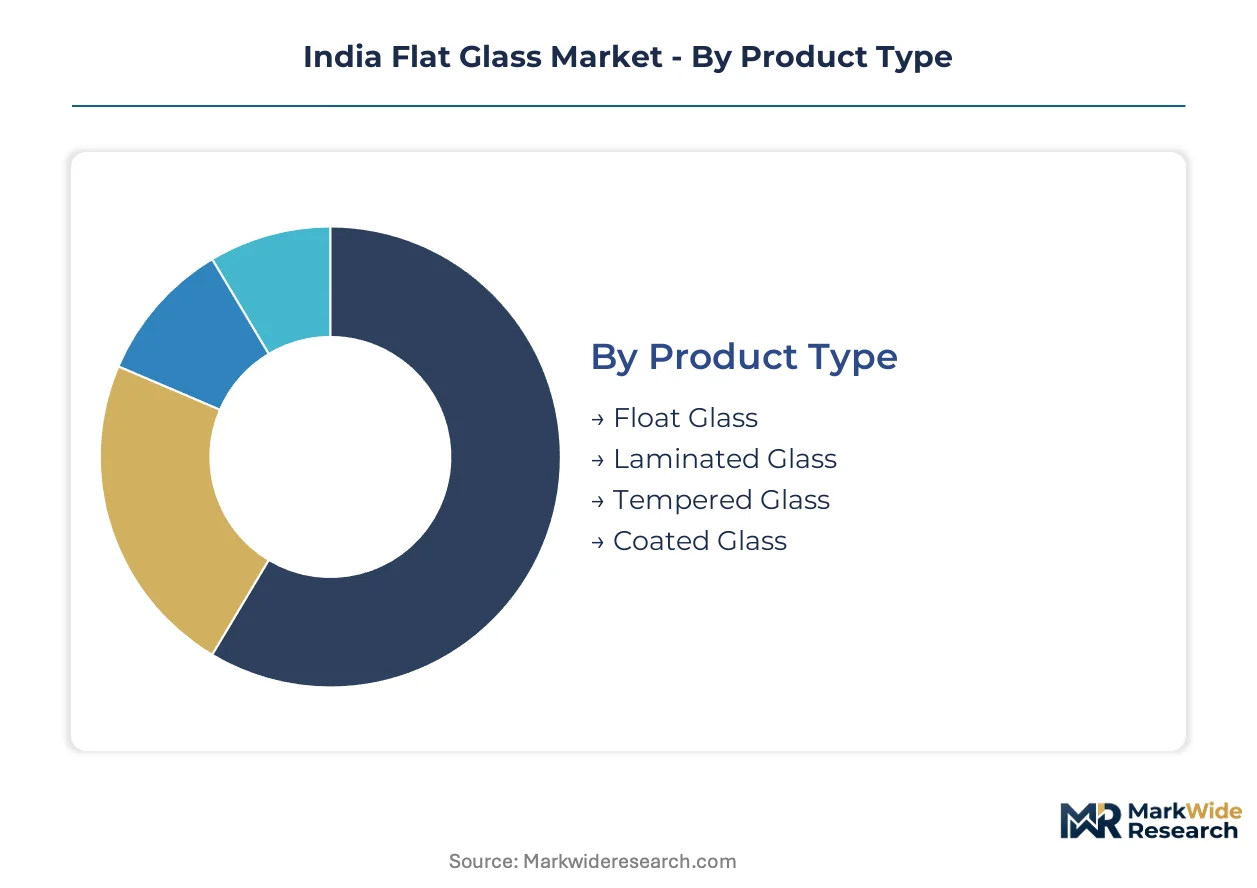
- Float Glass:Silica-sand-soda ash-limestone formulations melted at 1500°C and floated on molten tin deliver uniform optical clarity for high-rise glazing across Mumbai and Delhi NCR. Mass residential tower construction in these metros sustains dominant volume placement despite thinner margins.
- Tempered Glass:Rapid thermal quenching creates surface compression that fragments into small granular pieces upon breakage, satisfying IS 2553 automotive windshield mandates and facade safety codes. Passenger vehicle production in Chennai and Pune anchors consistent offtake.
- Laminated Glass:Polyvinyl butyral interlayers bond glass plies for penetration resistance in hurricane-prone coastal zones and premium architectural applications.
- Coated Glass:Low-emissivity and spectrally selective layers enable solar heat gain coefficient compliance under Maharashtra and Gujarat energy conservation building codes.
Volume placements concentrate in Float Glass; the faster expansion belongs to Coated Glass.
Application:
Cost-tier stratification separates specification-intensive projects from price-sensitive replacement markets, with certification burdens filtering supplier participation.
- Architectural:Fenestration and curtain walling for commercial towers and residential high-rises constitutes the largest value pool, with BEE star-rating mandates redirecting procurement toward documented U-value performance.
- Automotive:OEM windshields and aftermarket replacement demand tempered and laminated formulations meeting IS 2553 fragmentation standards; electric vehicle production growth in Tamil Nadu pulls specialized lightweight glazing.
- Furniture:Tabletops, shelving, and decorative partitions utilize annealed and tempered variants with lower certification thresholds than structural applications.
- Solar Energy:Photovoltaic module manufacturing in Gujarat and Rajasthan requires tempered solar glass with anti-reflective coatings proven against desert thermal cycling.
Architectural applications dominate current revenue; solar energy installations are climbing the fastest.
End User:
Customer-type concentration shapes channel strategy, with large developers demanding technical advisory integration while fragmented retail tolerates longer logistics lead times.
- Construction:Large commercial developers in Bengaluru and Hyderabad now procure through energy-performance contracting models bundling glass with guaranteed thermal savings.
- Automotive Manufacturers:OEM supply agreements require batch traceability and just-in-sequence delivery to assembly plants in Maharashtra and Tamil Nadu.
- Home Decor:Interior designers and residential renovators source decorative glass through distributor networks with fabrication customization.
- Retail:Independent hardware stores and building material outlets serve small contractors with standard sheet sizes and limited technical support.
Construction sector placements lead by value; automotive manufacturers impose the strictest qualification protocols.
Distribution Channel:
Supply concentration in Gujarat and Maharashtra float lines dictates channel efficiency, with direct relationships capturing high-volume projects and intermediaries serving geographic dispersion.
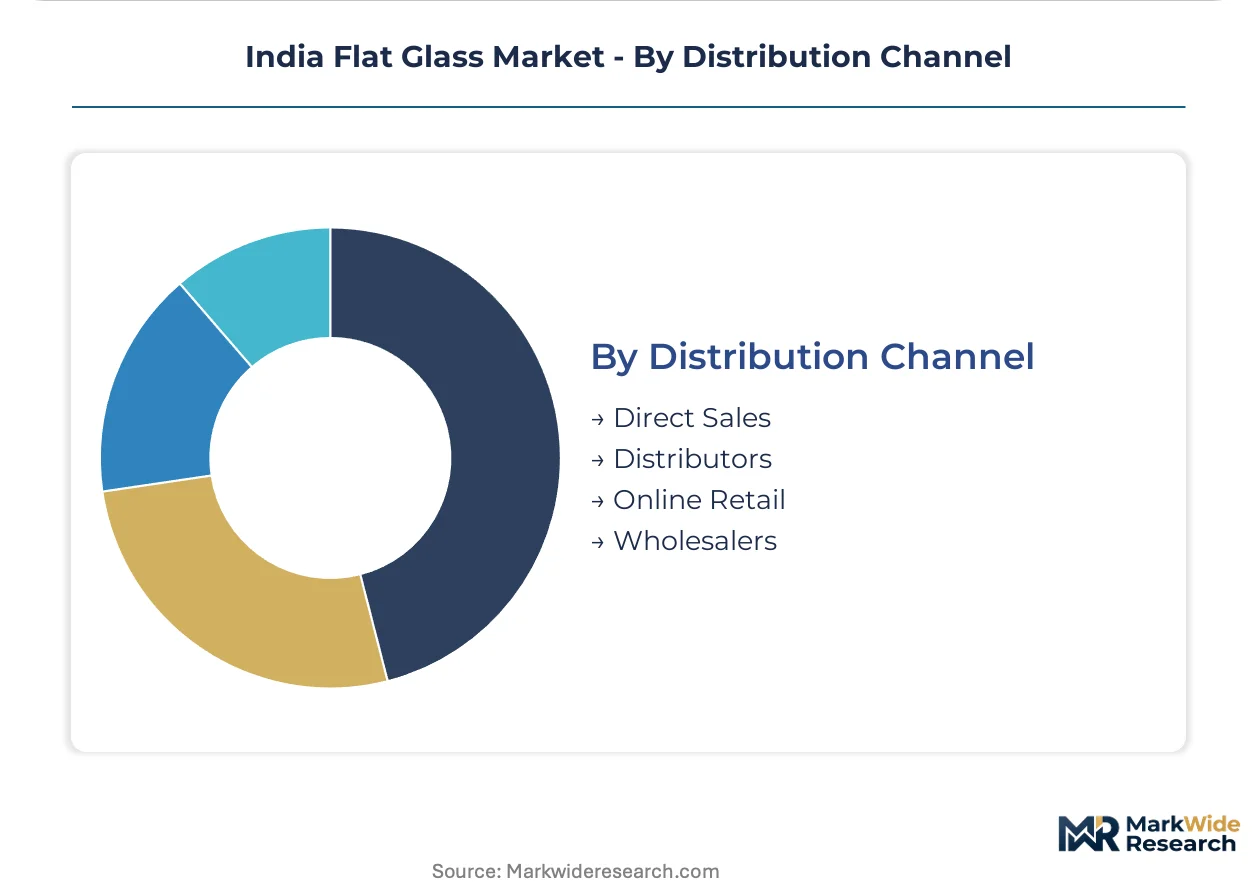
- Direct Sales:Saint-Gobain and Asahi India Glass technical teams embed directly into architect specification processes for large commercial developments, compressing traditional distributor influence.
- Distributors:Regional stocking points buffer lead times for mid-size fabricators in eastern states lacking local float capacity.
- Online Retail:Standard-sized tempered panels and decorative glass reach small contractors and homeowners through building material platforms with logistics partnerships.
- Wholesalers:Volume aggregators supply fragmented downstream tempering operations in Odisha and West Bengal where fabrication scale remains limited.
Direct sales capture premium project value; distributor networks are gaining share fastest in underserved eastern markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in western India while consumption spreads across emerging construction corridors. Gujarat and Maharashtra float lines supply distant markets through logistics networks that disadvantage eastern fabricators.
Gujarat
Solar module manufacturing zones in Mundra and Sanand pull tempered solar glass volumes. BIS certification for IS 14900 structural glazing filters smaller importers from state infrastructure tenders. Hazira and Mundra ports anchor export-oriented float capacity serving Middle East markets.
Maharashtra
Mumbai high-rise construction sustains premium coated glass demand for green-building compliance. State-level energy conservation building codes enforce U-value thresholds that disqualify non-compliant imports. Pune automotive clusters anchor tempered windshield offtake from nearby float lines.
Karnataka
Bengaluru IT park expansions drive energy-performance contracting for facade retrofits. Bureau of Energy Efficiency star-rating mandates redirect procurement toward documented thermal performance. Electronic City and Whitefield commercial zones concentrate specification-intensive projects.
Tamil Nadu
Chennai automotive OEM plants require just-in-sequence glass delivery for windshield assembly. IS 2553 fragmentation standards displace annealed formulations in passenger vehicle production. Sriperumbudur manufacturing corridor anchors consistent tempered glass offtake.
Telangana
Hyderabad pharmaceutical campus construction adopts lifecycle cost models for glazing procurement. State building code amendments align with Maharashtra and Gujarat energy efficiency thresholds. Genome Valley and HITEC City developments bundle glass replacement with thermal performance guarantees.
India Flat Glass Market Competitive Environment
Top-tier vendors anchor specification relationships with large developers, while mid-scale fabricators compete on logistics reach and batch flexibility. The market structures around three tiers: integrated float-temper-coat operations, standalone float suppliers, and downstream fabrication specialists. Strategic archetypes include technical advisory integrators, solar glass specialists, and scale-driven commodity producers. Dominant competitive moves encompass captive solar capacity expansion and energy-performance service bundling.
Among India-based integrated manufacturers, Asahi India Glass and Gold Plus Float Glass exemplify scale-driven positioning across multiple state-level markets. Saint-Gobain represents the technical advisory archetype through embedded architect relationships. Borosil Renewables occupies the solar specialization tier with tempered coating capabilities. Şişecam and Guardian Industries demonstrate multinational float glass presence through Indian joint ventures and licensing arrangements.
| Leading Market Players |
|---|
| Asahi India Glass |
| Saint-Gobain |
| Gold Plus Float Glass |
| Gujarat Guardian |
| Şişecam |
| Guardian Industries |
| Nippon Sheet Glass |
| Borosil Renewables |
| FUSO |
| Others |
Value Chain & Pricing Dynamics
Float furnace technology upgrades toward oxy-fuel combustion and electric boosting are compressing energy costs for Gujarat and Maharashtra producers while widening the cost gap against eastern competitors still running conventional natural gas configurations. This dual shift concentrates pricing power with western integrated manufacturers and accelerates regional supply consolidation.
Pricing Analysis
Margin tightening in standard float glass reflects soda ash import volatility from Turkey and the United States transmitting directly into batch cost instability. Three-tier pricing structure across BEE 5-star certified, standard IS-compliant, and uncertified commodity grades separates specification-intensive projects from price-sensitive replacement markets. Cost-down pressure on eastern fabricators accelerates because pipeline infrastructure gaps force reliance on expensive LNG trucking. Large commercial developers in Bengaluru and Hyderabad demonstrate lowest price sensitivity through energy-performance contracting models.
Supply Chain Analysis
Bureau of Energy Efficiency star-rating mandates and state-level ECBC amendments are reshaping sourcing toward domestic suppliers with certified U-value documentation. Geographic supply concentration centers on Gujarat, Maharashtra, and Tamil Nadu float lines feeding fabrication clusters across peninsular India. Raw material dependencies draw from silica sand deposits in Rajasthan, imported soda ash from the United States and Turkey, and natural gas from domestic fields and LNG terminals. Single-source vulnerability sits with the Hazira-Mundra pipeline corridor supplying western furnace clusters. Distribution runs through direct technical-sales relationships for premium projects and regional distributor networks for fragmented eastern markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's flat glass market reads as supply-constrained with float furnace capacity expansion lagging solar deployment and high-rise construction timelines. Natural gas pipeline gaps in eastern states prop pricing premiums for Gujarat and Maharashtra producers.
For Market Incumbents: Hedge against soda ash import volatility through backward integration into synthetic soda ash production or long-term offtake contracts with Turkish suppliers. Anchor specification relationships with large developers through embedded technical advisory teams that compress distributor influence and defend margin position against commodity imports.
For New Entrants and Emerging Players: Enter via solar glass specialization targeting Gujarat and Rajasthan photovoltaic manufacturing zones where tempered coating capabilities face shortage against desert thermal cycling requirements. Capture underserved eastern state volume through logistics partnerships with existing float lines rather than greenfield furnace investment.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational float glass majors seeking India manufacturing footprint and technical advisory capabilities. Long-term viability favors integrated float-temper-coat operations with captive solar glass capacity. Watch BIS certification backlog resolution as inflection signal for innovative coating formulation launches.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soda Ash | Synthetic soda ash production insulates batch costs from Turkish lira volatility and shipping disruptions. |
| Solar Glass Capacity Expansion | Tempered coating lines in Gujarat capture photovoltaic module manufacturing growth under PLI incentives. |
| Energy-Performance Service Bundling | Facade retrofit contracts with guaranteed thermal savings displace spot purchasing in Bengaluru IT parks. |
| Eastern State Logistics Partnerships | Distribution alliances with existing float lines bypass pipeline infrastructure gaps in Odisha and West Bengal. |
| BIS Certification Fast-Track Investment | IS 2553 and IS 14900 testing capability accelerates specification approval for low-emissivity formulations. |
Study Parameters
Trade statistics from the Directorate General of Foreign Trade, Bureau of Energy Efficiency star-rating registration databases, and state-level ECBC amendment notifications formed the secondary backbone for volume and specification trend validation. Primary interviews with float plant operations managers, facade contractor procurement leads, and solar module manufacturing supply chain heads combined with secondary triangulation to anchor production capacity and offtake assumptions. Bottom-up project pipeline analysis across Gujarat, Maharashtra, Karnataka, Tamil Nadu, and Telangana construction corridors cross-checked against top-down macro construction forecasts.
Historical trendline analysis of flat glass consumption against cement and steel offtake established intensity ratios for forward projection. Segmentation modeling across product type, application, end user, and distribution channel dimensions generated volume splits with regional production-consumption balance adjustments. CAGRs derived from regression against construction sector growth, automotive production forecasts, and photovoltaic deployment targets with natural gas price scenario overlays.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained LNG price spikes or accelerated ECBC enforcement timelines. Forecasts reflect assumptions around PLI scheme continuity and BIS laboratory capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Recycled Glass Aggregates Market
Glass
Global Vitrification Market
Glass
Glass Tableware Market
Glass
Europe Silica Sand for Glass Making Market
Glass
3D Glass Substrate Market
Glass
Crystalware and Glassware Market
Glass
Fiberglass Window Market
Glass
Spherical Silica Market
Glass
Glass Grade Dolomite Market
Glass
Float Glass Market
Glass
Flexible Glass Market
Glass
Optical Glass Market
Glass
North America and Australia Silica Market
Glass
Glass Prepreg Market
Glass
Laboratory Glass Container Market
Glass
Global Self-Cleaning Glass Market