
 Silica Sand for Glass Making Market | 2026-2036
Silica Sand for Glass Making Market Size, Share, and Industry Trends Forecast 2026-2036
Silica Sand for Glass Making Market Outlook
Container glass buyers is collapsing as a share of total offtake, while solar glass and specialty electronics buyers capture incremental volume. U.S. Silica Holdings dominates Appalachian Basin deposits and extends its reach through captive rail logistics. Sibelco competes on beneficiation technology leadership, particularly in ultra-low iron refining. Covia Holdings anchors its position through backward integration into resin-coated proppant co-production, sharing processing infrastructure with glass-grade circuits.
Silica sand for glass making consists of processed quartz grains graded by iron content, particle size distribution, and alkali levels, with premium grades requiring below 0.01 percent Fe2O3 to prevent green tinting in finished glass. The material undergoes washing, attrition scrubbing, acid leaching, and thermal drying to meet optical clarity standards for float and container applications. Flat glass commands the largest volume share due to construction and automotive glazing requirements, though specialty glass achieves the highest per-ton pricing through stringent purity thresholds. High-purity grade is displacing standard grade in solar panel manufacturing, where iron tolerance has tightened measurably.
EPA silica dust rules under OSHA enforce permissible exposure limits that elevate capital costs for U.S. mining and processing facilities. REACH registration requirements in Europe constrain imports from non-compliant jurisdictions, reshaping supplier qualification protocols. China's GB standards and MEE environmental audits are raising compliance barriers for small-scale processors. Stakeholders must monitor regulatory divergence across these three regimes when siting new beneficiation capacity or restructuring long-term supply contracts.
Market Dynamics
Solar photovoltaic manufacturing is pulling beneficiation capacity toward ultra-low iron specifications, while construction glass demand stagnates in mature economies. This demand pivot is compressing standard-grade margins and rewarding processors with acid-leaching capabilities.
Growth Catalysts
- EU REACH crystalline silica limits:Furnace operators across Germany, Belgium, and Italy must retrofit filtration systems, creating captive demand for pre-processed low-dust feedstock from certified suppliers.
- Floating solar installations:Vietnam's new float-glass complexes are signing decade-long offtake agreements with domestic sand processors, locking in volume before capacity comes online elsewhere.
- Photovoltaic glass iron thresholds:Solar panel manufacturers now reject batches above 0.008 percent Fe2O3, forcing sand upgraders to install magnetic separation and flotation circuits.
Market Restraints
- Appalachian Basin supply concentration:Premium deposits in Pennsylvania and West Virginia are controlled by a handful of rail-integrated operators, limiting entry for new processors lacking logistics assets.
- Natural gas price volatility:Thermal drying and calcination stages consume substantial energy input, exposing margin structures to Henry Hub fluctuations.
- Substitute materials in specialty applications:Synthetic fused silica is capturing share in semiconductor crucibles and fiber optics where thermal stability requirements exceed natural sand capabilities.
Strategic Opportunities
- Vietnam beneficiation greenfield:Coastal provinces offer untapped dredging permits and proximity to glass manufacturing clusters, rewarding early movers with integrated mine-to-furnace economics.
- China MEE environmental audit compliance:Small-scale processors failing new wastewater and dust standards are exiting, consolidating market share among operators with capital to upgrade.
- Digital particle-sizing integration:Real-time laser diffusion analysis linked to automated sorting is enabling premium-grade recovery from marginal deposits previously classified as construction sand.
Industry Challenges
- Qualified metallurgist scarcity:Acid-leaching circuit optimization and impurity profiling require specialized talent that mining engineering programs have deprioritized amid energy transition narratives.
- ISO 9001 and IATF 16949 certification timelines:Automotive glass suppliers now mandate 18-month qualification periods for new sand sources, freezing out spot-market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silica Sand for Glass Making Market |
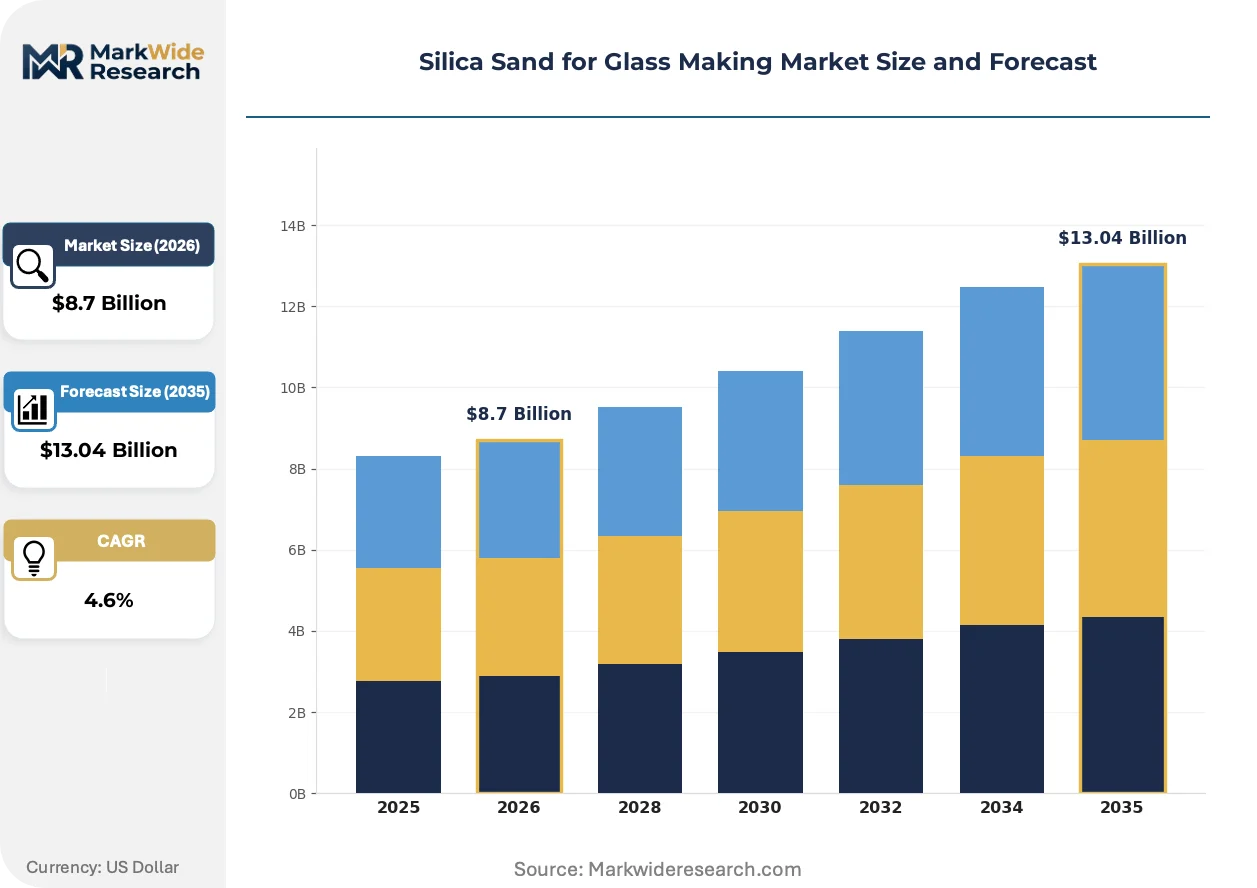
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Automotive Glass, Container Glass, Flat Glass, Specialty Glass Grade: High Purity, Low Iron, Standard Grade, Ultra Fine Form: Granular, Powdered, Crushed, Blended End User: Construction, Automotive Manufacturers, Electronics, Furniture |
| Companies Covered | U.S. Silica Holdings, Sibelco, Covia Holdings, Quarzwerke Group, Imerys, Xinyi Glass Holdings, Fairmount Santrol, Solvay, CRH plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silica Sand for Glass Making Market Strategic Shifts
Beneficiation technology is splitting the market into two distinct supply tiers, while regulatory divergence across major economies complicates cross-border sourcing strategies.
Electromagnetic high-gradient separation is bifurcating the premium segment from commodity supply. Solar glass manufacturers in Vietnam and China are installing 20-tesla superconducting magnets to achieve 0.005 percent Fe2O3 levels. This capital-intensive approach is compressing the addressable market for standard washing-and-scrubbing circuits.
REACH registration requirements are reshaping European import protocols. Non-EU processors must now submit full substance dossiers to ECHA before supplying float-glass furnaces in Germany or Italy. Container glass producers with legacy supply contracts are absorbing compliance costs rather than switching sources mid-contract.
Long-term offtake contracting is displacing spot-market purchasing for high-purity grades. Solar panel manufacturers are offering five-year prepayment structures to secure dedicated beneficiation lines. This preference shift is most visible in Vietnam, where new glass complexes have committed 70 percent of planned output through binding supply agreements.
Silica Sand for Glass Making Market Segmentation
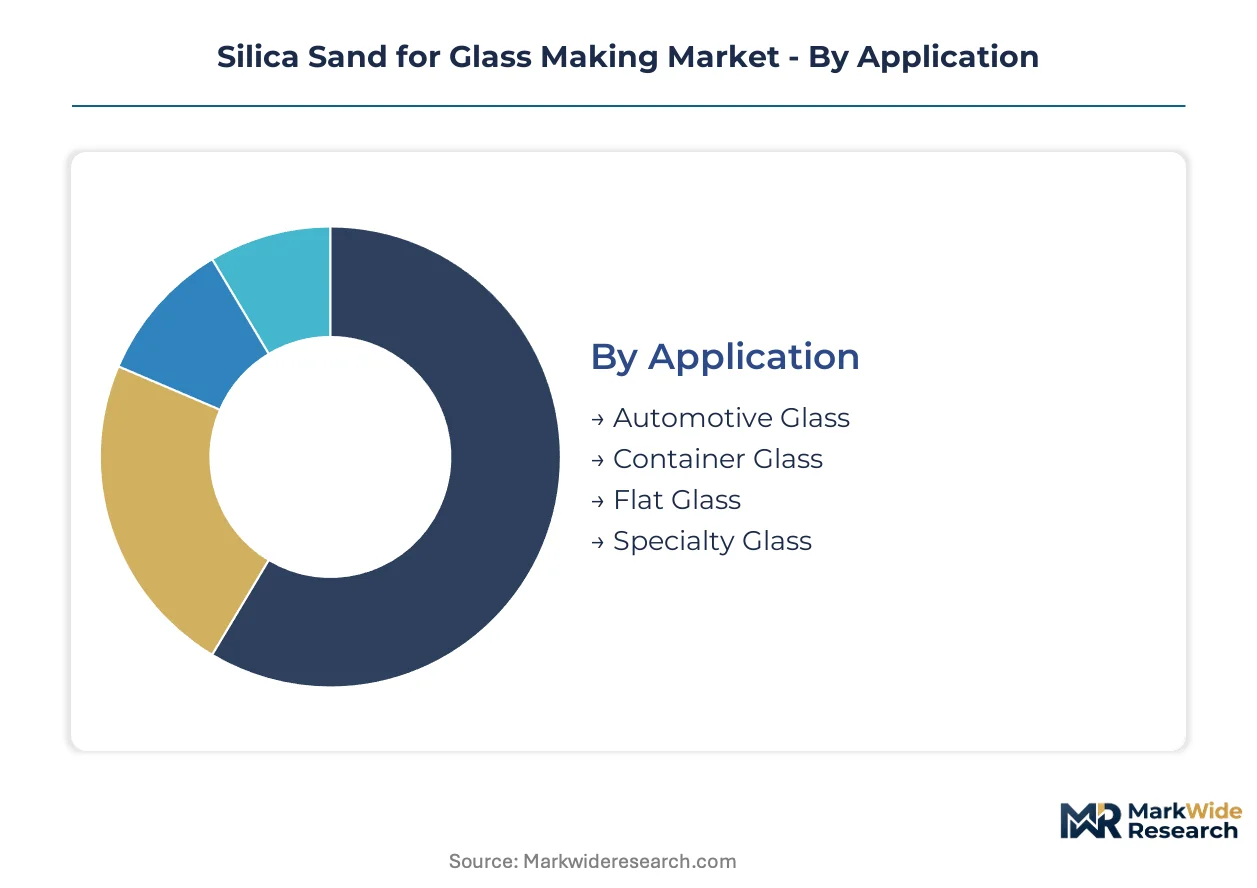
Silica sand for glass making fragments across specification tiers that command vastly different pricing power and geographic reach. Processors must align beneficiation investments with the exacting thresholds of target end-uses, as solar glass iron tolerances now diverge sharply from container glass norms.
Application:
Flat glass and container glass serve predominantly domestic construction and packaging markets, while specialty and automotive grades feed export-led electronics and vehicle assembly chains.
- Flat Glass:Float-glass furnaces consume the largest tonnage, with iron content capped at 0.03 percent Fe2O3 for architectural clarity. Demand concentrates in Vietnam's new manufacturing clusters, where domestic processors have locked in decade-long supply agreements ahead of capacity ramp.
- Specialty Glass:Optical and solar applications mandate below 0.01 percent Fe2O3, requiring acid-leaching and superconducting magnetic separation circuits. Solar panel manufacturers in China and Vietnam now reject batches above 0.008 percent, compressing the qualified supplier base.
- Container Glass:Bottles and jars tolerate higher iron levels, with beneficiation limited to washing and attrition scrubbing. Food and beverage packaging demand is stagnating in mature economies.
- Automotive Glass:Laminated and tempered windshields require tight particle size distribution for optical distortion control. OEM qualification periods now stretch to 18 months under IATF 16949 protocols.
Flat glass commands the established base. The steepest expansion runs through specialty glass.
Grade:
Cost tiers separate capital-intensive ultra-low iron circuits from standard washing operations, with premium grades achieving threefold pricing multiples over commodity supply.
- High Purity:Below 0.015 percent Fe2O3 content serves semiconductor crucibles and fiber optics where thermal stability is paramount. Synthetic fused silica is capturing share in extreme-performance applications beyond natural sand capabilities.
- Low Iron:0.015-0.03 percent Fe2O3 meets solar panel and high-end container specifications. Magnetic separation and flotation circuits are becoming mandatory as iron thresholds tighten.
- Standard Grade:Up to 0.05 percent Fe2O3 suffices for construction glass and basic containers. Margins are compressing as solar demand pulls beneficiation capacity toward premium tiers.
- Ultra Fine:Sub-75 micron particle size distribution enables thin-film glass and precision optics. Grinding energy costs and dust control requirements elevate processing expenses substantially.
Standard grade retains volume dominance. High purity is climbing the fastest as solar and electronics specifications tighten.
Form:
Volume concentration favors granular supply for furnace feed, while powdered and blended forms serve specialized coating and precision molding applications with narrower geographic distribution.
- Granular:0.1-0.6 mm grain size constitutes the primary furnace feedstock for float and container glass. Thermal drying and calcination stages consume substantial natural gas, exposing margins to Henry Hub volatility.
- Powdered:Sub-100 micron material enables glass-ceramic composites and specialty coatings. Dust exposure triggers stringent OSHA silica limits and REACH crystalline silica compliance costs.
- Crushed:Coarse fractions from quarry operations enter construction glass and lower-spec container applications. Minimal beneficiation preserves margin but limits end-use flexibility.
- Blended:Custom grain distributions match specific furnace chemistry requirements. Blending operations demand real-time laser diffusion analysis for quality assurance.
Granular forms anchor supply volumes. Powdered material is gaining share fastest in electronics and coating applications.
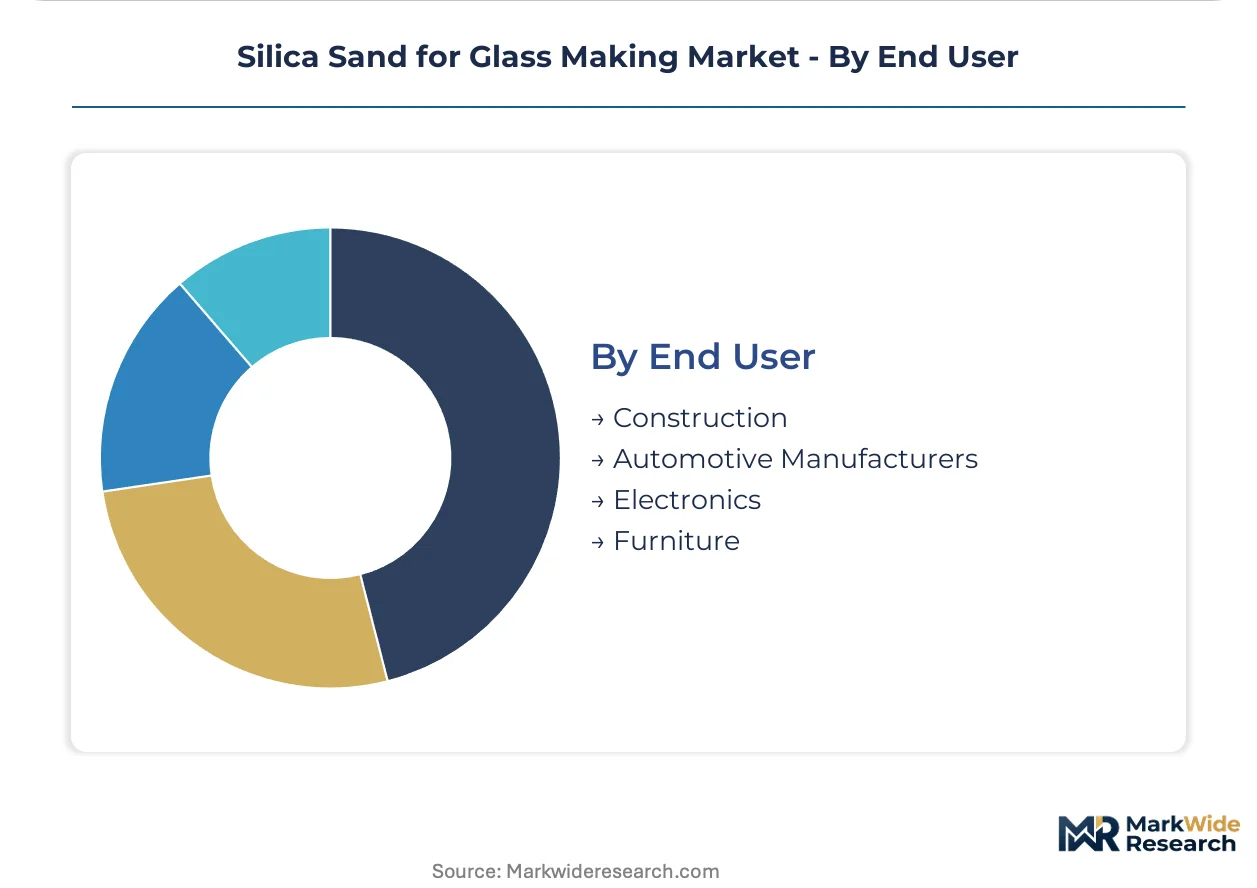
End User:
Customer concentration varies sharply, with automotive and electronics buyers demanding certified long-term contracts while construction procurement retains spot-market flexibility.
- Construction:Architectural glazing and fenestration absorb standard and low-iron grades through regional distributors. Mature economy demand is stagnating as building activity plateaus.
- Automotive Manufacturers:OEM glass suppliers mandate ISO 9001 and IATF 16949 certification with 18-month qualification timelines. This freezes out spot-market entrants and reinforces incumbent processor positions.
- Electronics:Display panel and semiconductor manufacturers drive ultra-purity specifications. Five-year prepayment structures for dedicated beneficiation lines are displacing traditional purchasing.
- Furniture:Decorative and mirrored glass applications tolerate moderate iron content. Smaller batch sizes and fragmented demand limit contract scale.
Construction maintains the volume base. Electronics is expanding most quickly as display and solar manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Float-glass manufacturers in Vietnam and solar panel producers in China now dictate procurement velocity, while European furnace operators absorb REACH compliance costs to maintain qualified supply relationships.
Vietnam
New float-glass complexes in coastal provinces are signing decade-long offtake agreements with domestic sand processors ahead of capacity ramp. The Ministry of Natural Resources and Environment is tightening dredging permits to control coastal erosion. Manufacturing clusters near Haiphong and Quang Ninh are locking in 70 percent of planned output through binding supply contracts.
China
Solar panel manufacturers now reject silica sand batches exceeding 0.008 percent Fe2O3, pulling beneficiation capacity toward ultra-low iron specifications. The Ministry of Ecology and Environment environmental audits are forcing small-scale processors to exit, consolidating market share among capital-rich operators. Yangtze River Delta glass corridors are retrofitting magnetic separation and flotation circuits to meet tightened thresholds.
United States
OSHA silica dust rules enforce permissible exposure limits that elevate capital costs for Appalachian Basin mining and processing facilities. Premium deposits in Pennsylvania and West Virginia remain controlled by rail-integrated operators, limiting entry for new processors lacking logistics assets. Henry Hub natural gas volatility directly compresses margins for thermal drying and calcination stages.
Germany
Float-glass furnaces across Belgium, Italy, and Germany must retrofit filtration systems under EU REACH crystalline silica limits, creating captive demand for pre-processed low-dust feedstock. ECHA registration requirements constrain imports from non-compliant jurisdictions, reshaping supplier qualification protocols. Industrial clusters in North Rhine-Westphalia are absorbing compliance costs rather than switching sources mid-contract.
India
Container glass demand for food and beverage packaging is stagnating as building activity plateaus in mature urban centers. The Bureau of Indian Standards is developing stricter silica purity benchmarks for specialty glass applications. Glass manufacturing corridors in Gujarat and Maharashtra are evaluating acid-leaching investments to serve electronics export chains.
Silica Sand for Glass Making Market Competitive Environment
Player mix skews toward integrated miners with captive rail logistics and specialized beneficiation technology providers. Tier-one positions concentrate among operators controlling premium Appalachian Basin deposits or proprietary ultra-low iron refining circuits. Two strategic archetypes dominate: rail-integrated basin operators and acid-leaching technology specialists. Competitive moves center on long-term offtake contracting and backward integration into resin-coated proppant co-production.
Among rail-integrated operators, U.S. Silica Holdings exemplifies the basin-control archetype through Appalachian deposit dominance. Sibelco and Covia Holdings occupy positions within the technology-specialist and co-production tiers respectively, representing alternative paths to margin defense. These three companies anchor the competitive structure without exhausting strategic variation in the supplier base.
| Leading Market Players |
|---|
| U.S. Silica Holdings |
| Sibelco |
| Covia Holdings |
| Quarzwerke Group |
| Imerys |
| Xinyi Glass Holdings |
| Fairmount Santrol |
| Solvay |
| CRH plc |
| Others |
Value Chain & Pricing Dynamics
Synthetic fused silica substitution in semiconductor crucibles and fiber optics is simultaneously pulling premium-grade pricing upward while compressing the addressable market for natural sand beneficiators, reshaping supply geography toward Vietnam's coastal dredging permits and China's Yangtze River Delta corridors where acid-leaching capacity concentrates.
Pricing Analysis
Cost-plus contracts indexed to Henry Hub natural gas dominate thermal drying and calcination stages, with premium grades achieving threefold multiples over standard supply through ISO 9001 and IATF 16949 certification tiers. Price differentiation hinges on Fe2O3 thresholds and magnetic separation circuit investment. Pricing pressure intensifies in standard-grade tiers as solar demand pulls capacity toward ultra-low iron specifications. Container glass buyers exhibit highest price sensitivity; electronics and automotive OEMs accept premium positioning for qualified supply security.
Supply Chain Analysis
Strategic stockpiling prevails among float-glass furnaces in Vietnam and Germany, while solar panel manufacturers run just-in-time programs with five-year prepayment structures. Supply concentrates in Vietnam, China, and the United States, with Appalachian Basin rail-integrated operators controlling premium deposit access. Processing draws from hydrochloric acid, natural gas, and superconducting magnet systems. Single-source vulnerability runs through qualified acid-leaching circuit operators. Distribution runs through long-term offtake agreements displacing spot-market purchasing for high-purity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for beneficiation circuit optimization and impurity profiling are expanding faster than raw sand offtake, creating recurring-revenue layers that outperform commodity trading margins.
For Market Incumbents: Consolidate through backward integration into resin-coated proppant co-production, sharing processing infrastructure with glass-grade circuits to defend margin position against synthetic fused silica substitution. Acquire acid-leaching technology specialists to lock in qualified metallurgist talent pools. Prioritize Vietnam beneficiation greenfield positions before dredging permit tightening accelerates. For New Entrants and Emerging Players: Differentiate on digital particle-sizing integration, deploying real-time laser diffusion analysis to recover premium grades from marginal deposits previously classified as construction sand. Target Vietnam's coastal provinces where decade-long offtake windows remain partially uncommitted. Pursue electronics sector entry through five-year prepayment structures for dedicated beneficiation lines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with rail-integrated basin operators in the Appalachian region holding captive logistics but aging beneficiation technology. Five-to-ten-year viability favors processors with acid-leaching capabilities and Vietnam coastal access. Watch for MEE environmental audit failures in China forcing small-scale processor exits as consolidation inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin-Coated Proppant Co-Production | Covia Holdings exemplifies margin defense through shared Appalachian Basin processing infrastructure. |
| Acid-Leaching Circuit Investment | Solar panel manufacturers now reject batches above 0.008 percent Fe2O3, mandating magnetic separation and flotation upgrades. |
| Long-Term Offtake Agreement | Vietnam's new float-glass complexes have locked in 70 percent of planned output through binding supply contracts. |
| Digital Particle-Sizing Integration | Real-time laser diffusion analysis enables premium-grade recovery from deposits previously classified as construction sand. |
| Vietnam Beneficiation Greenfield | Coastal provinces offer untapped dredging permits and proximity to glass manufacturing clusters for integrated mine-to-furnace economics. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with beneficiation plant managers, solar glass procurement leads, and ECHA regulatory affairs specialists; and secondary validation through customs trade data, SEC 10-K filings, and MEE environmental audit disclosures. Bottom-up volume modeling triangulated against top-down industry association estimates from glass manufacturing corridors in Vietnam, China, and Germany.
Across the projection horizon, the analytical framework segmented volume and value outputs by grade tier, end-use application, form factor, and regional production hub. CAGRs derived from regression analysis of historical offtake patterns against solar capacity installation forecasts and automotive glass content trajectories. Key inputs included Fe2O3 threshold tightening timelines and natural gas price volatility scenarios.
The analysis sits within stated boundaries; outcomes outside sustained solar manufacturing expansion or REACH compliance cost absorption by European furnace operators would require recalibration. Forecasts reflect assumptions regarding qualified metallurgist availability and dredging permit issuance velocity. Revision becomes warranted when synthetic fused silica cost curves cross natural sand beneficiation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Global Flat Glass Market
Glass
Europe Glass Insulators Market
Glass
Global Ultra-Thin Glass Market
Glass
Tinted Glass Market
Glass
Global Vacuum Insulated Glass Market
Glass
Double Glazing Glass Market
Glass
Glass Balustrade Lamination Market
Glass
Glass Lens Market
Glass
Asia-Pacific Fiberglass Window Market
Glass
Recycled Glass Market
Glass
Global Glass Tempering System Market
Glass
Mirrored Glass Market
Glass
Spherical Silica Market
Glass
Solar PV Glass Market
Glass
Coated Solar Control Glass Market
Glass
Tempered Glass Market