
 Specialty Silica Market | 2026-2036
Specialty Silica Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Silica Market Intelligence
Green tire manufacturers is rotating demand away from conventional carbon black reinforcement toward high-performance silica blends. Evonik Industries AG leverages its fumed silica technology leadership to supply premium grades for fuel-efficient tire compounds. Cabot Corporation anchors its position through backward integration into silicon metal sourcing. Wacker Chemie AG differentiates via specialized hydrophobic grades for high-voltage cable applications.
Specialty silica encompasses synthetic amorphous silicon dioxide produced through thermal or wet chemical processes, with specific surface areas ranging from 50 to 400 m²/g depending on the manufacturing route and intended function. Precipitated silica dominates volume for rubber reinforcement, while colloidal silica commands premium pricing in semiconductor polishing and catalyst support applications where particle size distribution below 100 nanometers is critical. Fumed silica leads margin pools in coatings and adhesives due to its rheology control properties, whereas silica gel remains a mature, cost-sensitive segment concentrated in desiccant and chromatography end uses.
EPA oversight under the Toxic Substances Control Act shapes product registration timelines for U.S. manufacturers, while REACH compliance in Europe mandates extensive substance dossiers for imported silica grades. FDA food contact regulations and USP pharmaceutical monographs establish purity thresholds that filter out lower-grade suppliers from premium segments. Stakeholders must monitor evolving PFAS restrictions, as fluorosilane surface treatments face substitution pressure that could redirect R&D spending toward bio-based hydrophobization chemistries.
Market Dynamics
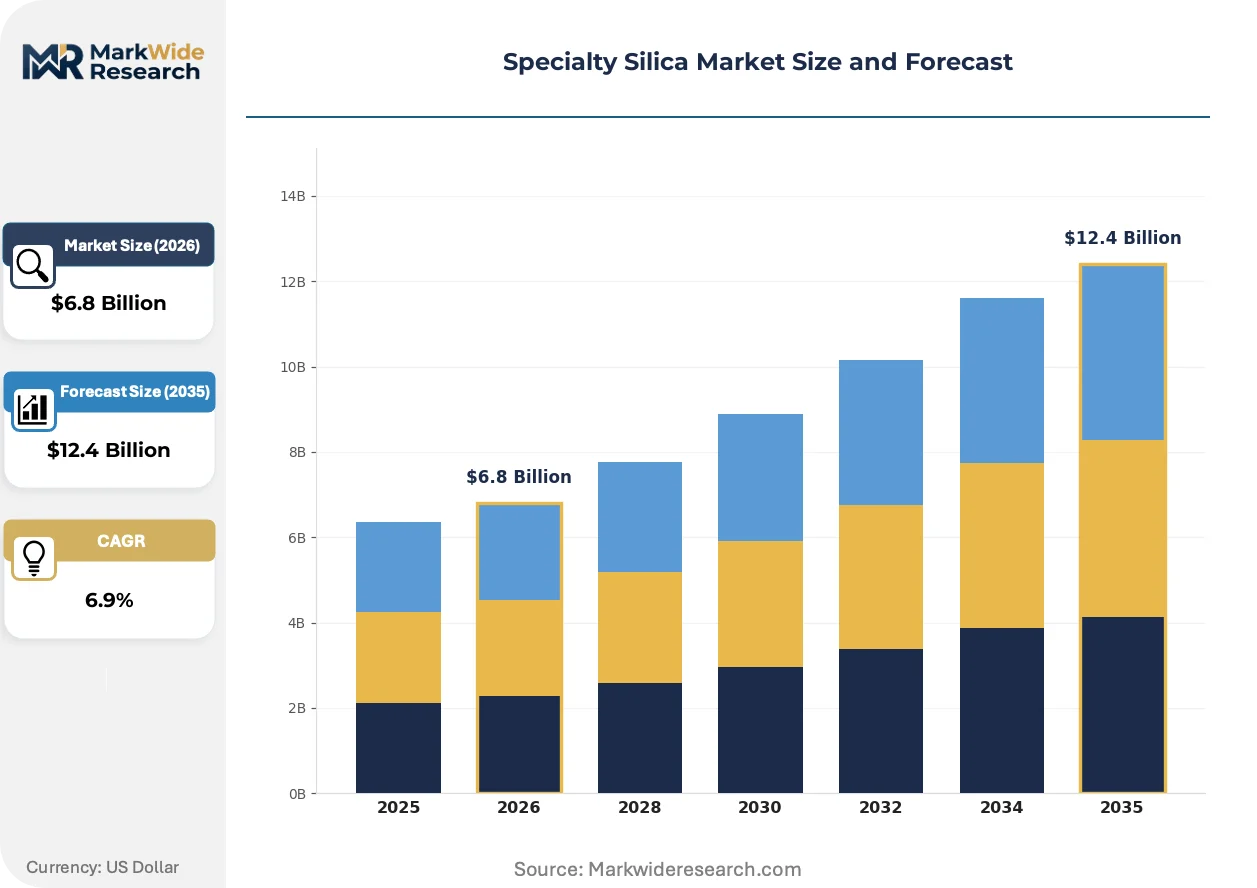
Tire compounders are forcing a feedstock pivot from carbon black to precipitated silica, driven by EU tire-labeling mandates for rolling-resistance performance. This demand rotation concentrates purchasing power among three automotive OEMs, reshaping supplier negotiation leverage across the value chain.
Growth Catalysts
- EU tire-labeling regulation:Minimum efficiency grades for passenger-car tires mandate silica loading above 15% in tread compounds, pulling compounders toward high-dispersion grades.
- Semiconductor polishing:Sub-50 nanometer colloidal silica slurries enable advanced node planarization, with foundries in Taiwan and South Korea expanding captive consumption.
- China:Domestic coatings production exceeding 30 million metric tons annually consumes precipitated silica for matting-agent applications, reducing import dependency.
Market Restraints
- Sodium silicate cost volatility:Energy-intensive fusion furnaces for sodium silicate precursor production expose margin structures to natural-gas price spikes in Germany and the Netherlands.
- Supply concentration:Fumed silica reactor capacity clusters along the US Gulf Coast and Antwerp-Rotterdam hub, creating hurricane and port-strike exposure.
- Technical substitution:Carbon-silica dual-phase fillers from select carbon-black producers threaten to reclaim share in economy-tier tire segments.
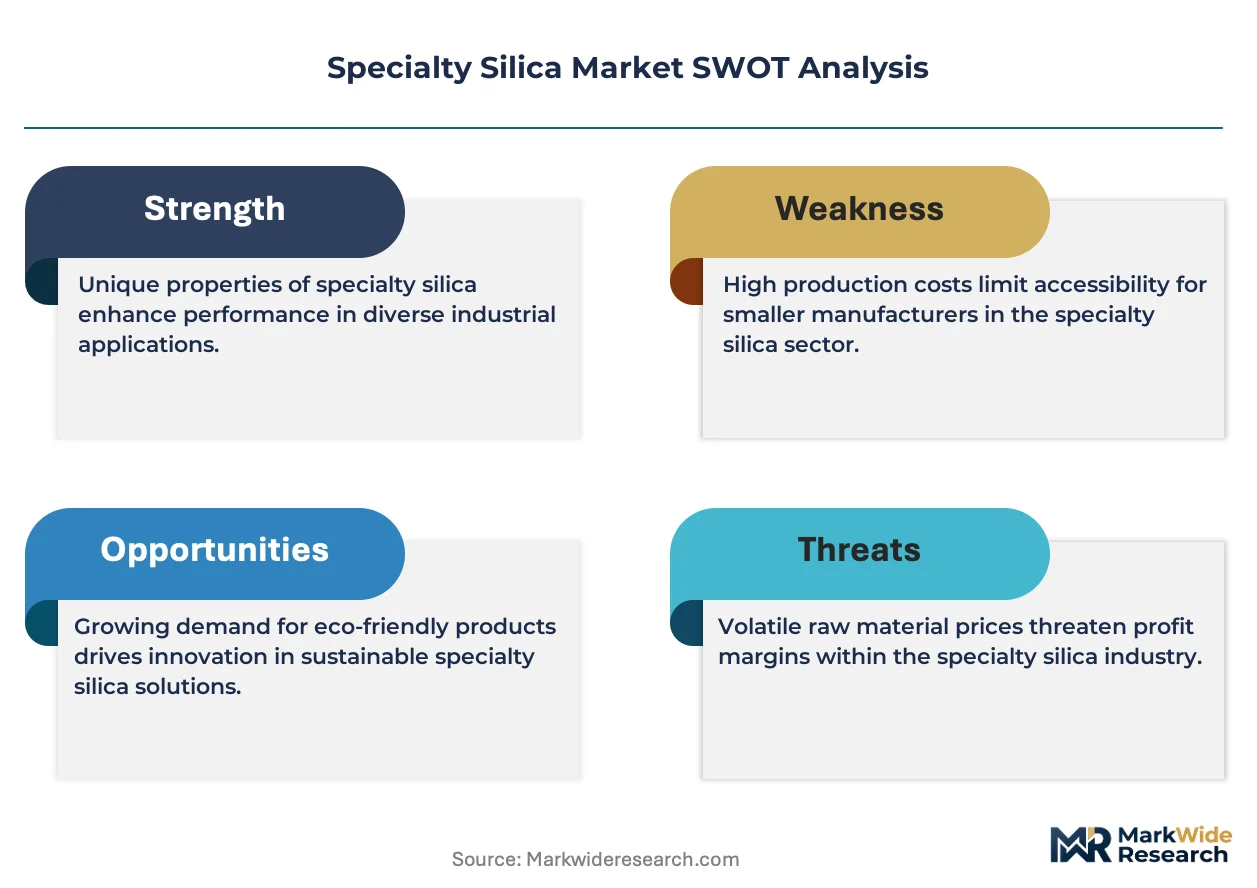
Strategic Opportunities
- India:PLI scheme incentives for domestic tire manufacturing create greenfield demand for rubber-grade precipitated silica, currently served by imports.
- Bio-based hydrophobization:Alkylsilane surface treatments derived from plant-based feedstocks circumvent pending PFAS restrictions in the EU F-Gas Regulation.
- Direct-to-compounder e-procurement:Digital platforms bypass traditional distributor markups for standardized rubber-grade volumes, capturing mid-tier compounders.
Industry Challenges
- REACH dossier compilation:Substance data requirements for nanoforms demand toxicology expenditure exceeding €2 million per legal entity, filtering SME importers from the EU market.
- Reactor turnaround coordination:Fumed silica production requires 45-day maintenance cycles that must synchronize with automotive compounder just-in-sequence delivery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Silica Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.4 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fumed Silica, Precipitated Silica, Colloidal Silica, Silica Gel Application: Rubber, Plastics, Coatings, Adhesives End User: Automotive, Pharmaceuticals, Electronics, Food & Beverage Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Solvay, Imerys, Evonik Industries AG, Tata Chemicals, PPG Industries, Cabot Corporation, 3M, Clariant, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Silica Market Strategic Shifts & Innovations
Silica manufacturing routes are diverging into performance-optimized versus cost-optimized process designs. This technical schism reflects end-use polarization between specification-critical applications and commodity replacement markets.
Surface functionalization chemistry is bifurcating between fluorosilane hydrophobic grades for high-voltage cables and silanol-rich hydrophilic grades for aqueous coatings. Automotive wire-harness manufacturers specify the former for electric-vehicle platform voltage ratings above 800V, while architectural coatings formulators specify the latter for waterborne acrylic systems. The technical split is compressing intermediate-grade margins and forcing reactor investments into dedicated product lines rather than swing capacity.
REACH nanoform registration requirements entered full enforcement in 2022, mandating specific surface-area and aspect-ratio characterization for synthetic amorphous silica. European importers now face extended customs holds for undocumented nanoform classifications, diverting spot-volume flows toward Middle Eastern and Southeast Asian ports with less stringent declaration protocols. Food-contact and pharmaceutical-grade suppliers absorb the compliance burden through dedicated regulatory-affairs teams, while industrial-grade traders exit the EU market.
Compounders in Germany and Japan now specify lot-specific surface-area certificates with 95% confidence intervals rather than nominal manufacturer datasheets. This documentation shift forces precipitated silica producers to invest in automated BET analyzers at packaging lines, replacing quarterly laboratory sampling. The practice spreads through tier-one automotive supply chains first, with second-tier compounders in Eastern Europe and Mexico following under OEM audit pressure.
Specialty Silica Market Segmentation
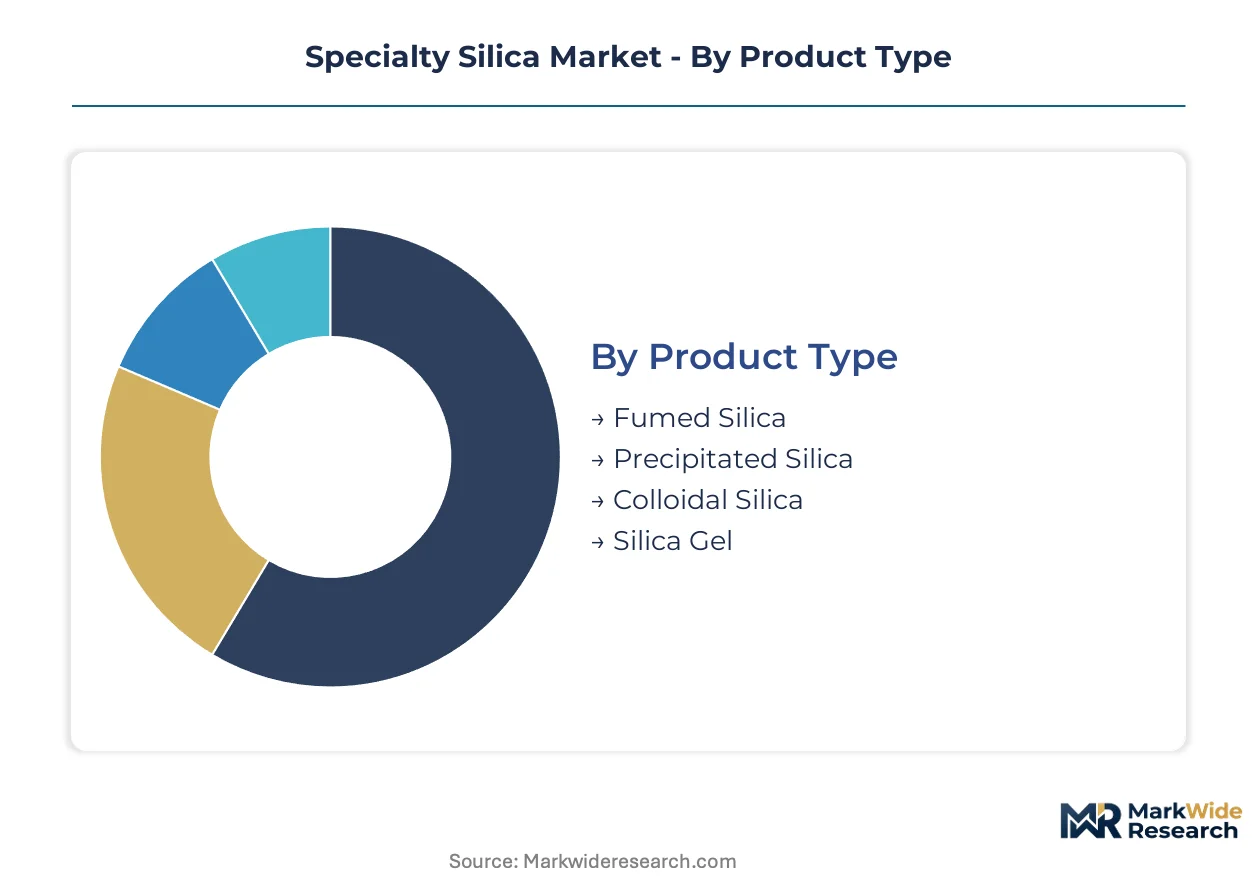
Specialty silica producers must navigate divergent purity mandates across pharmaceutical, automotive, and electronics verticals. Each end-use imposes distinct surface-area specifications and regulatory dossier requirements that fragment manufacturing strategies.
Product Type:
REACH nanoform registration and FDA food-contact monographs create tiered compliance burdens that separate premium-grade producers from commodity suppliers.
- Fumed Silica:Produced via flame hydrolysis of silicon tetrachloride, yielding specific surface areas of 200-400 m²/g with chain-like aggregate structures. Automotive wire-harness manufacturers in Germany and Japan specify hydrophobic grades for electric-vehicle platforms exceeding 800V, pulling capacity toward silane-treated variants.
- Precipitated Silica:Wet chemical precipitation from sodium silicate solutions generates controlled porosity for rubber reinforcement. Tire compounders in China and India consume volume for low-rolling-resistance tread formulations under EU labeling mandates.
- Colloidal Silica:Stabilized aqueous dispersions with particle sizes below 100 nanometers serve semiconductor planarization.
- Silica Gel:Microporous desiccant grades dominate humidity control and chromatography applications.
Established volume favors precipitated silica; emerging adoption favors colloidal silica.
Application:
Cost stratification across specification tiers determines margin capture, with pharmaceutical and semiconductor applications commanding 3-5x rubber-grade pricing.
- Rubber:Tire tread compounds represent the dominant volume sink, with EU tire-labeling regulations mandating silica loadings above 15% for passenger-car efficiency grades. Compounders in Germany, Japan, and South Korea enforce lot-specific surface-area certificates with 95% confidence intervals, forcing packaging-line BET analyzer investments.
- Coatings:Architectural formulators specify hydrophilic grades for waterborne acrylic systems, while industrial coatings demand rheology control in high-solids formulations. China's domestic coatings output exceeding 30 million metric tons annually reduces import dependency for matting-agent applications.
- Plastics:Anti-blocking and reinforcement functions in polyethylene films and engineering polymers.
- Adhesives:Thixotropic control in construction and electronics assembly formulations.
Rubber applications anchor volume scale; coatings applications capture margin expansion.
End User:
Customer concentration among three automotive OEMs reshapes supplier negotiation leverage across tire and wire-harness supply chains.
- Automotive:Tire manufacturers and electric-vehicle wire-harness producers drive differentiated demand—fuel-efficiency compounds versus high-voltage insulation. OEM audit pressure propagates documentation standards from tier-one German compounders to second-tier suppliers in Eastern Europe and Mexico.
- Electronics:Foundries in Taiwan and South Korea expand captive consumption of sub-50 nanometer colloidal silica for advanced node planarization.
- Pharmaceuticals:USP monograph compliance and EMA drug master file requirements filter lower-grade suppliers from excipient and API processing applications.
- Food & Beverage:FDA food-contact regulations and anti-caking agent approvals constrain sourcing to dossier-complete producers.
Automotive end users concentrate purchasing power; electronics end users expand most quickly.
Distribution Channel:
Channel selection correlates with grade standardization and customer scale, with direct relationships dominating specification-critical volumes.
- Direct Sales:Automotive OEMs and semiconductor foundries procure through long-term contracts with embedded quality protocols and just-in-sequence delivery windows. Fumed silica's 45-day reactor turnaround cycles must synchronize with these arrangements.
- Distributors:Regional inventory holders serve fragmented coatings and adhesives formulators with standardized rubber-grade and industrial-grade volumes.
- Online Retail:Laboratory-scale and research quantities bypass traditional procurement for colloidal silica and chromatography grades.
- Wholesalers:Bulk silica gel and desiccant volumes move through cost-optimized channels for packaging and logistics applications.
Direct sales secure premium-tier relationships; distributor networks retain mid-market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders export high-dispersion precipitated silica grades to tire manufacturers across Eastern Europe and Turkey, while Chinese domestic production absorbs matting-agent demand previously served by imports.
China
Domestic coatings production exceeding 30 million metric tons annually consumes precipitated silica for matting-agent applications, reducing import dependency. SAMR enforces GB standards for food-contact silica purity. The Yangtze River Delta hosts reactor clusters supplying rubber-grade volumes to domestic tire manufacturers.
Germany
Automotive wire-harness manufacturers specify hydrophobic fumed silica grades for electric-vehicle platforms exceeding 800V. ECHA REACH nanoform registration mandates specific surface-area characterization. The Cologne-Leverkusen chemical corridor concentrates fumed silica reactor capacity serving EU compounders.
United States
Semiconductor foundries in Arizona and Texas expand captive consumption of sub-50 nanometer colloidal silica for advanced node planarization. EPA oversight under the Toxic Substances Control Act shapes product registration timelines. The US Gulf Coast clusters fumed silica production exposed to hurricane disruption.
India
PLI scheme incentives for domestic tire manufacturing create greenfield demand for rubber-grade precipitated silica currently served by imports. BIS certification requirements filter lower-grade suppliers from premium segments. Gujarat and Maharashtra host emerging compounding facilities sourcing local silica.
South Korea
Foundries in Gyeonggi Province consume colloidal silica slurries for semiconductor planarization at advanced process nodes. MFDS pharmaceutical monographs establish purity thresholds for excipient applications. The Seoul Capital Area concentrates electronics-grade silica demand from memory and logic chip producers.
Specialty Silica Market Key Industry Players
Player mix skews toward integrated chemical conglomerates with backward integration into silicon metal sourcing. The structure concentrates around three strategic tiers: multinational diversified materials groups, regional sodium silicate-integrated producers, and specialized fumed silica technology holders. Capacity expansion and portfolio diversification toward pharmaceutical and electronics grades represent the dominant competitive moves.
Among German chemical conglomerates, Evonik Industries AG and Wacker Chemie AG exemplify technology-led positioning in high-margin hydrophobic grades. Cabot Corporation represents North American integrated supply chain control. These three occupy distinct archetype positions: premium-grade technology leadership, diversified materials scale, and regional supply security.
| Leading Market Players |
|---|
| Solvay |
| Imerys |
| Evonik Industries AG |
| Tata Chemicals |
| PPG Industries |
| Cabot Corporation |
| 3M |
| Clariant |
| Wacker Chemie AG |
| Others |
Cost & Logistics Intelligence
REACH nanoform registration requirements in Europe gate both supplier qualification timelines and price differentiation between dossier-complete and industrial-grade silica. This regulatory filter compresses margins for commodity traders while amplifying premium capture for pharmaceutical and semiconductor-grade producers with dedicated compliance infrastructure.
Pricing Analysis
Next-generation hydrophobic fumed silica for 800V electric-vehicle platforms commands substantial premiums over current-generation rubber-grade precipitated silica and prior-generation desiccant silica gel. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and surface-area precision, with FDA food-contact and USP pharmaceutical tiers at the apex. Price erosion runs through industrial-grade precipitated silica as Chinese domestic production scales. Tire compounders exhibit highest price sensitivity; semiconductor foundries show lowest.
Supply Chain Analysis
China and Germany anchor precipitated silica and hydrophobic fumed silica production respectively, with the US Gulf Coast clustering fumed silica reactor capacity. Sodium silicate precursor production draws from energy-intensive fusion furnaces in Germany and the Netherlands, while silicon tetrachloride feedstock rests on chlor-alkali co-location. Single-source vulnerability concentrates around Antwerp-Rotterdam port handling for European imports. Distribution runs through direct long-term contracts for automotive and electronics grades, with regional distributors serving fragmented coatings formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among three automotive OEMs and captive semiconductor foundries, fragmenting supplier negotiation leverage across tier-one and tier-two compounders.
For Market Incumbents: Fortify backward integration into silicon metal sourcing to defend against carbon-silica dual-phase filler substitution threats in economy-tier tire segments. Lock in 45-day reactor turnaround synchronization with automotive just-in-sequence delivery windows through dedicated logistics contracts. Prioritize ECHA REACH nanoform dossier maintenance as a compliance moat filtering SME competitors. For New Entrants and Emerging Players: BIS certification fast-tracks for India's PLI-subsidized tire manufacturing greenfield sites offer the most penetrable entry vector. Target rubber-grade precipitated silica supply gaps in Gujarat and Maharashtra compounding clusters. Deploy direct-to-compounder e-procurement platforms to bypass established distributor markups for standardized volumes. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sub-50 nanometer colloidal silica capacity for semiconductor planarization. Five-to-ten-year viability favors producers with captive sodium silicate integration and pharmaceutical-grade certification infrastructure. Monitor PFAS restriction implementation timelines as inflection signals for bio-based hydrophobization chemistry substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Metal | Cabot Corporation's upstream control secures feedstock cost stability against sodium silicate volatility. |
| REACH Nanoform Dossier Investment | Evonik Industries AG's regulatory infrastructure filters SME importers from EU pharmaceutical-grade segments. |
| Direct E-Procurement Platform Launch | Digital bypass of distributor markups captures mid-tier tire compounders in Eastern Europe and Mexico. |
| Bio-Based Hydrophobization R&D | Alkylsilane surface treatments from plant feedstocks circumvent pending EU F-Gas Regulation restrictions. |
| India Greenfield Capacity Expansion | Domestic precipitated silica production aligns with PLI scheme tire manufacturing incentives in Gujarat. |
Research Approach
Operator-level perspectives from plant managers at sodium silicate fusion facilities, procurement leads at tire compounders, technical R&D directors at coatings formulators, and regulatory affairs specialists anchored the qualitative base. Secondary validation drew from ECHA substance dossier databases, US EPA TSCA registration filings, customs trade flow records, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up volume modeling triangulated against top-down end-use consumption estimates across rubber, coatings, and electronics verticals.
Sensitivity analysis tested forecast outputs against natural-gas price volatility scenarios and PFAS regulatory acceleration timelines across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry, surface-area specification grade, and regional production hub. CAGRs derived from regression-weighted historical growth patterns and elasticity-adjusted demand drivers. Semiconductor node advancement cadence and EU tire-labeling enforcement stringency served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained EU regulatory enforcement and China domestic production growth assumptions; material deviation would warrant model refresh. Forecasts reflect base-case assumptions around REACH compliance cost absorption and sodium silicate energy input stability. Recalibration cycles align with material shifts in automotive electrification voltage platform specifications and foundry planarization node transitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
Conductive Plastics Market
Specialty Materials
Global Synthetic Zeolite Market
Specialty Materials
Europe Acrylic Sheet Market
Specialty Materials
Light Diffusion Materials Market
Specialty Materials
Super Engineering Plastics Market
Specialty Materials
Global Supplementary Cementitious Materials Market
Specialty Materials
Global Flexible Substrates Market
Specialty Materials
Edge Banding Materials Market
Specialty Materials
Hornbeam Market
Specialty Materials
Latin America International CEP Market
Specialty Materials
Water Soluble Film Market
Specialty Materials
Cellulose Gel Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Nitrocellulose Market