
 Fumed Silica Market | 2026-2036
Fumed Silica Market Size, Share, and Industry Trends Forecast 2026-2036
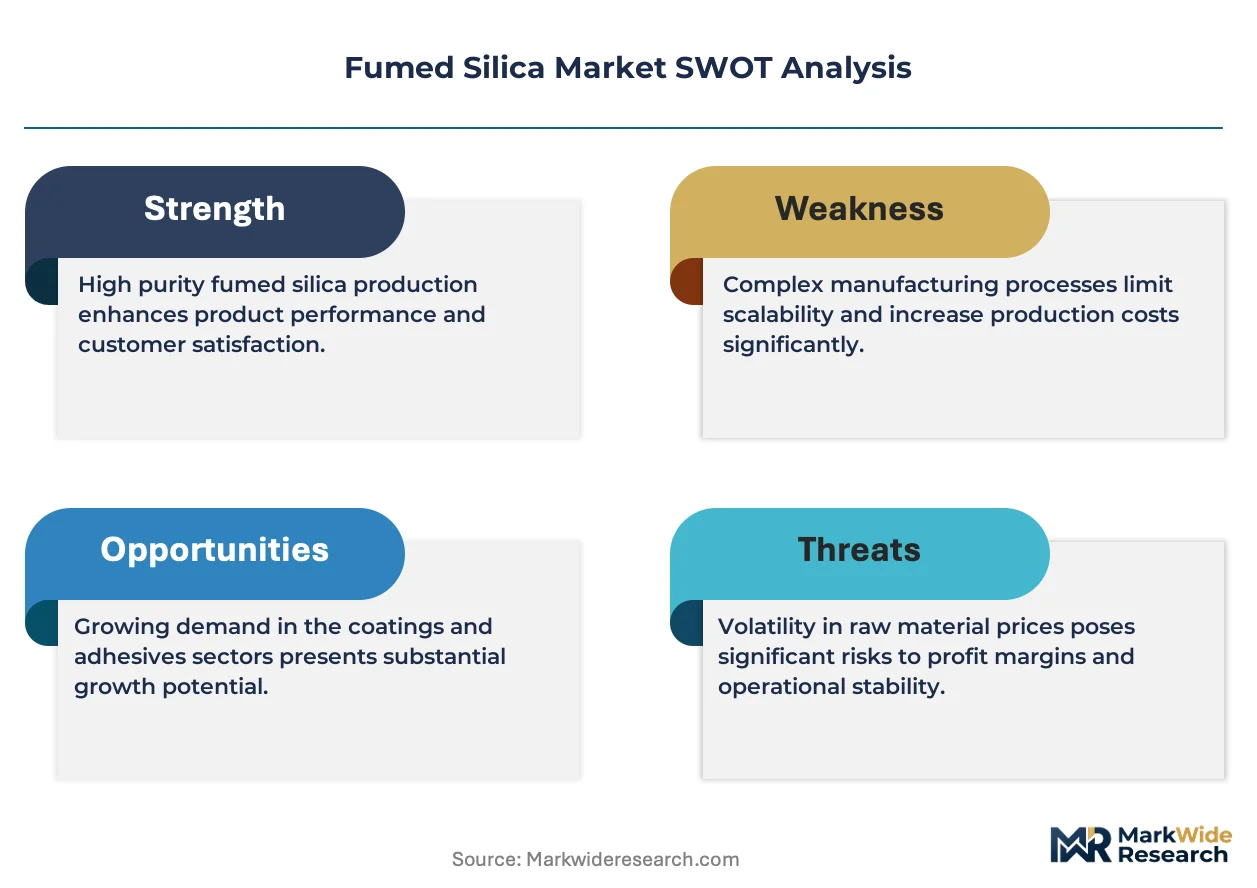
Fumed Silica Market Analysis
The EU Green Deal is recalibrating fumed silica procurement across European coatings value chains. Evonik Industries AG leverages its integrated precursor supply to sustain premium hydrophobic output. Cabot Corporation anchors North American supply through dedicated aerosol reactor capacity. Dongyue Group competes on scale from its Shandong manufacturing base.
Fumed silica consists of nanoscale amorphous silicon dioxide particles produced through flame hydrolysis of silicon tetrachloride, yielding specific surface areas between 50 and 400 square meters per gram for rheology control and reinforcement. Hydrophobic grades carry wider margin pools due to complex post-treatment chemistry and pharmaceutical-grade certification requirements. The adhesives and sealants application cluster absorbs volume from automotive lightweighting programs. Direct sales channels dominate bulk pharmaceutical and electronics contracts where lot traceability and technical service integration determine supplier selection.
REACH registration obligations through ECHA govern import thresholds and substance characterization across European value chains. FDA oversight of excipient-grade fumed silica in the United States enforces ICH Q3D elemental impurity limits for pharmaceutical use. China's GB standards and MEE environmental compliance protocols shape export eligibility from domestic producers. Buyers must weigh regulatory divergence against regional manufacturing density when qualifying second-source suppliers.
Market Dynamics
REACH compliance tightening impurity thresholds for silicone elastomers is forcing German manufacturers to accelerate qualification of premium hydrophobic grades, compressing supplier selection timelines and reallocating procurement budgets toward certified producers.
Growth Catalysts
- Automotive Lightweighting:Adhesives and sealants specifications in electric vehicle battery enclosures require rheology-controlled fumed silica for thermal management and structural bonding.
- EU Green Deal:Coatings value chains across Germany, France, and the Netherlands face procurement recalibration toward low-carbon precursor routes and verified supply chain emissions.
- Flame Hydrolysis Scale-Up:Dedicated aerosol reactor investments in the United States and China expand nameplate capacity for pharmaceutical-grade surface areas between 200 and 400 square meters per gram.
Market Restraints
- Silicon Tetrachloride Volatility:Precursor cost swings tied to polysilicon manufacturing cycles compress margin predictability for non-integrated producers.
- Shandong Supply Concentration:Chinese export eligibility hinges on MEE environmental compliance protocols, creating single-point vulnerability for hydrophilic grade availability.
- Organic Substitute Threat:Precipitated calcium carbonate and modified clay extenders compete in sealant formulations where extreme thermal stability is not specified.
Strategic Opportunities
- India Pharmaceutical Excipients:CDSCO alignment with ICH Q3D standards creates first-mover advantage for impurity-certified suppliers targeting generic drug manufacturing clusters in Hyderabad and Ahmedabad.
- Electronics Direct Sales:Lot traceability requirements in semiconductor packaging adhesives favor technical service-integrated contracts over distributor intermediation.
- Dual Carbon Convergence:China's carbon intensity targets and the EU Carbon Border Adjustment Mechanism jointly reward producers with integrated renewable energy and carbon capture at precursor synthesis.
Industry Challenges
- Post-Treatment Chemistry Talent:Hydrophobic surface functionalization requires specialized expertise in organosilane chemistry that competes with broader silicone materials hiring pools.
- Pharmaceutical Certification Timelines:FDA excipient-grade validation and ECHA dossier updates demand 18-to-24-month qualification cycles that lock working capital in pre-revenue inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fumed Silica Market |
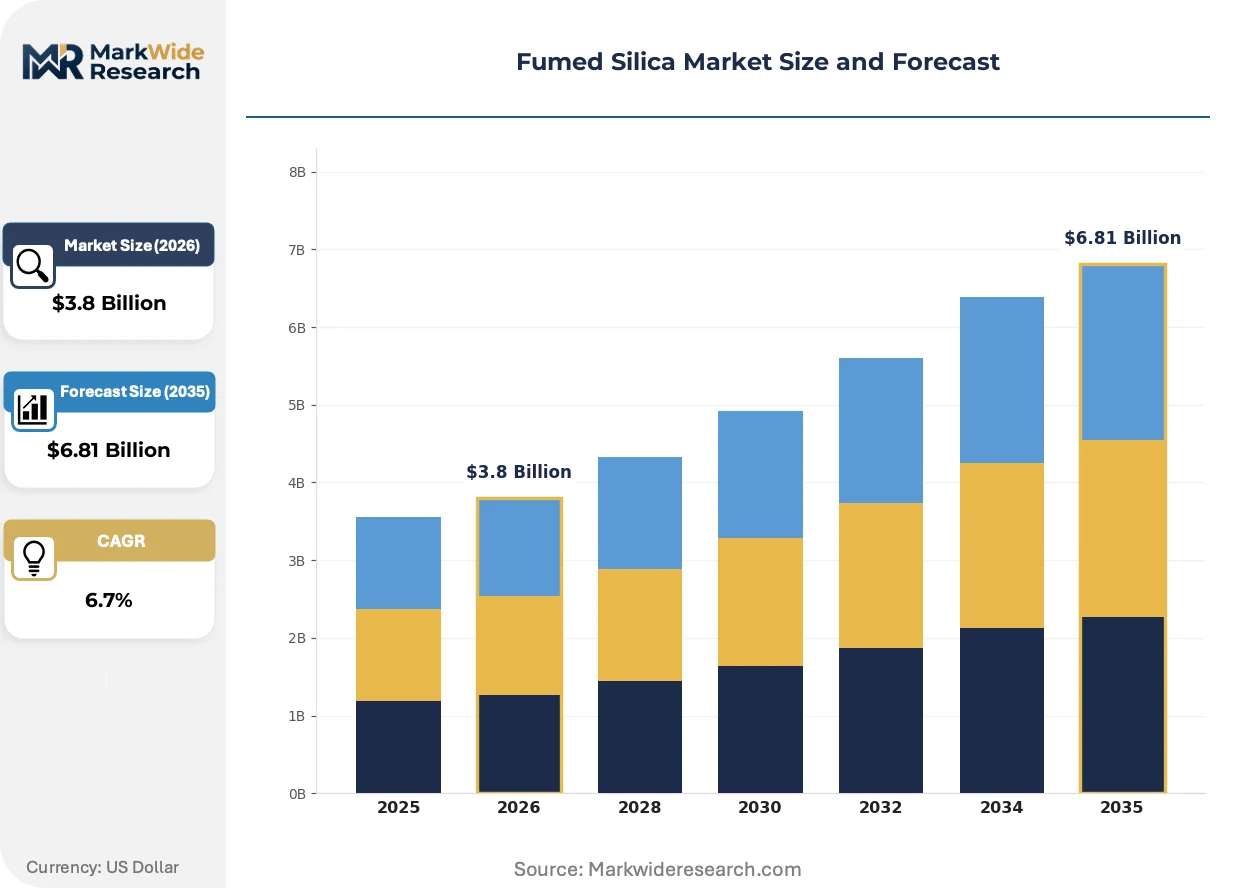
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrophobic, Hydrophilic, Surface Treated, Non-Treated Application: Coatings, Adhesives, Sealants, Plastics End User: Automotive, Electronics, Pharmaceuticals, Food Industry Distribution Channel: Online, Direct Sales, Retail, Distributors |
| Companies Covered | Tokuyama Corporation, PPG Industries, Evonik Industries AG, W.R. Grace & Co, Solvay Group, Cabot Corporation, OCI Company Ltd, Dongyue Group, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fumed Silica Market Emerging Trajectories
Process intensification and regulatory disclosure requirements are compressing traditional batch manufacturing economics while opening pathways for modular, lower-carbon production architectures. Three forces are actively reshaping competitive positioning.
Continuous flame hydrolysis reactor designs are decentralizing capacity deployment away from coastal mega-sites toward demand-adjacent manufacturing. Modular 5,000-tonne-per-year units allow producers to locate adjacent to silicone elastomer compounding facilities in Ohio and Bavaria, cutting logistics exposure and enabling just-in-time surface area customization. This architecture compresses working capital requirements and accelerates customer co-development cycles.
The EU F-Gas Regulation phase-down is tightening feedstock availability for traditional silicon tetrachloride routes, pushing producers toward alternative chlorosilane precursors and integrated metallurgical-grade silicon upgrading. German chemical parks in Marl and Rheinfelden are piloting closed-loop chlorine recovery systems to maintain cost position. The regulation most acutely affects hydrophobic grade producers dependent on imported Chinese precursor.
Buyers in pharmaceutical and electronics verticals are consolidating supplier panels from six-to-eight qualified sources down to two-to-three strategic partnerships with embedded technical service. This concentration rewards producers with in-house analytical capabilities and dedicated account laboratories. The shift is most visible in United States generic drug manufacturing, where lot-to-lot consistency documentation has become a primary selection criterion over unit price.
Fumed Silica Market Segmentation
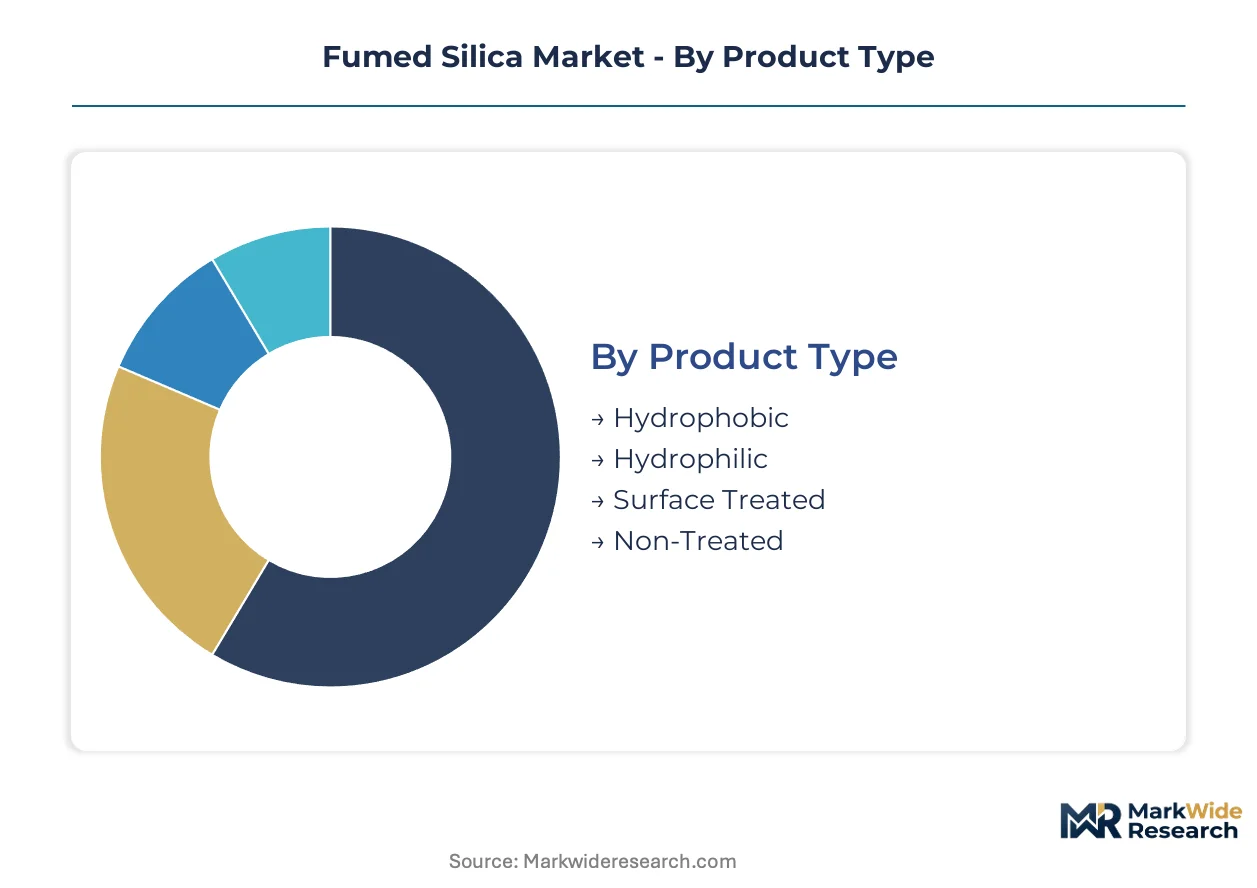
Fumed silica procurement patterns diverge sharply across surface chemistry grades and end-use specifications. Buyers in silicone elastomers and pharmaceutical formulations maintain parallel qualification tracks due to incompatible purity thresholds.
Product Type:
Supply concentration in hydrophobic production creates tiered availability, with post-treatment capacity limiting qualified supplier pools.
- Hydrophobic:Organosilane surface functionalization delivers water-repellent performance for moisture-sensitive sealants and cable compounds. German automotive suppliers now mandate REACH-registered grades, compressing procurement to ECHA-dossiered producers. FDA excipient certification extends qualification timelines to 18-24 months for pharmaceutical use.
- Hydrophilic:Native silanol groups enable hydrogen bonding in polar systems such as waterborne coatings and aqueous adhesives. Shandong manufacturing clusters supply volume to Asian coatings value chains, though MEE environmental compliance protocols create export eligibility friction.
- Surface Treated:Custom organofunctional coatings target dispersion stability in specific polymer matrices.
- Non-Treated:Base flame-hydrolyzed material serves cost-sensitive applications where surface modification adds no performance value.
Today's leader: Hydrophobic. Tomorrow's challenger: Surface Treated.
Application:
Cost tier stratification separates specification-grade formulations from commodity extenders, with rheology control commanding premium positioning.
- Coatings:Thixotropic behavior prevents sag in vertical architectural applications and enables high-build industrial finishes. EU Green Deal procurement recalibration in the Netherlands and France favors low-carbon precursor routes, rewarding integrated chlorine recovery systems.
- Adhesives:Structural bonding in electric vehicle battery enclosures demands thermal management compatibility alongside viscosity control. Ohio and Bavaria compounding facilities drive just-in-time surface area customization requirements.
- Sealants:Compression set resistance and moisture cure stability dominate construction and automotive specifications.
- Plastics:Reinforcement and anti-blocking functions compete with precipitated calcium carbonate in cost-driven formulations.
Adhesives gain share fastest in volume terms; coatings retain margin leadership.
End User:
Customer type determines technical service intensity, with direct sales channels dominating where lot traceability is non-negotiable.
- Automotive:Lightweighting programs in battery electric vehicles absorb specialized rheology modifiers for thermal interface materials. United States and German OEMs consolidate supplier panels to three qualified sources with embedded analytical capabilities.
- Electronics:Semiconductor packaging adhesives require sub-ppm metallic impurity documentation and dedicated account laboratories. Lot-to-lot consistency has displaced unit price as primary selection criterion in United States generic drug manufacturing.
- Pharmaceuticals:ICH Q3D elemental impurity limits govern excipient-grade supply, with CDSCO alignment creating first-mover openings in Hyderabad and Ahmedabad.
- Food Industry:Anti-caking and flow aid applications operate under FSSAI and FDA food contact regulations with distinct certification pathways.
Electronics direct sales contracts command highest technical service premiums; food industry volume runs through distributor intermediation.
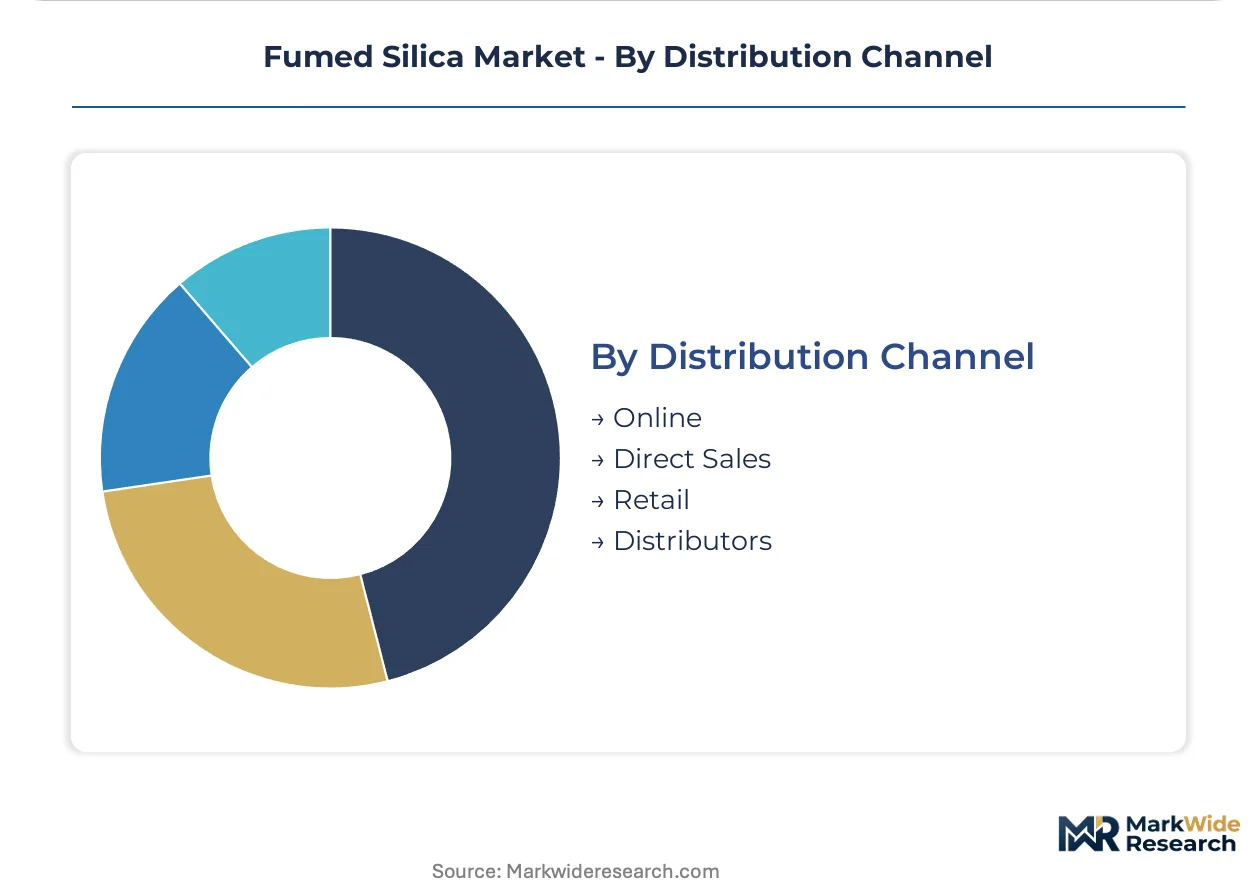
Distribution Channel:
Volume concentration in bulk pharmaceutical and electronics contracts favors channel structures that embed traceability and technical integration.
- Direct Sales:Embedded technical service and lot traceability documentation dominate pharmaceutical and electronics procurement. Account laboratories co-develop surface area specifications with compounding facilities in Ohio and Bavaria.
- Distributors:Inventory pooling serves fragmented coatings and sealants formulators with standardized hydrophilic grades. Geographic coverage compensates for lack of customization capability.
- Online:Specification sheets and certificate of analysis downloads support small-lot R&D sampling and spot purchasing.
- Retail:Packaged quantities target maintenance-repair-operations segments and small-scale formulators with limited storage infrastructure.
Direct sales captures margin concentration; distributors retain volume breadth in mature geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized organosilane chemists concentrate in German chemical parks and Chinese coastal manufacturing zones, anchoring hydrophobic grade production capacity. REACH compliance and FDA certification requirements fragment procurement patterns across major demand centers.
United States
Automotive lightweighting programs in Ohio and Michigan absorb specialized rheology modifiers for electric vehicle battery thermal interface materials. FDA oversight of excipient-grade fumed silica enforces ICH Q3D elemental impurity limits for pharmaceutical applications. Ohio compounding facilities drive just-in-time surface area customization requirements through embedded technical service contracts.
Germany
Silicone elastomer manufacturers in Bavaria and North Rhine-Westphalia expand orders as REACH compliance tightens impurity thresholds. The EU F-Gas Regulation phase-down pushes producers toward alternative chlorosilane precursors and integrated chlorine recovery systems. Chemical parks in Marl and Rheinfelden pilot closed-loop production architectures to maintain cost position against imported precursor.
China
Shandong manufacturing clusters supply hydrophilic grade volume to Asian coatings value chains while MEE environmental compliance protocols create export eligibility friction. Dual carbon targets and GB standards shape domestic production allocation and international market access. Dongyue Group competes on scale from its Shandong base as carbon intensity metrics gain procurement weight.
India
CDSCO alignment with ICH Q3D standards creates first-mover advantage for impurity-certified suppliers targeting generic drug manufacturing clusters in Hyderabad and Ahmedabad. Domestic pharmaceutical excipient demand rises as contract manufacturing organizations expand formulation capabilities. The PLI scheme for specialty chemicals accelerates backward integration investments among domestic compounders.
Japan
Semiconductor packaging adhesive manufacturers in the Kanto and Kansai regions require sub-ppm metallic impurity documentation and dedicated account laboratories. METI industrial standards govern material specifications for electronics-grade supply. Osaka-based formulators consolidate supplier panels to three qualified sources with embedded analytical capabilities.
Fumed Silica Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the fumed silica value chain, with integrated precursor supply separating margin leaders from price-takers. The vendor base clusters around three strategic archetypes: diversified chemical conglomerates with captive chlorosilane supply, pure-play fumed silica specialists with dedicated aerosol reactor capacity, and Asian scale producers competing on volume. M&A activity concentrates on regional distributors and technical service capabilities, while capacity expansion focuses on modular reactor designs adjacent to customer compounding facilities.
Within the integrated chemical conglomerate tier, Evonik Industries AG and Wacker Chemie AG exemplify producers leveraging backward control over precursor supply to sustain premium hydrophobic output. Among North American specialists, Cabot Corporation anchors regional supply through dedicated aerosol reactor infrastructure. Dongyue Group occupies a position as the scale-driven Chinese producer competing from its Shandong manufacturing base.
| Leading Market Players |
|---|
| Tokuyama Corporation |
| PPG Industries |
| Evonik Industries AG |
| W.R. Grace & Co |
| Solvay Group |
| Cabot Corporation |
| OCI Company Ltd |
| Dongyue Group |
| Wacker Chemie AG |
| Others |
Supply Flow & Price Mechanics
Automotive OEMs in Germany and the United States consolidate supplier panels to three qualified sources, anchoring contract-based long-term offtake structures that reward REACH-registered and FDA-certified producers with pricing premiums over spot-market hydrophilic grades.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and commodity-grade levels dominates fumed silica procurement, with certification level and volume scale as the primary price differentiation drivers. Cost compression in hydrophilic grades is intensifying because Shandong manufacturing clusters compete on scale without integrated precursor supply. Pharmaceutical formulators exhibit the lowest price sensitivity due to 18-to-24-month qualification timelines that lock in supplier relationships, while coatings compounders in mature geographies remain most responsive to unit price shifts.
Supply Chain Analysis
Dual-sourcing requirements from automotive and electronics buyers mandate qualification of at least two REACH-registered or FDA-certified suppliers, dispersing procurement across Germany, the United States, and China despite production concentration in Shandong. Silicon tetrachloride, organosilane post-treatment chemicals, and metallurgical-grade silicon feedstock draw from polysilicon manufacturing cycles and chlorosilane upgrading facilities. Single-source vulnerability in Chinese hydrophilic grade exports hinges on MEE environmental compliance protocol enforcement. Distribution runs through direct sales channels for pharmaceutical and electronics contracts, with distributor intermediation serving fragmented coatings and sealants formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in fumed silica rests on backward integration into silicon tetrachloride supply and the shift toward pharmaceutical-grade certification tiers that command sustained premium positioning over industrial grades.
For Market Incumbents: Deploy captive chlorosilane supply to defend margin position against non-integrated Chinese scale producers. Accelerate modular aerosol reactor deployment adjacent to Ohio and Bavaria compounding facilities to capture just-in-time customization demand. Lock in long-term offtake contracts with automotive OEMs before REACH compliance tightening compresses qualified supplier pools further. For New Entrants and Emerging Players: Capture first-mover advantage in Indian pharmaceutical excipient supply as CDSCO alignment with ICH Q3D standards creates qualification windows in Hyderabad and Ahmedabad manufacturing clusters. Target surface-treated grade customization for dispersion stability in specific polymer matrices, a segment underserved by standardized hydrophobic and hydrophilic portfolios. Lead with dedicated account laboratories and embedded technical service to differentiate from distributor-dependent incumbents. For Investors and Strategic Acquirers: Specialty chemical conglomerates with captive chlorosilane assets are the most active acquirers in this space, seeking to extend backward integration into fumed silica finishing capacity. The acquisition target archetype is regional pure-play specialists with REACH-registered hydrophobic production and established automotive supplier relationships. Watch for EU Carbon Border Adjustment Mechanism implementation timelines as the inflection indicator that reweights procurement toward low-carbon precursor routes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Supply | Captive precursor production insulates margin predictability from polysilicon cycle volatility. |
| Modular Aerosol Reactor Deployment | Demand-adjacent 5,000-tonne units in Ohio and Bavaria compress logistics exposure and working capital. |
| Pharmaceutical-Grade Certification Investment | FDA excipient validation and ECHA dossier completion lock in 18-to-24-month qualification barriers. |
| Long-Term Supply Agreement with Automotive OEMs | Panel consolidation to three qualified sources favors embedded technical service contracts over spot purchasing. |
| Green Manufacturing Transition | Integrated renewable energy and carbon capture at precursor synthesis aligns with EU Carbon Border Adjustment Mechanism. |
Methodological Framework
Multiple input streams — executive interviews with silicone elastomer procurement leads, technical discussions with coatings formulators, and regulatory consultations with ECHA and FDA specialists — were reconciled against customs trade data, SEC 10-K filings from integrated chemical conglomerates, and ACC/Cefic industry reports. Bottom-up volume modeling across hydrophobic, hydrophilic, surface-treated, and non-treated grades was cross-validated through top-down demand aggregation from adhesives, sealants, coatings, and pharmaceutical end-use applications.
Historical capacity utilization trends were cross-referenced against panel input from plant managers at Shandong manufacturing clusters and technical R&D directors at German chemical parks. Segmentation dimensions modeled include surface chemistry grade, end-use industry, and regional regulatory compliance tier. CAGRs were derived through regression analysis of precursor cost trajectories and qualification timeline compression effects, with silicon tetrachloride volatility and REACH compliance tightening as industry-specific forecast inputs across the analysis window.
Polysilicon manufacturing cycle swings, MEE environmental compliance enforcement in Shandong, and EU F-Gas Regulation phase-down timelines are the dominant revision risks to supply and demand assumptions. Deviation in Chinese export eligibility protocols would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Specialty Carbon Black Market
Specialty Materials
Electroactive Polymers (EAP) Market
Specialty Materials
Silicone Gel Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Global PMMA Microspheres Market
Specialty Materials
Asia-Pacific Reflective Tape Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Colloidal Silica Market
Specialty Materials
Hornbeam Market
Specialty Materials
Asia-Pacific Green Sic Market
Specialty Materials
Marine Mineral Complexes from Mediterranean Shells Market
Specialty Materials
Elastic Films Market
Specialty Materials
Magnesium Fluoride Market
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Silicone Solutions Market