
 Ultra Violet Glass Bottles Market | 2026-2036
Ultra Violet Glass Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra Violet Glass Bottles Market Analytics
Subscription-based refill programs and brand-owned replenishment services is realigning how ultra violet glass bottles move through premium channels. MIRON Violetglass leverages its proprietary violetglass technology to command pricing power in cosmetic and aromatherapy segments. Gerresheimer AG anchors pharmaceutical demand through validated container closure systems for light-sensitive injectables. SGD Pharma sustains European market presence with specialized molded glass expertise for nutraceutical applications.
Ultra violet glass bottles are specialized containers fabricated from violet-tinted borosilicate or flint glass that filters visible light while permitting beneficial infrared and ultraviolet-A wavelengths, typically manufactured through precision molding or tubular glass conversion processes to preserve photosensitive contents. Dropper bottles capture dominant share in cosmetic essential oil dispensing, while pharmaceutical vials represent the fastest-expanding use case driven by biologic drug stability requirements. Child-resistant closures concentrate margin pools where regulatory compliance commands premium pricing across North American pharmaceutical contracts.
FDA container closure guidance and EMA stability testing requirements shape pharmaceutical adoption timelines, while REACH chemical compliance and EU Packaging and Packaging Waste Directive influence material specifications across European supply chains. Stakeholders must monitor evolving pharmacopeial standards for light transmission testing as regulatory divergence between FDA and EMA pathways creates certification complexity for multi-region suppliers.
Market Dynamics
Pharmaceutical stability mandates and cosmetic brand premiumization are compressing procurement cycles for validated violetglass packaging, forcing converters to hold larger safety stocks of borosilicate feedstock.
Growth Catalysts
- EMA stability testing requirements:Biologic drug developers across Germany and Switzerland now specify ultra violet glass vials for light-sensitive injectables, expanding pharmaceutical offtake.
- Premium cosmetic refill programs:French and German essential oil brands are converting single-use packaging to subscription-based violetglass systems, locking in multi-year supply agreements.
- Borosilicate glass corridors:Concentrated precision molding capabilities in Germany's industrial heartland enable rapid scale-up for nutraceutical contract manufacturers.
Market Restraints
- Energy-intensive borosilicate melting:Natural gas price volatility at German and Czech glassworks compresses margin pools for mid-volume converters.
- REACH chemical compliance:ECHA substance restrictions on certain colorant precursors extend certification timelines for new violetglass formulations by 8-14 months.
- Plastic barrier laminates:Multi-layer polymer containers with UV-blocking additives threaten cost-sensitive cosmetic segments where brand equity permits material substitution.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO-aligned manufacturers in Maharashtra and Gujarat are qualifying violetglass for temperature-sensitive biologics bound for European markets.
- Child-resistant closure integration:US FDA container closure guidance creates pull for combined violetglass vial and certified closure systems in pediatric and geriatric dosing.
- Near-infrared spectroscopy integration:Convergence of photoprotective glass with inline quality verification enables real-time stability monitoring for high-value serums.
Industry Challenges
- Pharmacopeial light transmission testing:Divergent USP and EP methods for ultraviolet-A permeability measurement force duplicate validation runs for multi-region suppliers.
- Specialized mold engineering talent:Shortage of precision glass tooling designers in Saxony and Thuringia extends new product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra Violet Glass Bottles Market |
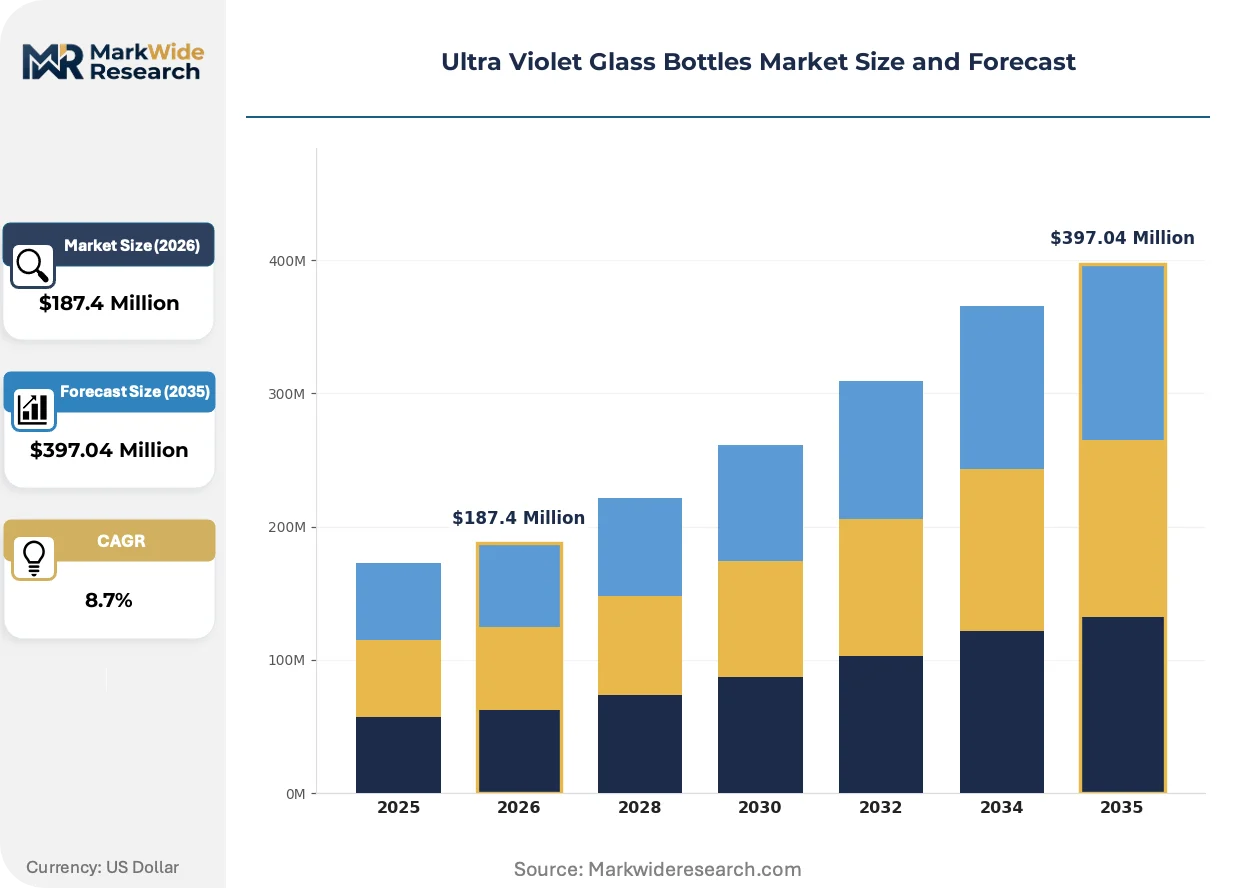
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dropper Bottles, Spray Bottles, Jars, Vials Use Case: Cosmetics, Pharmaceuticals, Food & Beverage, Nutraceuticals Capacity: 30ml, 50ml, 100ml, 250ml Closure Type: Child-Resistant Caps, Dropper Caps, Screw Caps, Pump Caps |
| Companies Covered | MIRON Violetglass, Berlin Packaging, SGD Pharma, Beatson Clark, Gerresheimer AG, Ardagh Group, Owens-Illinois Inc., Schott AG, Stoelzle Glass Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra Violet Glass Bottles Market Evolving Landscape
Material science advances and regulatory precision are compressing traditional glass-to-plastic substitution patterns while opening new performance tiers for photosensitive product protection.
Laser-etched surface functionalization is rewriting how violetglass bottles interact with automated filling lines. Pharmaceutical contract packagers in Germany and Switzerland are adopting micro-structured grip patterns that eliminate secondary labeling for traceability. This capability is rewriting throughput economics for high-speed biologic assembly operations.
REACH chemical compliance revisions are tightening colorant purity thresholds for violetglass formulations. ECHA substance evaluations now require extended migration testing for borosilicate contact layers. Cosmetic and pharmaceutical segments are responding by consolidating supplier qualification to pre-validated European converters with established analytical capabilities.
Direct-to-consumer replenishment subscriptions are displacing traditional wholesale distribution for premium essential oil brands. French aromatherapy houses now bypass distributor markups through owned-channel refill programs. This pattern concentrates most visibly in Paris and Lyon, where boutique formulators leverage violetglass durability to justify deposit-return logistics.
Ultra Violet Glass Bottles Market Segmentation
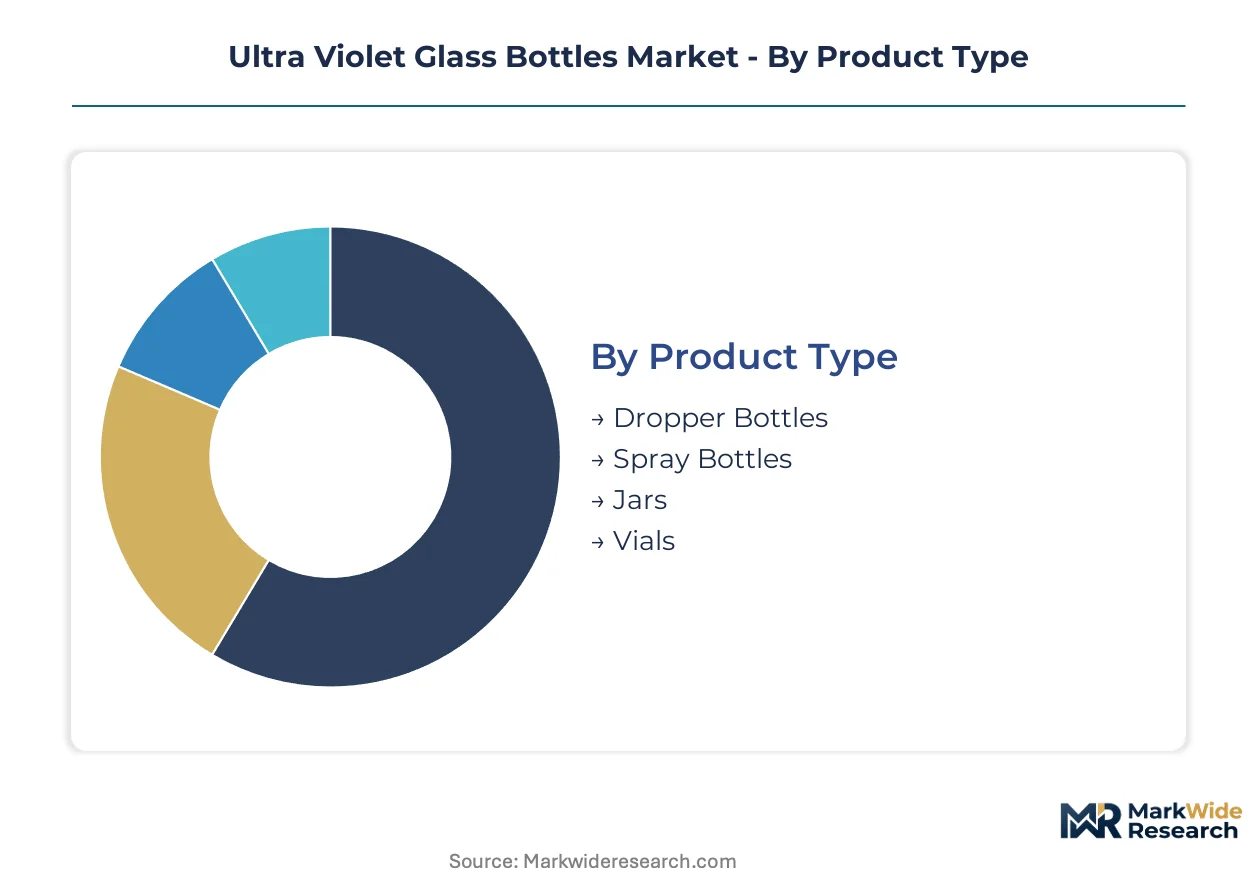
Ultra violet glass bottles fragment across four distinct category axes, each reflecting divergent buyer priorities around regulatory compliance, dispensing mechanics, and brand positioning. Understanding these splits reveals where pricing power concentrates and where converters must tailor capacity investments.
Product Type:
Buyers differentiate primarily by liquid viscosity and dispensing precision requirements rather than container geometry alone.
- Dropper Bottles:Engineered with precision-molded borosilicate necks and calibrated pipette interfaces for controlled essential oil and serum dispensing. French aromatherapy houses in Lyon and Paris specify these for subscription refill programs where deposit-return durability justifies premium unit economics.
- Vials:Tubular glass conversions with validated container closure systems for light-sensitive injectables. Swissmedic-aligned biologic developers across Basel and Zurich are accelerating pharmaceutical offtake driven by EMA stability testing mandates for temperature-sensitive formulations.
- Spray Bottles:Atomizer-compatible violetglass with compression-molded shoulder profiles for fine mist applications in cosmetic toners.
- Jars:Wide-mouth molded containers for semi-solid balms and cream formulations where spatula access matters.
Dropper bottles lead volumes today; vials are gaining share fastest.
Use Case:
End-use concentration determines certification burden and margin structure across converter portfolios.
- Cosmetics:Premium essential oil and serum packaging where brand equity permits material substitution resistance. German natural cosmetics brands leverage violetglass durability to justify owned-channel replenishment subscriptions, bypassing traditional wholesale markups.
- Pharmaceuticals:Validated container closure systems for light-sensitive biologics and injectables. FDA container closure guidance and EMA stability requirements compress procurement cycles, forcing converters to hold larger safety stocks of borosilicate feedstock.
- Nutraceuticals:Specialized molded glass for probiotic and omega-3 formulations where oxidation protection extends shelf stability.
- Food & Beverage:Niche applications for high-value honey and oil preservation where photoprotection commands sensory quality premiums.
Cosmetics anchors revenue today; pharmaceuticals shows the steepest expansion trajectory.
Capacity:
Volume selection correlates with usage frequency and replenishment cadence in direct-to-consumer channels.
- 30ml:Travel-size and trial-format specifications for subscription sampling programs. French boutique formulators concentrate procurement here for first-order customer acquisition economics.
- 50ml:Standard serum and essential oil formats balancing portability with per-unit value perception.
- 100ml:Core replenishment size for household essential oil consumption with optimized logistics cube efficiency.
- 250ml:Bulk professional and salon-grade formats where institutional buyers prioritize per-milliliter cost containment.
100ml leads volumes today; 30ml is climbing the fastest on sampling program adoption.
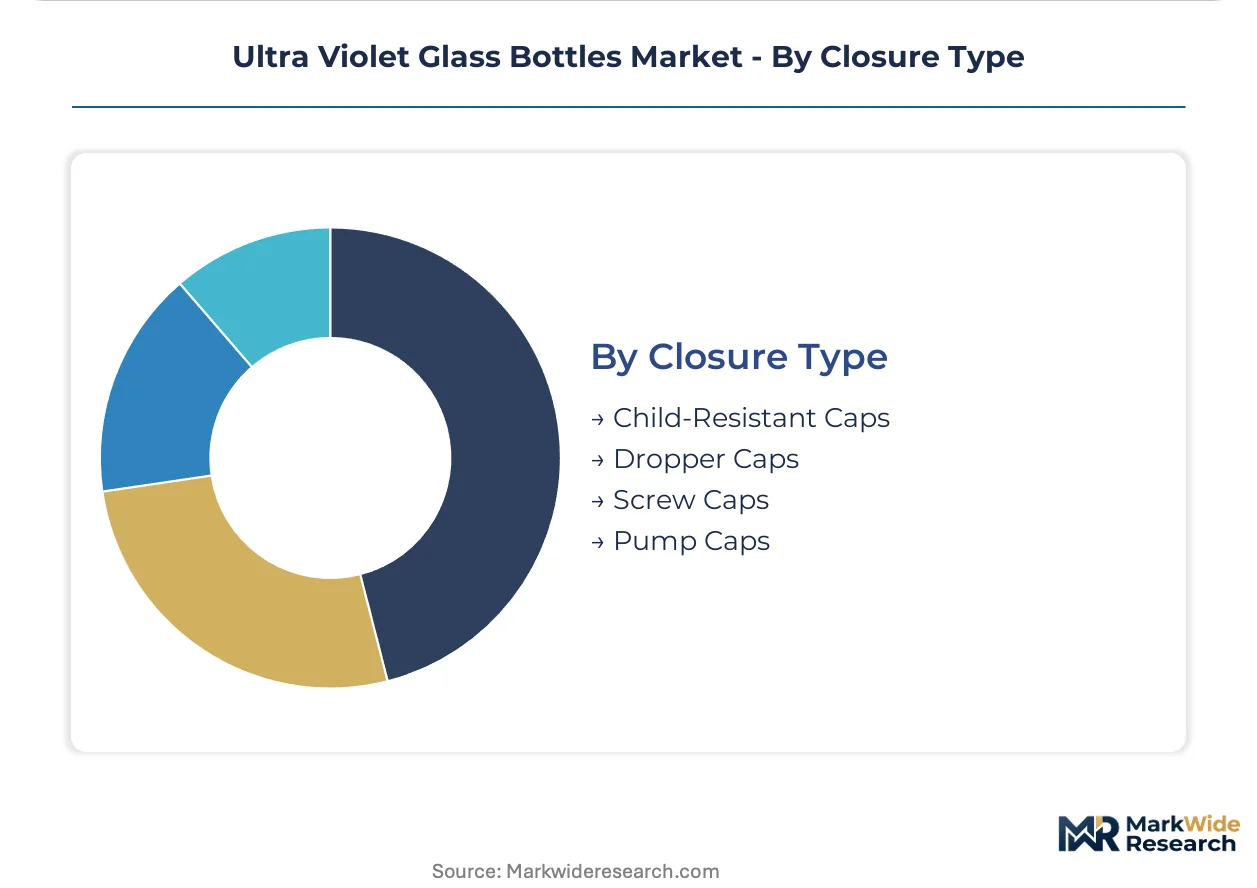
Closure Type:
Regulatory geography and end-user safety profiles dictate hardware specification and certification investment.
- Child-Resistant Caps:Certified closure systems combining violetglass vials with push-and-turn mechanisms for pediatric and geriatric dosing. US FDA container closure guidance creates concentrated margin pools where compliance commands premium pricing across North American pharmaceutical contracts.
- Dropper Caps:Integrated pipette assemblies with silicone bulb and glass stem for precision dispensing in cosmetic applications.
- Screw Caps:Standard threaded closures for cost-sensitive segments where tamper evidence suffices.
- Pump Caps:Metered-dose mechanisms for viscous serum formulations requiring controlled extrusion.
Dropper caps lead volumes today; child-resistant caps are expanding most quickly on regulatory pull.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pharmaceutical-grade violetglass output through precision borosilicate corridors, while France drives cosmetic subscription adoption through Paris and Lyon formulator networks. Regulatory fragmentation between FDA and EMA pathways forces multi-region suppliers into duplicate certification runs.
United States
Biologic drug developers specify violetglass vials under FDA container closure guidance for light-sensitive injectables. CDER stability testing mandates compress procurement timelines for validated packaging systems. New Jersey and Massachusetts pharmaceutical clusters anchor North American demand for certified child-resistant closure integration.
Germany
EMA stability requirements and REACH chemical compliance tighten material specifications for borosilicate converters. Natural gas price volatility at Saxon and Thuringian glassworks pressures mid-volume manufacturer margins. Bavaria's precision molding industrial corridor enables rapid scale-up for nutraceutical contract packaging.
Switzerland
Swissmedic-aligned biologic developers across Basel and Zurich accelerate pharmaceutical offtake for temperature-sensitive formulations. Stability testing protocols exceed EMA baselines, extending supplier qualification periods. Zürich's pharmaceutical packaging cluster concentrates demand for validated tubular glass conversions.
France
Premium essential oil houses in Paris and Lyon bypass wholesale distribution through owned-channel refill subscriptions. ANSM cosmetic safety regulations align with REACH colorant purity thresholds for violetglass formulations. Île-de-France aromatherapy formulators leverage deposit-return logistics justified by violetglass durability.
India
CDSCO-aligned manufacturers in Maharashtra and Gujarat qualify violetglass for biologic exports bound for European markets. PLI scheme incentives support pharmaceutical packaging capability expansion. Mumbai-Pune pharmaceutical corridor drives temperature-sensitive formulation packaging demand.
Ultra Violet Glass Bottles Market Competitive Landscape
Top-tier vendors anchor pharmaceutical validation tiers, while mid-cap specialists occupy cosmetic and nutraceutical niches. The vendor base stratifies across three layers: multinational glass conglomerates with FDA-EMA dual certification, regional precision molding specialists, and boutique violetglass technology licensors. Consolidation pressure concentrates among borosilicate feedstock converters facing energy cost volatility. Dominant competitive moves include backward integration into captive borosilicate supply and technology licensing partnerships for proprietary violetglass formulations.
Within the proprietary technology tier, MIRON Violetglass exemplifies specialized violetglass licensors commanding premium positioning in cosmetic channels. Gerresheimer AG and SGD Pharma represent validated pharmaceutical container specialists with established EMA-FDA dual pathway certification. These three anchors illustrate how competitive positioning diverges between technology-driven premiumization and regulatory-driven pharmaceutical validation.
| Leading Market Players |
|---|
| MIRON Violetglass |
| Berlin Packaging |
| SGD Pharma |
| Beatson Clark |
| Gerresheimer AG |
| Ardagh Group |
| Owens-Illinois Inc. |
| Schott AG |
| Stoelzle Glass Group |
| Others |
Value Network & Pricing Analysis
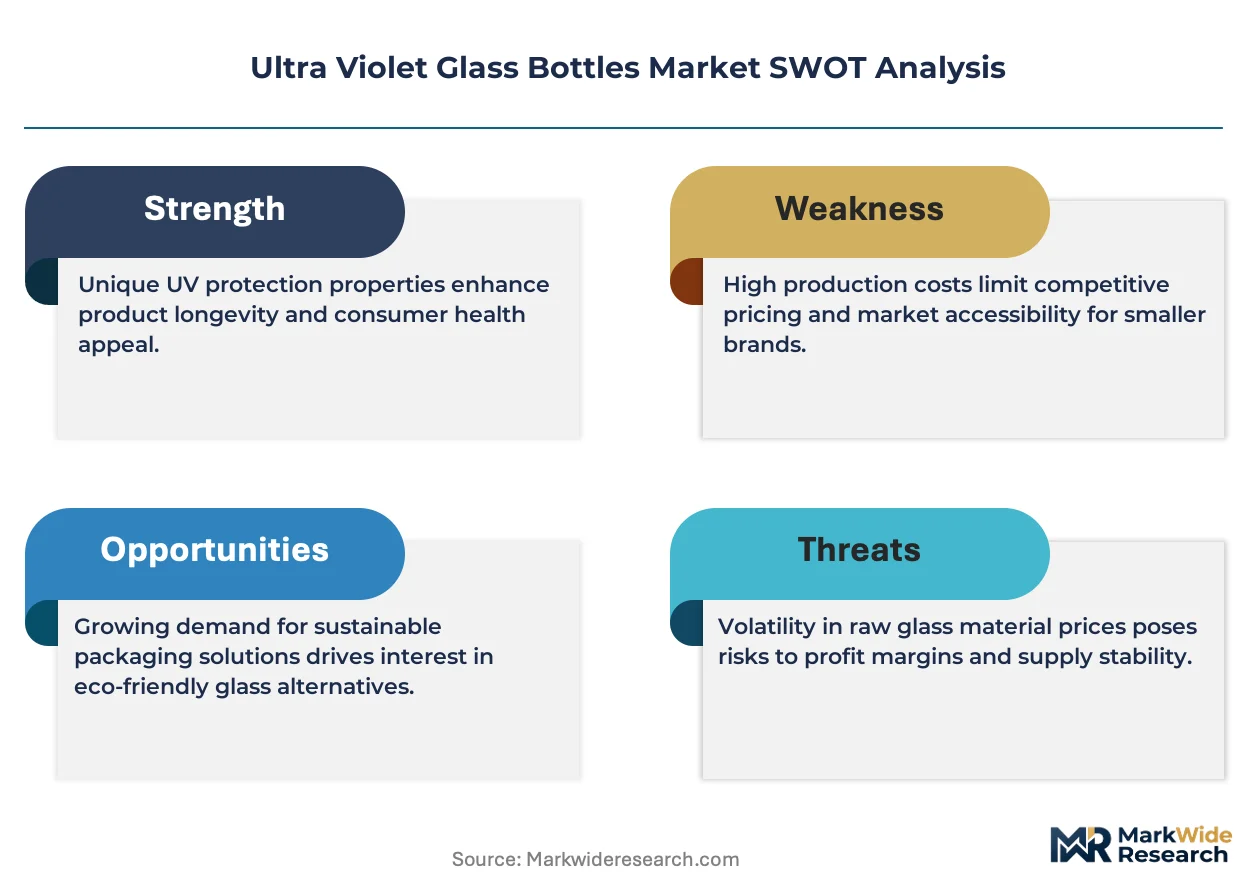
EMA stability testing mandates for light-sensitive biologics are compressing procurement cycles for validated violetglass packaging, forcing converters to hold larger safety stocks of borosilicate feedstock and tightening pricing power among certified suppliers.
Pricing Analysis
Capacity additions in Germany's precision molding corridor are reshaping price floors for pharmaceutical-grade violetglass. Three-tier pricing structure across premium, standard, and economy levels separates FDA-EMA dual-certified systems from single-pathway validated containers and unvalidated cosmetic grades. Price differentiation hinges on certification tier and volume scale. Pricing pressure stems from natural gas cost volatility at Saxon glassworks. Nutraceutical contract manufacturers show highest price sensitivity; Swiss biologic developers show least.
Supply Chain Analysis
Regional distribution centers in Bavaria and North Rhine-Westphalia anchor hub-and-spoke patterns for European pharmaceutical offtake. Manufacturing concentrates in Germany, France, and Switzerland. Production draws from specialized borosilicate feedstock, precision mold tooling, and certified closure hardware. Single-source vulnerability runs through Thuringian mold engineering talent pools. Distribution runs through validated cold-chain logistics for temperature-sensitive biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Premium cosmetic brands are converting wholesale procurement to subscription-based refill programs that demand durable violetglass specifications.
For Market Incumbents: Anchor pharmaceutical validation tiers through captive borosilicate supply and dual-pathway FDA-EMA certification investment. Plastic barrier laminates with UV-blocking additives threaten cost-sensitive cosmetic segments; defend through backward integration into proprietary violetglass formulations and exclusive channel control with Paris-Lyon aromatherapy houses. For New Entrants and Emerging Players: The gap between premium pharmaceutical-grade pricing and economy cosmetic tiers offers entry points for mid-cap specialists. Target Indian CDSCO-aligned manufacturers qualifying violetglass for European-bound biologic exports. Pursue white-label supply agreements with Maharashtra-Gujarat pharmaceutical corridors as the most penetrable geography. For Investors and Strategic Acquirers: Asymmetric upside sits with precision molding specialists holding validated EMA-FDA dual certification and established analytical capabilities for REACH colorant compliance. Five-to-ten year viability favors converters with captive borosilicate supply and child-resistant closure integration expertise. Watch ECHA substance evaluation timelines for violetglass colorant precursors as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Feedstock | Captive supply insulates Saxon and Thuringian converters from natural gas price volatility. |
| Dual-Pathway FDA-EMA Certification Investment | Validated container closure systems command premium pricing across North American and European pharmaceutical contracts. |
| Child-Resistant Closure Integration | Combined violetglass vial and certified closure systems address US FDA container closure guidance for pediatric dosing. |
| Subscription Refill Program Partnerships | French and German essential oil brands leverage violetglass durability to justify deposit-return logistics economics. |
| Near-Infrared Spectroscopy Capability Addition | Inline quality verification enables real-time stability monitoring for high-value serum formulations. |
Research Methodology
Direct dialogue with pharmaceutical packaging procurement managers, cosmetic brand supply chain directors, borosilicate glass plant engineers, and regulatory affairs specialists at EMA-aligned converters grounded the qualitative foundation. Secondary validation drew from FDA container closure guidance documents, EMA stability testing protocols, REACH substance restriction updates, and European glass federation production statistics. Bottom-up demand modeling and top-down supply capacity assessments were triangulated to cross-verify volume estimates.
Segment-level outputs across product type, use case, capacity tier, and closure configuration were generated over the projection horizon. CAGRs were derived from weighted average growth rates across pharmaceutical, cosmetic, nutraceutical, and food and beverage demand clusters. Forecast inputs incorporated EMA stability mandate adoption curves, natural gas price assumptions for German glassworks, and subscription refill program penetration rates in French aromatherapy channels.
The model assumes a particular technology adoption path for laser-etched surface functionalization; alternative pathways for automated traceability integration would alter the outlook. Forecasts reflect documented assumptions around regulatory timeline adherence and feedstock cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Low Iron Glass Market
Glass
Asia-Pacific Glassware Market
Glass
Global Glass Flake Coatings Market
Glass
Mirrored Glass Market
Glass
Global Flat Glass Market
Glass
Glass Grade Dolomite Market
Glass
Pharmaceutical Glass Tubing Market
Glass
Optical Glass Market
Glass
Glass Lens Market
Glass
Technical Glass Market
Glass
Laboratory Glassware Market
Glass
Birefringent Crystals Market
Glass
Glass Manufacturing Market
Glass
Glass Alternative Materials Market
Glass
Coated Solar Control Glass Market
Glass
Glazing Gel Market