
 Insulated Glass Market | 2026-2036
Insulated Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Glass Market Outlook
EN 1279 certification is reorganizing competitive access across the European insulated glass supply base, filtering out manufacturers lacking validated argon retention and dew point performance. Saint-Gobain S.A. leverages integrated float-to-fabrication capabilities across multiple continents. Cardinal Glass Industries anchors its position through captive low-emissivity coating technology and regional plant density. Schott AG differentiates via fire-resistant and specialty vacuum-insulated variants for premium architectural specifications.
Insulated glass consists of two or more hermetically sealed panes separated by a dehydrated airspace or inert gas fill, with thermal performance governed by spacer bar conductivity, gas type, and coating emissivity values below 0.05. Its primary purpose is to reduce conductive and radiative heat transfer in building envelopes while maintaining visible light transmission. Low-emissivity glass commands the dominant value share due to mandatory energy code adoption across temperate climate zones. Triple glazing represents the fastest-expanding product category as net-zero building standards tighten envelope performance thresholds. Facades concentrate the highest installed value per square meter among all application segments.
EPA ENERGY STAR certification requirements and ASHRAE 90.1 baseline envelope standards shape product specifications and market access across North American construction markets. ECHA REACH compliance and evolving EU Green Deal embodied-carbon tracking are extending regulatory scope from operational to full lifecycle thermal performance. Stakeholders must monitor evolving spacer warm-edge technology qualification protocols and regional low-carbon procurement mandates to align manufacturing investments with emerging code trajectories.
Market Dynamics
EN 1279 certification reorganization is filtering manufacturer access across Europe, while commercial retrofit mandates in Germany, the United States, and Japan are compressing specification cycles for high-performance glazing assemblies.
Growth Catalysts
- Passivhaus building codes:Germany's certified construction stock and adjacent Central European markets mandate triple-glazed assemblies, pulling demand for warm-edge spacer technology and low-emissivity coatings.
- F-Gas Regulation phase-out:Europe's accelerating restrictions on thermally inefficient glazing systems are disqualifying incumbent products and opening specification windows for gas-filled alternatives.
- Metropolitan retrofit corridors:Commercial building envelope upgrades in Chicago, London, and Tokyo are concentrating project pipelines for high-U-value insulated glass installations.
Market Restraints
- Argon supply concentration:Industrial gas production clusters in Germany and the United States create input cost volatility for gas-filled unit manufacturers.
- Spacer conductivity limitations:Aluminum spacer technology retains thermal bridging performance gaps that warm-edge alternatives have not fully displaced at scale.
- REACH compliance burden:ECHA chemical registration requirements extend certification timelines and raise qualification costs for coating chemistry suppliers.
Strategic Opportunities
- Vacuum-insulated glass convergence:The intersection of thin-film deposition expertise and hermetic sealing technology is opening premium architectural specifications for ultra-thin assemblies.
- India building code evolution:BIS energy efficiency standards for commercial construction are creating first-mover positioning for certified insulated glass suppliers.
- EU Green Deal procurement mandates:Embodied-carbon tracking requirements are tilting public project specifications toward low-carbon glazing supply chains.
Industry Challenges
- Warm-edge technology qualification:Regional certification protocol fragmentation between North American and European test standards complicates product portfolio rationalization.
- Coating equipment capex intensity:Low-emissivity sputter deposition lines require capital commitments that constrain mid-scale manufacturer expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Glass Market |
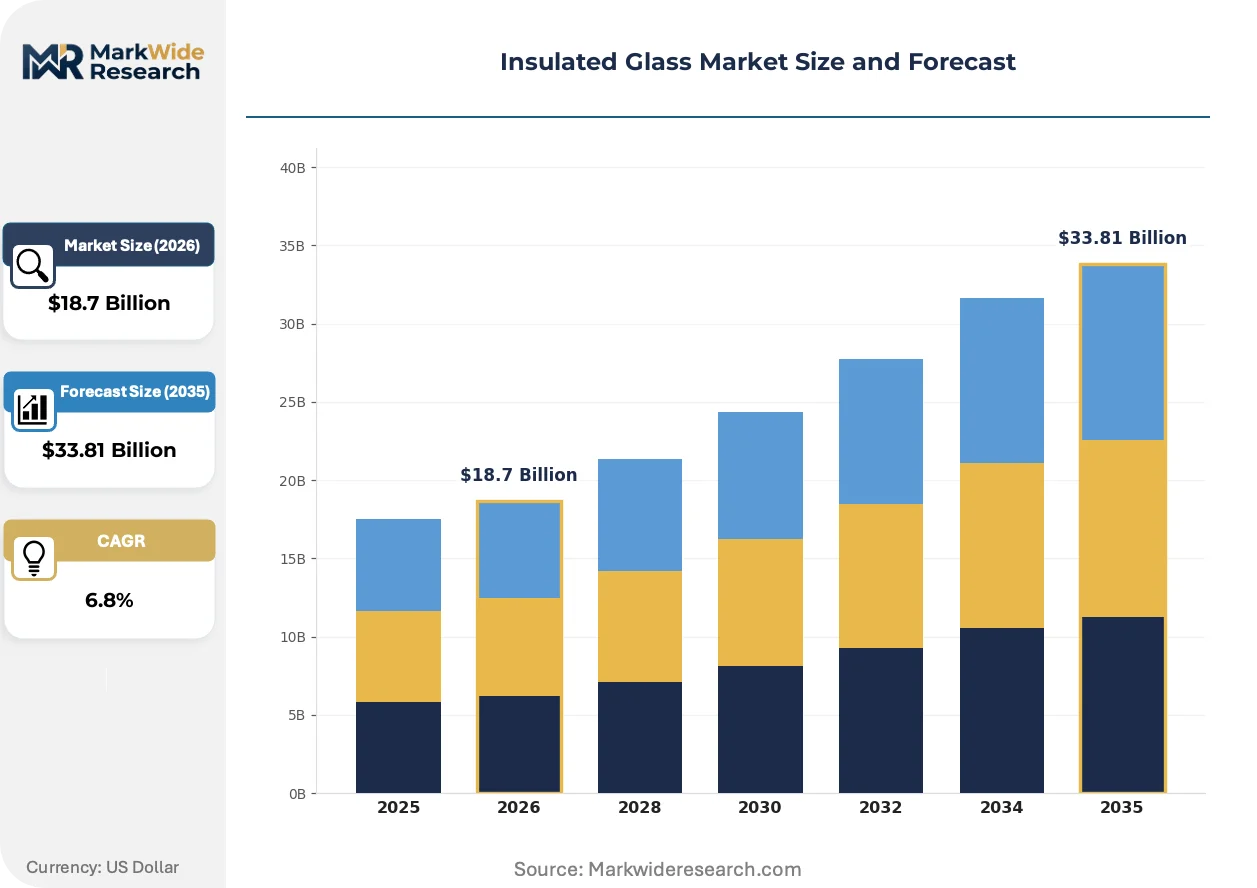
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double Glazing, Triple Glazing, Laminated Glass, Low-Emissivity Glass End User: Residential, Commercial, Industrial, Automotive Application: Windows, Doors, Facades, Skylights Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | NSG Group, Central Glass Co. Ltd., Saint-Gobain S.A., Pilkington Group Limited, Vitro S.A.B. de C.V., Guardian Glass, Cardinal Glass Industries, Schott AG, AGC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Glass Market Strategic Shifts
Specification velocity is accelerating as energy code adoption compresses product lifecycles, while coating and spacer technologies are diverging into performance-tiered architectures that reward manufacturing precision over commodity scale.
Warm-edge spacer technology is bifurcating the mid-market segment. Thermally optimized thermoplastic and stainless-steel profiles reduce linear thermal transmittance below aluminum alternatives. Passivhaus-certified projects and net-zero commercial specifications in Germany and Austria are adopting these spacers at accelerated rates. The technology is bifurcating competitive positioning between precision fabricators with validated psi-values and commodity assemblers locked into conventional aluminum systems.
REACH chemical registration and evolving EU Green Deal embodied-carbon tracking are extending regulatory scope from operational to full lifecycle thermal performance. Coating suppliers must now document cradle-to-gate emissions alongside argon retention and dew point specifications. Triple-glazed assemblies with certified low-carbon aluminum or timber framing are capturing preference share in public procurement across Denmark, the Netherlands, and France.
Architectural specification authority is consolidating around facade engineering consultancies and envelope commissioning agents. Building owners in London, New York, and Singapore are delegating glazing selection to specialized technical advisors rather than general contractors. This channel shift compresses manufacturer access to decision-makers and rewards suppliers with dedicated specification support capabilities and documented project reference libraries.
Insulated Glass Market Segmentation
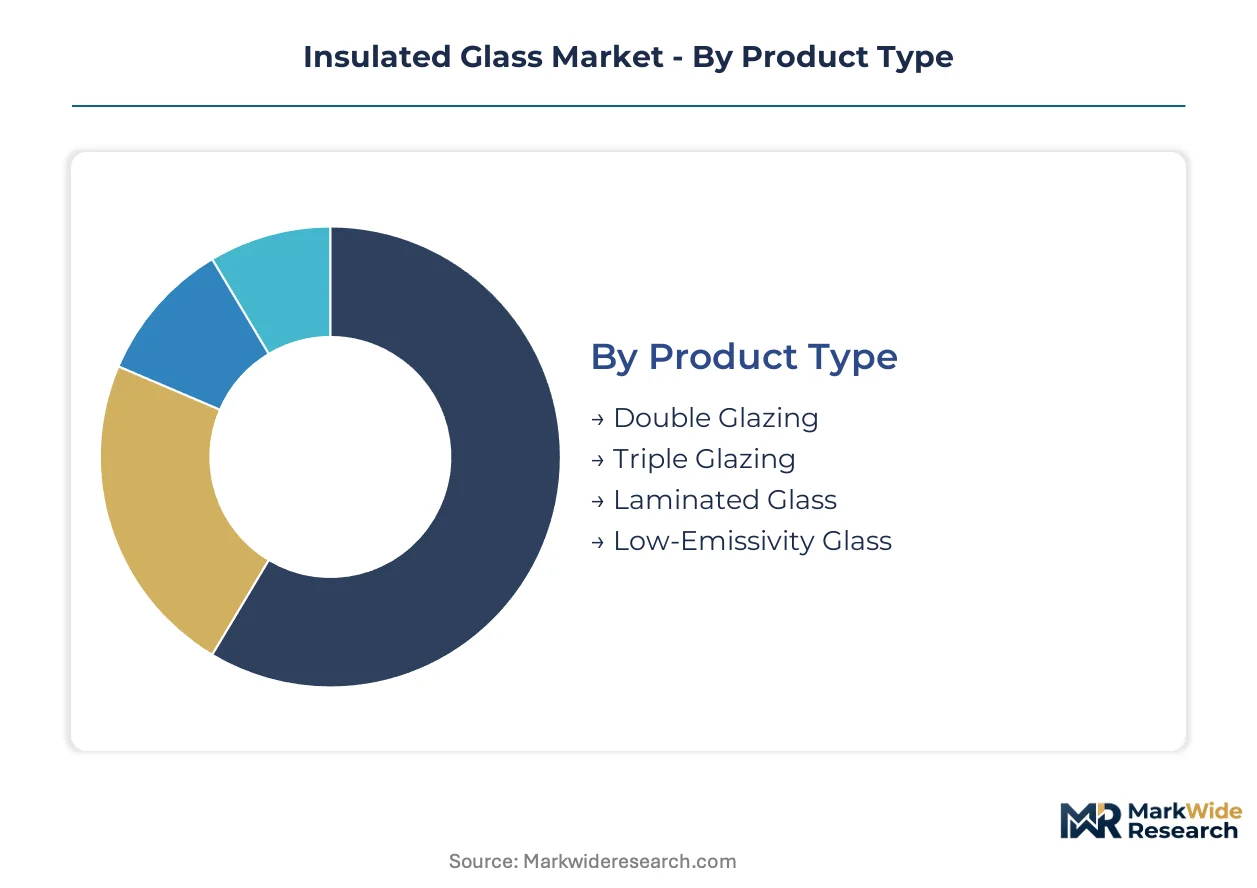
Segmentation in the insulated glass market reveals how thermal performance tiers, building typologies, and specification channels create distinct competitive arenas. Product architecture and distribution access determine which manufacturers capture value across retrofit and new construction cycles.
Product Type:
Substitute pressure concentrates on legacy double-glazing configurations as triple-glazed and low-emissivity variants displace thermal performance thresholds. Double glazing faces the most acute substitution risk from higher-performance alternatives.
- Low-Emissivity Glass:Sputter-deposited metallic oxide coatings reduce emissivity below 0.05, enabling U-value compliance in temperate climate zones without full triple-glazed thickness. Demand concentrates in North American commercial retrofits where ASHRAE 90.1 baselines mandate coated substrates.
- Triple Glazing:Three-pane assemblies with dual gas-filled cavities achieve U-values below 0.8 W/m²K, satisfying Passivhaus certification requirements. Germany and Austria's certified building stock anchor specification velocity for warm-edge spacer integration.
- Double Glazing:Two-pane units with single air or gas cavity retain cost advantage in price-sensitive residential segments and mild climate zones with less stringent energy codes.
- Laminated Glass:Polyvinyl butyral interlayers bond multiple glass plies for acoustic damping and structural safety, finding application in airport-adjacent and high-rise residential specifications.
Low-emissivity glass retains volume leadership; triple glazing holds the steepest expansion curve.
End User:
Cost tier stratification separates specification authority between owner-occupied assets and developer-driven construction where first-cost optimization dominates procurement.
- Commercial:Envelope commissioning agents and facade engineering consultancies control glazing selection for office towers, hotels, and retail complexes. Metropolitan retrofit corridors in Chicago and London compress project pipelines for high-U-value assemblies.
- Residential:Single-family and multi-family construction drives volume through regional window replacement contractors and national home improvement retailers. Passivhaus-certified single-family stock in Germany and Austria specifies triple-glazed units with certified psi-values.
- Industrial:Manufacturing facilities and warehouses prioritize daylighting with moderate thermal performance, accepting double-glazed units where operational energy represents smaller cost fractions.
- Automotive:OEM glazing specifications for windshields and side windows demand laminated and tempered substrates with integrated antenna and HUD compatibility.
Residential commands absolute unit volume; commercial delivers highest value per square meter installed.
Application:
Application architecture determines performance certification requirements and installation complexity, with facade systems demanding the most rigorous thermal and structural validation.
- Facades:Curtain wall and storefront systems integrate insulated glass with pressure-equalized rainscreen design. Unitized facade fabrication in Singapore and New York rewards suppliers with project-specific engineering support and documented reference libraries.
- Windows:Operable and fixed fenestration dominates replacement cycles and new construction volume. EN 1279 certification filters manufacturer access in European replacement markets.
- Doors:Entrance and patio door assemblies balance thermal performance with durability requirements for high-traffic openings.
- Skylights:Sloped and horizontal glazing applications demand enhanced structural loading and condensation resistance for overhead exposure.
Windows retain installation volume leadership; facades capture the steepest value-per-unit trajectory.
Distribution Channel:
Channel concentration shapes manufacturer margin structure, with direct sales to large contractors and developers bypassing distributor markups while requiring dedicated specification support investment.
- Direct Sales:Large commercial contractors and envelope subcontractors purchase through mill direct relationships with volume pricing and project-specific fabrication scheduling.
- Distributors:Regional glazing distributors and building material wholesalers stock standard configurations for residential replacement contractors and smaller commercial installers.
- Retail:Home improvement centers and lumberyards serve DIY replacement and local contractor pickup with limited size and performance ranges.
- Online:Digital channels emerge for specification-grade product selection and project quoting, though physical inspection requirements constrain final purchase closure.
Direct sales retain value concentration; distributor channels maintain broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial building envelope retrofits and Passivhaus-certified construction anchor demand across distinct metropolitan clusters. Specification authority concentrates in Germany's certified building stock, US commercial corridors, and Japanese urban renewal zones.
Germany
Passivhaus-certified construction mandates triple-glazed assemblies with certified psi-values for warm-edge spacers. F-Gas Regulation phase-out disqualifies thermally inefficient glazing systems from public procurement. Berlin and Munich metropolitan corridors compress specification cycles for high-performance facade installations.
United States
EPA ENERGY STAR certification and ASHRAE 90.1 baseline standards shape commercial retrofit specifications across temperate climate zones. Metropolitan corridors in Chicago and New York concentrate project pipelines for high-U-value insulated glass. Regional plant density near industrial gas clusters mitigates argon supply volatility.
Japan
Urban renewal mandates in Tokyo and Osaka drive commercial building envelope upgrades with stringent thermal performance thresholds. METI energy efficiency standards accelerate displacement of legacy single-pane systems. Yokohama and Nagoya fabrication clusters serve domestic specification-grade demand.
United Kingdom
Facade engineering consultancies in London delegate glazing selection for commercial towers and heritage retrofits. Evolving EN standards filter manufacturer access through validated argon retention protocols. Birmingham and Manchester distribution hubs channel replacement volume for residential contractors.
India
BIS energy efficiency standards for commercial construction create first-mover positioning for certified insulated glass suppliers. Developer-driven procurement in Mumbai and Delhi-NCR prioritizes first-cost optimization over performance tiers. Gujarat and Maharashtra industrial corridors attract coating technology investments.
Insulated Glass Market Competitive Environment
Player mix skews toward integrated float-to-fabrication conglomerates and regional specialty fabricators. Consolidation concentrates around coating technology holders and captive gas-filling capabilities. Two strategic archetypes dominate: integrated glass groups with proprietary low-emissivity deposition lines, and precision fabricators with validated EN 1279 certification. Competitive moves center on warm-edge spacer technology licensing and regional capacity expansion near metropolitan retrofit corridors.
Within the integrated glass tier, Saint-Gobain S.A. and AGC Inc. exemplify archetypes with captive float glass supply and multi-continental fabrication footprints. Among regional specialists, Cardinal Glass Industries occupies a position representing coating technology differentiation and dense regional plant networks. Schott AG sits within the specialty tier, exemplifying premium architectural positioning through vacuum-insulated and fire-resistant variants. These anchors illustrate how competitive advantage separates between scale-driven coating integration and precision fabrication with certified performance documentation.
| Leading Market Players |
|---|
| NSG Group |
| Central Glass Co. Ltd. |
| Saint-Gobain S.A. |
| Pilkington Group Limited |
| Vitro S.A.B. de C.V. |
| Guardian Glass |
| Cardinal Glass Industries |
| Schott AG |
| AGC Inc. |
| Others |
Value Chain & Pricing Dynamics
Float glass furnace scale economies in Germany and the United States anchor global cost structures, with 1,000-tonne-per-day capacity thresholds determining viable price floors for gas-filled unit manufacturers. Regional plant density near industrial gas clusters compresses logistics premiums while EN 1279 certification compliance separates premium-tier fabricators from commodity assemblers locked into aluminum spacer legacy pricing.
Pricing Analysis
Cost-plus contracts indexed to argon spot pricing and flat glass producer price indices dominate procurement between multinational fabricators and commercial envelope contractors. Price differentiation rests on EN 1279 certification tier and warm-edge spacer psi-value performance, with Passivhaus-certified projects commanding substantial premiums over standard double-glazed alternatives. Cost compression in mid-market residential replacement intensifies as regional distributors consolidate purchasing power. Developer-driven construction in India exhibits highest price sensitivity; Passivhaus-certified commercial towers in Germany and Austria demonstrate lowest sensitivity due to lifecycle energy cost optimization.
Supply Chain Analysis
Inventory lead times for sputter-deposited low-emissivity coatings extend fabrication scheduling windows, pressuring just-in-time project delivery for unitized facade contractors. Supply concentrates in Germany, the United States, and Japan for float glass and coating technology; China dominates spacer bar extrusion and desiccant supply. Raw material dependencies include argon industrial gas, silver-based sputtering targets, and polyisobutylene primary sealants. Single-source vulnerability in noble gas refining creates input cost volatility. Distribution runs through regional glazing distributors for residential replacement volume and direct mill relationships for large commercial contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulated glass market sits in early-cycle expansion as net-zero building codes accelerate penetration of triple-glazed assemblies beyond Passivhaus-certified stock into mainstream commercial construction. F-Gas Regulation phase-out and evolving EN standards create sustained specification tailwinds for gas-filled alternatives.
For Market Incumbents: Consolidate warm-edge spacer technology licensing positions and captive argon filling capabilities to defend against emerging precision fabricators with validated psi-value documentation. Prioritize capacity addition in Chicago and London metropolitan corridors where retrofit project pipelines concentrate. Lock in long-term industrial gas supply agreements to mitigate argon price volatility exposure from German and United States production clusters. For New Entrants and Emerging Players: EN 1279 certification fast-track investment opens specification access in European replacement markets filtering out uncertified competitors. Target India's commercial construction evolution as BIS energy efficiency standards create first-mover positioning before incumbent coating technology holders establish regional plant density. Pursue partnership routes with facade engineering consultancies in London and Singapore to bypass general contractor gatekeeping. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fabricators with validated EN 1279 certification and documented warm-edge spacer psi-values over commodity assemblers lacking performance documentation. Long-term viability rests on coating equipment capex intensity creating durable barriers to mid-scale expansion. Monitor regional low-carbon procurement mandate adoption across Denmark, the Netherlands, and France as inflection indicator for embodied-carbon tracking premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Warm-Edge Spacer Technology Licensing | Validates psi-value performance for Passivhaus certification compliance in Germany and Austria. |
| Regional Capacity Expansion | Captures metropolitan retrofit corridor demand in Chicago and London with localized fabrication. |
| Long-Term Argon Supply Agreement | Secures industrial gas input cost stability against German and United States production concentration. |
| Facade Engineering Consultancy Partnership | Bypasses general contractor channel control through specification authority delegation in Singapore. |
| EN 1279 Certification Investment | Filters competitive access in European replacement markets through validated argon retention protocols. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with facade engineering consultants, envelope commissioning agents, glazing procurement managers at commercial contractors, and technical directors at coating equipment manufacturers; alongside secondary validation through customs trade data, SEC 10-K filings of integrated glass groups, EN certification registry databases, and BIS energy efficiency standard documentation. Bottom-up unit volume estimates triangulated against top-down construction spend allocation models.
Across the projection horizon, the analytical framework modeled segmentation across product architecture, building typology, specification channel, and regional regulatory cluster. CAGRs derived from construction cycle timing, code adoption velocity, and replacement rate assumptions. Forecast inputs incorporated Passivhaus-certified building stock growth, F-Gas Regulation phase-out schedules, and metropolitan retrofit corridor project pipeline tracking.
Decision-makers should treat outputs as directional under base assumptions of sustained energy code tightening and stable industrial gas supply; material deviation in regulatory enforcement or argon production concentration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Block Market
Glass
Flexible Glass Market
Glass
Insulating Glass Market
Glass
North America Industrial Silica Sand Market
Glass
Pharmaceutical Glass Tubing Market
Glass
Metallic Glass Market
Glass
Technical Glass Market
Glass
Tinted Glass Market
Glass
Double Glazing Glass Market
Glass
Porous Glass Market
Glass
Asia Pacific Flexible Glass Market
Glass
Coated Glass Market
Glass
Crystalware and Glassware Market
Glass
Laboratory Glassware Market
Glass
Global Silicone Structural Glazing Market
Glass
Impact Resistant Glass Market