
 Latin America Flat Glass Market | 2026-2036
Latin America Flat Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Flat Glass Market Foresight
Commercial contractors are gaining procurement influence while residential developers lose relative share as demand is bifurcating across Latin America's flat glass value chain. Saint-Gobain leverages its integrated float-glass and coating operations to dominate premium architectural specifications in São Paulo and Mexico City. Vitro Architectural Glass anchors North American export channels through its Monterrey manufacturing base. Sisecam Group competes aggressively on tempered and laminated auto-glass contracts with Turkish production economics.
Flat glass consists of soda-lime silica sheets produced through the float process, achieving thickness tolerances between 2 mm and 25 mm for optical clarity and mechanical load-bearing. Its primary purpose spans transparent building envelopes, vehicle windshields, and solar thermal collectors requiring controlled light transmission and thermal insulation. Tempered glass leads volume in automotive safety applications where fragmentation resistance is mandatory, while coated glass commands the fastest growth as low-emissivity specifications penetrate green-certified commercial construction. Insulated glass units concentrate margin pools in high-rise curtain wall projects across Santiago and Bogotá, where thermal bridging regulations have tightened.
Brazil's ABNT efficiency standards, Mexico's CONUEE commercial building codes, and Colombia's RETIQ labeling requirements collectively reshape product certification pathways and import compliance costs across the region. ANATEL in Brazil and IFIET in Mexico additionally govern electromagnetic transparency for smart-glass and embedded electronics applications. Stakeholders must monitor how national energy agencies synchronize thermal performance thresholds with automotive safety mandates to avoid stranded inventory in cross-border distribution channels.
Market Dynamics
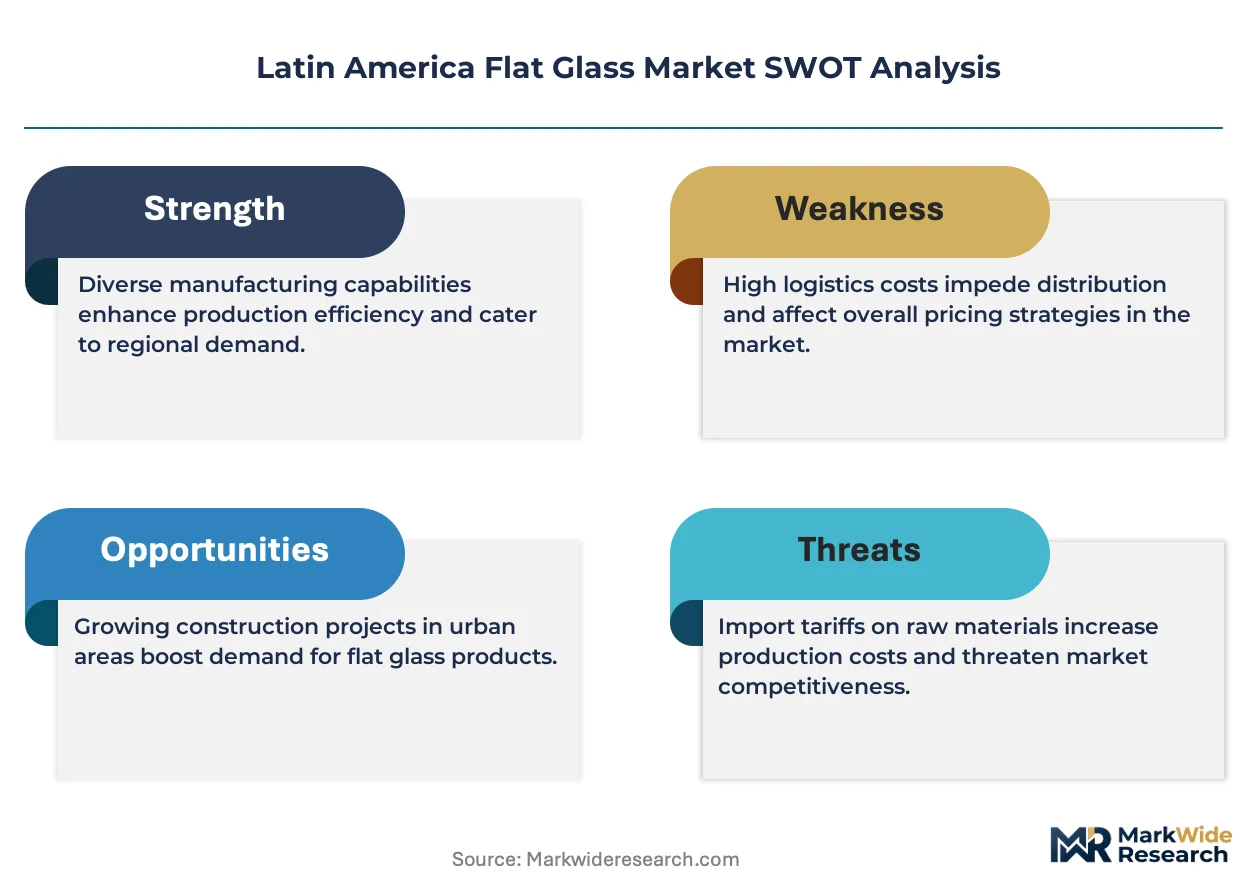
Energy-efficiency mandates across Brazil, Mexico, and Colombia are compressing product certification timelines while concentrating procurement authority among large commercial contractors with technical compliance capabilities.
Growth Catalysts
- CONUEE commercial codes:Mexico's updated building efficiency standards mandate low-emissivity glazing for new commercial construction above 2,000 square meters, pulling coated glass specifications into mainstream architectural procurement.
- Automotive glass fabrication:Cross-border OEM supply chains in Mexico's northern industrial corridor sustain tempered and laminated capacity expansion, with glass processors co-locating near assembly plants to compress logistics costs.
- ABNT efficiency standards:Brazil's national building code revisions now require thermal performance documentation for facade glazing, creating certification-driven demand premiums for insulated glass units in São Paulo high-rise development.
Market Restraints
- Soda ash input volatility:Flat glass production depends on synthetic soda ash imports from US Gulf Coast producers, exposing Mexican and Brazilian float lines to freight rate spikes and currency translation pressure.
- Float-glass supply concentration:The region's limited number of operational float tanks—concentrated in São Paulo state and Nuevo León—creates bottleneck risk during unplanned maintenance or natural gas supply interruptions.
- RETIQ compliance friction:Colombia's labeling requirements for thermal performance add 4-6 month pre-market validation timelines, disadvantaging imported products against domestic fabricators with established testing relationships.
Strategic Opportunities
- Smart-glass integration:Electrochromic and thermochromic glazing technologies are converging with building management systems, opening specification channels in Santiago and Bogotá premium commercial towers where ANATEL electromagnetic transparency certification is becoming standard.
- Chilean mining corridor:Underpenetrated industrial glazing demand from copper and lithium processing facilities in Antofagasta and Atacama regions offers specialized tempered glass contracts for chemical-resistant applications.
- Solar thermal collectors:Argentina's renewable energy incentives and distributed generation frameworks are pulling high-transmission solar glass into agricultural and industrial thermal process applications outside traditional construction channels.
Industry Challenges
- Coating technician scarcity:Vacuum deposition and sputtering expertise for low-emissivity and solar control coatings remains concentrated among senior technicians at legacy operations, constraining new line commissioning and quality consistency.
- IFIET electromagnetic certification:Smart-glass products with embedded conductive layers face extended validation timelines with Mexico's telecommunications regulator, compressing product launch windows against unregulated conventional alternatives.
- Float line reconfiguration capex:Transitioning existing capacity from clear to tinted or coated glass requires furnace chemistry modifications and tin bath adjustments demanding 18-24 month capital commitments with uncertain demand confirmation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Flat Glass Market |
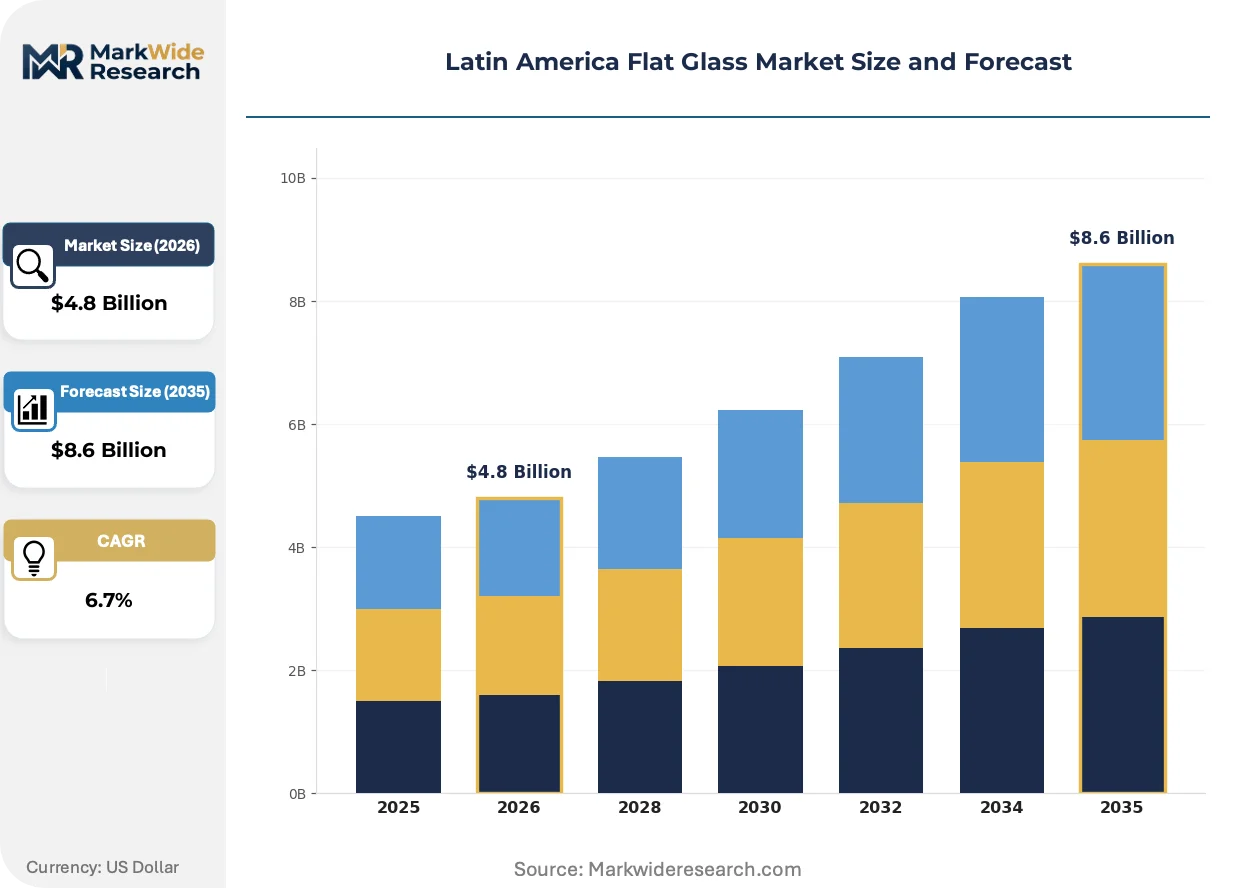
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Insulated Glass, Coated Glass Application: Construction, Automotive, Furniture, Electronics End User: Manufacturers, Contractors, Distributors, Retailers Distribution Channel: Direct Sales, Online Retail, Wholesalers, Showrooms |
| Companies Covered | SCHOTT AG, Flat Glass Group, AGC Inc., Central Glass, Cevital, Saint-Gobain, Guardian Glass, Sisecam Group, Vitro Architectural Glass, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Flat Glass Market Shifts & Advancements
Product specification authority is migrating from general contractors to specialized glazing subcontractors with energy modeling capabilities, while coating technologies and digital integration reshape competitive differentiation.
Low-emissivity coating stacks are bifurcating the architectural glass market. Double-silver and triple-silver sputtered coatings deliver thermal performance values below 0.25 U-factor, enabling compliance with Brazil's ABNT and Mexico's CONUEE stringent commercial codes. Large commercial contractors in São Paulo and Mexico City now specify these coatings as baseline for green-certified projects, compressing market share for single-silver and pyrolytic alternatives in premium segments.
Brazil's ANATEL electromagnetic transparency standards are reshaping smart-glass product development pathways. The regulation mandates specific attenuation limits for glazing with embedded antennas, sensors, or conductive traces, forcing fabricators to pre-validate designs with certified testing laboratories. Automotive and commercial building segments deploying connected glazing are absorbing 6-9 month pre-market timelines, with compliance costs concentrating procurement among vertically integrated suppliers with in-house certification capabilities.
Specification authority is consolidating among glazing subcontractors with energy modeling software and thermal bridge calculation expertise. General contractors in Santiago and Bogotá are ceding envelope design decisions to specialized firms certified in RETIQ and local thermal performance documentation, replacing traditional arm's-length material procurement. This channel shift elevates technical consultation over price competition in curtain wall and high-performance facade projects.
Latin America Flat Glass Market Segmentation
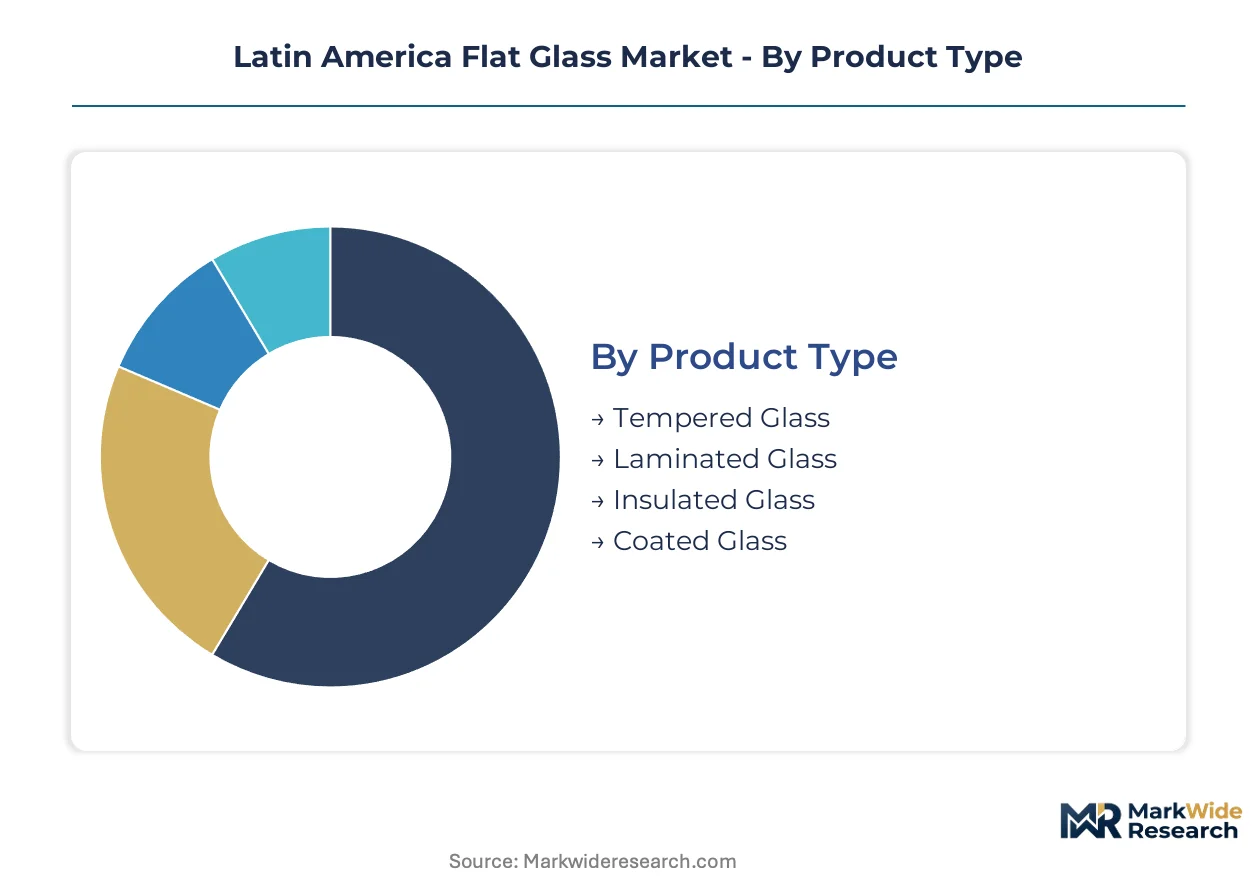
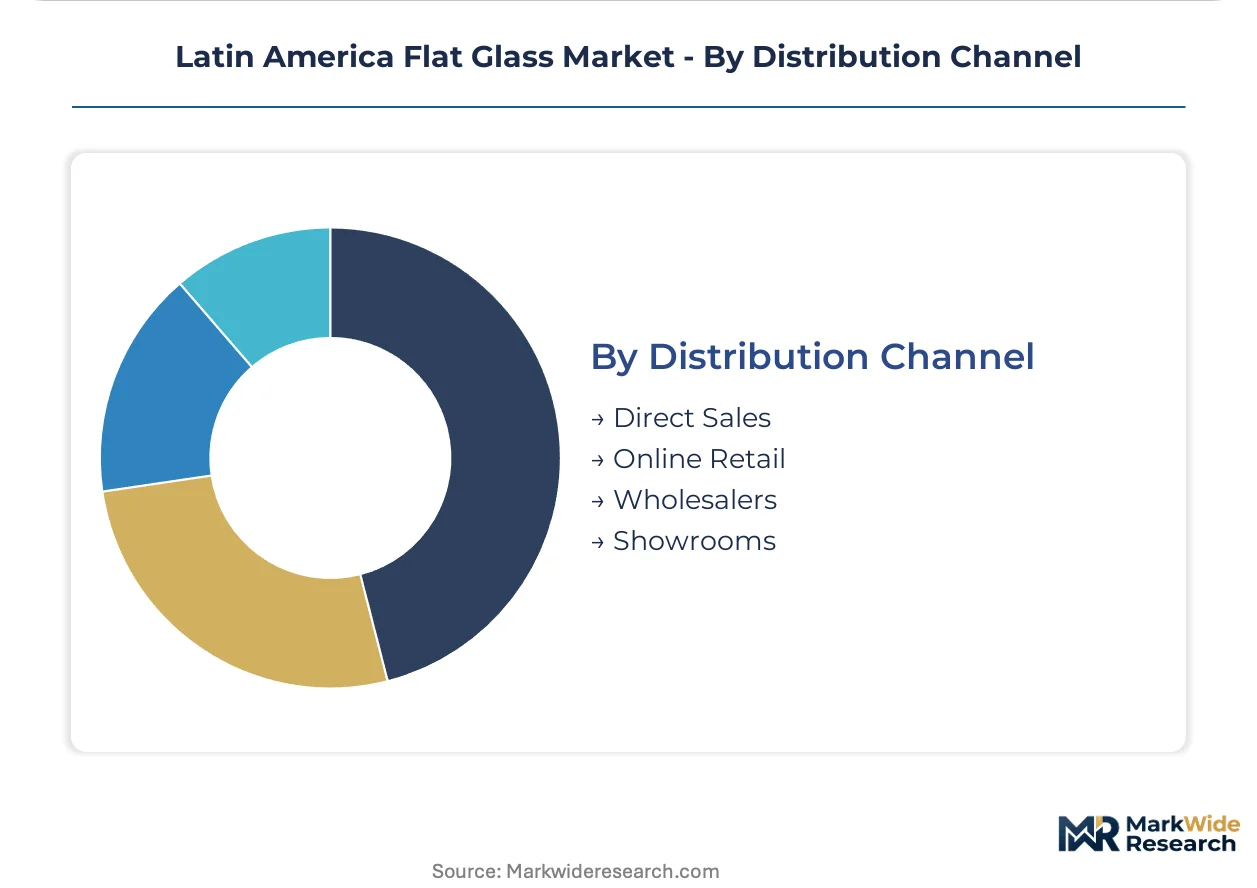
Segmentation reveals how procurement authority concentrates among specialized glazing contractors in Latin America's flat glass value chain. Channel differentiation separates premium architectural specifications from commodity construction supply.
Product Type:
Channel mix varies sharply by product type, with coated and insulated glass flowing through specification-driven design-build channels while tempered glass moves through automotive OEM direct procurement.
- Tempered Glass:Heat-treated soda-lime silica with surface compression exceeding 69 MPa delivers fragmentation resistance for vehicle windshields and architectural safety glazing. Mexican automotive processors in Nuevo León and Chihuahua dominate procurement volume through just-in-time supply contracts with cross-border OEM assembly plants.
- Coated Glass:Sputtered metal-oxide stacks achieve thermal emissivity below 0.25 for ABNT and CONUEE compliance. São Paulo commercial contractors specify double-silver and triple-silver coatings as baseline for green-certified high-rise envelopes, pulling this segment through specialized glazing subcontractors with energy modeling capabilities.
- Laminated Glass:Polyvinyl butyral interlayers bond glass plies for acoustic dampening and post-breakage retention in hurricane-resistant facades.
- Insulated Glass:Hermetically sealed dual-pane units with argon fill concentrate margin pools in Bogotá and Santiago curtain wall projects where thermal bridging regulations have tightened.
Tempered glass dominates installed base. Coated glass is where expansion concentrates.
Application:
Cost tier segmentation separates premium building envelope specifications from commodity residential window replacement demand.
- Construction:Commercial facade glazing commands highest unit values through performance-certified specifications, with insulated and coated glass penetrating São Paulo and Mexico City green building projects. Residential developers in Brazil's southeast corridor absorb clear float glass through distributor channels at compressed margins.
- Automotive:Tempered and laminated safety glass for windshields, sidelites, and backlites flows through direct OEM supply chains concentrated in Mexico's northern industrial corridor.
- Furniture:Decorative tempered and acid-etched glass for interior applications moves through showroom and retailer channels with lower technical barriers.
- Electronics:High-transmission substrates for displays and solar thermal collectors serve specialized industrial demand in Argentina's agricultural processing regions.
Construction commands revenue concentration. Automotive is where volume expansion accelerates.
End User:
Customer type determines technical service intensity, with manufacturers and contractors absorbing compliance documentation burdens that exclude smaller distributors.
- Manufacturers:Automotive glass fabricators and architectural glazing subcontractors in Monterrey and São Paulo procure raw float glass and coating services at scale, managing ANATEL and CONUEE certification pathways internally.
- Contractors:Large commercial envelope specialists in Santiago and Bogotá consolidate specification authority, displacing general contractors through energy modeling and thermal bridge calculation expertise.
- Distributors:Regional stocking intermediaries serve residential replacement demand with limited technical support.
- Retailers:Showroom and big-box channels handle small-lot furniture and decorative glass with minimal certification requirements.
Manufacturers anchor volume procurement. Contractors are where margin capture concentrates.
Distribution Channel:
Supply concentration shapes channel economics, with direct sales capturing premium architectural specifications while wholesalers absorb price-sensitive residential volume.
- Direct Sales:Vertically integrated producers and large fabricators serve automotive OEMs and major commercial contractors through dedicated account management, compressing logistics costs in Mexico's northern industrial corridor.
- Wholesalers:Regional distributors stock standard thickness clear float and tempered glass for residential construction and replacement demand across Brazil's interior states.
- Showrooms:Architectural glazing specialists in São Paulo and Mexico City display coated and decorative product ranges for specification-driven commercial projects.
- Online Retail:Emerging digital channels handle small-lot decorative and furniture glass with limited penetration in technical architectural segments.
Direct sales dominate premium specification flow. Wholesalers capture residential volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's northern industrial corridor exports tempered and laminated automotive glass to US-based OEM assembly plants, while Brazil ships coated architectural products to neighboring Mercosur markets. Cross-border supply chains concentrate procurement authority in border-adjacent fabrication clusters.
Brazil
São Paulo state hosts the region's densest float-glass manufacturing base, serving green-certified commercial construction across the southeast corridor. ABNT efficiency standards mandate thermal performance documentation for facade glazing, elevating demand premiums for insulated glass units. High-rise envelope specialists in São Paulo and Rio de Janeiro now specify double-silver low-emissivity coatings as baseline for new commercial towers.
Mexico
Automotive glass processors in Nuevo León and Chihuahua sustain capacity expansion through just-in-time supply contracts with cross-border OEM assembly plants. CONUEE commercial building codes mandate low-emissivity glazing for new construction above 2,000 square meters, pulling coated specifications into mainstream architectural procurement. Monterrey anchors both automotive fabrication clusters and premium architectural coating operations serving Mexico City specifications.
Colombia
Bogotá's curtain wall projects concentrate margin pools for insulated glass units as thermal bridging regulations tighten in high-rise commercial development. RETIQ labeling requirements for thermal performance add 4-6 month pre-market validation timelines, advantaging domestic fabricators with established testing relationships. The Andean capital's glazing subcontractors now consolidate specification authority through energy modeling and thermal bridge calculation expertise.
Chile
Santiago premium commercial towers drive specification demand for electrochromic and thermochromic glazing integrated with building management systems. ANATEL electromagnetic transparency certification is becoming standard for smart-glass deployments, forcing 6-9 month pre-market validation timelines. The underpenetrated mining corridor in Antofagasta and Atacama regions offers specialized tempered glass contracts for chemical-resistant industrial applications.
Argentina
Renewable energy incentives and distributed generation frameworks pull high-transmission solar glass into agricultural and industrial thermal process applications outside traditional construction channels. Buenos Aires province hosts the primary distribution infrastructure serving interior agricultural processing regions. Local fabricators face compressed margins competing against Brazilian and Chilean imports for standard architectural specifications.
Latin America Flat Glass Market Competitive Landscape
Player mix skews toward integrated multinational producers with captive float-glass and coating operations. Market structure concentrates procurement influence among three to four vertically positioned suppliers controlling premium architectural specifications and automotive OEM channels. Strategic archetypes separate integrated float-coating operators, automotive-focused tempering specialists, and regional distribution-oriented fabricators. Dominant competitive moves include furnace chemistry modifications for tinted and coated product transitions, and co-location strategies near OEM assembly plants to compress logistics costs.
Among integrated multinational operators, Saint-Gobain, Vitro Architectural Glass, and Sisecam Group occupy positions spanning premium architectural and automotive segments. Saint-Gobain exemplifies the float-coating integration archetype through operations anchored in São Paulo and Mexico City specification channels. Vitro Architectural Glass represents the North American export linkage model, with Monterrey manufacturing serving cross-border supply chains. Sisecam Group sits within the automotive tempering specialist tier, competing on Turkish production economics for laminated and tempered safety glass contracts.
| Leading Market Players |
|---|
| SCHOTT AG |
| Flat Glass Group |
| AGC Inc. |
| Central Glass |
| Cevital |
| Saint-Gobain |
| Guardian Glass |
| Sisecam Group |
| Vitro Architectural Glass |
| Others |
Supply & Pricing Matrix
Synthetic soda ash substitution for natural trona-based inputs is rerouting procurement toward US Gulf Coast suppliers while compressing margin structures for Mexican and Brazilian float-glass producers exposed to freight rate volatility and currency translation pressure.
Pricing Analysis
Double-silver and triple-silver low-emissivity coatings command 40-60% premiums over single-silver and pyrolytic alternatives, creating a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on CONUEE and ABNT certification tiers plus volume scale commitments from large commercial contractors in São Paulo and Mexico City. Cost compression in standard clear float glass is intensifying because Brazilian distributors absorb excess Chinese import volume. Residential replacement buyers in Brazil's interior states exhibit highest price sensitivity, while green-certified high-rise developers in Santiago and Bogotá demonstrate lowest sensitivity due to performance documentation mandates.
Supply Chain Analysis
Port congestion at Santos and Manzanillo is elevating inbound logistics costs for US-origin synthetic soda ash and specialty coating precursors, with container availability tightening on the Houston-Veracruz trade lane. Geographic supply concentrates in Brazil, Mexico, and Turkey, with Sisecam's Turkish operations feeding automotive tempering contracts across Latin America. Raw material dependencies center on synthetic soda ash, tin metal for float baths, and silver sputtering targets for low-emissivity stacks. Single-source vulnerability persists for US Gulf Coast soda ash supply to Mexican float lines. Distribution runs through direct sales channels for automotive OEMs and large commercial contractors, with regional wholesalers absorbing residential construction volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's flat glass market is recovering from a cyclical trough driven by construction permit normalization in Brazil and Mexico following post-pandemic regulatory backlogs.
For Market Incumbents: Shield margin pools in premium architectural specifications by accelerating furnace chemistry modifications for tinted and coated glass transitions before demand confirmation solidifies. Defensive consolidation of coating technician training programs addresses capability scarcity threatening new line commissioning. Prioritize captive supply of sputtering targets and silver inputs to reduce exposure to precious metal price volatility.
For New Entrants and Emerging Players: Lead with specialized tempered glass contracts for Chile's underpenetrated mining corridor in Antofagasta and Atacama, where chemical-resistant industrial applications command technical premiums. Argentina's agricultural solar thermal collector segment offers white-space penetration outside traditional construction channels. Establish co-location partnerships with distributed generation installers rather than competing through conventional distributor networks.
For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors vertically integrated float-coating operators with established ANATEL and CONUEE certification capabilities. Long-term viability across the projection horizon hinges on regulatory synchronization between energy efficiency mandates and automotive safety standards. Monitor IFIET electromagnetic certification timeline compression as the inflection signal for smart-glass specification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Chemistry Modification | Enables tinted and coated glass transitions for ABNT and CONUEE compliance in São Paulo and Mexico City. |
| Backward Integration into Soda Ash | Reduces exposure to US Gulf Coast freight volatility and currency translation pressure for Mexican producers. |
| Coating Technician Training Programs | Addresses vacuum deposition expertise scarcity constraining new low-emissivity line commissioning. |
| Smart-Glass ANATEL Pre-Validation | Compresses 6-9 month electromagnetic transparency timelines for Santiago premium commercial tower specifications. |
| Mining Corridor Tempering Capacity | Captures specialized chemical-resistant contracts in Chile's Antofagasta and Atacama lithium processing regions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with float-glass plant managers, architectural glazing subcontractors, automotive OEM procurement teams, and coating technology specialists. Secondary validation drew from ANATEL certification databases, CONUEE building code filings, customs trade records for soda ash imports, and SEC disclosures from publicly traded glass manufacturers. Bottom-up volume estimates from individual production facilities were triangulated against top-down construction permit and automotive production forecasts.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, application segment, end-user category, and distribution channel, with additional segmentation by national regulatory cluster. CAGRs were derived from regression analysis of historical permit issuance, OEM production schedules, and energy efficiency code adoption curves. Industry-specific inputs included float tank capacity utilization rates, natural gas price indices for furnace operations, and low-emissivity coating penetration rates by building certification tier.
The analysis sits within stated boundaries; outcomes outside sustained construction permit growth in Brazil and Mexico or stable natural gas supply to São Paulo and Nuevo León float lines would require recalibration. Practitioners should keep alternative scenarios live as ANATEL and IFIET electromagnetic certification timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Silica Sand Market
Glass
Glass Lined Equipment Market
Glass
Flexible Glass Market
Glass
Asia-Pacific Glassware Market
Glass
Screen-Printing Glass Market
Glass
Solar Reflective Glass Market
Glass
Glass Mat Thermoplastic Market
Glass
Glass Vials Market
Glass
Fiberglass Window Market
Glass
3D Glass Substrate Market
Glass
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market
Glass
France Silica Sand Market
Glass
Metallic Glass Market
Glass
Tempered Glass Market
Glass
Global Glassware Market
Glass
Silica Sol Market