
 Europe Glassware Market | 2026-2036
Europe Glassware Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Glassware Market Intelligence
The shift towards high-clarity, lead-free crystal glassware is redrawing the competitive landscape in the European premium tableware segment. Zwiesel Kristallglas AG leverages its specialization in Tritan crystal technology to capture this high-margin market. Meanwhile, Arc International S.A. competes across multiple price points with its extensive manufacturing scale in soda-lime glass. Bormioli Rocco S.p.A. differentiates through its focus on Italian design and innovative material treatments for both household and professional use.
European glassware encompasses a range of vitrified silicate products, formed through processes like blowing, pressing, or drawing molten glass. Its primary function spans from food and beverage containment in tableware to specialized applications in scientific institutions requiring borosilicate glass for thermal shock resistance. Within product types, tableware holds the largest share, while laboratory glassware, particularly borosilicate variants, offers higher margins. Distribution is increasingly moving towards online retail channels, complementing traditional sales through specialty stores and hotels.
Market access in Europe is governed by strict regulations, including CE marking for products intended for food contact. The EU's REACH regulation also constrains the use of certain substances like lead in crystal glass, influencing material formulation. Producers must now navigate the dual pressures of material compliance under these frameworks while meeting consumer demand for sustainable, recyclable products.
Market Dynamics
The European glassware market's trajectory is defined by the convergence of strict EU food contact safety regulations and escalating demand from the hospitality sector for durable, aesthetically superior, and compliant tableware. This dual pressure accelerates material and design innovation.
Growth Catalysts
- Hospitality Sector Expansion:Renewed investment in Europe's hotel, restaurant, and catering (HoReCa) industries, especially in premium establishments within Germany and France, fuels demand for high-quality, durable crystal and soda-lime tableware.
- Sustainability Mandates:The EU Green Deal and consumer preferences for circularity favor glass, a fully recyclable material, over single-use plastics for food and beverage packaging, creating new volume opportunities.
- Specialized Material Development:Advances in borosilicate glass formulations for laboratory and technical applications provide high-margin growth avenues, driven by Europe's robust pharmaceutical and chemical research sectors.
Market Restraints
- Energy Cost Volatility:The energy-intensive nature of glass melting furnaces exposes European manufacturers to significant operational cost fluctuations, impacting price stability and profitability, especially in Germany's industrial sector.
- Regulatory Compliance Burden:Navigating and documenting compliance with the EU's REACH and CE marking frameworks for food-safe products represents a substantial administrative and financial hurdle for small and mid-sized enterprises.
- Low-Cost Import Competition:The market for standard, mass-produced soda-lime glassware faces intense price pressure from manufacturers in regions with lower energy and labor costs, threatening domestic European production volumes.
Strategic Opportunities
- Eastern European Market Penetration:The developing hospitality and retail sectors in countries across Eastern Europe represent an underserved market for premium and design-differentiated glassware products from established European brands.
- Direct-to-Consumer Channels:Building out brand-owned e-commerce platforms allows producers to capture higher margins, control brand messaging, and access a wider consumer base for specialized or artisanal glassware collections.
- Functional Material Innovation:There is an opportunity to develop glassware with value-added properties, such as enhanced thermal shock resistance for culinary use or antimicrobial surfaces for healthcare and public-facing environments.
Industry Challenges
- Artisanal Skill Scarcity:Preserving and transferring the specialized skills required for mouth-blown and handcrafted glassware is a critical challenge, as the pool of master glassblowers diminishes across traditional European production centers.
- Capital-Intensive Modernization:Upgrading production facilities to incorporate energy-efficient furnaces and automated inspection systems requires significant capital expenditure to meet both sustainability targets and quality control demands.
- Recycled Cullet Sourcing:Securing a consistent supply of high-purity, color-sorted recycled glass (cullet) is a logistical challenge that can constrain the ability of manufacturers to meet their circular economy objectives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Glassware Market |
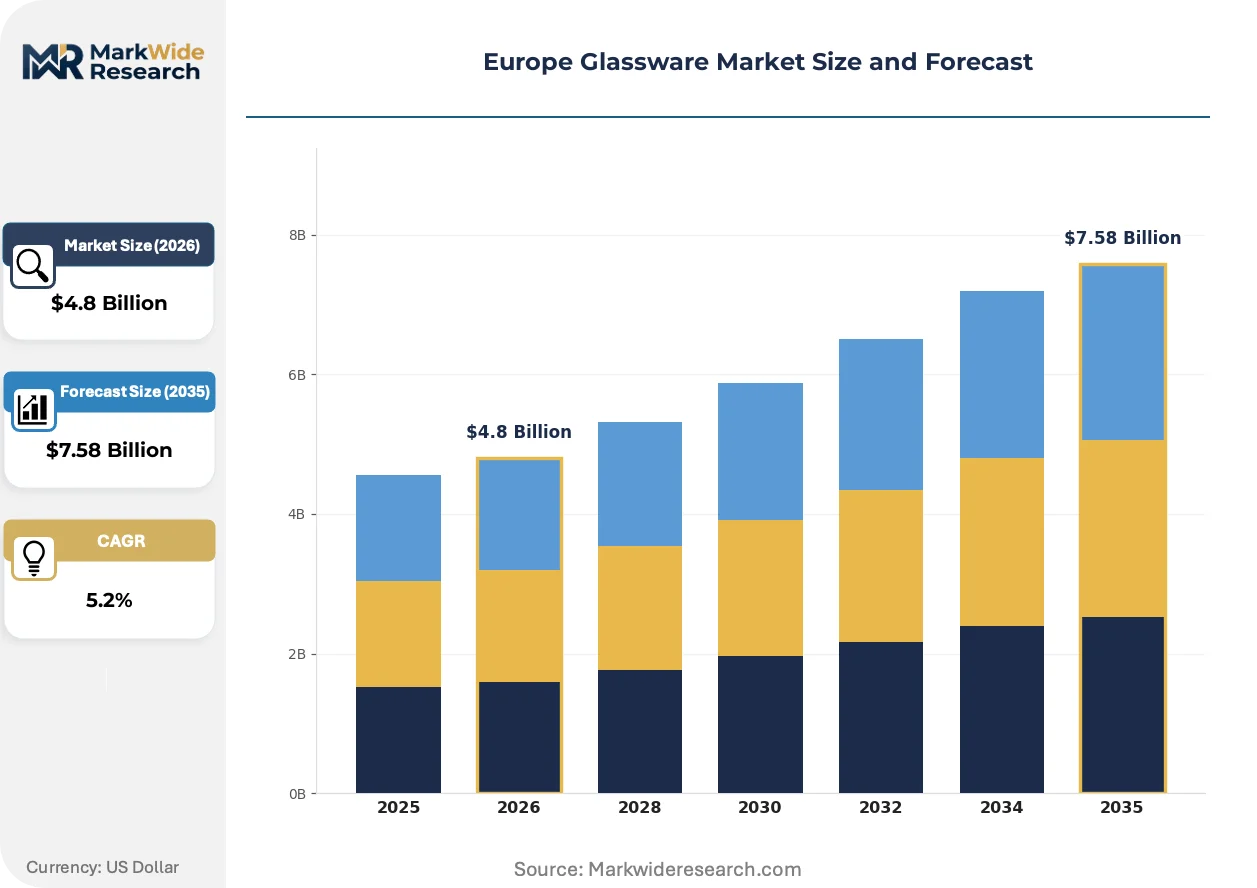
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tableware, Cookware, Laboratory Glassware, Decorative Glass Material: Lead Crystal, Soda-lime Glass, Borosilicate Glass, Tempered Glass End User: Household, Restaurants, Hotels, Scientific Institutions Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | O-I Glass, Inc., Arc International S.A., Verallia S.A, Duralex International S.A.S., Bormioli Rocco S.p.A., Gerresheimer AG, Stoelzle Oberglas GmbH, Zwiesel Kristallglas AG, Vidrala, S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Glassware Market Strategic Shifts & Innovations
Material science innovation is intersecting with circular economy principles, fundamentally altering product design and manufacturing priorities in the European glassware market. This shift forces producers to balance performance enhancements with sustainability mandates from both regulators and consumers.
Lead-free crystal formulations, such as those using titanium oxide, provide enhanced durability, dishwasher resistance, and high clarity. The European hotel and restaurant industry is adopting this material for premium beverage service to reduce breakage and elevate guest experience. This adoption is bifurcating the tableware market, creating a distinct high-performance segment separate from conventional soda-lime or leaded crystal products.
The EU’s REACH regulation continues to tighten restrictions on substances of very high concern, including lead oxide in crystal glass. This regulatory pressure compels manufacturers to reformulate products, investing heavily in R&D to create lead-free alternatives that do not sacrifice brilliance or acoustic properties. The high-end decorative and stemware categories are most affected, with compliance becoming a critical benchmark for market access in Germany and France.
A significant behavioral change is the rise of direct-to-consumer (D2C) sales through brand websites and curated online platforms. This model disrupts the traditional distribution path through specialty retailers and wholesalers, particularly for design-led and artisanal glassware. This shift is most visible within the household segment across Western Europe, allowing Italian and Scandinavian brands to engage directly with end-users.
Europe Glassware Market Segmentation
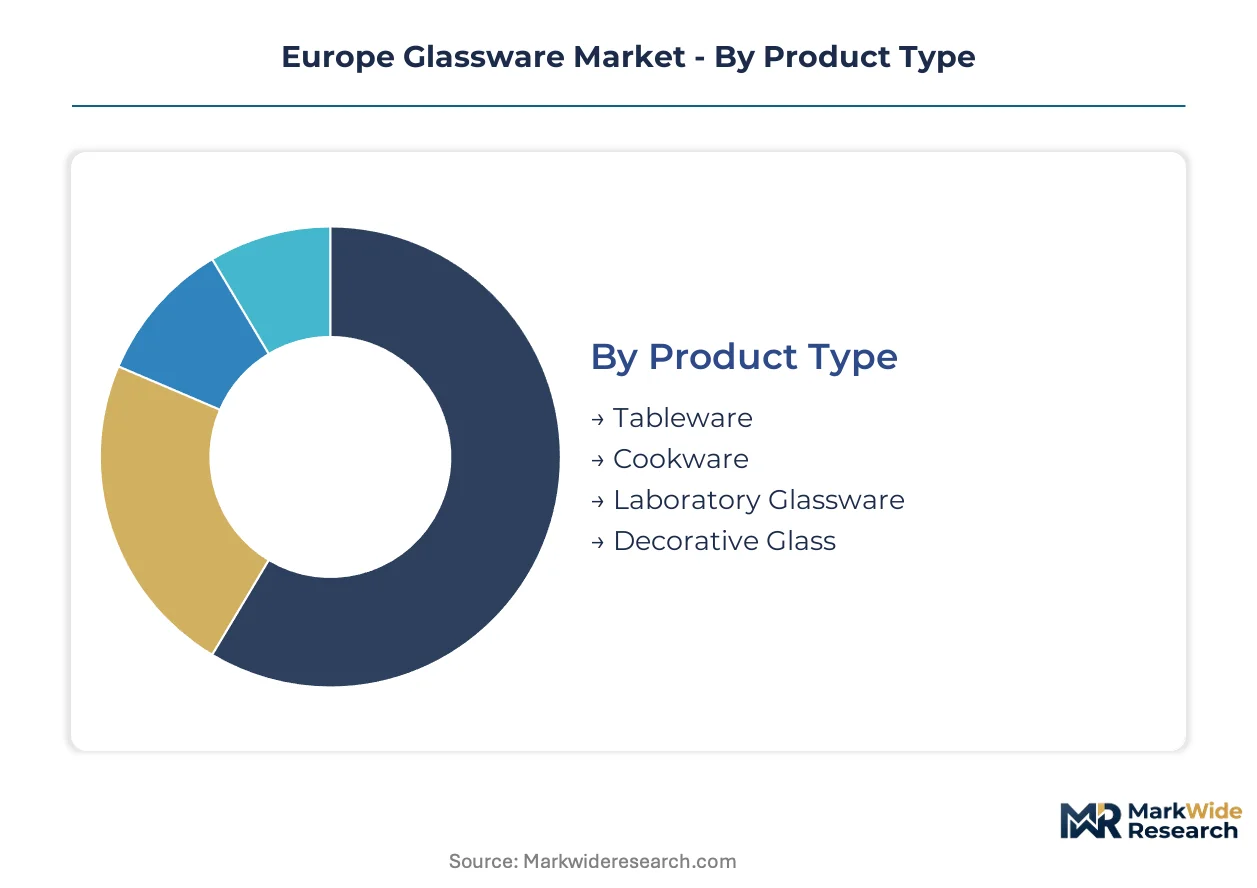
Understanding the Europe glassware market through granular segmentation reveals the varied demand drivers and competitive dynamics across different product categories and end-user applications. This detailed breakdown highlights where innovation is most critical and where established product lines face evolving market pressures.
Product Type:
Substitution pressure is most pronounced in the utilitarian segments of the glassware market, where alternative materials or lower-cost imports can readily replace traditional glass products.
- Tableware:This segment includes glasses, plates, and serving dishes used for food and beverage consumption in both domestic and commercial settings. Demand in Germany's hospitality sector drives innovation in lead-free crystal formulations for enhanced durability and aesthetic appeal.
- Laboratory Glassware:Comprising beakers, flasks, and test tubes, this category demands precision and chemical inertness, often using borosilicate glass for its thermal shock resistance. Europe's robust pharmaceutical and chemical research sectors in countries like Switzerland and Germany fuel consistent, high-margin demand.
- Cookware:Glass cookware, such as baking dishes and casseroles, offers heat resistance and visual appeal for food preparation and serving. Household demand across Western Europe values its non-reactive properties and ease of cleaning.
- Decorative Glass:This segment encompasses vases, figurines, and ornamental items, emphasizing aesthetic design and artisanal craftsmanship. Consumer preferences for unique home decor items support smaller, specialized producers in Italy and Scandinavia.
Tableware anchors the volume base while Laboratory Glassware gains share at the steepest rate.
Material:
Margin differentiation among materials reflects both production complexity and performance characteristics, with specialized glass types commanding higher price points due to their unique properties.
- Soda-lime Glass:This is the most common and economical glass type, widely used for mass-produced bottles, jars, and standard tableware due to its ease of manufacturing. Arc International S.A. utilizes its extensive scale in this material to serve broad market segments across Europe.
- Borosilicate Glass:Known for its superior thermal shock resistance and chemical durability, borosilicate glass is crucial for laboratory equipment and high-performance cookware. Demand from scientific institutions and specialized culinary applications in Germany and France underpins its premium positioning.
- Lead Crystal:Traditionally valued for its brilliance and acoustic properties, lead crystal contains lead oxide, which enhances its refractive index. Stricter EU REACH regulations are compelling manufacturers to reformulate products, affecting high-end decorative and stemware categories.
- Tempered Glass:This material undergoes a thermal or chemical treatment to increase its strength and safety, making it resistant to breakage and shattering. Its use in durable tableware and architectural applications responds to safety and longevity requirements in public and commercial spaces.
Soda-lime Glass forms the foundational material segment, while Borosilicate Glass is expanding most quickly due to specialized demand.
End User:
Demand stability varies significantly across end-user segments, with institutional buyers often providing more predictable procurement patterns compared to fluctuating consumer preferences.
- Hotels:The European hotel sector, particularly premium establishments, drives significant demand for durable, aesthetically superior, and compliant glassware for guest rooms and dining services. Renewed investment in hospitality across Germany and France directly impacts this segment.
- Scientific Institutions:Universities, research laboratories, and pharmaceutical companies require specialized borosilicate glassware for experiments and material analysis. Europe's robust research and development ecosystem ensures consistent, high-value demand for precision glass products.
- Household:Individual consumers purchase glassware for daily use in kitchens and dining areas, driven by trends in home decor, personal preferences, and affordability. Online retail channels increasingly cater to this segment across Western Europe.
- Restaurants:Similar to hotels, the restaurant and catering (HoReCa) industry demands a steady supply of functional and presentable glassware for beverage service and food presentation. European food service trends influence material choices for durability and design.
The Household segment provides the broadest consumer base, while Scientific Institutions are climbing the fastest in terms of specialized procurement.
Distribution Channel:
Market reach through distribution channels is undergoing a transformation, with digital platforms extending accessibility beyond traditional brick-and-mortar outlets and wholesale networks.
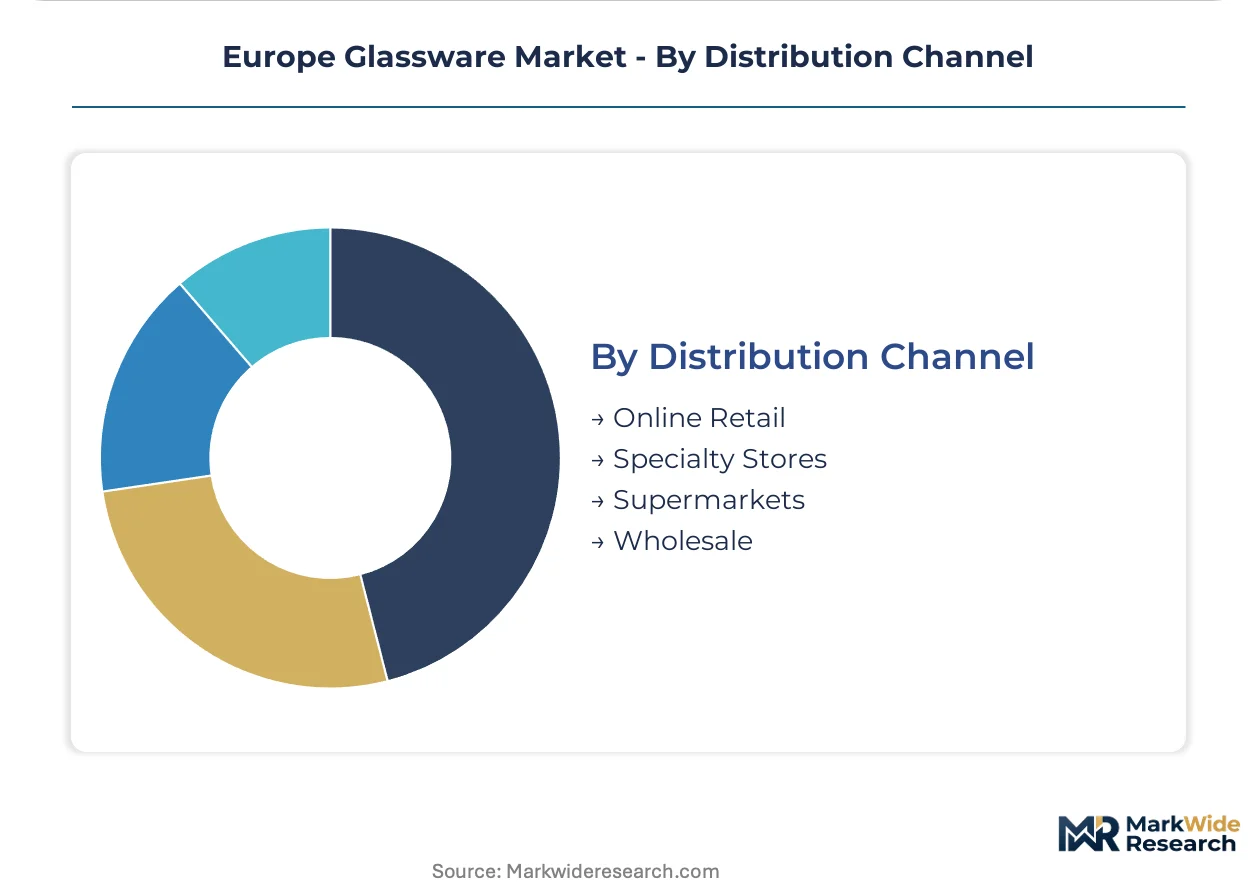
- Online Retail:E-commerce platforms, including brand-owned websites and large marketplaces, enable direct sales to consumers, offering a wider selection and often specialized or artisanal products. This channel is gaining significant traction across Western Europe for design-led glassware.
- Specialty Stores:These retailers focus on curated collections of high-quality, often premium or artisanal glassware, providing expert advice and a tactile shopping experience. They remain important for luxury and gift segments, particularly in urban centers.
- Supermarkets:Mass-market retailers offer a convenient option for everyday glassware, focusing on affordability and accessibility for a broad consumer base. This channel primarily serves the household segment with standard soda-lime glass products.
- Wholesale:This channel supplies large volumes of glassware to businesses, including hotels, restaurants, and other retail outlets, often through bulk purchasing agreements. Wholesale operations manage logistics for significant commercial clients across Europe.
Supermarkets maintain a broad volume base, while Online Retail shows the steepest expansion trajectory in consumer reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's specialized glassware manufacturers export high-clarity products across Europe, establishing a significant trade corridor. This cross-border commerce supports premium hospitality sectors in neighboring countries. The sustained demand for durable, aesthetically superior tableware drives this European market activity.
Germany
Germany's robust hospitality sector, particularly premium hotels and restaurants, drives demand for durable, high-quality tableware. Compliance with EU REACH regulations for lead-free crystal is a critical factor for domestic producers. The Bavarian region concentrates high-end glassware manufacturing, focusing on innovation in material science.
France
France exhibits strong demand for sophisticated glassware in its renowned culinary and luxury dining segments. Strict CE marking requirements ensure product safety and quality for food contact applications. Northern France features significant soda-lime glass production, catering to both domestic and export markets.
Italy
Italy's market values design-led glassware for household use, emphasizing aesthetic appeal and artisanal craftsmanship. The EU Green Deal influences production towards more sustainable and recyclable glass solutions. Tuscany supports numerous specialized decorative glass producers, catering to niche consumer preferences.
Poland
Poland represents an underserved market with developing hospitality and expanding retail sectors driving glassware consumption. Adherence to EU food contact material guidelines is essential for market entry and product acceptance. The Silesia region is a hub for mass-produced soda-lime glassware, serving both domestic and Eastern European markets.
Switzerland
Switzerland's scientific institutions and affluent consumer base generate demand for specialized borosilicate and premium household glassware. Swissmedic regulations govern the quality and safety of laboratory glassware used in pharmaceutical research. Basel's pharmaceutical research cluster consistently requires high-precision borosilicate glass for advanced applications.
Europe Glassware Market Key Industry Players
Listed leaders compete with private specialists across diverse price points and product specialization in the Europe glassware market. The market exhibits a tiered structure, from high-volume standard glass to artisanal premium crystal. Key strategic archetypes include large-scale industrial producers, design-focused premium brands, and technical glass innovators. Companies engage in material innovation and targeted geographic expansion to secure market share.
Within the premium and design-led segments, Arc International S.A. exemplifies broad market reach through extensive soda-lime glass manufacturing. Bormioli Rocco S.p.A. (Società per Azioni) occupies a position focused on Italian design and innovative material treatments for both household and professional use. Zwiesel Kristallglas AG, a German Aktiengesellschaft, represents specialization in high-margin Tritan crystal technology for the high-clarity, lead-free market.
| Leading Market Players |
|---|
| O-I Glass, Inc. |
| Arc International S.A. |
| Verallia S.A |
| Duralex International S.A.S. |
| Bormioli Rocco S.p.A. |
| Gerresheimer AG |
| Stoelzle Oberglas GmbH |
| Zwiesel Kristallglas AG |
| Vidrala, S.A. |
Cost & Logistics Intelligence
Long-term supply agreements between major glassware manufacturers and hospitality groups lock in both supply access and price visibility for high-volume orders across Europe. This structure provides stability against commodity price shifts for established players.
Pricing Analysis
The pricing gap between advanced lead-free crystal formulations and conventional soda-lime glass products defines market value. Premium-mid-economy pricing differentiation exists across product types and materials. Price differentiation stems from quality grade, particularly for Tritan crystal, and the level of CE marking compliance required for food contact. Pricing pressure intensifies for standard soda-lime glassware due to low-cost import competition. Household consumers demonstrate higher price sensitivity compared to scientific institutions procuring specialized borosilicate glass.
Supply Chain Analysis
Long inventory lead times for specialized borosilicate glass from European manufacturers highlight the bespoke nature of scientific procurement. Geographic supply concentration for glassware centers in Germany, France, and Italy, with Poland serving Eastern European markets. Raw material dependencies include high-purity silica sand, soda ash, and consistent supplies of recycled glass cullet. Energy cost volatility represents a significant structural risk for European glass melting operations. Distribution runs through a hybrid model, combining wholesale for commercial clients and rapidly expanding online retail for household consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a platform-economics inflection, driven by the evolving regulatory ecosystem around material compliance and circularity. Interoperability between material science innovation and sustainable manufacturing practices is crucial.
For Market Incumbents: Fortify core market positions by investing in energy-efficient furnace technologies to mitigate operational cost fluctuations. Develop next-generation lead-free crystal formulations that meet stringent EU REACH regulations, countering the threat of non-compliant imports. Expand automated inspection systems to ensure consistent product quality and reduce waste. Deepen vertical integration into recycled cullet processing to secure consistent feedstock supply.
For New Entrants and Emerging Players: Anchor in underserved Eastern European markets by offering design-differentiated and compliant glassware solutions for the developing hospitality sector. Target the growing direct-to-consumer channel across Western Europe with artisanal or specialized glassware collections. Leverage innovative material treatments, such as enhanced thermal shock resistance for culinary use, to create niche product categories. Focus on sustainable, fully recyclable product lines to align with consumer preferences and EU Green Deal mandates.
For Investors and Strategic Acquirers: Specialized borosilicate glass manufacturers with robust R&D pipelines for scientific and technical applications present compelling acquisition targets. These firms benefit from high-margin demand from Europe's pharmaceutical and chemical research sectors. Long-term viability depends on a strong intellectual property portfolio in material science and adherence to strict regulatory frameworks like Swissmedic. The signal to watch is the adoption rate of advanced borosilicate glass in new high-tech applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Lead-Free Crystal R&D | Ensures compliance with EU REACH regulations for high-end tableware and stemware. |
| Expand Direct-to-Consumer Channels | Captures higher margins and strengthens brand messaging for specialized glassware collections. |
| Modernize Production Facilities | Improves energy efficiency and reduces operational costs for glass melting furnaces. |
| Penetrate Eastern European Hospitality | Accesses developing markets with unmet demand for premium and design-led glassware. |
| Secure Recycled Cullet Supply | Supports circular economy objectives and reduces reliance on virgin raw materials for manufacturers. |
Research Approach
Operator-level perspectives from HoReCa procurement managers, R&D leads, retail buyers, and regulatory compliance officers anchored the qualitative base for this study. This primary intelligence was validated against secondary data from EU legislative documents, industry association reports, corporate financial filings, and trade statistics. A comprehensive bottom-up and top-down triangulation approach ensured data accuracy and market sizing precision.
Sensitivity analysis framed the quantitative assessment, modeling various scenarios across the analysis window. The analytical framework integrated segmentation dimensions including product type, material, end-user, distribution channel, and regional regulatory cluster. Compound annual growth rates were derived through a robust statistical model, incorporating key inputs such as hospitality investment trends and borosilicate glass R&D spending. Market volume and value outputs reflect a triangulated approach.
Material uncertainties — including unforeseen energy price shocks, new EU regulatory mandates, or significant supply chain disruptions — sit outside the modeled envelope. Forecasts reflect assumptions documented through extensive primary and secondary research. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Like Carbon Market
Glass
Double Glazing Glass Market
Glass
Global Laminated Glass Market
Glass
Glass Insulator Market
Glass
Metallic Glass Market
Glass
Europe Glass Insulators Market
Glass
Global Flat Glass Market
Glass
Technical Glass Market
Glass
Global Ultra-Thin Glass Market
Glass
Global Glassware Market
Glass
Global Self-Cleaning Glass Market
Glass
Insulated Glass Market
Glass
Solar Control Glass Market
Glass
Pharmaceutical Glass Tubing Market
Glass
North America Flat Glass Market
Glass
Glass Reactors Market