
 Precipitated Silica Market | 2026-2036
Precipitated Silica Market Size, Share, and Industry Trends Forecast 2026-2036
Precipitated Silica Market Intelligence
The development of highly dispersible silica for low rolling resistance tires is fragmenting the market away from commodity grades. This shift creates distinct performance tiers for specialty chemical producers. Evonik Industries AG leads in the innovation of these advanced silica formulations. Solvay SA competes directly through its portfolio of solutions for the automotive sector, while Tata Chemicals Ltd leverages its large-scale production capacity to serve diverse industrial applications.
Precipitated silica is a synthetic, amorphous form of silicon dioxide produced through the precipitation of a solution containing silicate salts. The material is characterized by its high surface area and porous structure, making it an effective reinforcing filler, abrasive, or thickening agent. The rubber application, primarily for tire manufacturing within the automotive industry, commands the largest share of consumption. In contrast, use in personal care as an abrasive in toothpaste and in food additives as an anti-caking agent offers higher-margin opportunities.
Regulatory frameworks like the EU's REACH legislation and the US FDA's guidelines for substances Generally Recognized As Safe (GRAS) govern market access. These standards dictate purity levels and permissible applications, particularly for food-contact and personal care products. Navigating the technical demands for high-performance automotive grades while managing cost pressures in industrial applications will define competitive success.
Market Dynamics
The precipitated silica market is defined by a structural bifurcation between commodity grades and high-performance specialty materials. This divergence is driven by technical demands from the automotive sector for fuel-efficient tires, creating distinct value chains and competitive arenas for producers.
Growth Catalysts
- Tire Labeling Regulations:Mandates such as the EU's tire labeling framework compel manufacturers to adopt high-performance silica to meet specific targets for fuel efficiency, wet grip, and noise reduction, directly stimulating demand for advanced grades.
- Food and Personal Care Applications:The use of high-purity silica as an anti-caking agent in food products, governed by FDA GRAS status, and as a cleaning abrasive in toothpaste, offers higher-margin growth avenues outside the cyclical automotive industry.
- Automotive Production in China:The country's status as the world's largest vehicle and tire producer creates a massive, geographically concentrated demand center for all grades of precipitated silica, anchoring a significant portion of consumption.
Market Restraints
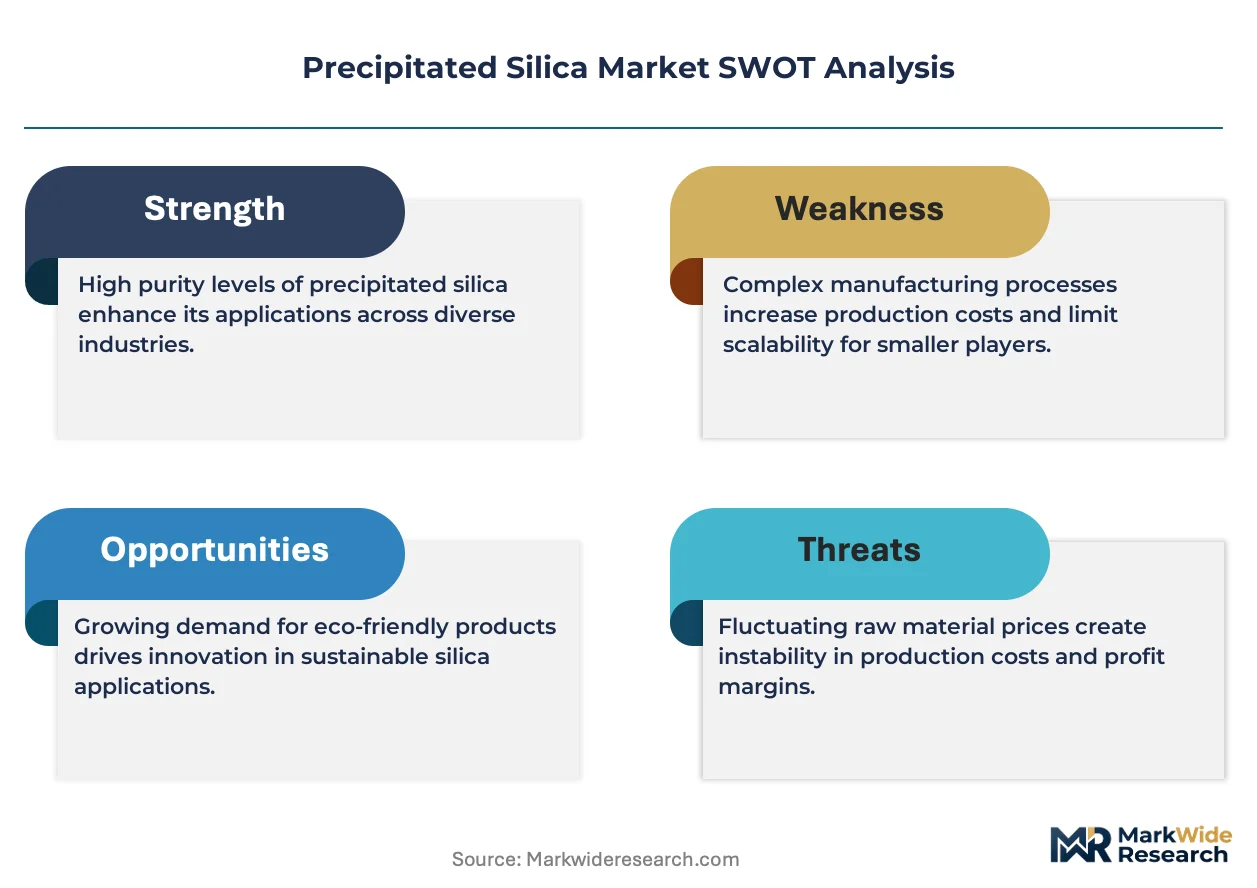
- Energy Price Volatility:The production of precipitated silica is an energy-intensive process, making manufacturing costs highly sensitive to fluctuations in global electricity and natural gas prices, which can compress producer margins.
- Substitution from Carbon Black:In less demanding rubber applications, particularly for mechanical rubber goods and non-performance tires, lower-cost carbon black remains a viable reinforcing filler, capping silica's penetration in certain price-sensitive segments.
- Regulatory Compliance Costs:Adhering to comprehensive chemical safety regulations like Europe's REACH framework requires significant investment in testing and documentation, acting as a market access barrier for smaller producers or those from less-regulated regions.
Strategic Opportunities
- Electric Vehicle Battery Components:Emerging use of specialty silica as a coating for separators in lithium-ion batteries presents a new, high-value application tied to the rapidly expanding electric vehicle market, offering diversification for producers.
- Biomedical and Pharmaceutical Excipients:The development of ultra-pure, biocompatible silica grades for use as drug delivery carriers and pharmaceutical processing aids opens a niche, high-margin opportunity requiring advanced material science capabilities.
- Expansion in Southeast Asia:Growing automotive manufacturing and industrialization in countries like Vietnam and Indonesia create opportunities for establishing local production or distribution to serve nascent demand for tire and industrial rubber applications.
Industry Challenges
- Capital-Intensive Production:Constructing new manufacturing facilities, especially for highly dispersible silica (HDS), requires substantial capital investment in reactors and drying technology, posing a high barrier to entry and capacity expansion.
- Specialized Process Expertise:Manufacturing consistent, high-performance silica grades demands sophisticated process control and a workforce skilled in chemical engineering, creating a talent bottleneck for producers aiming to enter the specialty market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precipitated Silica Market |
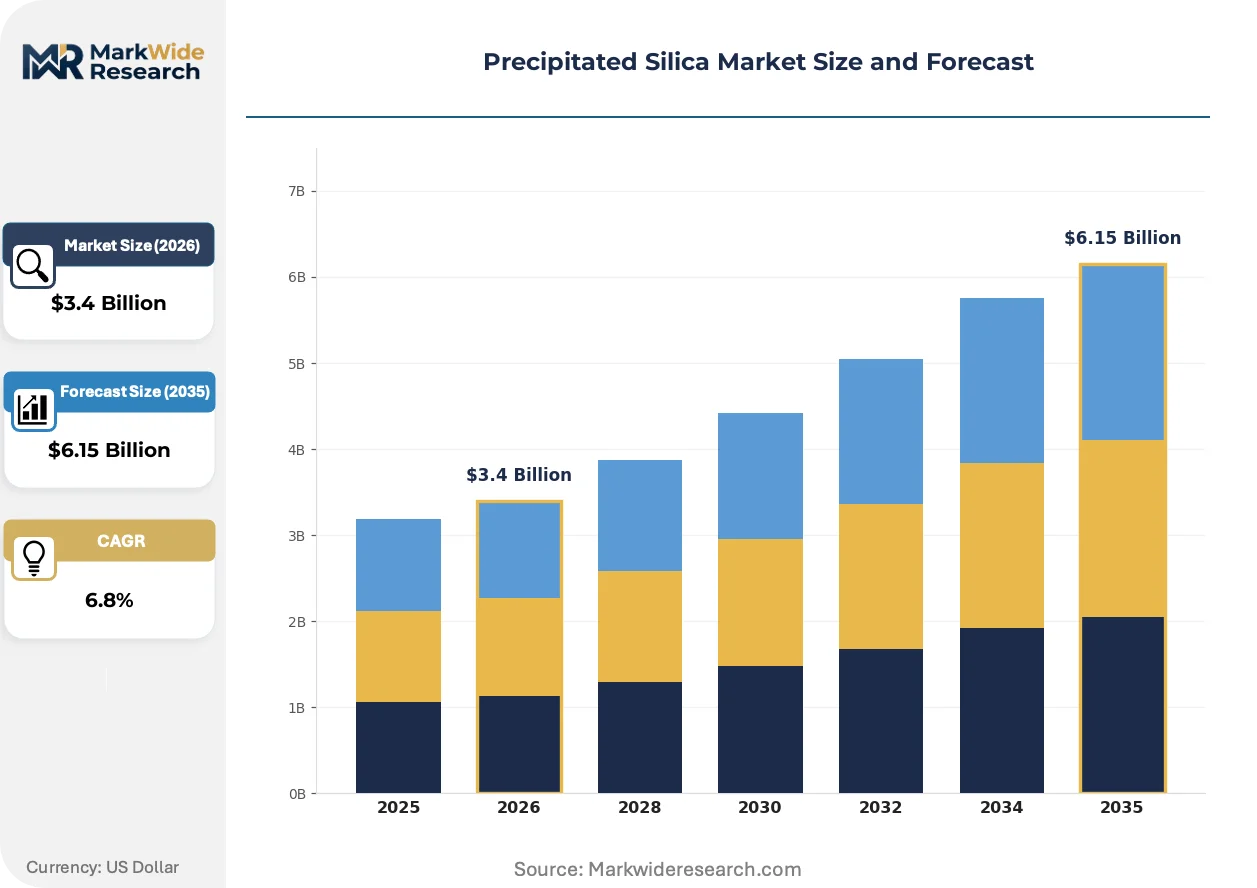
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular Silica, Fumed Silica, Hydrated Silica, Coated Silica Application: Rubber, Coatings, Plastics, Food Additives End Use Industry: Automotive, Personal Care, Electronics, Pharmaceuticals Distribution Channel: Direct Sales, Wholesalers, Online Retail, Distributors |
| Companies Covered | W.R. Grace & Co, Madhu Silica Pvt. Ltd, Evonik Industries AG, Oriental Silicas Corporation, Tata Chemicals Ltd, Solvay SA, Cabot Corporation, Tosoh Silica Corporation, QEMETICA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precipitated Silica Market Strategic Shifts & Innovations
Innovation in the precipitated silica market centers on material functionalization to meet specific end-use performance targets. This trend is moving the material from a passive additive to an active, performance-enabling component, particularly in the automotive and personal care industries.
Surface-modified silica, treated to enhance bonding with polymers, is a key product evolution. Tire manufacturers focused on electric vehicles are rapidly adopting these grades to achieve lower rolling resistance and improved wear characteristics. This advancement is hybridizing precipitated silica from a simple reinforcing filler into an integral, reactive part of the rubber matrix, altering compound chemistry.
Global food safety regulations are tightening purity requirements for silica used as a direct additive. Frameworks from the US FDA and the European Food Safety Authority (EFSA) impose strict limits on heavy metals and other impurities. The food and beverage segment is most affected, compelling producers to invest in dedicated, food-grade production lines and rigorous quality control systems to maintain market access.
A shift from transactional sales to co-development partnerships is altering customer relationships. Tire and specialty coatings manufacturers increasingly engage directly with silica producers to create custom formulations tailored to specific performance outcomes. This model bypasses traditional distribution channels in favor of direct technical collaboration, a pattern most visible within the automotive supply chains of Germany and Japan.
Precipitated Silica Market Segmentation
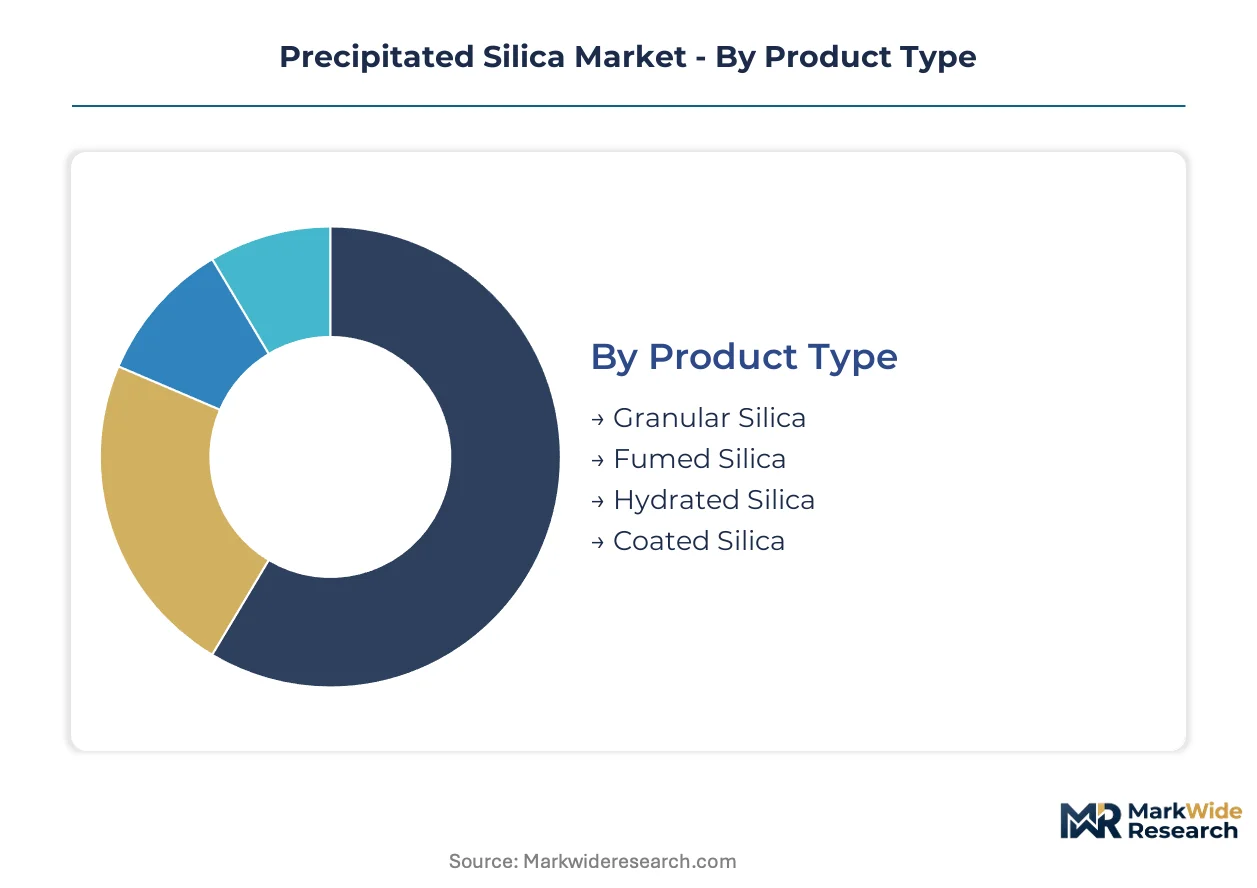
The precipitated silica market's segmentation highlights the structural bifurcation between commodity grades and high-performance materials. This differentiation is critical for understanding varied technical requirements and competitive dynamics across diverse end-use sectors. Each segment reflects specific product attributes and market access strategies.
Product Type:
The product type landscape exhibits a blend of mature commodity offerings and emerging specialty formulations.
- Granular Silica:This basic form serves as an effective reinforcing filler in various rubber applications and as an abrasive. Demand concentrates in industrial rubber goods and construction materials, where cost-effectiveness is paramount.
- Coated Silica:Surface-modified silica enhances bonding with polymers, crucial for advanced material performance. Demand focuses on high-performance tire manufacturing for electric vehicles, aiming for lower rolling resistance.
- Fumed Silica:Characterized by its extremely fine particle size and high surface area, fumed silica functions as a thickening agent and thixotropic additive.
- Hydrated Silica:Known for its abrasive and polishing properties, hydrated silica finds extensive use in personal care products, particularly in dental care formulations.
Granular Silica retains volume leadership; Coated Silica holds the steepest expansion curve.
Application:
Application segments range from high-volume, cost-sensitive uses to specialized, value-added formulations.
- Rubber:Precipitated silica acts as a primary reinforcing filler, significantly improving tear strength and abrasion resistance in rubber products. Demand within the automotive sector is substantial, especially for fuel-efficient tires meeting EU labeling standards.
- Food Additives:High-purity silica functions as an anti-caking agent and flow aid, preventing clumping in powdered food products. Demand in the food and beverage sector requires strict adherence to regulatory standards like FDA GRAS status.
- Coatings:In coatings, silica serves as a rheology modifier, matting agent, and anti-settling agent, enhancing surface properties.
- Plastics:Silica provides reinforcement, improves mechanical properties, and acts as a flame retardant additive in various plastic compounds.
Demand for Rubber applications anchors market volume, while Food Additives offers significant margin expansion.
End Use Industry:
End-use industries demonstrate varied consumption patterns, from mass-market manufacturing to niche, high-purity requirements.
- Automotive:The automotive industry utilizes precipitated silica primarily in tire manufacturing for enhanced performance and fuel efficiency. Demand is driven by China's position as the world's largest vehicle producer and innovation in EV battery components.
- Pharmaceuticals:Ultra-pure, biocompatible silica grades serve as excipients, drug delivery carriers, and processing aids in pharmaceutical formulations. Demand stems from biomedical research and advanced drug development requiring specialized material science capabilities.
- Personal Care:Precipitated silica functions as an abrasive in toothpaste, a thickener in cosmetics, and an absorbent in various personal care items.
- Electronics:In electronics, silica is used for insulation, thermal management, and as a filler in semiconductor encapsulants.
The Automotive sector drives the largest volume, whereas the Pharmaceuticals segment commands premium pricing.
Distribution Channel:
Distribution channels reflect diverse customer engagement models, from direct manufacturer relationships to broad market reach.
- Direct Sales:This channel involves direct engagement between silica producers and large industrial customers, often for custom formulations and technical support. Demand comes from tier-one automotive suppliers and specialty chemical buyers requiring co-development.
- Distributors:Distributors provide supply chain efficiency and regional market access, serving a wide array of industrial clients. Demand is generated by small and medium-sized enterprises (SMEs) across diverse industrial applications.
- Wholesalers:Wholesalers manage bulk purchasing and inventory, supplying smaller distributors and industrial buyers with standard grades.
- Online Retail:This channel facilitates sales of smaller volumes or niche products, catering to specialized applications or research institutions.
Direct Sales facilitates specialized partnerships, while Distributors ensure widespread market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's substantial output of precipitated silica increasingly supplies automotive and industrial sectors across Southeast Asia. This export-driven model supports regional manufacturing hubs. The material's utility in diverse applications, from tires to food additives, underpins its widespread demand.
China
Demand for precipitated silica in China is primarily driven by its massive automotive and tire production. The dual carbon goals policy encourages the use of advanced silica in fuel-efficient tires. Manufacturing clusters in the Yangtze River Delta actively innovate new silica grades for domestic consumption and export.
Germany
Europe's automotive industry, particularly in Germany, relies on high-performance silica for low rolling resistance tires. The EU's REACH legislation sets strict purity and safety standards for chemical products. North Rhine-Westphalia hosts major chemical producers developing specialized silica formulations.
United States
The United States market sees significant demand for precipitated silica in personal care and food applications, alongside rubber. The FDA's GRAS guidelines ensure high purity for food-grade silica. Chemical manufacturing in the Gulf Coast region continues to expand capacity for diverse industrial uses.
Japan
Japan's advanced automotive and electronics industries require specialized precipitated silica grades for performance enhancement. METI promotes material science innovations to support high-tech manufacturing. The Kanto region serves as a hub for research and development into new silica applications.
India
Rapid industrialization and a growing automotive sector fuel demand for precipitated silica in India. The BIS standards govern product quality and safety across various applications. Gujarat's chemical industry is expanding production capabilities to meet rising domestic consumption.
Precipitated Silica Market Key Industry Players
On the supply side, the industry is bifurcated between large-scale commodity producers and specialized manufacturers of high-performance grades. Strategic archetypes include global chemical conglomerates, regional specialists, and emerging players focused on specific application niches. Dominant competitive moves involve significant capital investments in advanced production facilities and strategic partnerships for co-development with end-use customers. Capacity expansion for high-purity silica also remains a key focus.
Within the specialty chemical producers, Germany-based Evonik Industries AG exemplifies innovation in highly dispersible silica formulations for advanced tire applications, setting performance benchmarks. France-based Solvay SA occupies a strong position with its comprehensive portfolio of solutions tailored for the automotive sector, competing directly in high-value segments. India-based Tata Chemicals Ltd represents a major player leveraging large-scale production capacity to serve diverse industrial applications, including rubber and personal care markets. These companies demonstrate varied approaches to market penetration and value creation across the precipitated silica landscape, balancing scale with specialization.
| Leading Market Players |
|---|
| W.R. Grace & Co |
| Madhu Silica Pvt. Ltd |
| Evonik Industries AG |
| Oriental Silicas Corporation |
| Tata Chemicals Ltd |
| Solvay SA |
| Cabot Corporation |
| Tosoh Silica Corporation |
| QEMETICA |
| Others |
Cost & Logistics Intelligence
The Suez Canal freight corridor's cost dynamics influence global precipitated silica pricing, particularly for bulk shipments from concentrated Asian production hubs, impacting price differentiation in regional markets. This directly affects margins for commodity grades.
Pricing Analysis
The technology-generation pricing gap separates highly dispersible silica (HDS) from commodity grades. Contract-based long-term offtake agreements define specialty silica pricing, driven by certification levels like FDA GRAS and customized performance attributes. Pricing softness reflects energy price volatility, particularly impacting commodity spot markets. Industrial rubber buyers exhibit high price sensitivity, while pharmaceutical excipient purchasers prioritize purity and performance over cost.
Supply Chain Analysis
Large global chemical conglomerates like Evonik Industries AG and Solvay SA hold significant capacity for advanced silica grades, while Tata Chemicals Ltd focuses on large-scale commodity production. Geographic supply concentration centers on China, Germany, and the United States. Production relies on key raw materials such as sodium silicate and sulfuric acid. Regulatory compliance costs, particularly Europe's REACH framework, present a structural supply chain risk, with distribution primarily through direct sales and regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The precipitated silica market is entering a cyclical recovery, driven by renewed automotive production cycles globally. This rebound in vehicle manufacturing directly stimulates demand for high-performance tires.
For Market Incumbents: Insulate core market share by deepening investments in highly dispersible silica (HDS) production capabilities, particularly for advanced automotive applications. Secure long-term raw material contracts for sodium silicate to mitigate energy price volatility. Invest in achieving premium certifications like FDA GRAS to differentiate high-purity grades from lower-cost alternatives, countering substitution from carbon black in industrial rubber.
For New Entrants and Emerging Players: Establish a beachhead in niche, high-margin segments such as biomedical and pharmaceutical excipients, which demand ultra-pure, biocompatible silica grades. Focus on the emerging use of specialty silica in electric vehicle battery components, offering diversification. A go-to-market strategy emphasizing co-development partnerships with specific end-users in Germany and Japan can bypass established distribution channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core precipitated silica assets. The market offers long-term viability over the next decade, supported by sustained demand from the automotive and personal care industries. Acquisition targets should include mid-sized producers possessing specialized process expertise in highly dispersible silica or ultra-pure grades for biomedical applications. Increased M&A activity within the specialty silica segment signals market consolidation and value creation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for HDS | Boosts supply of high-performance silica for fuel-efficient tire manufacturing in the automotive sector. |
| Green Manufacturing Transition | Reduces energy consumption and waste, aligning with EU environmental regulations and corporate sustainability goals. |
| Long-term Supply Agreement | Secures consistent raw material input for producers, mitigating energy price volatility and supply chain risks. |
| Joint Venture for R&D | Accelerates innovation in new silica functionalization, particularly for EV battery components and biomedical uses. |
| Product Launch of Ultra-pure Grades | Captures high-margin opportunities in pharmaceutical and food additive applications requiring strict purity standards. |
Research Approach
Findings reconcile primary fieldwork against secondary review of trade association reports, customs data, company filings, and regulatory documentation. Primary interviews involved plant managers, R&D directors at specialty chemical producers, procurement leads from automotive OEMs, and distribution channel partners. These insights were triangulated with quantitative data from sources like ACC/Cefic reports and EU REACH publications. A rigorous bottom-up and top-down approach ensured data consistency and market validation.
Forecast inputs considered include historical market performance, macroeconomic indicators, and technological advancements across the analysis window. The analytical framework modeled segmentation dimensions such as product type, application, end-use industry, distribution channel, and regional production capacity. Compound annual growth rates were derived from historical trends and projected demand drivers like tire labeling regulations. Electric vehicle adoption rates also served as a key industry-specific forecast input.
Macroeconomic conditions sit as an overlay; deviation in global energy prices or automotive production volumes would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and raw material availability. Quarterly review of global manufacturing output and key commodity prices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Injection Mold Hot Runners Market
Industrial Materials
Industrial Pails and Drums Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
Asia-Pacific Wood Based Panel Market
Industrial Materials
Steel Cord Market
Industrial Materials
Static Mixer Market
Industrial Materials
Global Metal Anodizing Market
Industrial Materials
Global Industrial Chain Market
Industrial Materials
Pre-Painted Steel Coil Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
Industrial Mixers Market
Industrial Materials
Industrial Standoff and Spacer Market
Industrial Materials
Asia-Pacific Industrial Flooring Market
Industrial Materials
Crimped Wire Brushes Market
Industrial Materials
Global Polyurethane Screen Panels Market
Industrial Materials
Industrial Continuous Furnaces Market