
 Specialty Polyamides Market | 2026-2036
Specialty Polyamides Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Polyamides Market Intelligence
Specialty polymer engineering talent scarcity is redrawing competitive boundaries as formulation expertise becomes the decisive bottleneck for capacity expansion. Evonik Industries AG leverages its integrated high-performance polymers platform to sustain pricing power in aromatic polyamide grades. BASF SE anchors its position through backward integration into adipic acid and caprolactam precursors. Arkema S.A. differentiates via bio-based polyamide 11 technology leadership and controlled geographic manufacturing footprint.
Specialty polyamides comprise engineered thermoplastic polymers with repeating amide linkages, distinguished by melting points exceeding 260°C and tensile strengths above 80 MPa, synthesized through condensation of diamines and dicarboxylic acids or ring-opening polymerization of lactams for applications demanding thermal stability and chemical resistance. High-performance polyamides command premium positioning due to their substitution potential against metals in under-hood automotive components and electrical connectors. Aromatic polyamides occupy the highest margin tier where flame retardancy and dimensional stability justify specialized processing infrastructure. Copolymer polyamides represent the fastest-expanding product category as blend flexibility enables tailored property profiles for medical device and consumer electronics housings.
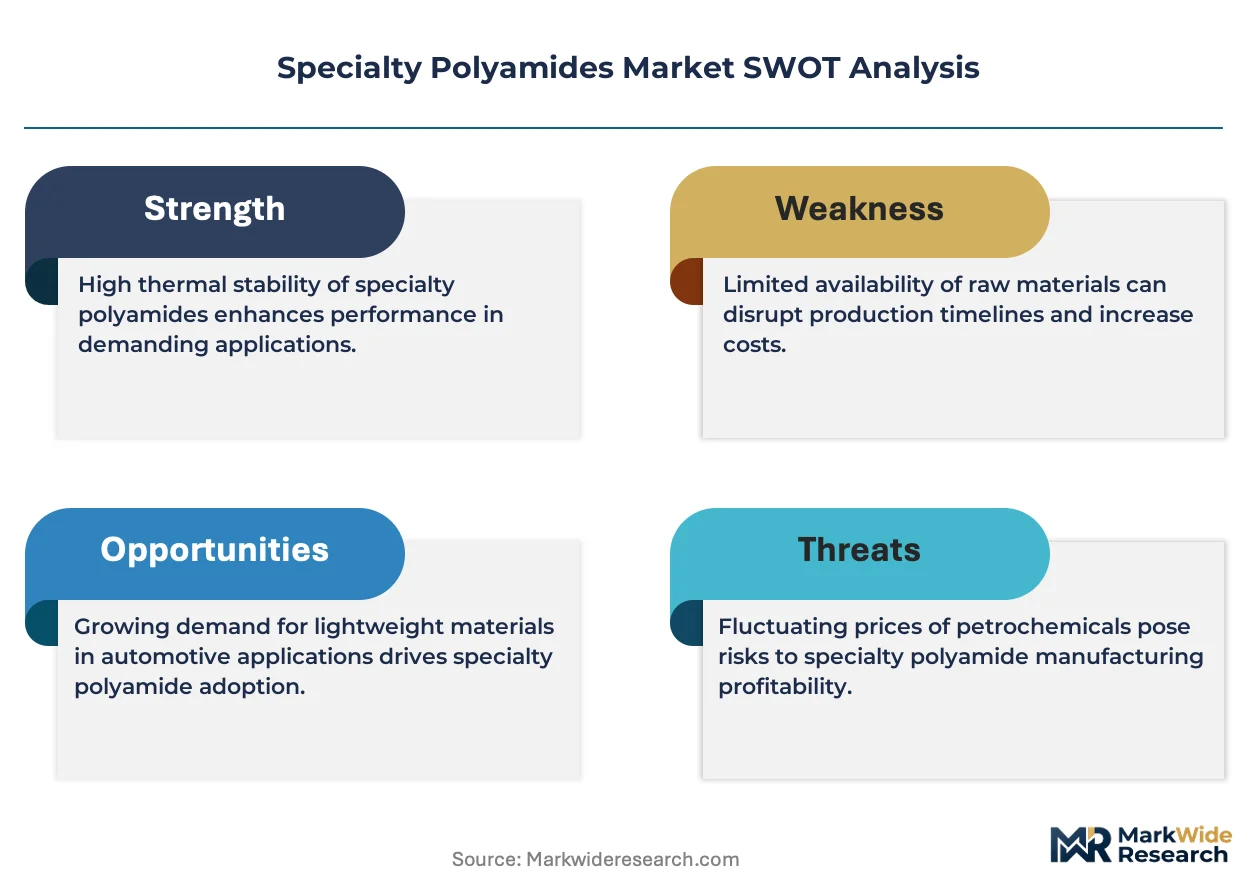
EPA regulations on per- and polyfluoroalkyl substances are redirecting formulation strategies toward fluorine-free flame retardant systems in US-bound production. REACH restrictions on CMR substances and the EU F-Gas Regulation are tightening compliance thresholds for polymer additives and processing aids. The EU Green Deal's carbon border adjustment mechanism is reshaping sourcing economics for European compounders dependent on imported base resins. Stakeholders must monitor regulatory divergence between EPA and ECHA chemical restriction timelines when allocating R&D budgets and qualifying alternative additive packages.
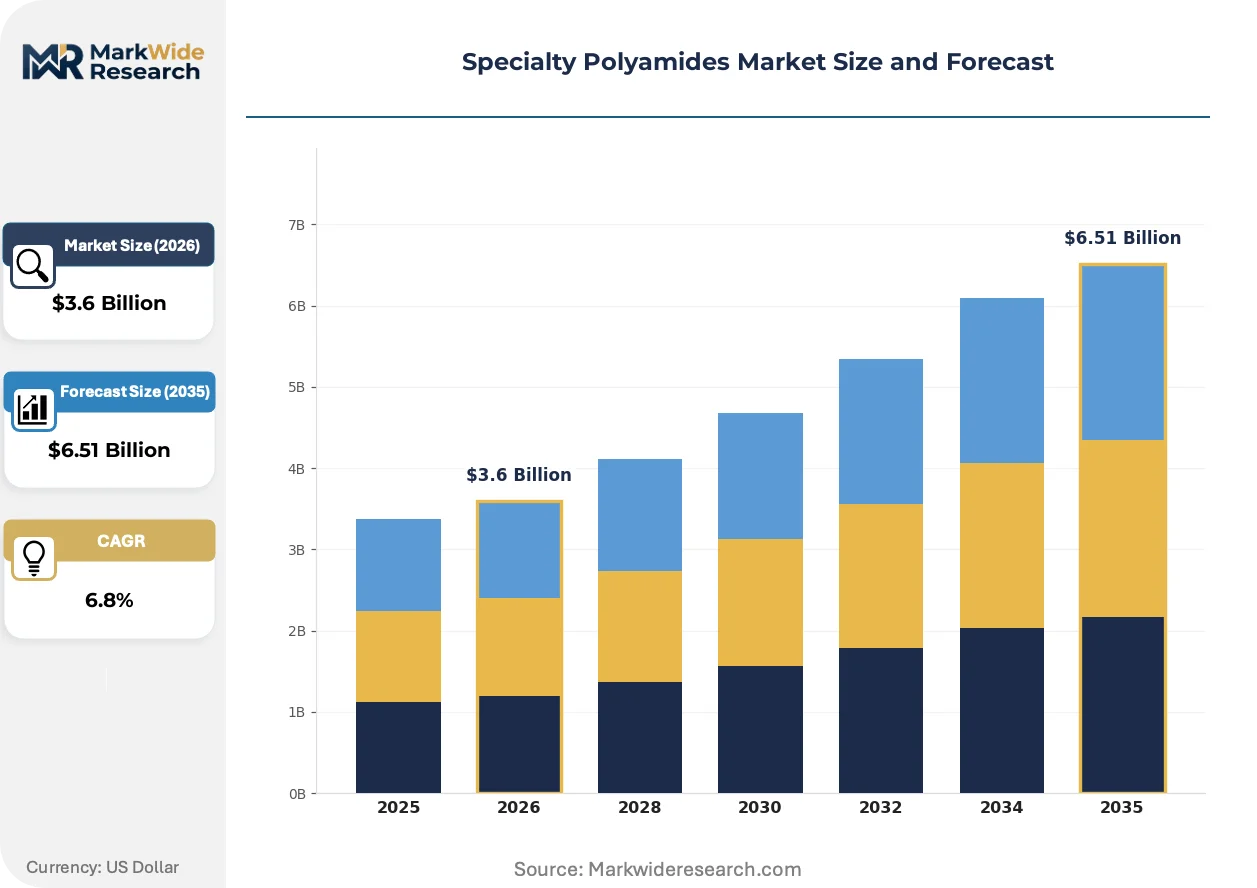
Market Dynamics
Automotive electrification is compressing thermal management requirements into smaller component footprints, forcing compounders to reformulate polyamide grades for simultaneous heat dissipation and electrical isolation in battery housings and power electronics.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon blowing agents is accelerating adoption of specialty polyamide foams in thermal insulation for electric vehicle battery packs.
- Medical device miniaturization:Sterilization-resistant copolymer grades are penetrating surgical instrument housings and drug delivery systems requiring repeated autoclave cycles.
- China dual carbon goals:Domestic automotive OEMs are qualifying lightweight polyamide composites to replace metal brackets and reduce vehicle curb weight for emissions compliance.
Market Restraints
- Adipic acid supply concentration:Over 60% of global feedstock production sits in mainland China, exposing European and North American compounders to shipping cost volatility and tariff exposure.
- REACH CMR restrictions:Classification of certain flame retardant additives as carcinogenic, mutagenic, or reprotoxic is forcing reformulation of established polyamide grades with limited qualified alternatives.
- Polyether ether ketone substitution:Continuous fiber-reinforced PEEK is displacing aromatic polyamides in aerospace connector applications above 150°C continuous service temperature.
Strategic Opportunities
- India PLI scheme for automotive:Production-linked incentives for advanced chemistry cell manufacturing are creating captive demand for localized polyamide compound supply to battery pack assemblers.
- 5G base station infrastructure:Low-dielectric constant polyamide formulations are penetrating RF connector and antenna housing applications as mmWave deployment accelerates.
- Bio-based feedstock convergence:Castor oil-derived sebacic acid chemistry is enabling carbon-negative polyamide 10,10 and 6,10 grades for premium consumer electronics branding requirements.
Industry Challenges
- Reactive extrusion expertise scarcity:Compounding facilities capable of in-situ polymerization and reactive alloying are concentrated among a handful of European and Japanese operators, limiting capacity expansion.
- UL 94 V-0 recertification timelines:Reformulated halogen-free flame retardant systems require 18-24 month qualification cycles for electrical connector applications, freezing specification decisions.
- Legacy injection molding asset incompatibility:High-temperature aromatic polyamide grades demand barrel temperatures above 340°C, exceeding the rated capacity of installed machinery across Tier-2 automotive supplier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Polyamides Market |
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $6.51 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aliphatic Polyamides, Aromatic Polyamides, Copolymer Polyamides, High-Performance Polyamides Application: Aerospace, Automotive, Electronics, Textiles End User: Consumer Electronics, Industrial Equipment, Transportation, Medical Devices Form: Films, Fibers, Resins, Composites |
| Companies Covered | Evonik Industries AG, Arkema S.A., BASF SE, DuPont de Nemours, Inc., Koninklijke DSM N.V., Asahi Kasei Corporation, LG Chem, INVISTA, Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Polyamides Market Strategic Shifts & Innovations
Material science convergence with digital manufacturing protocols is redefining how specialty polyamide formulations reach qualification. Real-time rheology monitoring and AI-assisted mold flow simulation are compressing development cycles.
Bio-based long-chain polyamides synthesized from renewable sebacic acid feedstocks are decomposing the historical petroleum dependency of high-performance grades. European automotive OEMs are mandating recycled content thresholds in supplier scorecards. This feedstock shift is compressing margin structures for conventional petrochemical routes while opening premium positioning for verified sustainable supply chains.
REACH restrictions on per- and polyfluoroalkyl substances are redirecting formulation strategies toward phosphorus-nitrogen synergist systems in electrical connector applications. Compounders must requalify entire additive packages without sacrificing glow-wire ignition temperature performance. German automotive suppliers are most exposed given their concentration in under-hood fuse box and junction block manufacturing.
Direct-to-compounder digital procurement platforms are fragmenting historical distributor control over specialty resin allocation. Tier-1 automotive buyers are establishing API connections to polymer producers for real-time inventory visibility and lot traceability. This channel compression is most advanced in the US Midwest manufacturing corridor where just-in-sequence assembly plants demand synchronized material flows.
Specialty Polyamides Market Segmentation
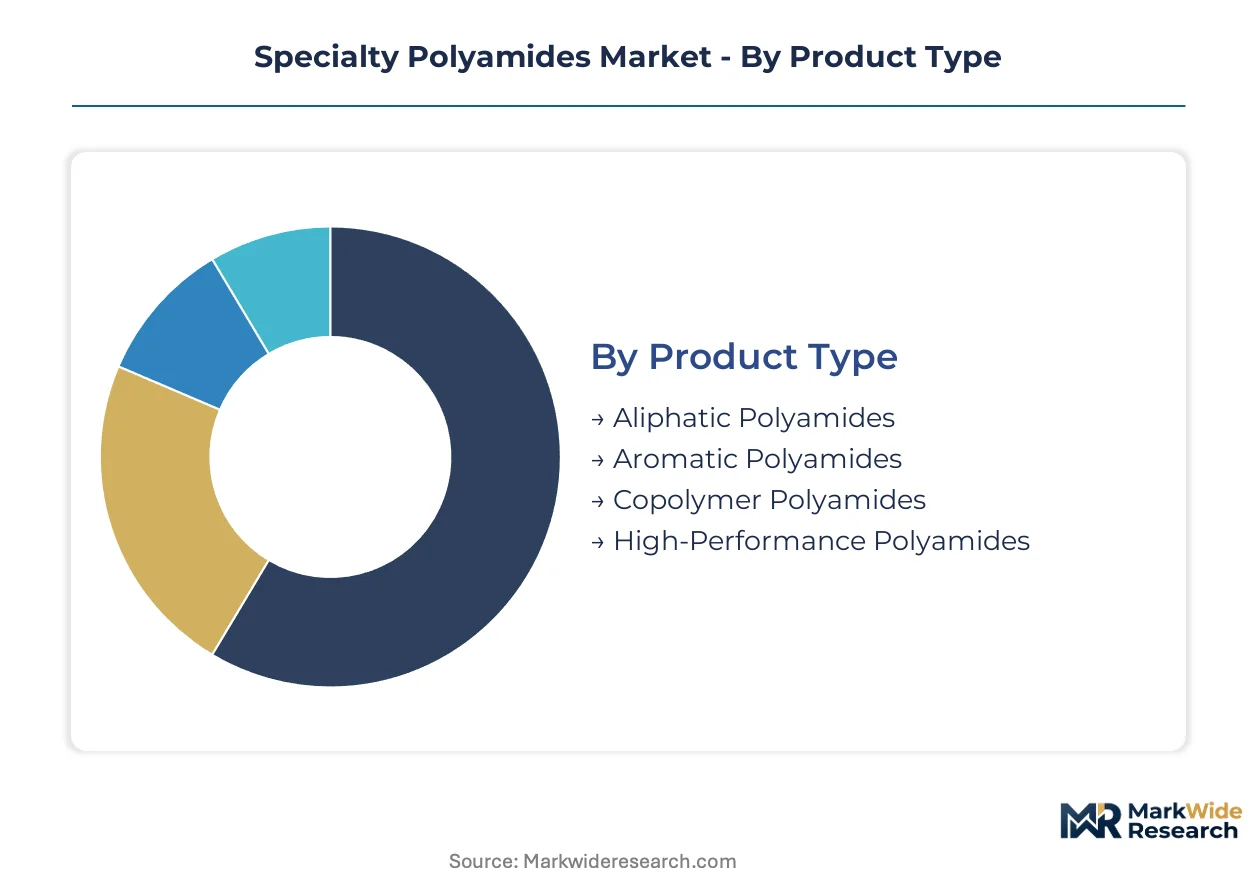
Specialty polyamides serve divergent performance requirements across automotive under-hood components, surgical instrument sterilization cycles, and 5G antenna housings. Channel differentiation separates bulk resin distributors serving commodity compounders from direct technical sales teams qualifying medical device OEMs.
Product Type:
Aliphatic grades move through distributor networks to Tier-2 automotive suppliers, while aromatic and high-performance variants require direct technical engagement with OEM engineering teams.
- Aromatic Polyamides:These polymers incorporate benzene rings into the backbone, delivering continuous service temperatures above 150°C and inherent flame retardancy without halogenated additives. German automotive suppliers in fuse box and junction block manufacturing anchor demand, though REACH restrictions on CMR-classified flame retardants are forcing additive package requalification. By volume, aliphatic polyamides lead. By growth pace, aromatic grades are climbing the fastest.
- Copolymer Polyamides:Blend flexibility through controlled monomer sequencing enables tailored property profiles balancing stiffness, impact resistance, and moisture uptake. Medical device OEMs in Switzerland and surgical instrument manufacturers in Germany are driving qualification of sterilization-resistant grades capable of repeated autoclave cycles.
- Aliphatic Polyamides:Standard PA 6 and PA 66 derivatives synthesized from petrochemical caprolactam and adipic acid feedstocks.
- High-Performance Polyamides:Long-chain and semi-aromatic grades with melting points exceeding 260°C and tensile strengths above 80 MPa.
Aromatic polyamides command the highest margin tier; copolymer grades are gaining share fastest in medical and electronics applications.
Application:
Cost tier separation distinguishes aerospace qualification programs with 18-24 month certification cycles from automotive just-in-sequence procurement with compressed lead times.
- Automotive:Battery pack housings, power electronics enclosures, and thermal management components for electrified powertrains. Chinese OEMs qualifying lightweight polyamide composites for dual carbon compliance are expanding volume faster than European premium brands.
- Electronics:RF connectors, antenna housings, and circuit breaker components requiring low dielectric constants for mmWave 5G deployment. US-based compounders serving Midwest manufacturing corridors face EPA pressure to eliminate per- and polyfluoroalkyl substances from flame retardant formulations.
- Aerospace:Connector and insulation applications above 150°C where PEEK substitution threatens aromatic polyamide positioning.
- Textiles:Technical fibers for industrial filtration and protective apparel.
Automotive consumes the greatest tonnage; electronics applications are expanding most quickly.
End User:
Customer type fragmentation separates medical device OEMs demanding lot traceability and biocompatibility documentation from industrial equipment buyers prioritizing cost-per-kilogram metrics.
- Transportation:Captures automotive, rail, and commercial aviation procurement with divergent qualification protocols. Indian battery pack assemblers under the PLI scheme for advanced chemistry cells are creating localized demand concentration.
- Medical Devices:Surgical instrument housings, drug delivery systems, and implantable component packaging requiring US FDA and EMA biocompatibility clearances.
- Consumer Electronics:Smartphone structural frames, laptop hinge mechanisms, and wearable device housings.
- Industrial Equipment:Pumps, valves, and conveyor components in chemical processing environments.
Transportation dominates volume; medical devices show the steepest expansion trajectory.
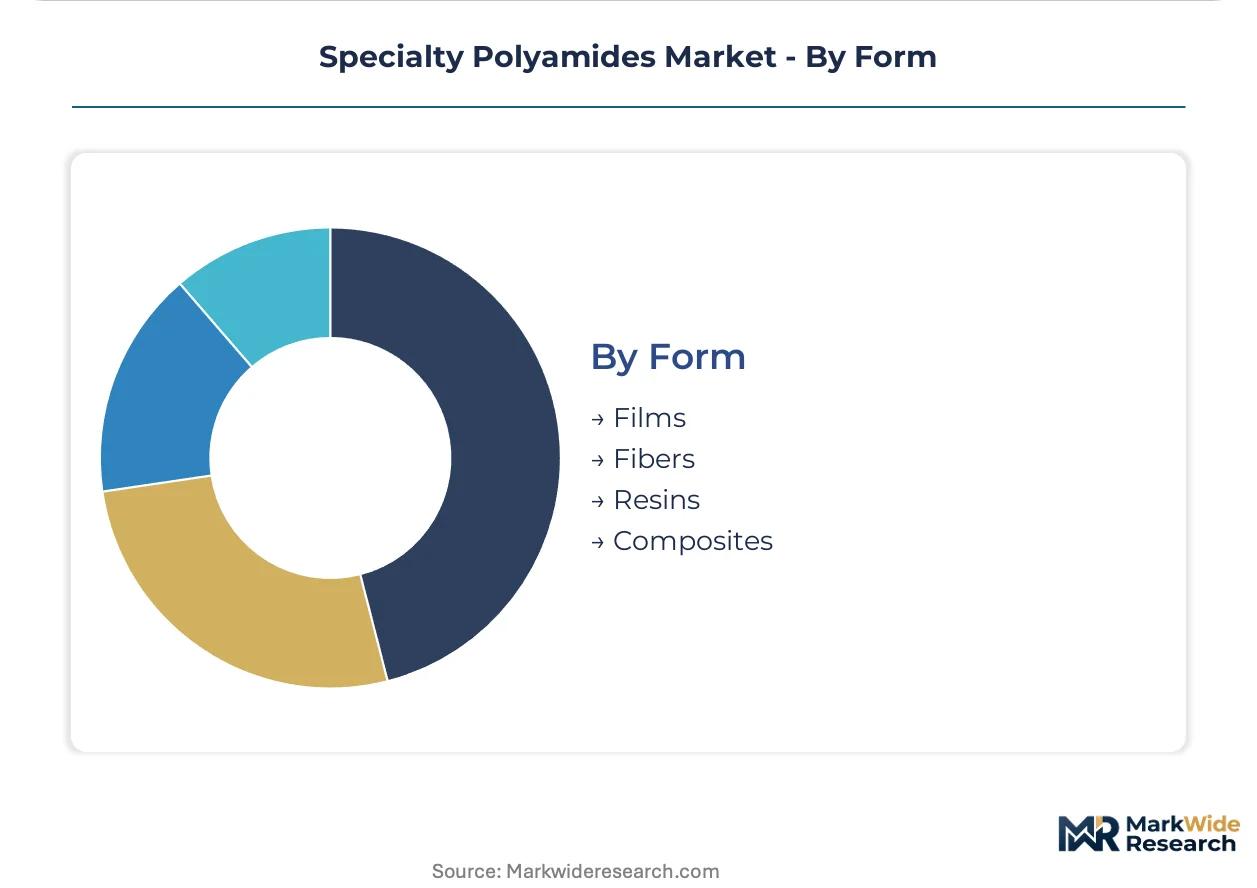
Form:
Supply concentration varies by form factor, with fiber production gravitating toward integrated petrochemical complexes and resin compounding fragmenting across specialized toll operators.
- Resins:Pelletized base polymers and custom compounds serving injection molders and extrusion processors. Arkema's bio-based PA 11 resin production in France and Thailand supplies premium branding requirements for consumer electronics OEMs.
- Composites:Glass fiber and carbon fiber reinforced grades displacing metal brackets in automotive lightweighting initiatives. China's domestic OEMs are qualifying these materials fastest for emissions compliance.
- Fibers:Continuous filament and staple forms for technical textiles and industrial filtration.
- Films:Biaxially oriented and cast film formats for flexible electronics and food packaging barrier layers.
Resins lead by volume; composites are gaining share fastest in transportation electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH and the EU Green Deal anchor European regulatory influence over specialty polyamide formulation standards, while China's dual carbon goals and India's PLI scheme for automotive batteries reshape Asian demand geography.
Germany
Automotive electrification drives demand for heat-resistant battery housings and power electronics enclosures. The EU F-Gas Regulation accelerates specialty polyamide foam adoption in EV thermal insulation. Industrial clusters around Stuttgart and Munich concentrate fuse box manufacturing for premium OEMs.
China
Domestic automotive OEMs qualify lightweight polyamide composites for dual carbon compliance and vehicle curb weight reduction. MIIT emission standards tighten material traceability requirements across supply chains. The Yangtze River Delta hosts the fastest-growing concentration of battery pack assemblers sourcing localized compounds.
United States
EPA restrictions on per- and polyfluoroalkyl substances redirect flame retardant formulation strategies toward fluorine-free systems. Midwest manufacturing corridors demand synchronized material flows for just-in-sequence assembly. Michigan and Ohio-based Tier-1 suppliers face 18-24 month UL 94 V-0 recertification timelines.
India
Production-linked incentives for advanced chemistry cell manufacturing create captive demand for localized polyamide compound supply. BIS standards elevate material qualification protocols for automotive applications. Tamil Nadu and Gujarat emerge as primary battery pack assembly clusters requiring sterilization-resistant grades.
Switzerland
Medical device OEMs drive qualification of copolymer grades for surgical instrument housings requiring repeated autoclave cycles. Swissmedic biocompatibility clearances set documentation thresholds for implantable component packaging. Basel-area precision manufacturers anchor European demand for sterilization-resistant formulations.
Specialty Polyamides Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in specialty polyamides. The upper tier commands pricing power through captive adipic acid and caprolactam supply, while specialists differentiate via bio-based feedstock chemistry and controlled geographic footprints. Three archetypes dominate: backward-integrated petrochemical majors, bio-based technology leaders, and regional compounders with reactive extrusion expertise. Competitive moves concentrate on additive package requalification for REACH and EPA compliance, plus capacity expansion in India and Southeast Asia to serve localized automotive battery demand.
Among European-based integrated producers, Evonik Industries AG, BASF SE, and Arkema S.A. exemplify divergent strategic positions. Evonik occupies a position within the aromatic polyamide tier where formulation expertise sustains premium positioning. BASF SE represents backward-integrated scale through in-house production of adipic acid and caprolactam precursors. Arkema S.A. anchors the bio-based specialization vector with castor oil-derived sebacic acid chemistry for carbon-negative grades. These three collectively illustrate how feedstock control, technical differentiation, and sustainability credentials now separate competitive tiers.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Arkema S.A. |
| BASF SE |
| DuPont de Nemours, Inc. |
| Koninklijke DSM N.V. |
| Asahi Kasei Corporation |
| LG Chem |
| INVISTA |
| Solvay SA |
| Others |
Cost & Logistics Intelligence
Castor oil-derived sebacic acid chemistry replacing petroleum-based adipic acid in long-chain polyamide grades is redrawing supply geography toward Thailand and India while compressing margin structures for conventional petrochemical routes and opening premium positioning for verified sustainable supply chains.
Pricing Analysis
Geographic price spreads between European compounders and Asian producers reflect divergent feedstock access and regulatory compliance burdens. Three-tier pricing structure across aromatic, high-performance, and aliphatic grades separates premium formulations for German automotive fuse box manufacturers from standard grades serving Tier-2 injection molders. Cost compression in aliphatic polyamides is intensifying because Chinese adipic acid supply concentration exposes European compounders to shipping volatility. Medical device OEMs in Switzerland show least price sensitivity due to sterilization-resistant copolymer requirements, while industrial equipment buyers prioritize cost-per-kilogram metrics.
Supply Chain Analysis
Strait of Malacca transit underwrites seaborne adipic acid flows from Chinese production hubs to European compounding facilities, creating logistics vulnerability for just-in-sequence automotive supply chains. Manufacturing concentrates in China, Germany, and Thailand, with raw material flows drawing from caprolactam, adipic acid, and castor oil-derived sebacic acid feedstocks. Single-source vulnerability in Chinese adipic acid production exposes compounders to tariff exposure and shipping cost volatility. Distribution runs through direct-to-compounder digital procurement platforms fragmenting historical distributor control over specialty resin allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification cycles are lifting specialty polyamide demand as battery pack housings and power electronics enclosures drive material qualification programs across German and Chinese OEM supply chains.
For Market Incumbents: Fortify formulation expertise moats by investing in reactive extrusion capabilities and captive sebacic acid supply from castor oil processing partnerships. PEEK substitution in aerospace connector applications above 150°C threatens aromatic polyamide positioning, demanding accelerated R&D in hybrid copolymer architectures. Backward integration into adipic acid precursors sustains margin defense against Chinese feedstock volatility. For New Entrants and Emerging Players: Anchor in India's PLI scheme for advanced chemistry cell manufacturing, where localized polyamide compound supply to battery pack assemblers remains underdeveloped. Bio-based polyamide 10,10 and 6,10 grades for premium consumer electronics branding offer the most penetrable white space. Pursue toll compounding partnerships with European automotive Tier-1 suppliers seeking dual sourcing for REACH-compliant formulations. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors compounders with reactive extrusion expertise and qualified UL 94 V-0 additive packages. Long-term viability hinges on feedstock flexibility across petroleum and bio-based routes. Acquisition targets should demonstrate castor oil supply chain relationships or Indian manufacturing footprints. Watch for EPA-ECHA regulatory divergence on flame retardant timelines as the inflection signal for reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sebacic Acid | Captive bio-based feedstock supply secures carbon-negative grade positioning for European automotive OEM scorecards. |
| Reactive Extrusion Capacity Expansion | In-situ polymerization expertise concentrates among Japanese and European operators, limiting qualified supply growth. |
| UL 94 V-0 Additive Requalification | Phosphorus-nitrogen synergist systems demand 18-24 month certification cycles, freezing specification decisions at Midwest Tier-1 suppliers. |
| India Manufacturing Footprint Establishment | Tamil Nadu and Gujarat battery pack clusters require localized compound supply under PLI scheme localization mandates. |
| Direct-to-Compounder Digital Platform Launch | API-connected procurement fragments distributor control and enables real-time lot traceability for just-in-sequence assembly plants. |
Research Approach
Cross-validation between primary interviews with polymer plant managers, automotive Tier-1 procurement leads, and medical device R&D directors and secondary sources including customs trade data, SEC 10-K filings, and Cefic industry reports anchors the qualitative findings. Bottom-up demand modeling from injection molder consumption patterns and top-down supply validation from adipic acid production disclosures complete the triangulation.
Sensitivity analysis across grade tier, end-use industry, and regional production hub dimensions shapes the analytical framework over the projection horizon. CAGRs derive from segment-level volume trajectories weighted by automotive electrification intensity and medical device sterilization cycle requirements. Modeled inputs include Chinese dual carbon compliance timelines and EU F-Gas Regulation phase-down schedules for hydrofluorocarbon blowing agents.
Underlying assumptions cover REACH and EPA regulatory stability, with deviation risk concentrated in CMR substance restriction timelines and castor oil harvest volatility. Practitioners should keep alternative scenarios live as automotive OEM recycled content thresholds and carbon border adjustment mechanism implementations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Mica Sheet Market
Specialty Materials
Latin America International CEP Market
Specialty Materials
Niobium Pentoxide Market
Specialty Materials
Medical Injection Molded Plastics Market
Specialty Materials
Cellulose Gel Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Electrode Paste Market
Specialty Materials
Polyimide Foam Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Global Synthetic Zeolite Market
Specialty Materials
Global PMMA Microspheres Market
Specialty Materials
Absorbent Booms and Socks Market
Specialty Materials
Silicone Solutions for Leather and Textile Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
APAC Fluoroelastomer Market