
 Polyimide Foam Market | 2026-2036
Polyimide Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Polyimide Foam Market Outlook
Specialized polymer chemist availability is bifurcating the competitive landscape, with large incumbents capturing scarce talent while smaller firms struggle to staff formulation labs. DuPont leverages its century of fluoropolymer expertise to sustain leadership in high-temperature foam architectures. Evonik Industries anchors European supply through integrated precursor manufacturing at its Marl site. Boyd Corporation specializes in converting raw polyimide stock into application-specific thermal management assemblies for aerospace tier-one suppliers.
Polyimide foam constitutes a closed-cell or open-cell aromatic polymer structure synthesized from pyromellitic dianhydride and aromatic diamines, delivering continuous service temperatures exceeding 300°C with extremely low thermal conductivity and outgassing properties. The material serves primarily as lightweight thermal and acoustic insulation in environments where hydrocarbon-based foams degrade. Flexible foam formulations dominate commercial volumes due to their adaptability in aircraft cabin insulation and electronics packaging, while rigid foam commands premium positioning in structural support applications for launch vehicles. High-temperature foam represents the fastest-expanding category as hypersonic programs and next-generation propulsion systems drive specification thresholds upward.
FAA airworthiness standards and EASA certification requirements govern material flammability and smoke toxicity in aerospace applications, directly dictating which foam grades achieve platform qualification. EPA regulations on volatile organic compound emissions during foam manufacturing constrain solvent-based production methods and favor water-blown or supercritical CO2 processes. REACH compliance in Europe adds substance registration burdens that favor incumbents with established dossier portfolios. Stakeholders must monitor evolving thermal performance benchmarks from defense procurement agencies and decide whether to absorb certification costs internally or pursue strategic partnerships with established qualified suppliers.
Market Dynamics
Aerospace procurement offices are consolidating vendor lists around qualified thermal insulation suppliers, compressing the supplier base while elevating certification barriers for new entrants. This buyer-side concentration is restructuring competitive access and margin distribution across the value chain.
Growth Catalysts
- EU Green Deal industrial emissions framework:Tightening material compliance requirements are accelerating replacement of hydrocarbon-based insulation in German advanced manufacturing corridors.
- Hypersonic propulsion programs:Defense procurement agencies are elevating thermal performance benchmarks, pulling demand toward high-temperature foam grades exceeding 300°C continuous service.
- Supercritical CO2 foaming:Water-blown and CO2-based manufacturing processes are gaining preference as EPA volatile organic compound regulations constrain solvent-based production methods.
Market Restraints
- Specialized polymer chemist scarcity:Formulation expertise concentration among large incumbents restricts smaller firms from staffing development labs.
- Precursor supply concentration:Pyromellitic dianhydride manufacturing clusters in specific chemical corridors create input vulnerability.
- Aerogel substitution threat:Silica aerogel blankets are capturing share in sub-200°C electronics packaging applications where weight minimization dominates.
Strategic Opportunities
- Launch vehicle structural support:Rigid foam grades command premium positioning in reusable rocket programs requiring combined thermal protection and load-bearing capacity.
- India PLI scheme:Production-linked incentives for aerospace component manufacturing are drawing precursor conversion investments toward Indian subcontinent assembly.
- Digital qualification platforms:Blockchain-tracked certification documentation is emerging as a channel innovation for streamlining EASA and FAA airworthiness approval workflows.
Industry Challenges
- FAA-EASA dual certification timelines:Parallel airworthiness validation processes extend platform qualification cycles and tie up technical resources.
- Legacy aircraft retrofit integration:Foam replacement in certified airframes requires extensive re-qualification of adjacent systems.
- Capex intensity for REACH dossier expansion:European substance registration burdens favor incumbents with established portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyimide Foam Market |
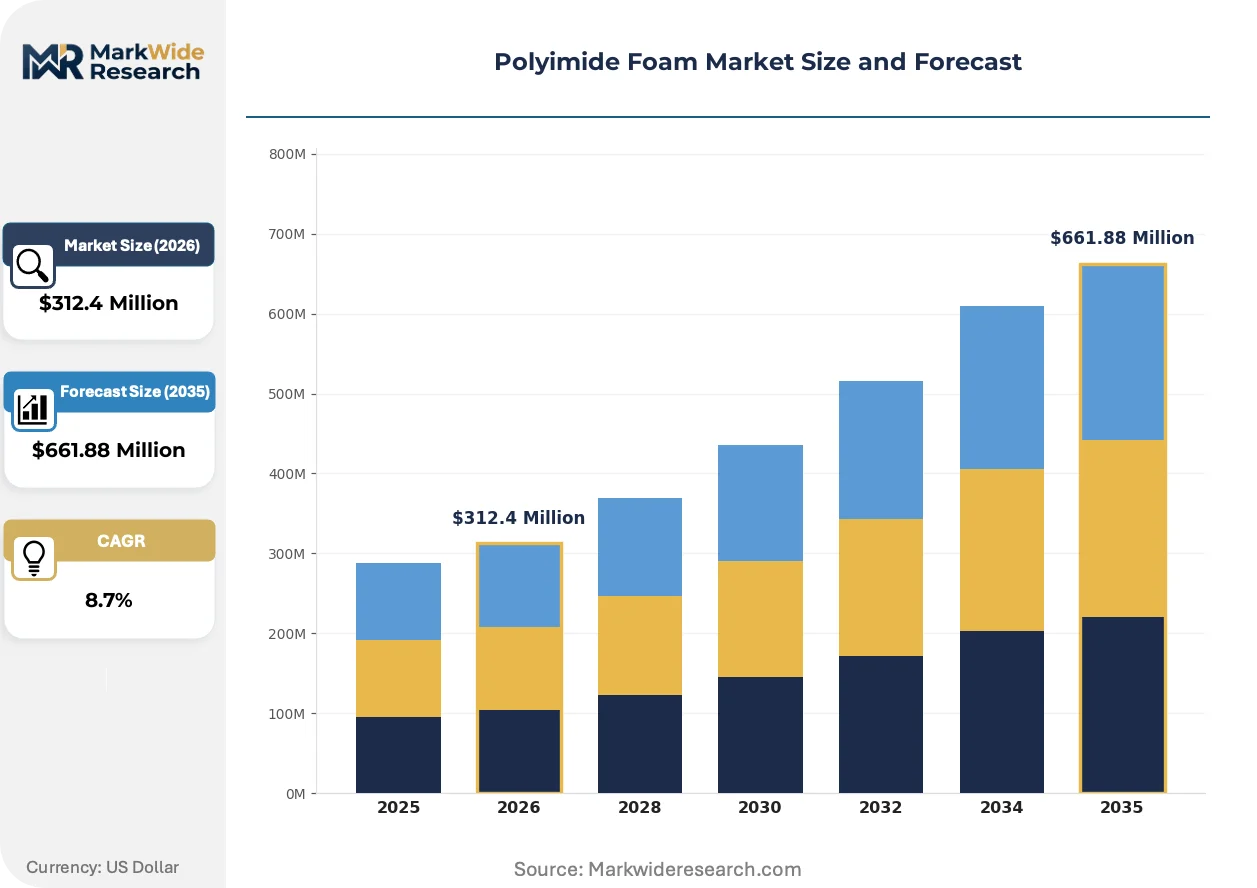
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Core Foam, Flexible Foam, Rigid Foam, High-Temperature Foam End User: Aerospace, Automotive, Electronics, Industrial Application: Insulation, Soundproofing, Thermal Protection, Structural Support Form: Sheets, Blocks, Custom Shapes, Rolls |
| Companies Covered | Boyd Corporation, DuPont, Evonik Industries, UFP Technologies, Polymer Technologies, Soundown, Trelleborg, Rogers Corporation, Kaneka Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyimide Foam Market Strategic Shifts
Material scientists are converging on manufacturing processes that eliminate volatile byproducts while expanding service temperature windows. These advances are redefining competitive differentiation around environmental compliance and extreme-environment performance.
Supercritical CO2 foaming technology is supplanting traditional solvent-based expansion methods in closed-cell polyimide production. Aerospace tier-one suppliers are specifying CO2-processed stock for new platform introductions to preempt regulatory non-compliance. This process shift is compressing the viable supplier base to firms with capital-intensive pressurized reactor infrastructure.
REACH substance registration requirements are tightening documentation burdens for aromatic diamine precursors entering European manufacturing. ECHA compliance costs are favoring integrated producers with captive precursor supply over merchant market buyers. Flexible foam grades for aircraft cabin insulation face the steepest registration cost escalation relative to volume.
Long-term supply agreements are displacing spot purchasing for qualified thermal insulation in commercial aviation programs. Boeing and Airbus procurement offices are compressing vendor lists to three approved suppliers per platform to reduce qualification overhead. This consolidation pattern is most visible in Germany's advanced manufacturing corridor where tier-one converters anchor regional demand clusters.
Polyimide Foam Market Segmentation
Segmentation in polyimide foam reveals how technical specifications dictate channel access and margin capture. Product architecture, end-use certification requirements, and form factor constraints each reshape competitive positioning across the value chain.
Product Type:
Flexible foam and rigid grades flow through distinct channel structures—tier-one aerospace converters versus specialized structural fabricators—while high-temperature formulations command direct OEM relationships bypassing distribution layers.
- Flexible Foam:Open-cell aromatic polymer structures dominate aircraft cabin insulation and electronics packaging applications. Demand clusters in Germany's advanced manufacturing corridor where Boeing and Airbus procurement offices consolidate vendor lists around qualified thermal insulation suppliers.
- High-Temperature Foam:Closed-cell formulations engineered for continuous service exceeding 300°C serve hypersonic propulsion programs and next-generation launch vehicles. Defense procurement agencies in the United States and France are elevating thermal performance benchmarks, pulling specification thresholds upward.
- Core Foam:Lightweight sandwich panel infill for aerospace structural applications.
- Rigid Foam:Load-bearing thermal protection for reusable rocket programs.
By volume, flexible foam leads. By growth pace, high-temperature foam is climbing the fastest.
End User:
Cost tier segmentation separates qualification-intensive aerospace buyers from price-sensitive industrial purchasers, with automotive and electronics occupying intermediate positions.
- Aerospace:FAA and EASA airworthiness standards govern material flammability and smoke toxicity, directly dictating which foam grades achieve platform qualification. Tier-one suppliers in Toulouse, Hamburg, and Seattle compress vendor lists to three approved suppliers per platform.
- Electronics:Outgassing properties and thermal management specifications drive specification in semiconductor packaging and battery modules. Silica aerogel blankets capture share in sub-200°C applications where weight minimization dominates.
- Automotive:Thermal barrier applications in electric vehicle battery enclosures and exhaust systems.
- Industrial:Process equipment insulation and high-temperature gasket applications.
Aerospace commands premium pricing. Electronics is gaining share fastest in volume terms.
Application:
Application mix determines margin structure—thermal protection and structural support carry qualification premiums while insulation and soundproofing compete on specification compliance.
- Thermal Protection:Re-entry vehicle heat shields, rocket nozzle insulation, and hypersonic leading edges require combined ablative and insulative performance. Defense agencies in the United States, France, and the United Kingdom fund development programs.
- Structural Support:Rigid foam grades integrate thermal protection with load-bearing capacity in reusable launch vehicle structures. Premium positioning reflects combined mechanical and thermal qualification requirements.
- Insulation:Lightweight thermal barriers for aircraft fuselages and industrial equipment.
- Soundproofing:Acoustic attenuation in aircraft engine nacelles and cabin partitions.
Insulation leads by installed volume. Structural support shows the steepest expansion trajectory.
Form:
Form factor segmentation tracks customer integration capability—sheets and rolls for high-volume converters versus custom shapes for specialized assembly operations.
- Custom Shapes:CNC-machined or thermoformed components for complex geometric integration in satellite structures and aircraft ducting. Boyd Corporation and similar converters anchor demand in Germany's advanced manufacturing corridor.
- Sheets:Standardized stock for downstream fabrication into cabin insulation panels and electronics substrates. Long-term supply agreements displace spot purchasing as Boeing and Airbus procurement offices reduce qualification overhead.
- Blocks:Billet stock for machining specialized components.
- Rolls:Continuous format for automated cutting and lamination processes.
Sheets dominate by shipment volume. Custom shapes are expanding most quickly in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness standards anchor the United States as the primary demand geography, with EASA certification requirements in Germany and France forming a secondary regulatory pole. Procurement consolidation by Boeing and Airbus compresses vendor lists around qualified suppliers in specific industrial corridors.
United States
Hypersonic propulsion programs at defense agencies pull specification thresholds toward high-temperature foam grades exceeding 300°C continuous service. EPA volatile organic compound regulations constrain solvent-based production methods and favor water-blown or supercritical CO2 processes. Seattle anchors commercial aviation demand clusters where Boeing procurement offices consolidate vendor lists to three approved suppliers per platform.
Germany
The EU Green Deal's industrial emissions framework accelerates replacement of hydrocarbon-based insulation in advanced manufacturing corridors. ECHA compliance costs favor integrated producers with captive precursor supply over merchant market buyers. Hamburg and Munich host tier-one converter operations where Boyd Corporation and similar firms process raw polyimide stock into application-specific thermal management assemblies.
France
Defense procurement agencies fund development programs for re-entry vehicle heat shields and rocket nozzle insulation requiring combined ablative and insulative performance. REACH substance registration requirements tighten documentation burdens for aromatic diamine precursors entering European manufacturing. Toulouse concentrates aerospace tier-one supplier activity around Airbus final assembly lines.
Japan
METI industrial policy supports domestic precursor manufacturing capabilities for high-performance polymer supply security. JIS standards govern material specifications in electronics packaging applications where outgassing properties drive semiconductor procurement decisions. The Osaka-Kobe chemical corridor clusters pyromellitic dianhydride manufacturing capacity serving regional foam producers.
India
The PLI scheme for aerospace component manufacturing draws precursor conversion investments toward subcontinent assembly operations. BIS standards increasingly align with FAA and EASA thermal performance benchmarks for export-oriented suppliers. Karnataka and Maharashtra host emerging converter facilities targeting tier-one supplier qualification for commercial aviation programs.
Polyimide Foam Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with DuPont and Evonik Industries commanding positions through century-long fluoropolymer expertise and integrated precursor manufacturing respectively. DuPont leverages historical capabilities in high-temperature foam architectures while Evonik anchors European supply through captive production at its Marl site. The competitive field separates into three archetypes: integrated chemical conglomerates with backward control over pyromellitic dianhydride supply, specialized converters transforming raw stock into application-specific assemblies, and regional fabricators serving qualified supplier networks. Dominant competitive moves include strategic partnerships with established qualified suppliers to bypass internal certification cost absorption, and capacity expansion in supercritical CO2 foaming infrastructure to preempt EPA regulatory non-compliance.
Among the named players in raw data, DuPont exemplifies the integrated chemical archetype with century-spanning polymer expertise, while Evonik Industries occupies a parallel position through its Marl-integrated precursor manufacturing. Boyd Corporation represents the specialized converter tier, anchoring demand in Germany's advanced manufacturing corridor through application-specific thermal management assembly production. These three firms illustrate how competitive positioning stratifies across upstream chemical integration, midstream conversion capabilities, and downstream qualification relationships with aerospace tier-one suppliers.
| Leading Market Players |
|---|
| Boyd Corporation |
| DuPont |
| Evonik Industries |
| UFP Technologies |
| Polymer Technologies |
| Soundown |
| Trelleborg |
| Rogers Corporation |
| Kaneka Corporation |
| Others |
Value Chain & Pricing Dynamics
Ninety-day qualification timelines for aerospace foam grades compress negotiation windows and amplify supplier pricing power for incumbent qualified vendors. This lead-time rigidity concentrates margin capture among firms with established EASA and FAA dossiers while forcing tier-two converters into spot-market precursor purchasing at volatile aromatic dianhydride pricing.
Pricing Analysis
Transatlantic price spreads of 15-25 percent separate German advanced manufacturing corridor deliveries from US Gulf Coast sourcing points for equivalent flexible foam grades. Three-tier pricing structure across aerospace-qualified, industrial-grade, and merchant-market levels dominates contract structures, with certification tier and volume scale as primary differentiation drivers. Pricing pressure stems from silica aerogel substitution in sub-200°C electronics packaging where weight minimization trumps thermal performance. Electronics packaging buyers exhibit highest price sensitivity while hypersonic propulsion program offices absorb premium positioning for high-temperature formulations.
Supply Chain Analysis
Pyromellitic dianhydride precursor manufacturing clusters in Germany's Marl chemical corridor and Japan's Osaka-Kobe corridor create single-source vulnerability for non-integrated foam producers. Raw material dependencies rest on aromatic diamine feedstocks, anhydride intermediates, and specialized blowing agents for supercritical CO2 processes. Tariff exposure on Chinese-origin chemical inputs threatens margin stability for merchant-market buyers lacking captive precursor supply. Distribution runs through long-term supply agreements with Boeing and Airbus tier-one converters, displacing spot purchasing in qualified aerospace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyimide foam sits in early-cycle expansion as hypersonic propulsion programs and reusable launch vehicle architectures pull specification thresholds beyond legacy hydrocarbon insulation capabilities.
For Market Incumbents: Consolidate formulation talent pools through targeted acquisition of specialized polymer chemistry teams to defend against DuPont and Evonik's incumbent talent capture. Anchor backward integration into pyromellitic dianhydride supply at Marl-scale chemical corridors to neutralize precursor price volatility. Expand supercritical CO2 foaming capacity ahead of EPA volatile organic compound enforcement windows to preempt regulatory displacement of solvent-based competitors. For New Entrants and Emerging Players: Differentiate on digital qualification platforms offering blockchain-tracked certification documentation to streamline EASA and FAA airworthiness approval workflows. Target India's PLI scheme aerospace component clusters where precursor conversion investments face lower qualification overhead than established German and US corridors. Pursue joint-venture structures with established qualified suppliers to bypass internal certification cost absorption and accelerate platform access. For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials compounder play because thermal protection requirements in next-generation propulsion systems structurally expand addressable market boundaries. Acquisition targets should emphasize integrated producers with captive precursor supply and established REACH dossier portfolios. Monitor defense procurement agency thermal performance benchmark elevations as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Captive pyromellitic dianhydride supply at Marl-scale chemical corridors neutralizes input price volatility for foam producers. |
| Supercritical CO2 Foaming Capacity Expansion | EPA volatile organic compound regulations favor water-blown or CO2-based processes over solvent-based production methods. |
| Digital Qualification Platform Development | Blockchain-tracked certification documentation streamlines EASA and FAA airworthiness approval workflows for aerospace tier-one suppliers. |
| Long-term Supply Agreement Structuring | Boeing and Airbus procurement offices compress vendor lists to three approved suppliers per platform, locking in volume commitments. |
| Specialized Polymer Chemist Acquisition | Formulation expertise concentration among large incumbents restricts smaller firms from staffing development labs. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with aerospace procurement officers, thermal management engineers at tier-one suppliers, chemical plant managers, and regulatory affairs specialists; and secondary validation through FAA airworthiness filings, EASA certification databases, EPA enforcement records, and customs trade data for pyromellitic dianhydride movements. Bottom-up triangulation across foam grade shipment volumes and top-down reconciliation against aerospace platform build rates anchored value estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions including foam architecture (flexible, rigid, high-temperature), end-use certification tier (aerospace-qualified versus industrial), and geographic production hub (German advanced manufacturing corridor, US defense procurement clusters, Japanese electronics packaging centers). CAGRs derived from elasticity-adjusted demand curves incorporating hypersonic program funding trajectories and REACH compliance cost escalations.
Material uncertainties — defense procurement cancellations, REACH substance registration rejections for aromatic diamine precursors, and aerogel technology breakthroughs in sub-300°C applications — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as thermal performance benchmarks from defense agencies and EU Green Deal industrial emissions frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Global Cellulose Esters Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Conductive Carbon Black Market
Specialty Materials
Solar Backsheet Films Market
Specialty Materials
Semiconductor O-Rings Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Reflective Polarizing Films Market
Specialty Materials
Light Diffusion Materials Market
Specialty Materials
Specialty Coating Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Latin America International CEP Market
Specialty Materials
South America Polyether Ether Ketone (Peek) Market
Specialty Materials
Asia Pacific Cellulose Acetate Market