
 Global Synthetic Zeolite Market | 2026-2036
Global Synthetic Zeolite Market Size, Share, and Industry Trends Forecast 2026-2036
Global Synthetic Zeolite Market Foresight
Chinese producers is pivoting toward higher-purity Zeolite Y output for FCC catalyst applications. Albemarle Corporation leverages its bromine-zeolite integration to control specialty catalyst supply chains across North American refineries. Zeolyst International anchors its position through molecular sieve technology leadership in gas separation membranes.
Synthetic zeolites are crystalline aluminosilicate materials with uniform pore diameters typically ranging from 3 to 10 angstroms, manufactured through hydrothermal crystallization of silica-alumina gels to perform selective adsorption, ion exchange, and catalytic functions. Powder formulations dominate detergent applications due to superior dispersibility in washing cycles, while pelletized zeolites command premium positioning in petrochemical catalytic reactors where pressure-drop management determines operational efficiency. Gas separation applications represent the fastest-expanding segment as hydrogen purification and carbon capture installations multiply.
EPA emission mandates and REACH chemical safety protocols jointly determine product certification pathways for zeolite manufacturers seeking cross-border market access. China's GB standards and MEE environmental enforcement create parallel compliance requirements for producers targeting Asia-Pacific industrial buyers. Stakeholders must evaluate regulatory divergence between EPA and MEE frameworks when siting new production capacity or reformulating product grades for multi-regional supply.
Market Dynamics
Phosphate-ban regulations across Southeast Asian detergent markets are forcing rapid substitution toward zeolite builders, while FCC catalyst replacement cycles accelerate under tightening EPA emission standards along the US Gulf Coast.
Growth Catalysts
- MEE Environmental Enforcement:China's Ministry of Ecology and Environment is tightening industrial discharge permits, compelling detergent manufacturers to abandon phosphates for zeolite alternatives in washing powder formulations.
- Fluid Catalytic Cracking Units:Petrochemical refiners in India and China are expanding FCC capacity to process heavier crude slates, driving Zeolite Y consumption for catalyst matrices that handle high metals feedstock.
- Hydrogen Purification Membranes:Gas separation applications are multiplying as carbon capture installations and blue hydrogen projects deploy molecular sieve technology for selective CO2 removal.
Market Restraints
- Alumina Supply Concentration:Specialty-grade alumina feedstock for high-purity zeolite synthesis concentrates among limited bauxite refiners in Australia and Guinea, exposing producers to raw material volatility.
- Energy-Intensive Hydrothermal Crystallization:Zeolite manufacturing requires sustained high-temperature processing, making production costs vulnerable to natural gas price swings and carbon border adjustment mechanisms.
- Silica Gel Substitution:Advanced desiccant applications in electronics packaging are partially migrating toward engineered silica gels and metal-organic frameworks with tunable pore architectures.
Strategic Opportunities
- Direct Air Capture Installations:Emerging carbon removal facilities in Iceland and the United States are piloting zeolite sorbents for low-concentration CO2 capture, creating demand for specialized lithium-exchanged formulations.
- India's Phosphate Ban Cascade:State-level detergent regulations in Maharashtra and Tamil Nadu are replicating Southeast Asian phosphate restrictions, opening fresh builder-grade zeolite demand from domestic formulators.
- Membrane Reactor Convergence:Catalytic membrane reactors combining zeolite films with palladium hydrogen separation layers are enabling compact process intensification for ammonia and methanol producers.
Industry Challenges
- Crystallization Process Control:Achieving uniform particle size distribution in Zeolite Y synthesis requires precise control of gel aging and seeding protocols, with batch-to-batch variability causing downstream catalyst performance drift.
- REACH Registration Timelines:European Chemicals Agency substance dossiers for novel zeolite compositions face extended evaluation periods, delaying market access for modified framework topologies targeting specialty adsorption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Synthetic Zeolite Market |
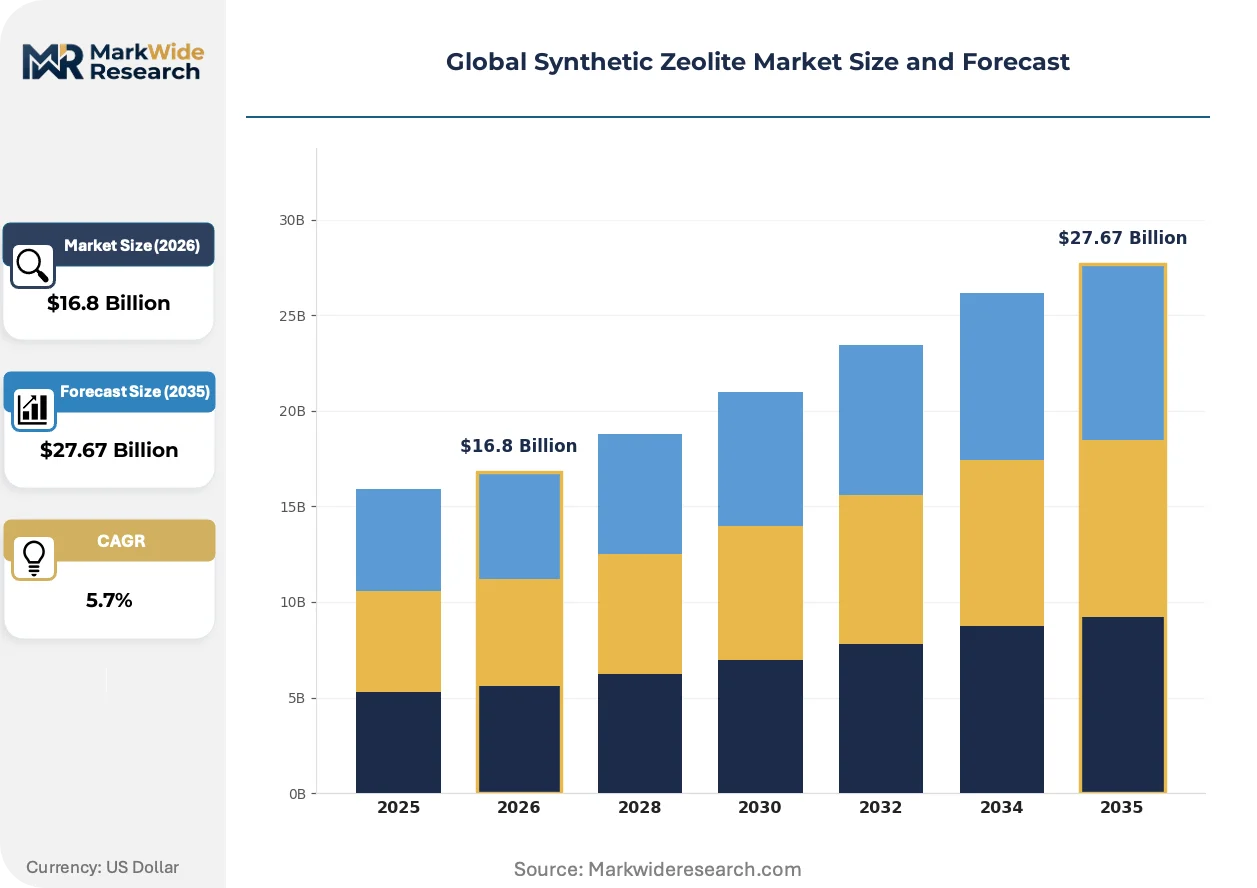
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $27.67 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zeolite A, Zeolite X, Zeolite Y, SAPO, MCM-41, Others Application: Detergents, Catalysts, Gas Separation, Water Treatment, Petrochemicals, Animal Feed Form: Powder, Granules, Pellets, Beads End User Industry: Chemical Manufacturing, Oil Refineries, Environmental Services, Agriculture, Animal Nutrition |
| Companies Covered | Albemarle Corporation, Zeolyst International, BASF SE, Zeochem AG, PQ Corporation, Honeywell International Inc., Arkema SA, Tosoh Corporation, Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Synthetic Zeolite Market Shifts & Advancements
Zeolite manufacturers are racing to customize framework compositions for emerging hydrogen and carbon capture applications, while regulatory pressure on phosphate detergents accelerates product reformulation cycles.
Core-shell zeolite architectures with hierarchical mesoporosity are integrating secondary pore networks into conventional microporous crystals. Petrochemical catalyst suppliers are adopting these structures to reduce diffusion limitations in FCC units processing resid feedstock. This integration is compressing the performance gap between synthetic zeolites and more expensive structured catalyst supports.
REACH chemical safety protocols are expanding registration requirements for nano-scale zeolite powders used in consumer products. The European Chemicals Agency's updated guidance on substance characterization is forcing detergent manufacturers to secure extended safety data sets for builder-grade zeolites. Formulators targeting EU market access are responding by consolidating supplier relationships with REACH-registered producers possessing complete toxicological dossiers.
Refinery procurement departments are compressing catalyst replacement cycles from annual to semi-annual intervals under EPA emission mandates. Long-term supply agreements with fixed pricing are displacing spot purchasing for FCC catalysts, particularly among US Gulf Coast operators facing continuous monitoring requirements. This pattern is most pronounced in Texas and Louisiana, where refiners prioritize supply security over unit cost optimization.
Global Synthetic Zeolite Market Segmentation
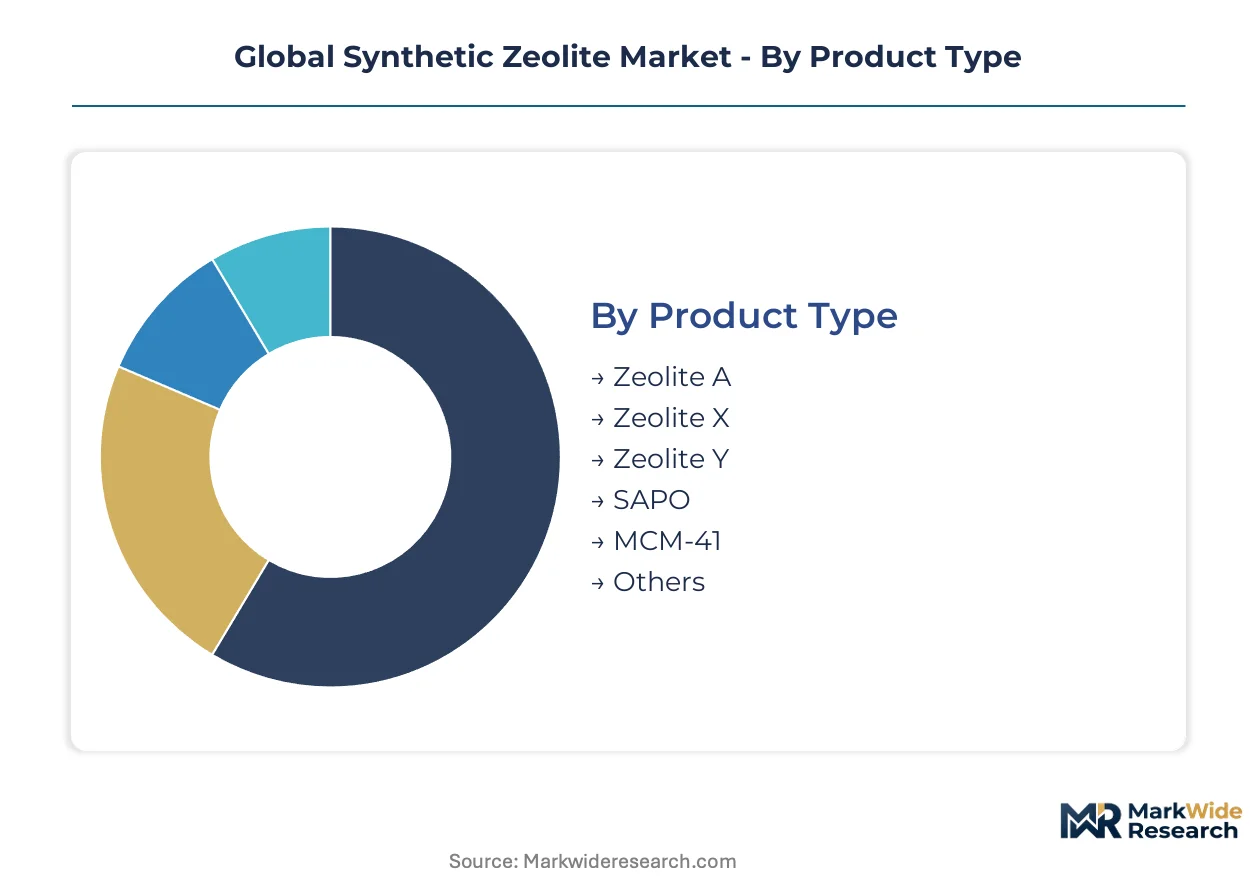
Zeolite manufacturers configure production lines around crystalline topology and pore architecture, with each framework type commanding distinct feedstock specifications and crystallization protocols. Product differentiation across form factors and end-use specifications determines margin capture and customer lock-in for specialty aluminosilicate suppliers.
Product Type:
Supply concentration clusters around Zeolite Y capacity along the US Gulf Coast and Zeolite A manufacturing in China's Shandong and Jiangsu provinces, where bauxite refiners anchor alumina feedstock security.
- Zeolite Y:Faujasite framework with 7.4 angstrom supercage apertures optimized for fluid catalytic cracking catalyst matrices. FCC units in Texas and Louisiana consume the majority of high-purity output under EPA-mandated replacement cycles.
- Zeolite A:LTA topology with 4.1 angstrom alpha cages serving as the primary phosphate substitute in detergent builder applications. Southeast Asian formulators in Indonesia and Vietnam are scaling purchases as national phosphate bans take effect.
- Zeolite X:Higher silica-to-alumina ratio variant of faujasite structure for selective gas adsorption in pressure swing units.
- SAPO:Silicoaluminophosphate molecular sieves with Bronsted acid sites for methanol-to-olefin catalysis.
- MCM-41:Mesoporous silica-alumina with tunable 20-100 angstrom pore diameters for large-molecule catalytic cracking.
- Others:Specialty frameworks including ZSM-5, beta zeolites, and custom-synthesized compositions for proprietary separation processes.
Zeolite Y absorbs the bulk of installed capacity; MCM-41 is expanding most quickly as refiners process heavier resid feedstock.
Application:
Cost tier stratification separates commodity detergent builders from premium FCC catalyst formulations, with gas separation membranes commanding the highest unit economics per kilogram.
- Catalysts:Zeolite Y and ZSM-5 frameworks embedded in petroleum refining and petrochemical processes. Indian refiners are expanding FCC capacity to process high-metals crude slates, driving matrix consumption.
- Gas Separation:Molecular sieve adsorbents for hydrogen purification, air separation, and carbon capture installations. Blue hydrogen projects in the United States and carbon capture pilots in Iceland are deploying lithium-exchanged formulations.
- Detergents:Builder-grade Zeolite A powder as phosphate replacement in washing powder formulations.
- Water Treatment:Ion exchange media for heavy metal removal and radionuclide capture in industrial effluent.
- Petrochemicals:Acidic zeolite catalysts for alkylation, isomerization, and aromatics processing.
- Animal Feed:Mycotoxin-binding clinoptilolite and synthetic analogues for livestock nutrition.
Catalyst applications dominate revenue contribution; gas separation is climbing the fastest as hydrogen infrastructure scales.
Form:
Customer type determines form factor selection, with powder specifications locked by detergent formulators and pellet geometries engineered to refinery reactor pressure-drop constraints.
- Powder:Fine particulate zeolites with high surface area for rapid dissolution and dispersion. Detergent manufacturers in Maharashtra and Tamil Nadu specify precise particle size distributions for washing powder integration.
- Pellets:Extruded cylindrical forms with controlled crush strength and pressure-drop characteristics. FCC catalyst manufacturers bind zeolite Y into alumina-matrix pellets for fluidized bed reactors.
- Granules:Intermediate particle size for fixed-bed adsorption systems in air drying and hydrocarbon purification.
- Beads:Spherical forms for packed column applications requiring uniform flow distribution and minimal attrition.
Powder absorbs the bulk of installed capacity; pellets are gaining share fastest as refinery catalyst replacement cycles compress.
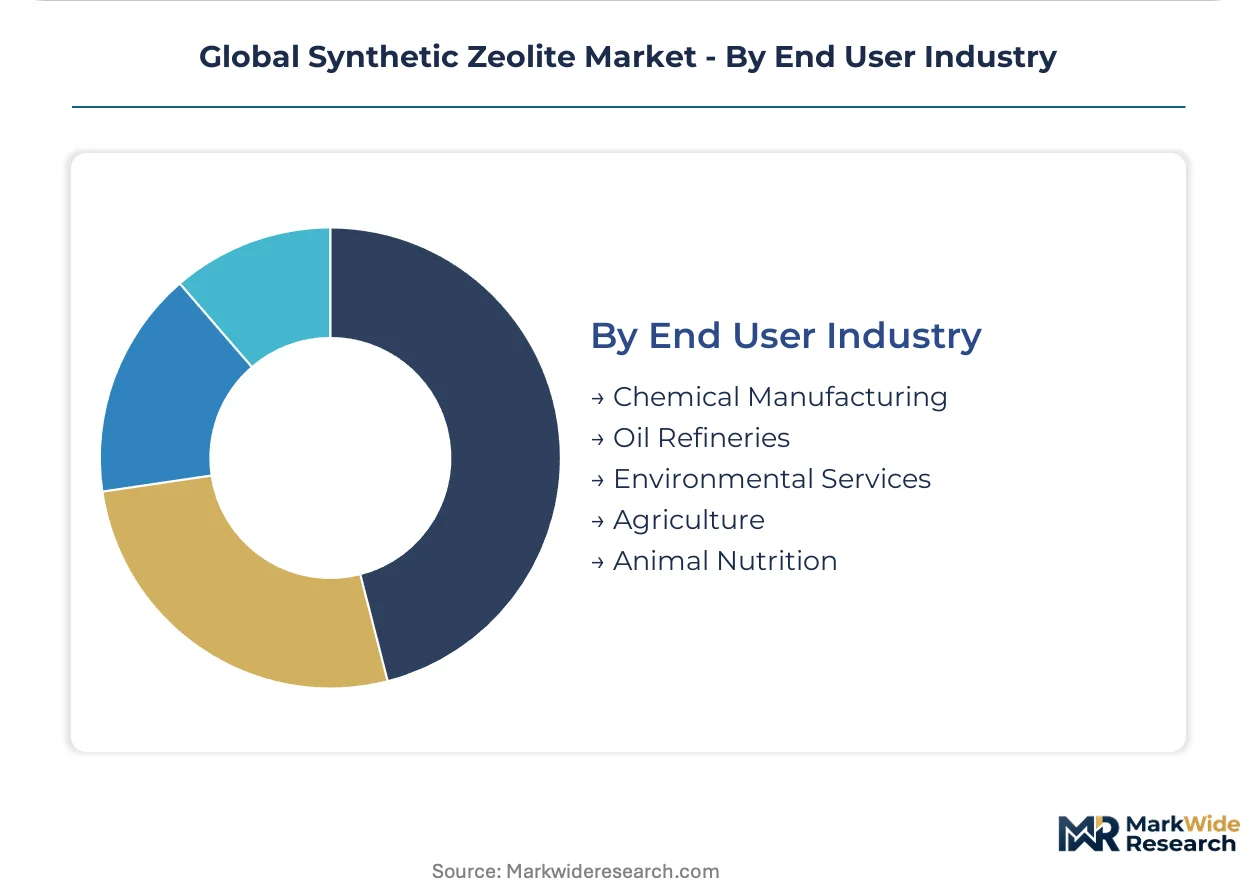
End User Industry:
Volume concentration in oil refineries contrasts with emerging demand from environmental services contractors deploying carbon capture and direct air capture systems.
- Oil Refineries:Integrated FCC unit operators consuming catalyst matrices and hydrocracking additives. US Gulf Coast refiners in Texas and Louisiana prioritize supply security through long-term offtake agreements.
- Chemical Manufacturing:Petrochemical producers utilizing zeolite catalysts for methanol-to-olefins, xylene isomerization, and ethanol dehydration.
- Environmental Services:Carbon capture developers and water treatment operators deploying molecular sieve technology.
- Agriculture:Soil amendment and controlled-release fertilizer applications using natural and synthetic zeolite minerals.
- Animal Nutrition:Feed additive formulators incorporating mycotoxin binders and rumen buffers.
Oil refineries absorb the bulk of installed capacity; environmental services is expanding most quickly as carbon removal installations multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bauxite refiners in Australia's Queensland and Guinea's Boké region anchor alumina feedstock security for high-purity zeolite synthesis, shaping production economics across three continents.
United States
Petrochemical refiners along the Texas and Louisiana Gulf Coast compress FCC catalyst replacement cycles under EPA emission mandates. Long-term offtake agreements displace spot purchasing as operators prioritize supply security over unit cost. Houston anchors the majority of Zeolite Y consumption for fluid catalytic cracking units.
China
Shandong and Jiangsu provinces concentrate Zeolite A manufacturing capacity for detergent builder applications. MEE environmental enforcement tightens industrial discharge permits, compelling formulators to abandon phosphates. Qingdao-based producers pivot toward higher-purity Zeolite Y output for FCC catalyst matrices.
India
State-level phosphate bans in Maharashtra and Tamil Nadu replicate Southeast Asian detergent restrictions. Refiners expand FCC capacity to process high-metals crude slates, driving Zeolite Y consumption for catalyst matrices. Mumbai and Chennai industrial corridors attract domestic formulator investment.
Germany
REACH chemical safety protocols expand registration requirements for nano-scale zeolite powders in consumer products. ECHA substance dossiers for novel compositions face extended evaluation periods. Ludwigshafen and Leverkusen chemical clusters concentrate specialty catalyst R&D.
Indonesia
National phosphate-ban regulations force rapid detergent-grade zeolite substitution across washing powder formulations. Jakarta and Surabaya manufacturing bases scale builder-grade imports from Chinese suppliers. Domestic formulators consolidate supplier relationships with REACH-registered producers.
Global Synthetic Zeolite Market Competitive Landscape
Global majors compete with regional champions across crystallization technology and feedstock integration. The vendor base clusters around three tiers: integrated petrochemical conglomerates with captive alumina supply, specialty aluminosilicate houses focused on catalyst matrices, and regional detergent-grade producers serving phosphate-replacement demand. Strategic moves concentrate on backward integration into bauxite refining and technology licensing for hierarchical mesoporous architectures.
Within the integrated chemical conglomerate tier, BASF SE and Albemarle Corporation exemplify positions anchored by bromine-zeolite integration and petrochemical catalyst supply chain control. Among specialty molecular sieve houses, Zeolyst International occupies a position representing technology leadership in gas separation membranes. These three entities sit within distinct competitive archetypes: feedstock-integrated multinational, catalyst-specialist with refinery relationships, and membrane-technology innovator.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Zeolyst International |
| BASF SE |
| Zeochem AG |
| PQ Corporation |
| Honeywell International Inc. |
| Arkema SA |
| Tosoh Corporation |
| Clariant |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap producers in China's Shandong province anchor much of the world's detergent-grade zeolite capacity, their concentrated ownership enabling disciplined capacity management that buffers price volatility even as energy costs swing. This supply-side consolidation grants pricing power to compliant incumbents while forcing buyers into longer-term offtake negotiations to secure volume.
Pricing Analysis
Technical service bundling separates premium FCC catalyst suppliers from commodity detergent-grade producers, with Zeolyst International and Albemarle Corporation embedding crystallization expertise and catalyst performance warranties into long-term supply agreements. Three-tier pricing structure across premium catalyst matrices, standard builder powders, and economy-grade water treatment media reflects certification tier and REACH registration status. Cost compression in detergent-grade powder is intensifying because Chinese overcapacity and Southeast Asian import competition erode margins. Detergent formulators in Vietnam and Indonesia exhibit highest price sensitivity, while US Gulf Coast refiners prioritize supply security and technical support over unit cost optimization.
Supply Chain Analysis
Specialty-grade alumina feedstock rests on bauxite refiners in Australia's Queensland and Guinea's Boké region, with limited alternative sourcing for high-purity gibbsite required in Zeolite Y synthesis. Silica sources from US Gulf Coast chemical complexes and Chinese feldspar processors complete the input base. Single-source vulnerability concentrates in Australian alumina supply, where port congestion and export licensing delays propagate through crystallization schedules. Distribution runs through integrated petrochemical distributors for refinery catalysts and regional chemical traders for detergent-grade powder in Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical safety protocols and EPA emission mandates erect formidable compliance moats, with registration timelines and toxicological dossier requirements filtering out undercapitalized competitors and rewarding producers with established regulatory infrastructure.
For Market Incumbents: Anchor supply security through backward integration into bauxite refining partnerships in Guinea or Australia, insulating against alumina price volatility that compresses crystallization margins. Defend against emerging metal-organic framework substitutes in electronics desiccant applications by accelerating hierarchical mesoporous R&D for gas separation membranes. For New Entrants and Emerging Players: Carbon capture engineering contractors represent the most penetrable channel partner type, their project pipelines hungry for lithium-exchanged zeolite sorbents not yet locked into incumbent supply agreements. Target direct air capture pilots in Iceland and the United States, where novel formulation requirements and limited qualified suppliers create white-space entry. Lead with technical collaboration models that co-develop customized framework compositions rather than competing on commodity detergent-grade volume. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty aluminosilicate houses with REACH-registered dossiers and established refinery relationships in Texas and Louisiana, their compliance assets appreciating as regulatory barriers thicken. Long-term viability hinges on hydrogen economy positioning, with carbon capture and blue hydrogen infrastructure scaling across the projection horizon. Watch MEE enforcement intensity in China as the inflection signal—tightening discharge permits accelerate phosphate substitution and concentrate demand among compliant domestic producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Refining | Captive alumina supply from Guinea's Boké region secures feedstock against price volatility and export restrictions. |
| Long-term Supply Agreement | US Gulf Coast refiners under EPA mandates prioritize supply security through multi-year FCC catalyst offtake contracts. |
| Green Manufacturing Transition | Carbon border adjustment mechanisms in Europe reward low-carbon hydrothermal crystallization powered by renewable energy. |
| Joint Venture | Carbon capture developers in Iceland partner with zeolite specialists to co-develop lithium-exchanged sorbent formulations. |
| Capacity Expansion | Qingdao-based producers pivot Zeolite A lines toward higher-purity Zeolite Y for Indian and Chinese FCC unit growth. |
Research Methodology
Trade databases, SEC filings from listed chemical conglomerates, and ECHA REACH registration records formed the secondary backbone, cross-referenced with primary interviews involving zeolite plant managers, FCC procurement leads at US Gulf Coast refineries, detergent formulator technical directors, and specialty alumina traders. Bottom-up crystallization capacity estimates and top-down end-use consumption models were triangulated to reconcile supply-side and demand-side perspectives across the analysis window.
Historical trendline analysis of Zeolite Y and Zeolite A production volumes established baseline growth patterns, with forward projections incorporating framework type, application segment, form factor, and regional regulatory cluster as segmentation dimensions. CAGRs were derived through regression analysis of correlated industrial indicators including FCC unit operating rates, phosphate-ban implementation timelines, and hydrogen project development pipelines. Energy cost trajectories and carbon border adjustment mechanisms were modeled as scenario-dependent inputs.
Caveats apply where alumina supply disruptions, MEE enforcement intensity fluctuations, or metal-organic framework substitution breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory implementation schedules and industrial capacity expansion plans. A small set of named triggers—REACH dossier evaluation delays, Indonesian import tariff revisions, and direct air capture technology maturation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Europe Textile Films Market
Specialty Materials
Halloysite Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
Super Engineering Plastics Market
Specialty Materials
Rigid Polyurethane Foams Market
Specialty Materials
Asia-Pacific Green Sic Market
Specialty Materials
Alginate Films Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
Magnesium Fluoride Market
Specialty Materials
Silicone Solutions Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Specialty Carbon Black Market
Specialty Materials
Carbon Mold Market
Specialty Materials
Lab Grown Diamonds Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Polyimide Foam Market