
 Cellulose Gel Market | 2026-2036
Cellulose Gel Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulose Gel Market Analysis
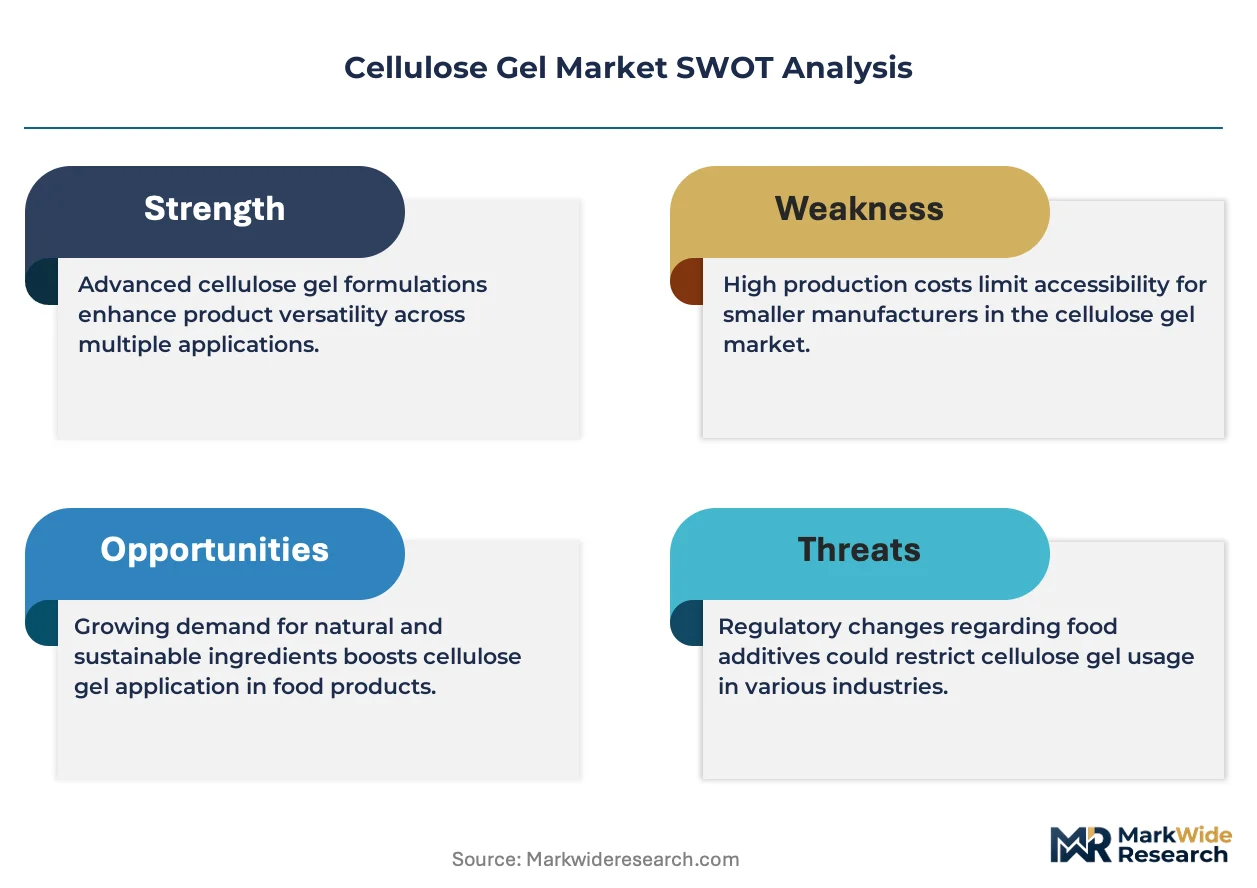
Pharmaceutical excipient demand is recalibrating the Cellulose Gel competitive landscape as oral solid dosage formulations expand. J. Rettenmaier & Söhne GmbH + Co KG anchors European supply through specialized microcrystalline cellulose production. Ashland Global Specialty Chemicals Inc. leverages polymer science expertise across pharmaceutical and personal care verticals. Roquette competes with plant-derived excipient portfolios that align with biopharma sourcing preferences.
Cellulose gel comprises refined cellulose polymers processed through controlled hydrolysis or etherification to achieve specific viscosity, particle size, and hydration profiles for industrial binding, thickening, and stabilizing functions. Microcrystalline cellulose dominates pharmaceutical-grade applications where compaction and flow properties determine tablet performance, while carboxymethyl cellulose captures food and beverage thickening demand where cold-water solubility and clarity standards apply. Hydroxypropyl methylcellulose occupies the fastest-expanding niche in controlled-release drug delivery and vegan capsule formulations.
FDA excipient guidelines and EMA quality standards govern cellulose gel purity, residual solvent limits, and documentation requirements for pharmaceutical applications. REACH compliance in Europe and FSSAI food additive regulations in India shape regional product specifications and market access conditions. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP monographs to anticipate qualification burdens and sourcing flexibility requirements.
Market Dynamics
Pharmaceutical-grade cellulose gel specifications are tightening as USP-NF, EP, and JP monograph harmonization accelerates, forcing excipient manufacturers to recalibrate purity documentation and residual solvent testing protocols across multiple regulatory jurisdictions simultaneously.
Growth Catalysts
- Controlled-release drug delivery expansion:Hydroxypropyl methylcellulose matrix systems are capturing oral solid dosage reformulations as bioavailability engineering demands intensify across FDA-regulated markets.
- EMA quality standard elevation:Stricter residual solvent limits and elemental impurity thresholds are disqualifying lower-grade suppliers and consolidating procurement toward certified excipient specialists.
- Vegan capsule formulation surge:Plant-derived alternatives to gelatin are driving hydroxypropyl methylcellulose demand in Germany, Japan, and the United States as clean-label pharmaceutical positioning hardens.
Market Restraints
- Purified cotton linters supply concentration:Pharmaceutical-grade cellulose feedstock depends on concentrated cotton processing regions, exposing formulators to agricultural yield volatility and climate-driven price swings.
- Carboxymethyl cellulose substitution pressure:Xanthan gum and guar gum variants are capturing certain food thickening applications where cold-water solubility requirements are less stringent.
- REACH registration cost burden:ECHA compliance documentation for cellulose ether derivatives imposes fixed cost barriers that disproportionately constrain mid-scale specialty chemical entrants.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO excipient qualification pathways and FSSAI food additive approvals are creating dual-use certification opportunities for cellulose gel suppliers targeting domestic and export markets.
- Personal care microplastic replacement:Microcrystalline cellulose bead technologies are capturing cosmetic exfoliant applications as EU microplastic restrictions under REACH annex amendments take effect.
- 3D printed pharmaceutical prototyping:Binder jetting and fused deposition modeling of cellulose-based excipient matrices is expanding into early-stage formulation development at contract research organizations.
Industry Challenges
- Multinational pharmacopeial harmonization lag:Discrepancies between USP-NF, EP, and JP testing methodologies force redundant analytical validation and extend excipient qualification timelines.
- Specialized process engineering scarcity:Controlled hydrolysis and etherification reactor operation requires expertise that concentrates among aging technical workforces in European and North American manufacturing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulose Gel Market |
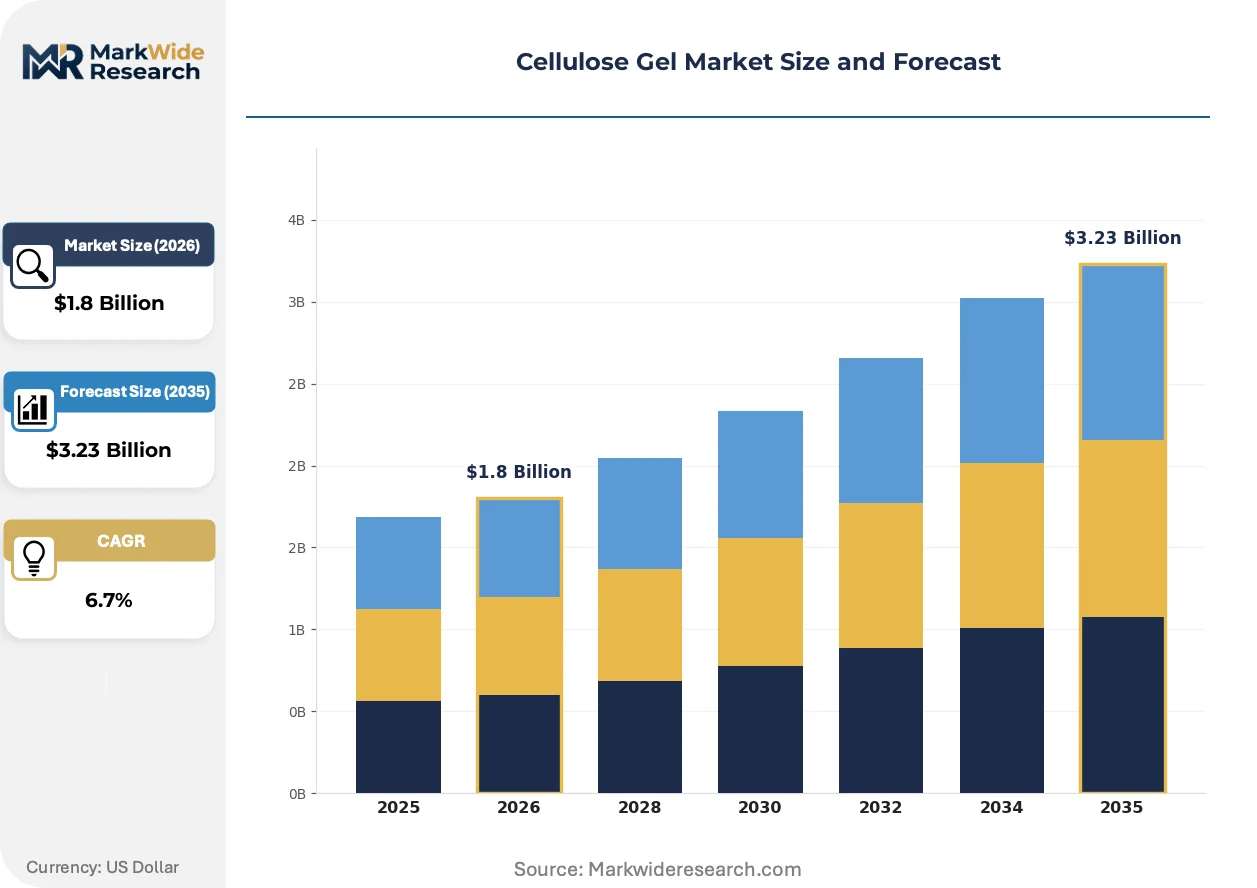
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcrystalline Cellulose, Carboxymethyl Cellulose, Hydroxypropyl Methylcellulose, Sodium Carboxymethyl Cellulose End Use: Pharmaceuticals, Food & Beverages, Cosmetics, Personal Care Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade Packaging Type: Boxes, Bags, Totes, Drums |
| Companies Covered | DFE Pharma GmbH & Co. KG, Sigachi Industries Limited, J. Rettenmaier & Söhne GmbH + Co KG, Asahi Kasei Corporation, Mingtai Chemical Co., Ltd., Libraw Pharma, Ashland Global Specialty Chemicals Inc., FMC Corporation, Roquette, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulose Gel Market Emerging Trajectories
Cellulose gel functionality is being redefined at the intersection of pharmaceutical performance engineering, regulatory chemistry documentation, and plant-derived material substitution across multiple industrial verticals.
Nano- and microcrystalline cellulose grades with tunable particle size distributions are expanding into high-performance tablet compaction applications where powder flow and lubricity requirements previously demanded synthetic binders. Generic drug manufacturers in India and contract development organizations in the United States are accelerating adoption as cost-engineered alternatives to premium excipient portfolios. The technology is expanding into continuous manufacturing line configurations that were previously optimized for direct compression with limited excipient flexibility.
REACH annex amendments restricting microplastic additives in cosmetics and personal care are compressing synthetic polymer market share across EU member states. ECHA guidance on polymer registration thresholds is forcing reformulation timelines for exfoliant and rheology-modifier applications. Cellulose microbead and microfiber alternatives are capturing technical qualification slots previously held by polyethylene and polypropylene derivatives in German and French cosmetic manufacturing clusters.
Direct sourcing contracts between pharmaceutical formulators and excipient manufacturers are displacing traditional distributor-mediated procurement in high-volume oral solid dosage categories. Large generic houses in India and integrated pharmaceutical companies in Japan are consolidating supplier panels and demanding dedicated manufacturing capacity with audit rights. This concentration is most visible in Hyderabad and Mumbai pharmaceutical corridors where CDSCO-inspected facilities are securing multi-year supply agreements with embedded quality escalation clauses.
Cellulose Gel Market Segmentation
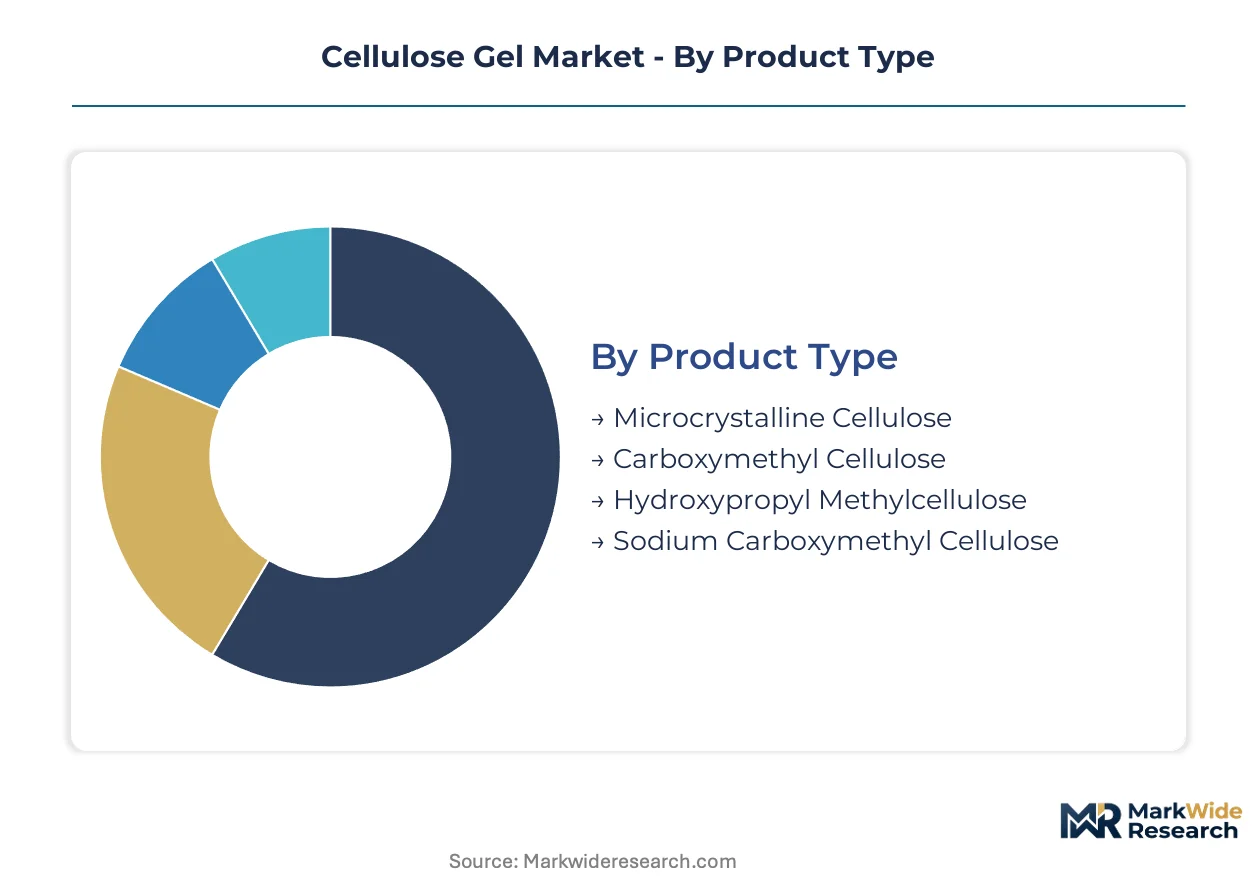
Cellulose gel market segmentation reveals distinct technical specifications and regulatory pathways that determine supplier qualification requirements. Product type and grade classifications impose the strictest purity documentation burdens, while end-use applications dictate formulation performance thresholds.
Product Type:
Integration depth varies sharply across cellulose gel chemistries, with standalone excipient functions dominating pharmaceutical applications while modified derivatives embed into complex formulation matrices.
- Microcrystalline Cellulose:Refined cellulose processed through controlled hydrolysis yields crystalline aggregates with defined particle size distributions. Tablet compaction in United States generic manufacturing concentrates procurement volumes as FDA bioequivalence standards tighten powder flow requirements.
- Carboxymethyl Cellulose:Etherified cellulose derivatives with tunable substitution degrees enable cold-water solubility for beverage stabilization. German clean-label food formulation and Japanese convenience food sectors drive specification differentiation around clarity and viscosity retention.
- Hydroxypropyl Methylcellulose:Propylene oxide-modified cellulose ethers form thermoreversible gel matrices for controlled-release oral dosage forms.
- Sodium Carboxymethyl Cellulose:Salt form of carboxymethyl cellulose optimized for ionic stability in processed food systems.
Volume placements concentrate in Microcrystalline Cellulose; the faster expansion belongs to Hydroxypropyl Methylcellulose.
End Use:
Cost tier stratification separates premium-certified pharmaceutical supply from commodity-grade food and industrial applications with divergent documentation requirements.
- Pharmaceuticals:Oral solid dosage formulations demand USP-NF, EP, and JP monograph compliance with residual solvent documentation. EMA quality standard elevation and FDA excipient guidelines force dedicated manufacturing lines with audit rights for large generic houses in India.
- Food & Beverages:Thickening and stabilizing functions in clean-label positioning require FSSAI approval in India and EFSA compliance in Europe. Plant-derived positioning in Germany and Japan drives substitution away from synthetic hydrocolloids.
- Cosmetics:REACH microplastic restrictions propel cellulose microbead adoption for exfoliant applications in French and German manufacturing clusters.
- Personal Care:Rheology modification and emulsion stabilization in skin and hair care products.
Revenue concentration sits in Pharmaceuticals; Cosmetics is climbing the fastest on regulatory substitution mandates.
Grade:
Application maturity separates established pharmaceutical-grade supply chains from emerging cosmetic-grade qualification pathways with shorter technical histories.
- Pharmaceutical Grade:Elemental impurity thresholds and residual solvent limits governed by ICH Q3D and Q3C guidelines. CDSCO inspections in India and PMDA assessments in Japan create multi-jurisdictional qualification burdens for excipient specialists.
- Food Grade:FSSAI food additive regulations and FDA GRAS determinations govern purity specifications. Cold-chain beverage applications in Japan and baked goods stabilization in Germany concentrate procurement volumes.
- Cosmetic Grade:ECHA REACH registration and EU Cosmetics Regulation compliance for microplastic-free positioning.
- Industrial Grade:Lower-purity specifications for construction, paper, and textile binding applications.
Supply concentration favors Pharmaceutical Grade; Cosmetic Grade is gaining share fastest on EU regulatory pressure.
Packaging Type:
Customer type and order scale determine packaging configuration, with integrated pharmaceutical manufacturers demanding dedicated bulk formats distinct from distributor-mediated small-lot supply.
- Drums:Steel and fiber drums with liner systems dominate pharmaceutical-grade shipments to contract manufacturing organizations. Hyderabad and Mumbai pharmaceutical corridors specify UN-certified configurations for international API co-shipment.
- Totes:Intermediate bulk containers capture high-volume food and beverage manufacturing in Germany and United States dairy processing clusters.
- Bags:Multi-wall paper and PE-lined configurations for industrial-grade and commodity food applications.
- Boxes:Corrugated configurations for cosmetic-grade and sample-quantity pharmaceutical shipments.
Shipment volume concentrates in Drums; Totes are expanding most quickly on continuous manufacturing line integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Visakhapatnam and Shenzhen accelerate cellulose gel production concentration through tax incentives and streamlined customs clearance for pharmaceutical excipient exports.
United States
FDA bioequivalence standards tighten powder flow requirements for generic oral solid dosages. The agency's excipient guidelines force dedicated manufacturing lines with embedded audit rights. New Jersey and North Carolina pharmaceutical corridors consolidate procurement volumes toward certified suppliers with USP-NF documentation capabilities.
Germany
Clean-label food formulation drives carboxymethyl cellulose specification differentiation around clarity and viscosity retention. EMA quality standard elevation imposes stricter residual solvent limits on pharmaceutical-grade imports. Bavarian chemical manufacturing clusters specialize in microcrystalline cellulose compaction technologies for European generic drug houses.
India
CDSCO excipient qualification pathways create dual-use certification opportunities for domestic and export markets. FSSAI food additive approvals govern purity specifications for beverage stabilization applications. Hyderabad and Mumbai pharmaceutical corridors secure multi-year supply agreements with embedded quality escalation clauses for oral solid dosage manufacturing.
Japan
PMDA assessments create multi-jurisdictional qualification burdens for excipient specialists targeting controlled-release formulations. METI industrial standards support thermoreversible gel matrix development for vegan capsule alternatives. Kanto region pharmaceutical manufacturers accelerate hydroxypropyl methylcellulose adoption as gelatin substitution intensifies.
China
NMPA pharmaceutical excipient registration requirements tighten documentation protocols for imported cellulose derivatives. SAMR food additive standards govern carboxymethyl cellulose deployment in convenience food sectors. Yangtze River Delta chemical processing hubs expand etherification reactor capacity for regional personal care and pharmaceutical supply.
Cellulose Gel Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade supply consolidating around certified excipient specialists while food-grade procurement fragments across regional distributors. Three structural tiers emerge: integrated polymer science conglomerates with cross-vertical portfolios, dedicated cellulose processing specialists with purified cotton linter supply control, and regional toll manufacturers serving commodity industrial applications. Capacity expansion and backward integration into purified feedstock supply represent the dominant competitive vectors as EMA and FDA documentation requirements harden.
Within the European specialist tier, J. Rettenmaier & Söhne GmbH + Co KG anchors German microcrystalline cellulose production through controlled hydrolysis expertise. Ashland Global Specialty Chemicals Inc. occupies a position spanning pharmaceutical and personal care verticals through polymer science capabilities. Roquette exemplifies plant-derived excipient positioning that aligns with biopharma sourcing preferences for vegan formulation alternatives.
| Leading Market Players |
|---|
| DFE Pharma GmbH & Co. KG |
| Sigachi Industries Limited |
| J. Rettenmaier & Söhne GmbH + Co KG |
| Asahi Kasei Corporation |
| Mingtai Chemical Co., Ltd. |
| Libraw Pharma |
| Ashland Global Specialty Chemicals Inc. |
| FMC Corporation |
| Roquette |
| Others |
Supply Flow & Price Mechanics
Large generic pharmaceutical houses in India and integrated Japanese manufacturers concentrate procurement volumes toward certified excipient specialists, embedding long-term contract structures with audit rights and quality escalation clauses that compress spot-market liquidity.
Pricing Analysis
Short lead-time premiums command substantial markups as pharmaceutical formulators buffer against CDSCO and PMDA inspection delays. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates USP-NF certified supply from FSSAI-compliant variants and commodity cellulose ethers. Cost compression in food-grade carboxymethyl cellulose is intensifying because xanthan gum substitution erodes volume commitments. Generic drug manufacturers in Hyderabad and Mumbai corridors exhibit highest price sensitivity, while vegan capsule specialists in Japan and Germany absorb premiums for hydroxypropyl methylcellulose with minimal volume elasticity.
Supply Chain Analysis
Specialized reactor operation expertise concentrates among aging technical workforces in Bavarian chemical clusters and Yangtze River Delta manufacturing hubs. Pharmaceutical-grade microcrystalline cellulose production draws from purified cotton linter supply anchored in concentrated cotton processing regions, while etherification capacity for carboxymethyl and hydroxypropyl methylcellulose variants rests on propylene oxide and chloroacetic acid feedstock streams. Single-source vulnerability pervades the cotton linter-to-excipient pipeline, exposing formulators to agricultural yield volatility and climate-driven input swings. Distribution runs through direct sourcing contracts displacing distributor-mediated procurement in high-volume oral solid dosage categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EMA and FDA documentation requirements harden, forcing mid-scale specialty chemical entrants to absorb disproportionate REACH registration cost burdens that disqualify undercapitalized competitors.
For Market Incumbents: Cement excipient qualification dominance through backward integration into purified cotton linter supply and dedicated manufacturing line expansion in CDSCO-inspected Hyderabad and Mumbai corridors. Threat from Roquette and plant-derived specialists demands accelerated hydroxypropyl methylcellulose capacity addition to capture vegan capsule formulation surge in Germany and Japan.
For New Entrants and Emerging Players: E-commerce and digital procurement platforms targeting mid-tier contract manufacturing organizations in India offer the most penetrable route. White-space exists in cosmetic-grade microcrystalline cellulose bead supply for EU microplastic replacement mandates, plus toll manufacturing partnerships for regional food-grade carboxymethyl cellulose in FSSAI-regulated beverage stabilization applications.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated cellulose processing specialists with captive cotton linter supply and multi-jurisdictional pharmacopeial qualification capabilities. Long-term viability hinges on consolidation of aging European and North American technical workforces with specialized controlled hydrolysis and etherification reactor expertise. Signal to monitor: CDSCO and PMDA harmonization acceleration that extends excipient qualification timelines beyond smaller competitors' capital endurance.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Purified Cotton Linter Supply | Captive feedstock control insulates against agricultural yield volatility and price swings. |
| Multi-Jurisdictional Pharmacopeial Qualification Investment | USP-NF, EP, and JP monograph compliance opens FDA and EMA-regulated pharmaceutical corridors. |
| Cosmetic-Grade Microbead Capacity Expansion | REACH microplastic restrictions propel cellulose alternatives in German and French manufacturing clusters. |
| Direct Sourcing Contract Consolidation | Audit rights and quality escalation clauses lock in large generic houses in India and Japan. |
| Continuous Manufacturing Line Integration | Tote-format supply agreements align with pharmaceutical automation investments in United States and Germany. |
Methodological Framework
Multi-period observation of CDSCO inspection timelines, EMA quality standard elevation trajectories, and FDA excipient guideline revisions anchored the trend analysis, supplemented by interviews with excipient manufacturing plant managers, pharmaceutical procurement leads at Indian generic houses, regulatory affairs directors navigating USP-NF and EP harmonization, and cosmetic formulation R&D heads in German and French clusters. Secondary validation drew from FDA Drug Master File submissions, EMA excipient quality documentation, FSSAI food additive approval registers, USP-NF and EP monograph revision histories, and SEC filings of listed specialty chemical conglomerates. Bottom-up volume triangulation across product type, grade tier, and end-use application intersected with top-down market sizing through trade flow analysis and capacity utilization assessment at major etherification reactor installations.
Input-output matrix framing connected propylene oxide and chloroacetic acid feedstock pricing to hydroxypropyl methylcellulose and carboxymethyl cellulose production economics, while cotton linter supply volumes mapped to microcrystalline cellulose capacity expansion decisions across the projection horizon. Segmentation dimensions modeled encompassed pharmaceutical-grade versus food-grade versus cosmetic-grade purity tiers, oral solid dosage versus beverage stabilization versus personal care end-uses, and drum versus tote versus bag packaging configurations. CAGRs derived from elasticity-adjusted demand projections incorporating bioequivalence standard tightening, vegan capsule substitution rates, and REACH microplastic restriction implementation timelines.
The model holds under continued pharmacopeial harmonization momentum and stable agricultural yield patterns for cotton linter supply; deviation in EMA-FDA regulatory divergence or extreme climate events affecting cotton processing regions would shift volume and value trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Specialty Silicone Market
Specialty Materials
Engineered Quartz Surface Market
Specialty Materials
Super-Hard Material Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Specialty Silica Market
Specialty Materials
Acrylic Fine Particle Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
North America Solar Control Window Films Market
Specialty Materials
Europe Microspheres Market
Specialty Materials
Methyl Silicone Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Asia-Pacific Reflective Tape Market
Specialty Materials
Halloysite Market
Specialty Materials
Carrageenan Film Market