
 Global Specialty Polymer Market | 2026-2036
Global Specialty Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Polymer Market Foresight
Automotive OEMs are collapsing their legacy commodity polymer specifications in favor of lightweight, high-heat formulations for electric powertrains. BASF SE leverages its integrated caprolactam chain to dominate engineering thermoplastic supply for under-hood applications. Evonik Industries AG specializes in polyamide 12 powders for additive manufacturing, anchoring its position in laser sintering feedstocks. Dow Inc. competes through silicone-fluoropolymer hybrids that sustain performance across extreme temperature cycles.
Specialty polymers are macromolecular materials engineered for specific functional properties beyond general-purpose resins, typically synthesized via controlled condensation, ring-opening, or addition polymerization with precise molecular weight distribution and purity grades targeting thermal stability above 150°C or chemical resistance to aggressive media. Their primary commercial purpose is to replace metals, ceramics, or commodity plastics in demanding environments where failure carries high consequential cost. High-performance polymers command the deepest margin pools due to fluoropolymer and polyaryletherketone chemistry barriers, while biopolymers represent the fastest-expanding demand vector as consumer goods manufacturers face EPR mandates. Thermoplastics still occupy the largest volume share across electronics and packaging applications, though elastomer growth in medical device seals is accelerating.
REACH restricts perfluorinated substance use across Europe, forcing reformulation of PTFE and FEP grades for membranes and sealants. FDA enforces ISO 10993 biocompatibility tiers for implantable polymers, creating dual-certification costs that filter supplier pools in medical devices. China's GB standards and MEE enforcement on VOC emissions during polymer processing are reshaping export qualification requirements for compounders serving electrical equipment makers. Stakeholders must monitor regulatory divergence between EU F-Gas phase-down timelines and US EPA risk evaluation pathways for fluorinated chemistries.
Market Dynamics
Automotive electrification is collapsing legacy polymer specifications as OEMs demand materials surviving 180°C continuous under-hood temperatures while cutting component weight by half versus aluminum. This thermal-performance tension is concentrating formulation expertise among integrated chemical producers with captive monomer supply.
Growth Catalysts
- EU MDR implant-grade certification:REACH and MDR compliance in Europe are accelerating substitution of conventional materials with certified specialty grades for cardiovascular and orthopedic devices.
- Additive manufacturing feedstock expansion:Laser sintering adoption in aerospace prototyping is pulling polyamide 12 powders and high-temperature photopolymers into production-scale volumes.
- EPR mandate proliferation:Extended producer responsibility frameworks across consumer goods are forcing brand owners toward bio-based and recyclable specialty polymer alternatives.
Market Restraints
- Fluoromonomer supply concentration:PTFE and FEP resin production clusters in China's Zhejiang province and Germany's chemical corridor, creating single-source vulnerability for membrane and sealant compounders.
- Caprolactam price volatility:Engineering thermoplastic margins compress when benzene-cyclohexane feedstock spreads widen, particularly affecting polyamide 6 and 66 grades.
- REACH perfluorinated restrictions:ECHA's PFAS restriction proposal forces reformulation of low-friction coatings and semiconductor process materials with unclear timeline certainty.
Strategic Opportunities
- India medical device manufacturing:CDSCO's alignment with ISO 13485 and PLI scheme incentives for domestic production create first-mover advantage for implant-grade polymer compounders establishing local cleanroom operations.
- Silicone-fluoropolymer hybrid convergence:Dow's temperature-cycle-stable elastomer technology opens battery thermal management and EV charging cable jacket applications previously served by conventional silicone.
- Direct-to-device-manufacturer distribution:Bypassing traditional distributor markups through qualified supplier programs lets compounders capture margin and secure volume commitments from MedTech OEMs.
Industry Challenges
- ISO 10993 biocompatibility testing backlog:FDA's third-party reviewer capacity constraints extend implantable polymer qualification timelines to 18-24 months, freezing working capital in pre-revenue inventory.
- Multi-standard certification complexity:Compounders serving global MedTech must simultaneously maintain USP Class VI, ISO 10993, and Japan's PMDA ministerial certification, fragmenting quality management systems.
- Legacy equipment incompatibility:High-performance polymer processing requires tighter temperature control and contamination protocols than commodity resin extrusion lines, stranding mid-tier compounders with obsolete capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Polymer Market |
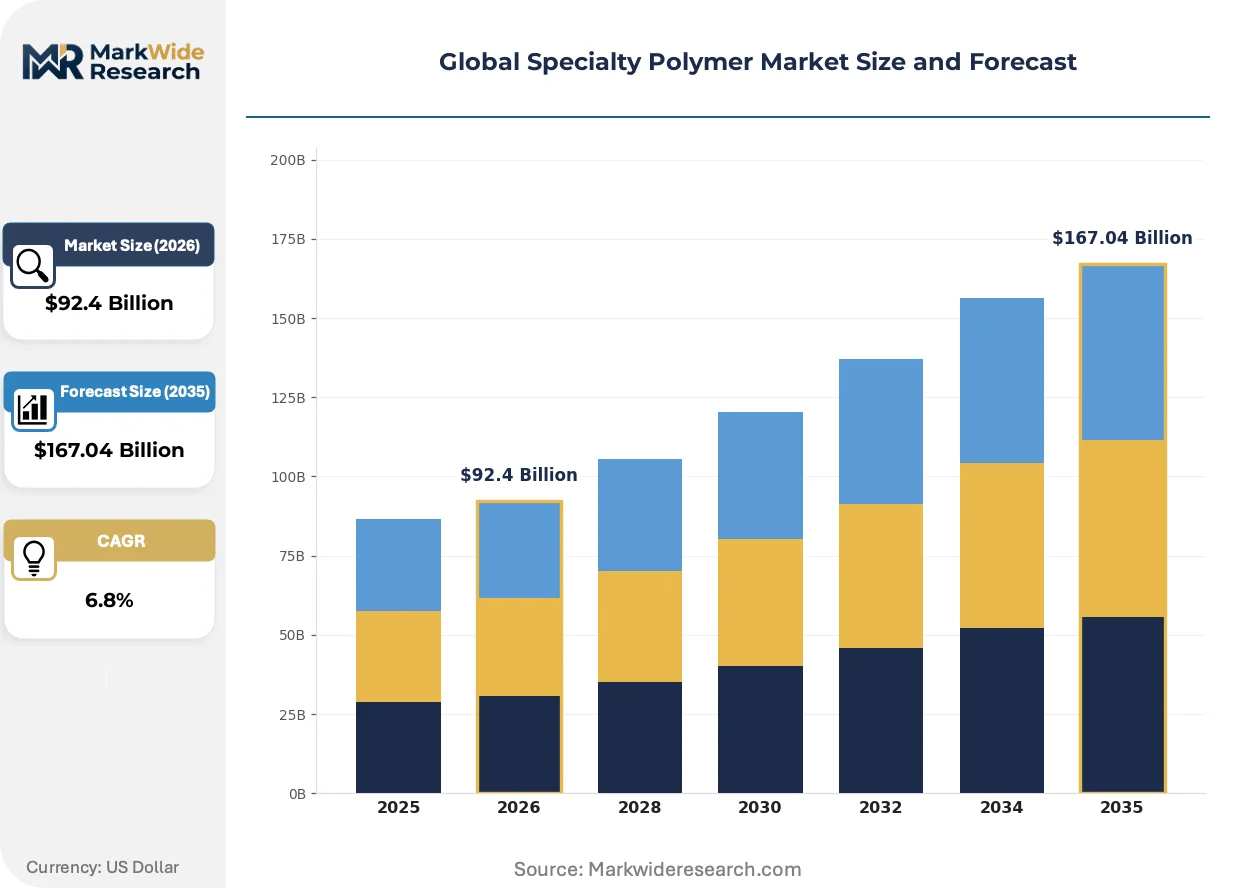
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $167.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastics, Thermosets, Elastomers, High-Performance Polymers, Biopolymers Application: Electronics, Aerospace Components, Packaging Materials, Membranes, Adhesives & Sealants Form: Pellets, Powders, Films, Sheets, Fibers End User Industry: Consumer Goods Manufacturers, Construction Sector, Medical Devices, Automotive OEMs, Electrical Equipment Makers |
| Companies Covered | BASF SE, Arkema, Evonik Industries AG, SABIC, Covestro AG, Solvay SA, Dow Inc., DuPont de Nemours, Inc., Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Polymer Market Shifts & Advancements
Material science convergence with digital manufacturing is collapsing traditional batch-compounding economics while regulatory chemistry restrictions force molecular architecture redesigns across fluoropolymer and polyaryletherketone families.
High-heat thermoplastic composites reinforced with continuous carbon fiber are displacing machined aluminum in electric motor housings and battery enclosures. Automotive tier suppliers in Germany and South Korea are qualifying these materials for 800V architecture platforms. The shift is compressing metal-to-polymer conversion timelines from five-year validation cycles to eighteen-month platform adaptations.
Europe's F-Gas Regulation phase-down timeline is forcing semiconductor fabrication equipment makers to abandon perfluorinated process gases and chamber materials by 2030. Equipment OEMs are redesigning etch and deposition tools around fluorine-free chemistries. This regulatory pressure is most acute in Netherlands and Ireland, where ASML's supply chain and Intel's Leixlip expansion face simultaneous chemistry and energy constraints.
Specification consolidation among MedTech procurement teams is collapsing approved vendor lists from twelve suppliers to three preferred partners per polymer category. Sourcing managers at cardiovascular device makers now demand dual-site manufacturing and disaster recovery certification as table stakes. This concentration is most visible in Minnesota and Massachusetts, where Boston Scientific and Medtronic headquarters procurement functions drive qualification decisions for global manufacturing networks.
Global Specialty Polymer Market Segmentation
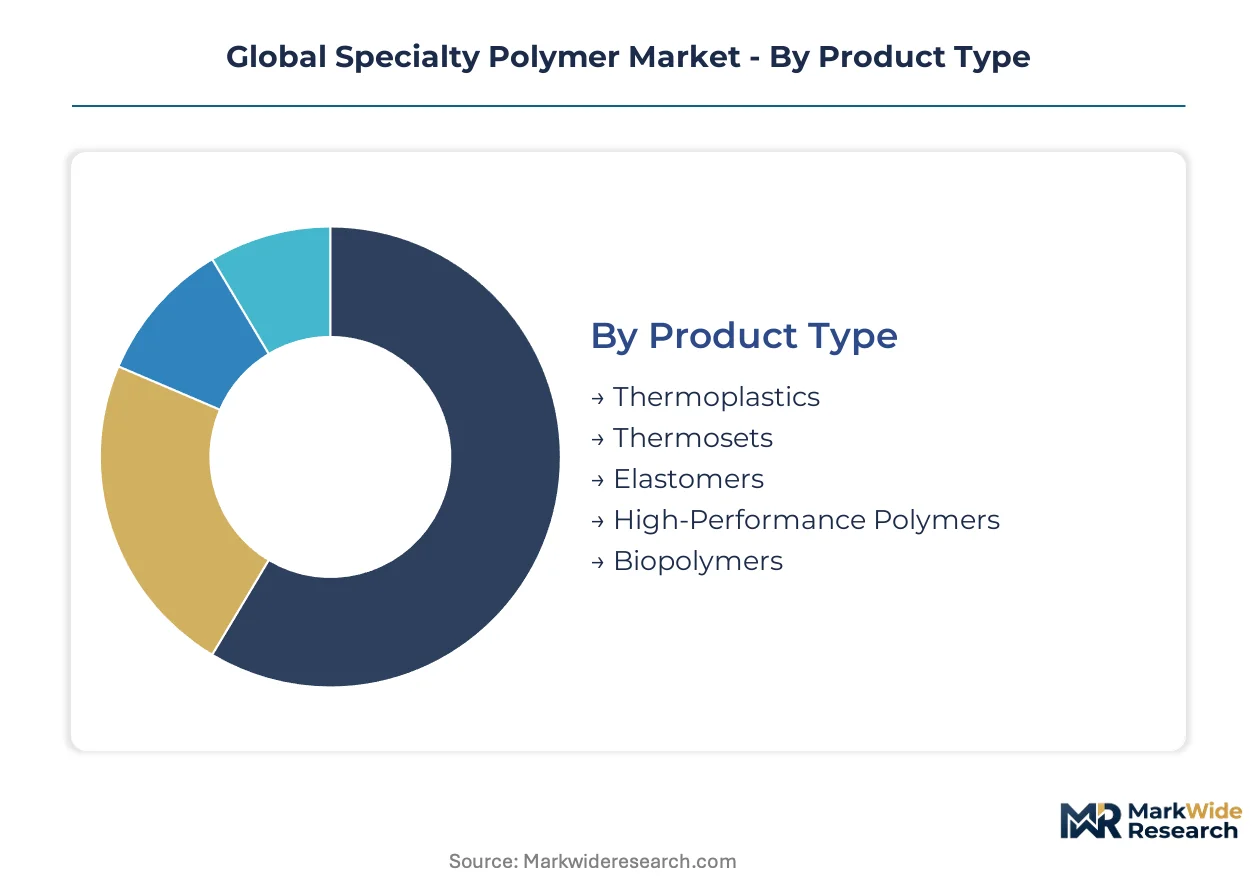
Specialty polymer segmentation reveals distinct channel economics across product categories. Thermoplastics flow through distributor networks to electronics compounders, while high-performance polymers demand direct technical sales to automotive and aerospace OEMs. Biopolymers increasingly bypass traditional channels as consumer goods brands establish captive offtake agreements with compounders.
Product Type:
Channel strategy diverges sharply across polymer families. Commodity-anchored thermoplastics move through regional distributors with inventory financing, whereas high-performance and medical-grade materials require qualified supplier programs with audit rights and batch traceability.
- Thermoplastics:Melt-processable resins including polyamides, polyesters, and polycarbonates dominate electronics housings and automotive under-hood components. Demand concentrates in Germany's chemical corridor and South Korea's automotive belt, where BASF and LG Chem compounders serve tier suppliers with just-in-time pellet delivery.
- High-Performance Polymers:Fluoropolymers, polyaryletherketones, and polyimides withstand continuous service above 200°C. Aerospace engine manufacturers in Connecticut and Toulouse drive qualification timelines for PEEK and PTFE grades, with AS9100 certification filtering supplier pools to three Western compounders.
- Thermosets:Cross-linked epoxies and phenolics serve electrical insulation and composite matrices. Epoxy resin demand clusters in China's Jiangsu province for wind turbine blade manufacturing.
- Elastomers:Silicone and fluoroelastomer compounds seal medical devices and automotive systems. Liquid silicone rubber injection molding growth in Minnesota medical device corridors accelerates platinum-cured grade consumption.
- Biopolymers:Polylactic acid and polyhydroxyalkanoates substitute petroleum-derived packaging. European EPR mandates force CPG brands toward certified compostable grades, with NatureWorks' Blair, Nebraska facility anchoring North American PLA supply.
By volume, thermoplastics lead. By growth pace, biopolymers are expanding most quickly.
Application:
Application mix determines margin structure and technical service intensity. Electronics and aerospace demand precision specification adherence with penalty clauses, while packaging applications prioritize throughput and price stability.
- Electronics:Low-dielectric thermoplastics and encapsulants insulate 5G infrastructure and electric vehicle inverters. Taiwan's PCB manufacturing cluster and Netherlands semiconductor equipment makers drive halogen-free flame retardant adoption.
- Aerospace Components:Carbon fiber-reinforced PEEK and thermoplastic composites replace machined aluminum in brackets and ducting. Boeing's Everett facility and Airbus's Hamburg plant qualify materials to NCAMP shared databases, compressing second-source approval timelines.
- Packaging Materials:Barrier films and sealant layers extend shelf life for pharmaceuticals and food. Multilayer coextrusion lines in Wisconsin and Bavaria consume EVOH and ionomer resins.
- Membranes:PVDF and PTFE filtration media purify biopharmaceutical processes and semiconductor ultrapure water. Pall Corporation's Port Washington, New York headquarters and Merck KGaA's Darmstadt operations specify resin purity to parts-per-billion ionic contamination limits.
- Adhesives & Sealants:Reactive hot-melts and structural acrylics bond dissimilar substrates in automotive and medical assembly. Henkel's Düsseldorf technical center and 3M's St. Paul campus formulate custom specialty polymer backbones.
Electronics applications generate the highest revenue per kilogram. Aerospace qualification cycles extend the longest.
Form:
Physical form dictates processing equipment compatibility and working capital requirements. Pellet and powder forms suit high-volume extrusion and molding, while films and fibers demand specialized capital and narrower customer bases.
- Pellets:Standardized cylindrical granules feed injection molding and extrusion lines globally. Automotive tier suppliers in Stuttgart and Detroit maintain silo inventories of polyamide and PBT grades with 48-hour call-off flexibility.
- Powders:Fine-ground resins serve rotational molding, coatings, and additive manufacturing. Polyamide 12 powder for laser sintering concentrates demand in Germany's chemical corridor and Texas aerospace prototyping shops.
- Films:Cast and oriented sheets package semiconductors and medical devices. Cleanroom extrusion in Massachusetts and Hesse supplies static-dissipative grades to Intel and Infineon wafer fabs.
- Sheets:Thick-gauge thermoplastic plates machine into prototypes and low-volume components. Quadrant's Lenzburg, Switzerland facility and Mitsubishi Chemical's Japanese plants dominate high-performance sheet supply.
- Fibers:Continuous filaments reinforce composites and weave into industrial textiles. Teijin's Arnhem, Netherlands carbon fiber-polymer hybrid operations serve automotive lightweighting programs.
Pellets move the highest tonnage. Powders for additive manufacturing are gaining share fastest.
End User Industry:
Customer concentration varies dramatically across end-use sectors. Automotive and medical device procurement functions consolidate approved vendor lists, while construction maintains fragmented specification authority.
- Automotive OEMs:Electric powertrain thermal management and battery enclosure materials command 180°C continuous service ratings. Volkswagen's Wolfsburg engineering center and Tesla's Austin operations specify materials eighteen months before production launch.
- Medical Devices:Implantable and surgical instrument polymers require ISO 10993 and USP Class VI certification. Boston Scientific's Maple Grove, Minnesota campus and Medtronic's Fridley headquarters drive cardiovascular catheter material selection for global manufacturing networks.
- Electrical Equipment Makers:Wire insulation and connector housings demand tracking resistance and flame retardancy. Schneider Electric's Grenoble campus and Siemens' Nuremberg operations qualify materials to IEC standards with regional variant testing.
- Consumer Goods Manufacturers:Packaging and durables brands face EPR mandates and recyclability targets. Unilever's Rotterdam and London procurement teams audit polymer supply chains for mass balance certification.
- Construction Sector:Geosynthetics, membranes, and sealants serve infrastructure and building envelopes. Specification authority fragments across German civil engineering consultants and Japanese general contractors.
Automotive OEMs purchase the highest volumes. Medical devices deliver the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine River chemical corridor and Rotterdam-Antwerp pipeline network anchor European specialty polymer distribution, while the Houston Ship Channel and Ningbo-Zhoushan port complex underwrite transatlantic and Asia-Pacific supply flows respectively.
Germany
Ludwigshafen and Leverkusen host integrated caprolactam-to-polyamide production chains serving automotive electrification programs. ECHA's REACH enforcement and EU MDR certification requirements filter supplier pools for implant-grade materials. BASF SE's headquarters complex coordinates engineering thermoplastic supply across the chemical corridor.
United States
Minnesota's medical device corridor and Texas Gulf Coast petrochemical infrastructure drive divergent demand vectors. FDA enforces ISO 10993 biocompatibility tiers for implantable polymers while EPA risk evaluations reshape fluorinated chemistry pathways. Dow Inc.'s Midland operations anchor silicone-fluoropolymer hybrid development for battery thermal management.
China
Zhejiang province concentrates PTFE and FEP resin production for membrane and sealant compounders. MEE enforcement on VOC emissions during polymer processing reshapes export qualification requirements for electrical equipment makers. The Yangtze River Delta hosts compounding operations serving domestic automotive and electronics manufacturers.
India
CDSCO's alignment with ISO 13485 and PLI scheme incentives accelerate domestic medical device manufacturing capacity. Maharashtra and Gujarat industrial corridors attract implant-grade polymer compounders establishing local cleanroom operations. Mumbai-Pune automotive belt demands high-heat formulations for emerging electric powertrain programs.
Japan
PMDA ministerial certification requirements fragment quality management systems for compounders serving global MedTech networks. METI industrial policy supports polyimide and liquid crystal polymer development for semiconductor packaging. Osaka-Kobe chemical complex maintains specialized fluoropolymer production for electronics process materials.
Global Specialty Polymer Market Competitive Landscape
Concentration sits with integrated chemical conglomerates controlling captive monomer supply and specialized compounders holding dual-certification qualifications for medical-grade segments. The vendor base stratifies across three tiers: global diversified producers with backward integration into feedstocks, regional specialists with formulation expertise in specific polymer families, and niche compounders serving qualified supplier programs with audit rights and batch traceability. Dominant competitive moves include capacity expansion in high-performance polymer grades and strategic partnerships with automotive OEMs for electric powertrain material qualification.
Among European-based integrated producers, BASF SE and Evonik Industries AG exemplify divergent specialization strategies within the chemical corridor, while Dow Inc. anchors North American silicone-fluoropolymer hybrid development. These three entities represent distinct archetypes: the diversified petrochemical conglomerate with caprolactam chain control, the specialty chemicals specialist with additive manufacturing feedstock focus, and the materials science hybrid innovator spanning elastomer and fluoropolymer convergence.
| Leading Market Players |
|---|
| BASF SE |
| Arkema |
| Evonik Industries AG |
| SABIC |
| Covestro AG |
| Solvay SA |
| Dow Inc. |
| DuPont de Nemours, Inc. |
| Celanese Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between automotive OEMs and integrated chemical producers lock in both caprolactam supply access and eighteen-month price visibility, insulating compounders from benzene-cyclohexane spread volatility while binding buyers to volume commitments through electric powertrain qualification cycles.
Pricing Analysis
Three-tier pricing structure across implant-grade, industrial-grade, and commodity-grade levels separates medical device compounders paying certification premiums from automotive tiers negotiating on thermal performance specifications. Price differentiation rests on ISO 10993 biocompatibility tiers and captive monomer supply integration. Cost compression in industrial-grade polyamide runs through benzene feedstock volatility and Asian import competition. Packaging compounders exhibit highest price sensitivity, while cardiovascular device manufacturers absorb premiums for dual-certified cleanroom production.
Supply Chain Analysis
China and Germany anchor fluoropolymer resin production, with Zhejiang province PTFE output feeding membrane compounders and Ludwigshafen caprolactam chains supplying automotive under-hood formulations. Raw material dependencies draw from benzene-cyclohexane feedstocks, fluorspar acid-grade ore, and bio-based lactic acid for PLA grades. Single-source vulnerability concentrates in Zhejiang fluoromonomer capacity, exposing sealant manufacturers to export license disruptions. Distribution runs through qualified supplier programs with audit rights for medical grades, while industrial thermoplastics flow through regional distributors with inventory financing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty polymer markets increasingly monetize through technical service attachments and formulation co-development fees, with qualified supplier program enrollment and regulatory filing support expanding faster than base resin tonnage.
For Market Incumbents: Secure backward integration into caprolactam and fluorspar supply to defend margin position against benzene volatility and Chinese export restrictions. Add cleanroom compounding capacity in India's Maharashtra corridor to capture CDSCO-aligned medical device manufacturing growth. Lock in long-term offtake with automotive OEMs before second-source qualification timelines compress further. For New Entrants and Emerging Players: Differentiate on bio-based and certified compostable grades targeting European EPR mandates, where brand owners face compliance deadlines and limited qualified supply. Target India's domestic medical device corridor with implant-grade polymer compounders establishing local operations under PLI scheme incentives. Lead with direct-to-device-manufacturer distribution bypassing traditional channel markups. For Investors and Strategic Acquirers: Dual-certified medical-grade compounders with ISO 10993 and PMDA ministerial qualifications represent the most defensible acquisition archetype, commanding scarcity premiums as procurement consolidation collapses approved vendor lists. Watch for FDA third-party reviewer capacity expansion as an inflection signal for implantable polymer qualification timeline normalization and working capital release from pre-revenue inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | BASF's Ludwigshafen complex demonstrates how captive monomer supply insulates engineering thermoplastic margins from benzene-cyclohexane spread volatility. |
| Medical-Grade Cleanroom Expansion | CDSCO's ISO 13485 alignment and India's PLI scheme create first-mover advantage for implant-grade polymer compounders establishing Mumbai-Pune operations. |
| Silicone-Fluoropolymer Hybrid Development | Dow's temperature-cycle-stable elastomer technology opens battery thermal management applications previously served by conventional silicone grades. |
| Direct-to-Device-Manufacturer Distribution | Bypassing traditional distributor markups through qualified supplier programs lets compounders capture margin and secure volume commitments from Boston Scientific and Medtronic procurement functions. |
| Bio-Based Grade Certification | European EPR mandates force Unilever and CPG brands toward certified compostable alternatives, with NatureWorks' Blair facility anchoring North American PLA supply. |
Research Methodology
Cross-validation between primary interviews with polymer plant managers, automotive Tier 1 procurement leads, medical device regulatory affairs directors, and distribution channel partners anchors the qualitative findings against secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH registration databases. Bottom-up modeling of compounding capacity and top-down triangulation against end-use demand vectors ensure segment-level consistency.
Sensitivity analysis across feedstock price scenarios, regulatory timeline variants, and automotive platform adoption curves stress-tests volume and value outputs across the projection horizon. Segmentation dimensions include polymer chemistry family, performance grade tier, end-use industry vertical, physical form factor, and regional production hub. CAGRs derive from regression analysis of historical capacity utilization, qualification timeline compression, and substitution elasticity against metals and ceramics.
Material uncertainties — ECHA PFAS restriction finalization, FDA third-party reviewer capacity constraints, and Chinese fluoromonomer export license policies — sit outside the modeled envelope. Forecasts reflect documented assumptions on regulatory trajectory and OEM platform standardization. Recalibration cycles align with material shifts in REACH enforcement timelines and automotive electrification program announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Nonene (Propylene Trimer) and Tetramer Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Fluoropolymer Masterbatch Market
Specialty Compounds
Global Sulfur Hexafluoride Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Organosulfur Compounds Market
Specialty Compounds
Global Customized Premixes Market
Specialty Compounds
Joint Compound Market
Specialty Compounds
Metasulphite Market
Specialty Compounds
GCC Specialty Chemicals Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Plasma Powder Market
Specialty Compounds
Europe Polypropylene Compounds Market
Specialty Compounds
Latin America Hydroxypropyl Methylcellulose Market
Specialty Compounds
Propylene Trimer Market
Specialty Compounds
Oxygen Scavenger Masterbatch Market