
 Carbon Fiber Filament Market | 2026-2036
Carbon Fiber Filament Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Fiber Filament Market Analytics
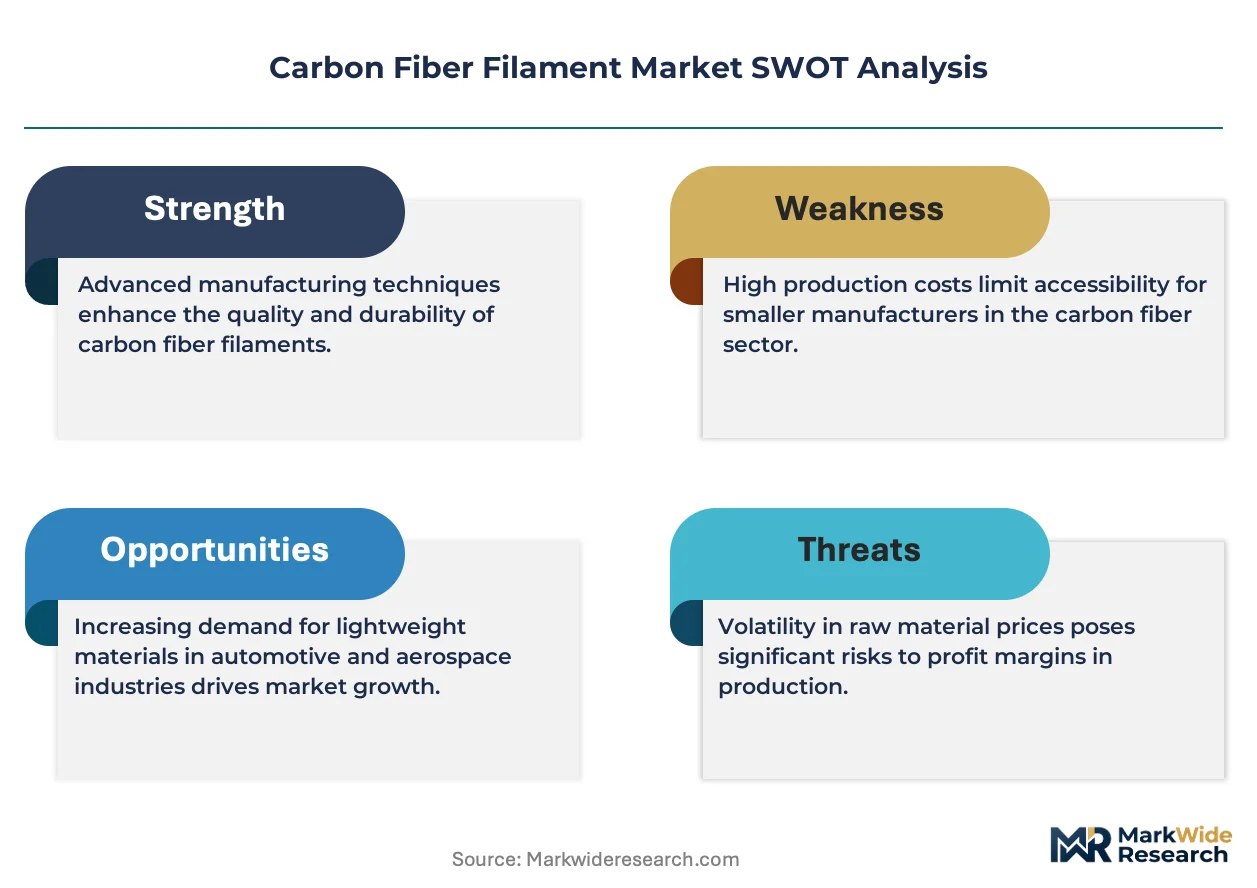
High-performance thermoplastic composites integration is reshaping how automotive and aerospace structures are designed and fabricated. Toray Industries, Inc. leverages its PAN precursor verticality to sustain cost discipline across the value chain. Hexcel Corporation anchors North American aerospace qualification pathways through long-term OEM partnerships. SGL Carbon specializes in automotive-grade carbon fiber filaments, competing on cycle-time reduction for high-volume electric vehicle platforms.
Carbon fiber filament denotes a continuous or chopped fiber reinforcement, typically 5–7 micrometers in diameter, composed of 90%+ carbon by weight and manufactured through controlled pyrolysis of polyacrylonitrile or pitch precursors. It delivers exceptional stiffness-to-weight ratios for load-bearing applications in transportation and energy infrastructure. Composite filament dominates current volume owing to established qualification protocols in aerospace primary structures, while additive manufacturing represents the fastest-growing technology segment as extrusion-based 3D printing of continuous fiber thermoplastics matures. Specialty filament commands premium positioning where pitch-based ultra-high-modulus grades serve satellite and defense applications.
The Federal Aviation Administration mandates damage tolerance and flammability standards that shape carbon fiber filament qualification timelines for commercial aviation applications. REACH and the EU Green Deal impose substance disclosure and embodied carbon thresholds that filter market access for non-European suppliers. China's GB standards and dual carbon goals accelerate domestic precursor-to-filament capacity buildout. Stakeholders must monitor evolving certification reciprocity between the FAA and EASA, as divergence in composite damage tolerance protocols would fragment qualification investments and reshape supplier selection criteria across the Atlantic basin.
Market Dynamics
EU Green Deal emissions mandates are forcing aerospace and automotive OEMs to substitute carbon fiber filament for aluminum and steel in primary load-bearing structures, compressing qualification timelines and reshaping supplier selection criteria across European manufacturing corridors.
Growth Catalysts
- REACH substance disclosure requirements:European manufacturers face embodied carbon thresholds that favor lightweight carbon fiber composites over metal alternatives in transportation applications.
- Electric vehicle platform expansion:Battery enclosure and chassis applications in Germany's automotive manufacturing corridor are absorbing high volumes of automotive-grade filament.
- Pyrolysis process advancement:Controlled oxidation and carbonization techniques are reducing precursor-to-filament conversion costs for PAN-based grades.
Market Restraints
- Acrylonitrile price volatility:PAN precursor costs fluctuate with petrochemical feedstock markets, squeezing filament margin structures.
- Japanese precursor concentration:Toray Industries and Mitsubishi Chemical control over 70% of global PAN precursor supply, creating single-source risk.
- FAA damage tolerance protocols:Commercial aviation qualification timelines extend 18-36 months, freezing new entrants from aftermarket revenue streams.
Strategic Opportunities
- India automotive localization:PLI scheme incentives for advanced materials manufacturing are drawing precursor-to-filament investment into Gujarat and Tamil Nadu industrial zones.
- Continuous fiber 3D printing:Extrusion-based additive manufacturing of thermoplastic composites is opening low-volume, high-complexity geometries previously uneconomical with autoclave curing.
- EU Green Deal carbon border adjustments:Embodied carbon tariffs on imported aluminum and steel widen the cost-competitiveness gap for domestic European carbon fiber production.
Industry Challenges
- Composite repair technician scarcity:Aerospace MRO facilities face recruitment gaps for bonded repair certification, constraining fleet expansion rates.
- Autoclave capacity bottlenecks:Out-of-autoclave curing technology adoption lags qualification requirements for primary structures, trapping capital in legacy equipment.
- FAA-EASA certification divergence:Damage tolerance testing protocol misalignment forces dual qualification investments for transatlantic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Fiber Filament Market |
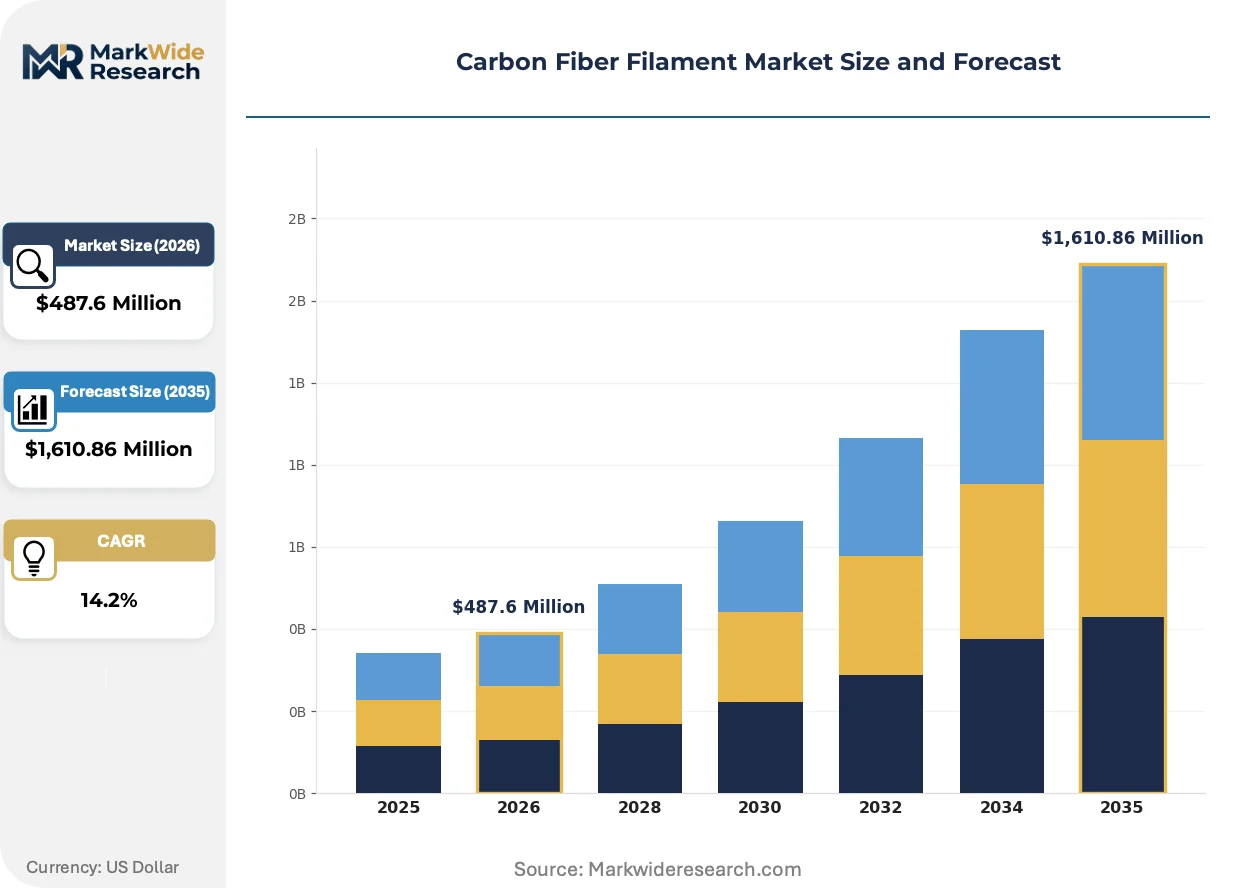
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Filament, Reinforced Filament, Continuous Fiber, Specialty Filament Application: Aerospace, Automotive, Sporting Goods, Industrial Equipment End User: Manufacturers, Suppliers, Retailers, Distributors Technology: Additive Manufacturing, 3D Printing, Filament Winding, Pultrusion |
| Companies Covered | Hexcel Corporation, Hyosung Advanced Materials, Toray Industries, Inc., Zhongfu Shenying Carbon Fiber Co., Ltd., SGL Carbon, Solvay, Teijin Limited, Nippon Graphite Fiber Co., Ltd., Mitsubishi Chemical Carbon Fiber and Composites, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Fiber Filament Market Evolving Landscape
Carbon fiber filament manufacturing is pivoting from thermoset-dominated aerospace qualification pathways toward thermoplastic processing methods that enable rapid cycle times for automotive scale. This migration compresses tooling costs and reshapes competitive positioning across material suppliers.
Continuous fiber-reinforced thermoplastic (CFRTP) technology is migrating from aerospace secondary structures into automotive chassis and battery enclosure applications. BMW and Porsche procurement teams are qualifying unidirectional tape formats for press-forming lines at 60-90 second cycle times. The technology is migrating from autoclave-cured epoxy prepregs toward in-situ consolidation processes that eliminate post-cure oven requirements.
REACH Annex XIV authorization lists are expanding to cover residual solvents in sizing chemistries used during filament surface treatment. European compounders must reformulate epoxy and thermoplastic sizings to maintain market access. Small-diameter filament grades for wind turbine blade spar caps face the steepest compliance cost escalation as blade OEMs consolidate European supply bases.
Buyer concentration among tier-one aerospace primes is compressing supplier negotiation cycles from annual to quarterly price reviews. Lockheed Martin and Airbus procurement organizations are unbundling material supply from fabrication services, forcing filament producers to compete directly on carbon fiber tow pricing rather than composite part value. This pattern is most visible in Washington State and Toulouse manufacturing clusters where qualification-locked suppliers face margin pressure from second-source entrants.
Carbon Fiber Filament Market Segmentation
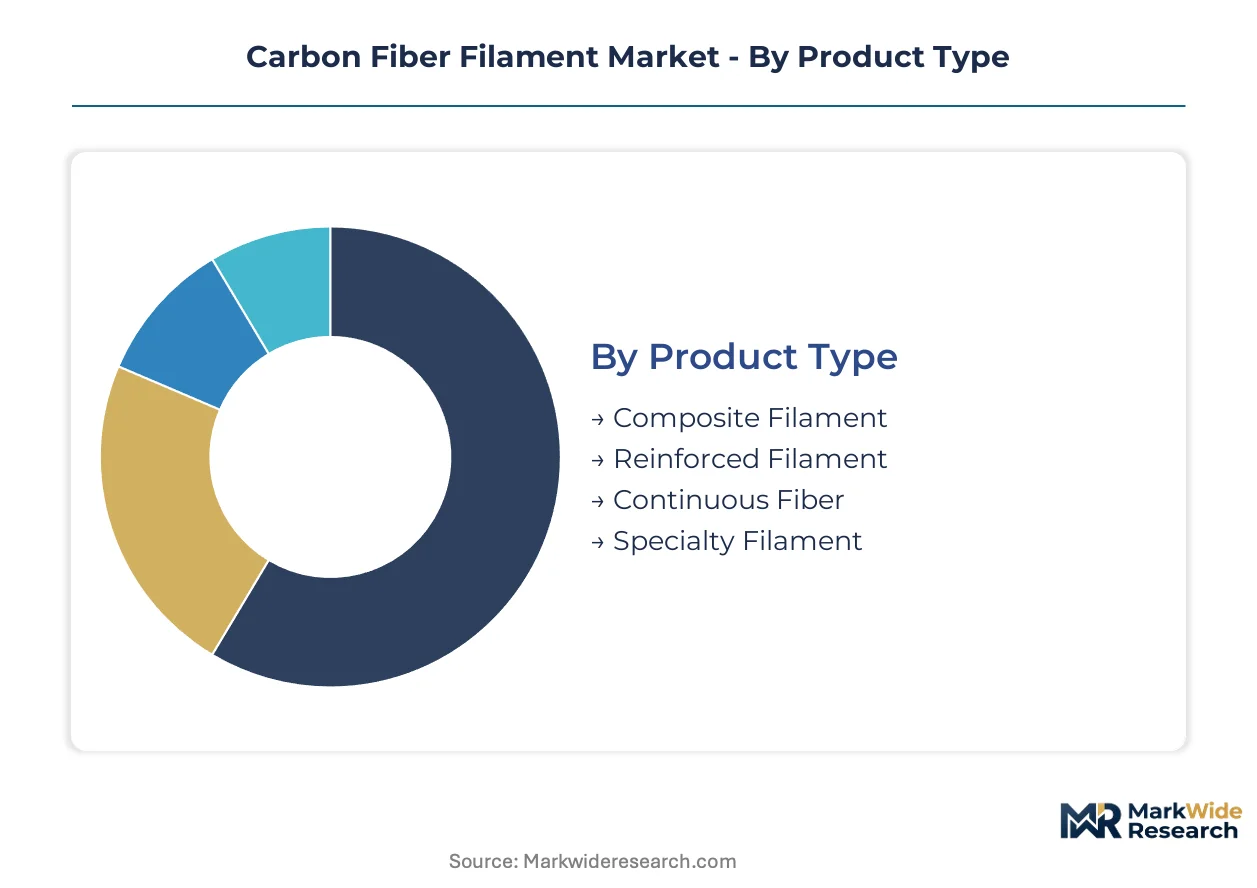
Carbon fiber filament segmentation reveals divergent qualification pathways and margin structures across product grades and manufacturing technologies. Aerospace and automotive procurement teams apply fundamentally different selection criteria, fragmenting supplier strategies across end-use verticals.
Product Type:
Cost tier differentiation separates commodity-grade reinforcements from premium structural filaments commanding qualification-locked pricing.
- Composite Filament:Polymer matrix composites combining carbon fiber with thermoset or thermoplastic binders, typically 30-60% fiber volume fraction. Demand concentrates in Toulouse and Hamburg aerospace clusters where Airbus qualification protocols lock in qualified suppliers. REACH Annex XIV substance disclosure requirements are escalating reformulation costs for European compounders.
- Specialty Filament:Pitch-based ultra-high-modulus grades exceeding 350 GPa tensile modulus for satellite structures and precision optics. Japanese precursor suppliers dominate supply, with Mitsubishi Chemical and Kureha controlling mesophase pitch feedstock access.
- Reinforced Filament:Chopped or milled fiber formats for injection molding compounds serving automotive underhood applications.
- Continuous Fiber:Unidirectional tow and tape formats for automated fiber placement in primary aircraft structures.
Composite filament commands the established base. The steepest expansion runs through specialty filament for defense and space applications.
Application:
Application-driven segmentation reflects divergent performance thresholds and certification burdens across transportation verticals.
- Aerospace:Primary and secondary structural applications requiring FAA/EASA damage tolerance qualification. Boeing and Airbus procurement teams unbundle material supply from fabrication, compressing filament producer margins. Autoclave curing protocols and NDI inspection requirements extend qualification timelines to 36 months for new entrants.
- Automotive:Battery enclosures, chassis components, and body-in-white structures where BMW and Porsche press-forming lines target 60-90 second cycle times. Germany's automotive manufacturing corridor absorbs high volumes of automotive-grade filament as OEMs pursue EU Green Deal emissions targets.
- Sporting Goods:Bicycle frames, golf shafts, and hockey sticks where performance branding supports premium pricing.
- Industrial Equipment:Robotics arms, tooling fixtures, and automation components requiring stiffness-to-weight optimization.
Aerospace retains the value concentration. Automotive applications are climbing the fastest as CFRTP processing matures.
End User:
Customer type segmentation captures divergent procurement sophistication and volume scale across the value chain.
- Manufacturers:Tier-one aerospace primes and automotive OEMs with captive composite fabrication operations. Lockheed Martin and Airbus procurement organizations conduct quarterly price reviews, compressing supplier negotiation cycles from annual to quarterly intervals.
- Suppliers:Tier-two compounders and prepreg converters serving multiple OEM platforms. These intermediaries face margin pressure from direct material sourcing by consolidated primes.
- Distributors:Technical distributors stocking qualified grades for MRO and aftermarket applications.
- Retailers:Specialty channels serving sporting goods and hobbyist additive manufacturing markets.
Manufacturers control volume allocation. Distributors are gaining share fastest as aftermarket repair networks expand.
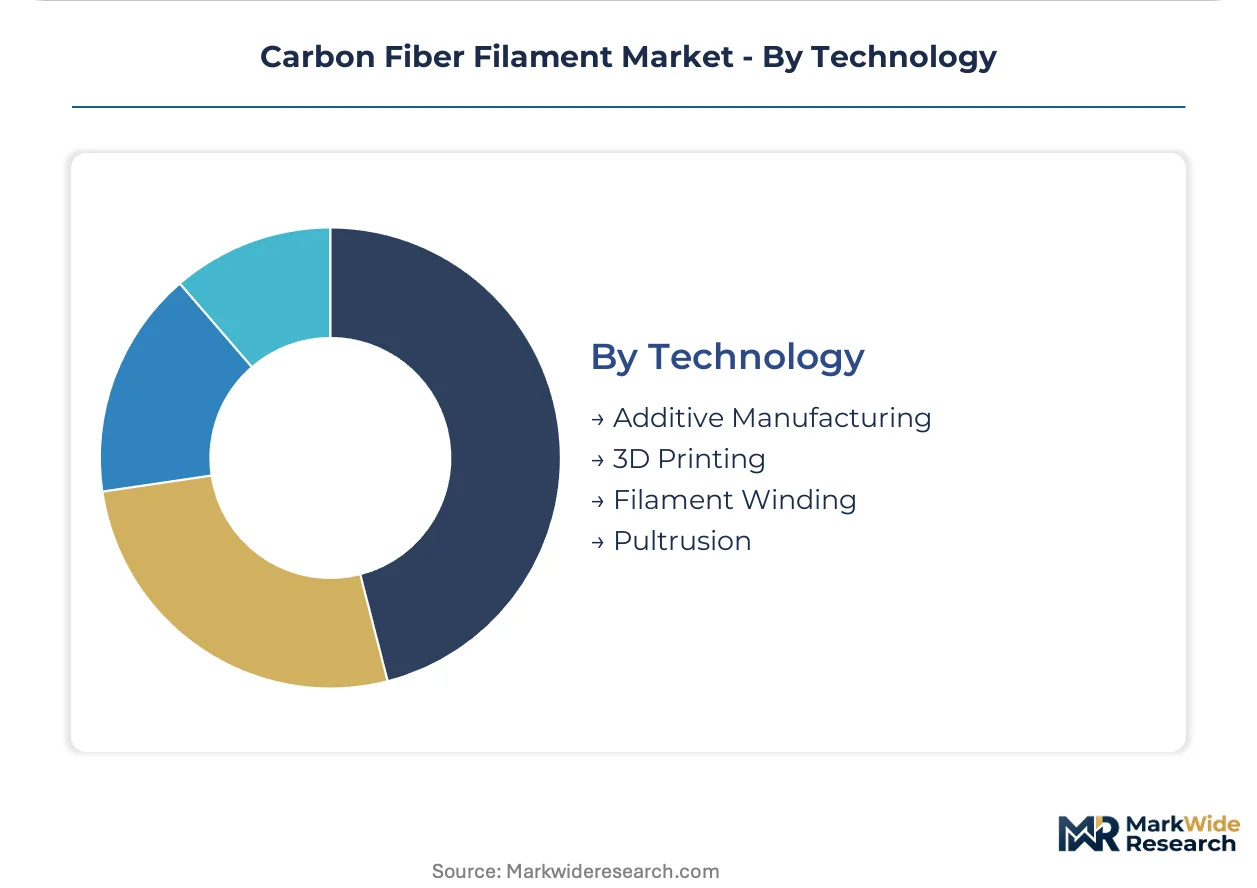
Technology:
Manufacturing method segmentation tracks the migration from thermoset-dominated aerospace pathways toward thermoplastic-enabled automotive scale.
- Filament Winding:Automated placement of continuous fiber onto mandrels for pressure vessels and cylindrical structures. Demand concentrates in hydrogen storage tank applications for fuel cell vehicles.
- Additive Manufacturing:Extrusion-based 3D printing of continuous fiber thermoplastics enabling low-volume, high-complexity geometries previously uneconomical with autoclave curing. AREVO and Continuous Composites are advancing in-situ consolidation processes.
- 3D Printing:Fused filament fabrication using chopped fiber-reinforced thermoplastics for prototyping and tooling.
- Pultrusion:Continuous profile manufacturing for structural beams and construction applications.
Filament winding anchors industrial volume. Additive manufacturing is expanding most quickly as equipment costs decline and qualification protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese precursor suppliers dominate upstream supply chains, exporting PAN-based feedstock to aerospace fabricators across Germany, the United States, and China's expanding domestic filament sector.
United States
Boeing's 787 and 777X programs drive qualification-locked demand for aerospace-grade tow. FAA damage tolerance protocols extend certification timelines to 36 months for new entrants. Washington State manufacturing clusters anchor North American composite fabrication capacity.
Germany
BMW and Porsche press-forming lines absorb automotive-grade filament for CFRTP battery enclosures. EU Green Deal emissions targets accelerate metal substitution in chassis applications. Bavaria's automotive corridor concentrates thermoplastic composite processing investments.
China
Domestic precursor-to-filament capacity buildout accelerates under dual carbon goals and GB standards harmonization. Commercial aviation programs drive qualification investments. Yangtze River Delta clusters host expanding carbon fiber industrial parks.
Japan
Toray Industries and Mitsubishi Chemical control over 70% of global PAN precursor supply, creating single-source dependencies for downstream filament producers. METI industrial policy supports pitch-based ultra-high-modulus development. Nagoya-Tokyo corridor anchors precursor research infrastructure.
India
PLI scheme incentives draw advanced materials investment into Gujarat and Tamil Nadu industrial zones. Automotive localization programs target battery enclosure applications. Domestic aerospace programs generate initial qualification demand for filament winding applications.
Carbon Fiber Filament Market Competitive Landscape
On the supply side, the industry is bifurcated between Japanese precursor oligopolists and diversified filament fabricators competing on qualification pathways. Toray Industries and Mitsubishi Chemical anchor upstream concentration through captive PAN supply. Mid-tier specialists compete on automotive cycle-time reduction. Strategic moves center on backward integration into precursor production and geographic expansion into India and Southeast Asia to bypass trade friction.
Within the precursor-integrated tier, Toray Industries, Inc. exemplifies vertical control from acrylonitrile to qualified aerospace tow. Hexcel Corporation occupies a position anchoring North American qualification pathways through long-term OEM relationships. SGL Carbon represents the automotive-specialist archetype, competing on press-forming cycle times for electric vehicle platforms.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Hyosung Advanced Materials |
| Toray Industries, Inc. |
| Zhongfu Shenying Carbon Fiber Co., Ltd. |
| SGL Carbon |
| Solvay |
| Teijin Limited |
| Nippon Graphite Fiber Co., Ltd. |
| Mitsubishi Chemical Carbon Fiber and Composites, Inc. |
| Others |
Value Network & Pricing Analysis
The Nagoya-Hamburg precursor freight corridor carries acrylonitrile and PAN feedstock across Eurasian rail networks, where logistics cost spikes amplify Japanese supplier pricing power and force European compounders into tiered sourcing strategies that separate aerospace-qualified tow from automotive-grade filament.
Pricing Analysis
The thermoset-thermoplastic processing gap separates legacy autoclave-cured prepregs from emerging press-forming grades, with CFRTP formats commanding cycle-time premiums in automotive procurement. Contract-based long-term offtake dominates aerospace tiers where FAA qualification locks in supply, while spot purchasing governs commodity chopped fiber. Price differentiation rests on certification tier and volume scale, with EASA-locked suppliers capturing margin above REACH-compliant compounders. Cost compression in standard-modulus grades is intensifying as Chinese domestic capacity feeds global spot markets. Tier-two automotive compounders exhibit highest price sensitivity; satellite-grade pitch-based filament buyers show least.
Supply Chain Analysis
Toray Industries and Mitsubishi Chemical anchor precursor contract manufacturing, controlling mesophase pitch and PAN oxidation capacity that feeds downstream filament tow production. Geographic supply concentration centers on Japan, Germany, and China's Yangtze River Delta, where precursor-to-filament integration is deepening. Raw material dependencies include acrylonitrile monomer, mesophase pitch feedstock, and epoxy sizing chemistries facing REACH Annex XIV reformulation costs. Single-source vulnerability runs through Japanese PAN precursor concentration exceeding seventy percent of global supply. Distribution runs through qualified prepreg converters and tier-one aerospace primes with captive fabrication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend carbon fiber filament's stiffness-to-weight positioning against glass fiber-reinforced thermoplastic substitution in automotive battery enclosures, where cost engineering threatens to displace carbon in volume platforms.
For Market Incumbents: Harden qualification moats by accelerating FAA-EASA harmonization investment to compress dual-certification burdens, and anchor backward integration into acrylonitrile supply through long-term petrochemical partnerships that buffer margin against feedstock volatility. Glass fiber-thermoplastic hybrid entrants threaten mid-modulus automotive grades. For New Entrants and Emerging Players: Build out additive manufacturing filament winding capacity serving India's PLI-incentivized automotive corridor, where battery enclosure localization lacks qualified CFRTP suppliers. Target Gujarat industrial zones with in-situ consolidation equipment that bypasses autoclave bottlenecks. Go-to-market through technical distributor partnerships stocking qualified grades for MRO networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded carbon fiber assets lacking aerospace qualification pathways. Long-term viability hinges on thermoplastic processing scale and precursor integration depth. Watch for FAA-EASA damage tolerance protocol convergence as inflection signal that would unlock transatlantic supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor | Toray's PAN verticality demonstrates cost discipline that Chinese challengers are replicating. |
| Thermoplastic Processing Scale-Up | BMW's 60-second press-forming lines validate CFRTP cycle times for EV platforms. |
| REACH Sizing Chemistry Reformulation | European compounders must reformulate epoxy sizings to maintain EU market access. |
| India PLI Localization | Gujarat industrial zones absorb precursor-to-filament investment for battery enclosure supply. |
| Additive Manufacturing Qualification | AREVO's in-situ consolidation advances continuous fiber 3D printing for low-volume aerospace. |
Research Methodology
The analysis maps precursor supply, filament conversion, composite fabrication, and end-use qualification tiers, each validated through procurement directors at tier-one aerospace primes, automotive platform engineers, REACH compliance officers at European compounders, and technical distributors serving MRO networks. Primary fieldwork combined with secondary validation from customs trade data, EASA certification databases, FAA airworthiness directives, and SEC filings from listed carbon fiber producers. Bottom-up volume builds across automotive, aerospace, and industrial applications triangulated against top-down precursor capacity assessments.
Assumptions held fixed include EU Green Deal emissions trajectory, FAA-EASA certification reciprocity frameworks, and PAN precursor technology pathways; variables stress-tested encompass acrylonitrile price volatility, Chinese domestic capacity buildout rates, and thermoplastic processing adoption curves. Segmentation modeling spanned product grade tier, application performance threshold, end-user procurement sophistication, and manufacturing technology maturity. CAGRs derived from volume elasticity to end-use production forecasts and substitution rate assumptions for metal displacement in transportation.
Stress conditions across feedstock cost bands, qualification timeline compression, and trade policy friction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and technology substitution rates. Quarterly review of EASA-FAA protocol alignment, Chinese GB standard harmonization progress, and automotive OEM CFRTP sourcing announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
Asia-Pacific Carbon Fiber Market
Fibers
Fiberglass Cloth Market
Fibers
Fiberglass Resin Market
Fibers
Viscose Filament Yarn Market
Fibers
Global Bicomponent Fiber Market
Fibers
Ultra-High Molecular Weight Polyethylene Fibers Market
Fibers
Basalt Continuous Fiber (BCF) Market
Fibers
Global Glass Fiber Reinforced Gypsum (GFRG) Market
Fibers
Triacetate Cellulose Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
Global Metal Fiber Market
Fibers
Carbon Fiber in Light Weight Pressure Vessels Market
Fibers
Polytetrahydrofuran Market
Fibers
Global Concrete Fiber Market
Fibers
Global Fiberglass Mold Market