
 Silicone Solutions for Leather and Textile Market | 2026-2036
Silicone Solutions for Leather and Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Solutions for Leather and Textile Market Analytics
EU REACH restrictions on solvent-based formulations is consolidating demand toward compliant silicone chemistries across European tanneries and textile mills. Dow leverages its integrated silicone supply chain to sustain formulation leadership in water-based leather treatments. Wacker Chemie AG anchors its position through specialized emulsion technologies for automotive interior applications. Elkem ASA competes on geographic proximity to Nordic textile clusters with tailored finishing solutions.
Silicone solutions for leather and textile comprise organosilicon compounds formulated as adhesives, coatings, emulsions, and sealants, typically delivered with viscosity ranges of 100-100,000 cSt and active content between 20-60% depending on application intensity. These materials impart water repellency, UV stability, and soft-hand feel to natural and synthetic substrates across fashion, automotive, and furniture end uses. The coatings segment dominates current value generation due to its critical role in automotive interior durability specifications, while emulsions represent the fastest-growing product category as water-based technology displaces solvent alternatives under tightening environmental mandates. Water-based systems command premium positioning in European and North American supply chains, whereas solvent-based formulations retain cost-driven volume in select developing markets where regulatory enforcement remains phased.
EPA oversight in the United States restricts volatile organic compound emissions from textile coating operations, while REACH governs substance authorization across European manufacturing bases. China's MEE implements parallel emission standards that redirect domestic producers toward compliant silicone platforms. Stakeholders must monitor the divergence between regional chemical compliance timelines and the capital requirements for hybrid system conversion.
Market Dynamics
Water-based silicone emulsions are consolidating formulation preferences across European tanneries as REACH substance restrictions phase out solvent-based alternatives. This chemistry pivot is redistributing competitive advantage toward suppliers with integrated emulsion capabilities.
Growth Catalysts
- Automotive Interior Specifications:OEM durability standards for seating and dashboard surfaces are mandating UV-stable silicone coatings that withstand thermal cycling and abrasion testing.
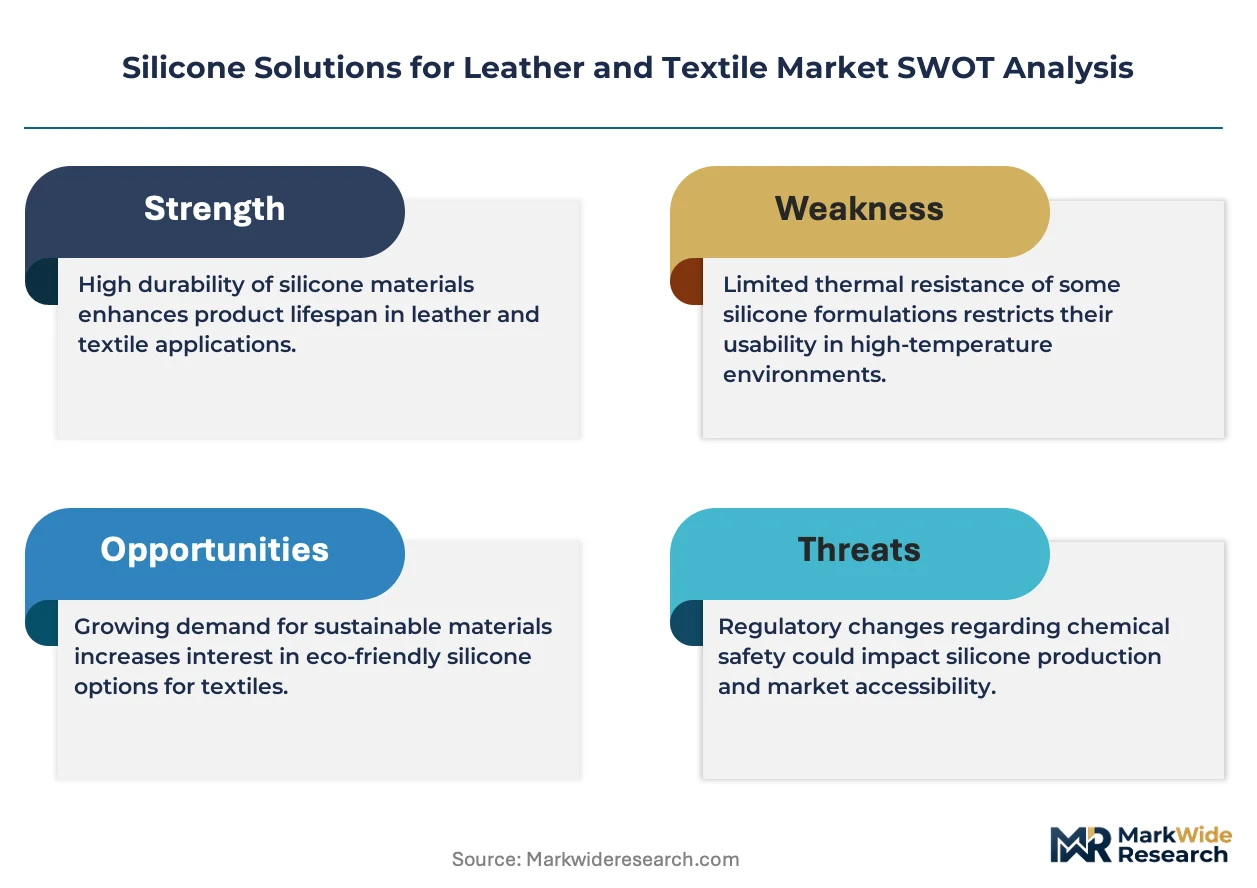
- REACH Substance Authorization:ECHA restrictions on N-methyl-2-pyrrolidone and other solvents in leather processing are redirecting finish-house procurement toward compliant silicone platforms.
- China Dual Carbon Goals:MEE emission intensity targets for textile coating operations are accelerating water-based system adoption in Zhejiang and Jiangsu manufacturing clusters.
Market Restraints
- Siloxane Feedstock Concentration:Organosilicon precursor supply concentrates among integrated chemical producers in Germany and China, creating vulnerability to force majeure events.
- Cure Temperature Requirements:Water-based silicone coatings demand 20-40°C higher drying temperatures than solvent alternatives, elevating natural gas exposure in European finish houses.
- Polyurethane Substitution:Aliphatic polyurethane dispersions compete on cost in furniture and fashion applications where hand-feel specifications permit lower durability.
Strategic Opportunities
- Brazil Leather Export Corridor:São Paulo tanneries serving Italian luxury brands present untapped demand for compliant finishing systems as ANVISA aligns with EU chemical standards.
- Digital Printing Convergence:Inkjet deposition of silicone functional layers onto textile substrates enables on-demand customization with reduced finishing waste.
- EU Green Deal Procurement Mandates:Public sector textile purchasing criteria are embedding recycled content and low-VOC requirements that favor certified silicone suppliers.
Industry Challenges
- Formulation Chemistry Expertise Gap:Leather finish houses lack personnel trained in emulsion stability management and substrate-specific adhesion optimization.
- Capital Equipment Retrofit Requirements:Converting solvent-based coating lines to water-compatible drying and recovery systems demands 18-24 month payback periods.
- Cross-Border Certification Complexity:Divergent testing protocols between OEKO-TEX, bluesign, and ZDHC Roadmap create redundant compliance expenditure for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Solutions for Leather and Textile Market |
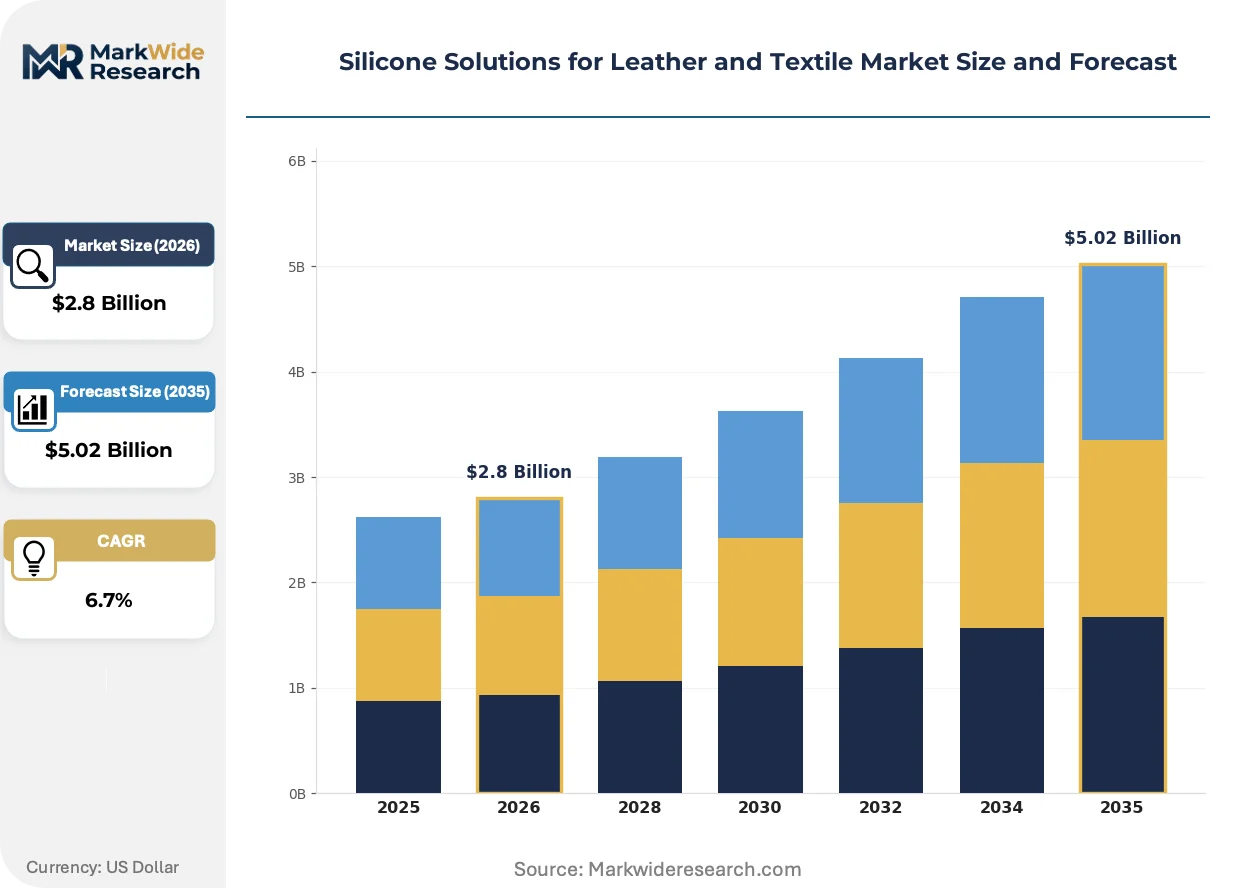
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Coatings, Emulsions, Sealants Application: Textile Finishing, Leather Treatment, Surface Protection, Color Enhancement Technology: Water-Based, Solvent-Based, High-Performance, Hybrid Systems End User: Fashion Industry, Automotive Interiors, Furniture, Footwear |
| Companies Covered | Dow, Wacker Chemie AG, Elkem ASA, Shin-Etsu Chemical Co., Ltd., Momentive Performance Materials, Evonik Industries AG, BASF, Huntsman International LLC., KCC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Solutions for Leather and Textile Market Evolving Landscape
Silicone chemistry advancement is compressing the performance gap between water-based and legacy solvent systems while regulatory pressure eliminates the latter's cost advantage. Three developments are restructuring competitive positioning.
Plasma-enhanced chemical vapor deposition is automating the application of ultra-thin silicone barrier layers onto synthetic leather substrates. Automotive seating manufacturers in Stuttgart and Wolfsburg are piloting this process to eliminate coating line wastewater discharge. The technology is automating quality control through in-line thickness monitoring that reduces rework rates.
EPA New Source Performance Standards for synthetic organic chemical manufacturing are tightening VOC emission limits for textile coating operations in Texas and North Carolina. Facilities exceeding 100 tons per year of regulated pollutants must install regenerative thermal oxidizers or switch to compliant chemistries. Small-batch custom finishers in the Carolinas are consolidating toward water-based silicone platforms to avoid capital expenditure.
Brand-led chemical management is restructuring supplier relationships in fashion and furniture verticals. ZDHC MRSL conformance is becoming a gatekeeper criterion for mill inclusion programs, displacing transactional purchasing based on unit cost alone. This pattern concentrates procurement authority among finish houses with verified supply chain transparency, particularly visible in Italian and Portuguese leather goods manufacturing.
Silicone Solutions for Leather and Textile Market Segmentation
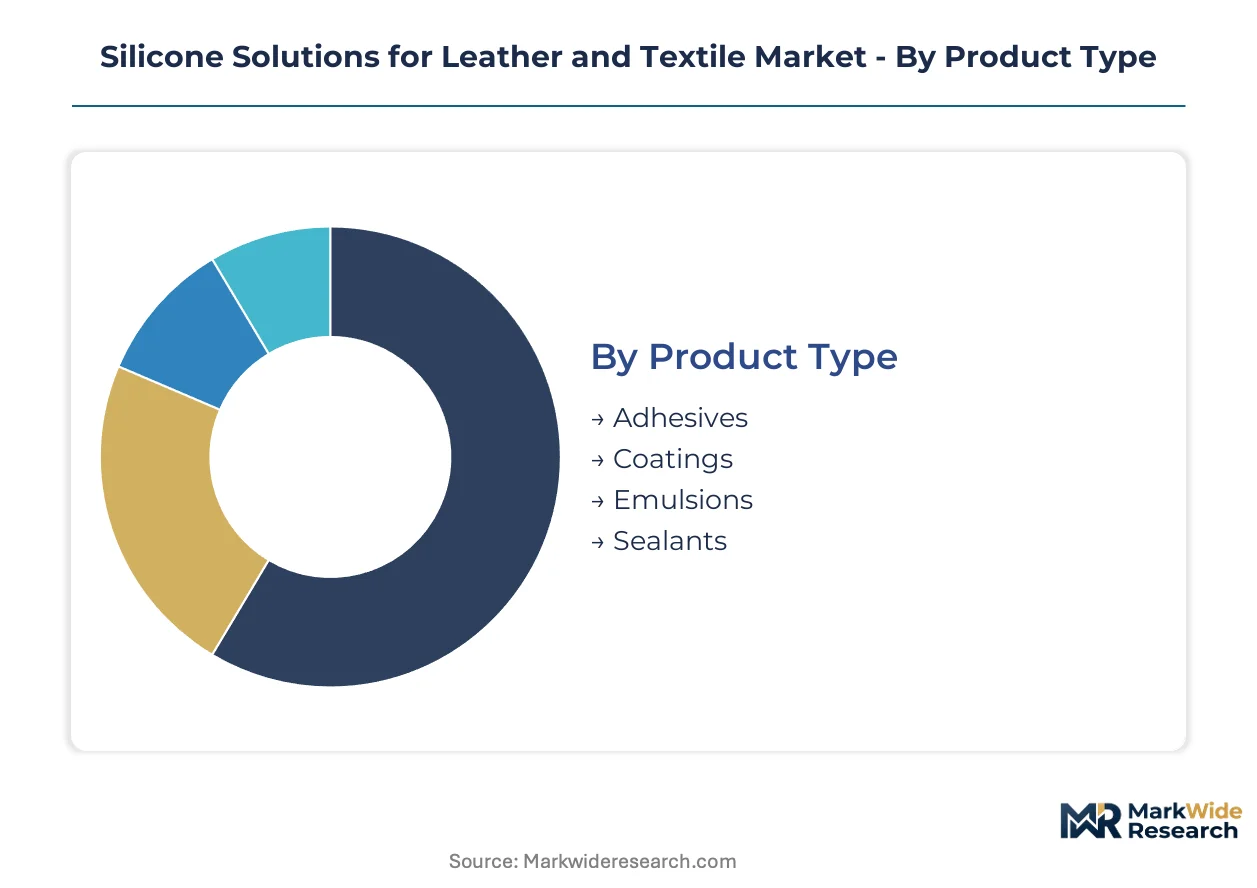
Silicone solutions for leather and textile applications fragment across four critical dimensions that determine formulation chemistry, regulatory compliance burden, and capital deployment intensity. Each segmentation axis reveals distinct margin structures and competitive moats.
Product Type:
Capital intensity concentrates in emulsion manufacturing infrastructure, where continuous-phase stability systems demand precision temperature control and specialized homogenization equipment.
- Adhesives:Pressure-sensitive and structural bonding formulations incorporate silanol-terminated polymers with 1,000-50,000 cSt viscosity ranges. Demand clusters in automotive seating lamination operations across Stuttgart and Wolfsburg manufacturing corridors, where OEM specifications mandate peel strength above 5 N/cm.
- Coatings:UV-curable and thermal-cure films deliver 50-200 micron dry-film thickness for synthetic leather substrates. Italian luxury tanneries in Tuscany and Veneto absorb the majority of high-performance coating volume, driven by durability specifications exceeding 100,000 Martindale abrasion cycles.
- Emulsions:Aqueous silicone dispersions with 20-60% active content displace solvent systems under tightening emission mandates.
- Sealants:Elastomeric joint compounds provide moisture barriers in furniture upholstery and marine textile applications.
Coatings absorb the bulk of installed capacity; emulsions are expanding most quickly.
Application:
Customer willingness-to-pay varies sharply by substrate protection requirements, with automotive specifications commanding formulation premiums of 40-60% above furniture-grade equivalents.
- Textile Finishing:Soft-hand treatments and water-repellent coatings for synthetic and natural fibers. Zhejiang and Jiangsu manufacturing clusters in China drive volume for apparel and home textile applications, where MEE emission standards redirect procurement toward water-based platforms.
- Leather Treatment:Aniline and semi-aniline finishing systems for full-grain and corrected-grain hides. São Paulo tanneries serving Italian luxury brands present concentrated demand for REACH-aligned finishing systems as ANVISA harmonizes with EU chemical standards.
- Surface Protection:Abrasion-resistant and stain-repellent functional layers.
- Color Enhancement:Pigment-binding and gloss-modifying additives for aesthetic finishing.
Leather treatment commands the highest formulation margins; textile finishing is climbing the fastest.
Technology:
Regulatory divergence across jurisdictions creates technology lock-in effects, with European finish houses unable to back-integrate into solvent-based production without ECHA authorization exposure.
- Water-Based:Aqueous emulsion and dispersion systems with VOC content below 50 g/L. European tanneries under REACH substance restrictions have consolidated procurement toward these platforms, with Dow and Wacker Chemie AG capturing formulation leadership through integrated emulsion supply chains.
- Solvent-Based:Organic-solvent carriers with superior substrate penetration and lower drying energy requirements. Select developing markets retain cost-driven volume where regulatory enforcement remains phased.
- High-Performance:Fluorosilicone and phenyl-modified systems for extreme temperature and chemical resistance.
- Hybrid Systems:Water-borne polyurethane-silicone copolymers balancing performance and compliance.
Solvent-based retains residual volume in cost-sensitive segments; water-based is gaining share fastest.
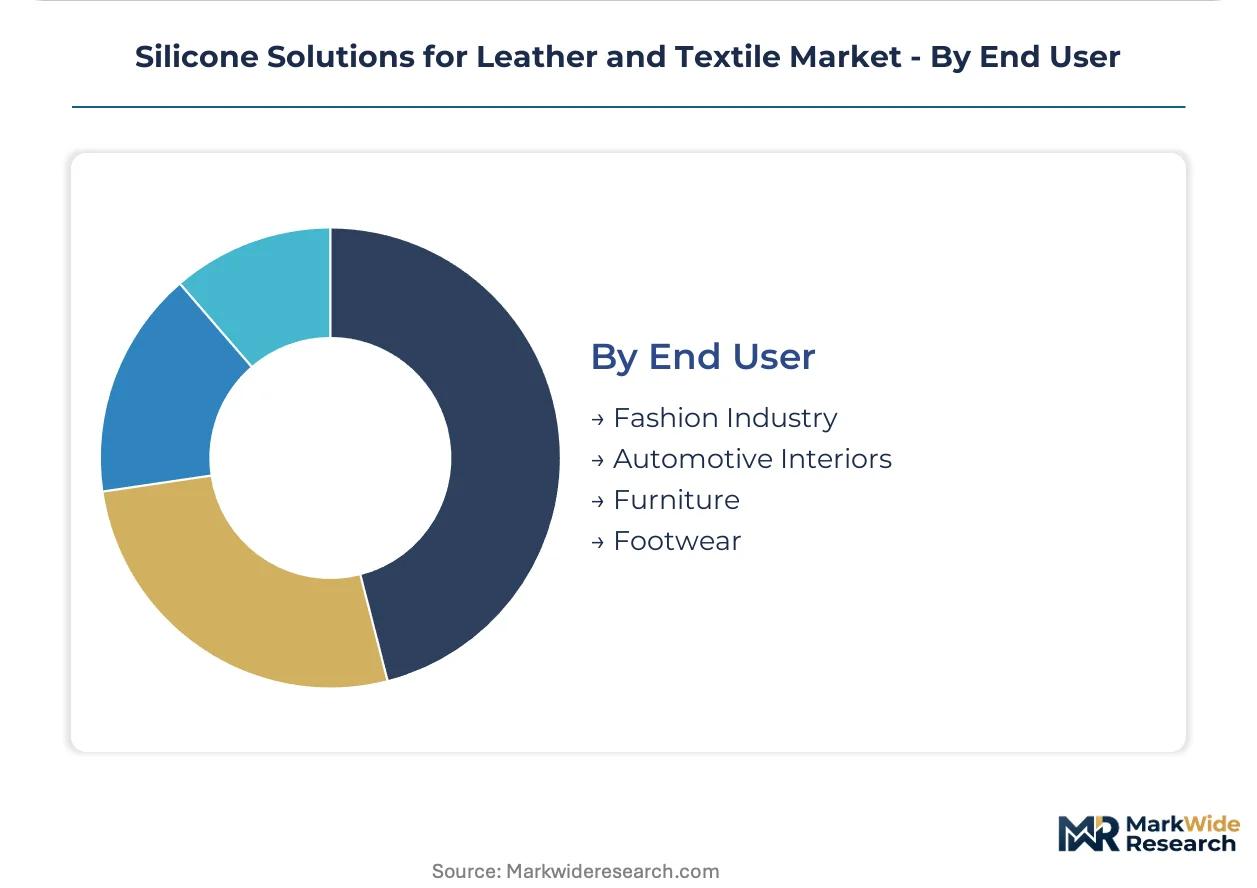
End User:
Specification authority concentrates with automotive OEMs and luxury fashion houses, who cascade chemical compliance requirements through tiered supplier networks.
- Fashion Industry:Apparel, accessories, and luxury leather goods requiring soft-hand aesthetics and colorfastness. Portuguese and Italian leather goods manufacturers enforce ZDHC MRSL conformance as a gatekeeper criterion, concentrating procurement among verified supply chain partners.
- Automotive Interiors:Seating, dashboard, and door panel surfaces subject to thermal cycling, abrasion, and UV exposure specifications. OEM durability standards mandate silicone coatings with 5-year color retention and 150°C thermal stability.
- Furniture:Upholstery and decorative applications with moderate durability requirements.
- Footwear:Athletic and fashion shoe upper treatments combining flexibility and water resistance.
Automotive interiors anchor premium pricing; fashion industry procurement is accelerating most sharply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates silicone precursor manufacturing capacity while Germany and Italy dominate high-value leather finishing formulation. Consumption growth accelerates in Brazil and India as export-oriented tanneries upgrade to compliant chemistries.
Germany
Automotive OEM specifications from Stuttgart and Wolfsburg drive premium coating demand. ECHA REACH substance restrictions phase out solvent-based alternatives in Baden-Württemberg tanneries. Wacker Chemie AG anchors emulsion supply chains from Burghausen manufacturing complexes.
China
Zhejiang and Jiangsu textile clusters absorb water-based silicone volume for apparel export production. MEE emission intensity targets redirect coating operations toward compliant platforms. The dual carbon goals accelerate capital deployment in Hangzhou and Shaoxing finishing facilities.
Italy
Tuscan and Veneto luxury tanneries specify coatings exceeding 100,000 Martindale abrasion cycles. ZDHC MRSL conformance gates mill inclusion programs for Armani and Prada supply chains. Solofra and Santa Croce sull'Arno concentrate artisanal finishing expertise.
Brazil
São Paulo tanneries serving Italian luxury brands present concentrated demand for REACH-aligned systems. ANVISA harmonizes chemical standards with EU regulations through phased enforcement timelines. The Campinas corridor attracts formulation technical service investments.
United States
EPA New Source Performance Standards tighten VOC limits for textile coating in Texas and North Carolina. Small-batch finishers consolidate toward water-based platforms to avoid thermal oxidizer capital expenditure. Carolinas furniture upholstery clusters drive emulsion specification.
Silicone Solutions for Leather and Textile Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive siloxane feedstock. Three tiers operate: multinational diversified materials suppliers, regional emulsion specialists, and automotive-focused coating formulators. Capacity expansion and strategic partnerships dominate competitive moves as players secure compliant chemistry pipelines.
Within the integrated materials tier, Dow and Wacker Chemie AG exemplify formulation leadership through emulsion technology control. Elkem ASA occupies a position among Nordic-proximate suppliers serving specialized textile clusters. These three entities anchor the premium water-based segment where regulatory compliance creates qualification barriers.
| Leading Market Players |
|---|
| Dow |
| Wacker Chemie AG |
| Elkem ASA |
| Shin-Etsu Chemical Co., Ltd. |
| Momentive Performance Materials |
| Evonik Industries AG |
| BASF |
| Huntsman International LLC. |
| KCC Corporation |
| Others |
Value Network & Pricing Analysis
Siloxane precursor costs cascade through three pricing tiers as organosilicon feedstock from Germany and China converts into finished emulsions for European automotive OEMs and São Paulo tanneries. Energy-intensive drying requirements for water-based systems elevate natural gas exposure in Italian finish houses, compressing margins at the standard tier while REACH-compliant premiums hold firm.
Pricing Analysis
Yield-guaranteed coating performance anchors value-based pricing for automotive seating specifications exceeding 100,000 Martindale abrasion cycles. Certification tier—bluesign versus uncertified—drives 40-60% price differentiation between premium and economy segments. Cost compression in standard-grade furniture applications intensifies as aliphatic polyurethane dispersions undercut silicone on unit economics. Small-batch custom finishers in the Carolinas exhibit highest price sensitivity, while luxury tanneries in Tuscany absorb formulation premiums for ZDHC MRSL conformance.
Supply Chain Analysis
Refurbishment flows for coating line equipment—from solvent-based to water-compatible drying systems—extend capital deployment cycles across European finish houses. Organosilicon precursor manufacturing concentrates in Germany and China, with emulsion formulation clustering in Italy and the United States. Siloxane feedstock, specialized homogenization equipment, and natural gas for thermal curing constitute critical input dependencies. Single-source vulnerability in siloxane supply creates exposure to force majeure disruptions. Distribution runs through integrated chemical conglomerates with captive feedstock and regional emulsion specialists serving Nordic textile clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silicone solutions market sits in a chemistry-transition phase as water-based emulsion technology displaces solvent-based legacy systems under REACH and EPA emission mandates.
For Market Incumbents: Acquire specialized emulsion technology assets to consolidate formulation leadership as polyurethane substitution threatens furniture-grade margins. Dow and Wacker Chemie AG already anchor integrated supply chains; challengers must secure backward control over siloxane feedstock or risk disqualification from automotive OEM qualification programs. Certification investment in ZDHC MRSL and bluesign systems gates mill inclusion programs for Italian luxury supply chains. For New Entrants and Emerging Players: ANVISA harmonization with EU chemical standards in Brazil opens a window for REACH-aligned finishing systems in São Paulo tanneries serving export markets. Digital printing convergence for on-demand silicone functional layer deposition represents the most penetrable white-space, with reduced finishing waste appealing to sustainability-positioned brands. Target technical service partnerships with Campinas corridor tanneries as the go-to-market anchor. For Investors and Strategic Acquirers: Capital deployment in Hangzhou and Shaoxing finishing facilities under China's dual carbon goals is the leading indicator that water-based system adoption is crossing the inflection threshold. Over a multi-year horizon, vertically integrated emulsion specialists with automotive OEM qualification offer superior viability than commodity coating distributors. Monitor EPA New Source Performance Standards enforcement in Texas and North Carolina for regulatory acceleration signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Feedstock | Captive organosilicon supply secures margin control against force majeure disruptions in Germany and China. |
| Water-Based Emulsion Capacity Expansion | Hangzhou and Shaoxing facilities align with MEE emission intensity targets for Zhejiang textile clusters. |
| ZDHC MRSL Certification Investment | Conformance gates mill inclusion programs for Armani and Prada supply chain participation. |
| Digital Printing Technology Partnership | Inkjet deposition of silicone layers enables on-demand customization with reduced finishing waste. |
| Technical Service Hub in Campinas Corridor | São Paulo tannery proximity supports ANVISA-aligned formulation adoption for Italian luxury exports. |
Research Methodology
Document review covered customs and trade data, SEC filings from integrated chemical producers, ECHA substance authorization databases, and MEE emission standard disclosures, complemented by interviews with tannery technical directors, automotive OEM procurement managers, textile mill R&D leads, and emulsion equipment suppliers. Bottom-up volume modeling across product types and applications triangulated against top-down industry association data from ACC and Cefic.
Cross-referencing historical adoption curves with expert panel input on regulatory phase-in timelines shaped the projection framework across the analysis window. Segmentation dimensions modeled include product chemistry, substrate application, technology platform, and end-use industry vertical. CAGRs derived from elasticity-adjusted demand curves incorporating automotive production forecasts and leather export volume trends.
The model assumes a particular technology adoption path; alternative pathways for plasma-enhanced chemical vapor deposition would alter the outlook if Stuttgart and Wolfsburg OEMs accelerate pilot programs. Forecasts reflect assumptions about REACH enforcement consistency and natural gas price stability. Practitioners should monitor EPA thermal oxidizer mandate thresholds and ANVISA harmonization deadlines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Sheath Materials Market
Specialty Materials
Nanoencapsulation Market
Specialty Materials
PVB Interlayers Market
Specialty Materials
Sulphur Bentonite Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Africa Collagen Market
Specialty Materials
Hornbeam Market
Specialty Materials
Colloidal Silica Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Polyimide Films Market
Specialty Materials
Specialty Polyamides Market
Specialty Materials
Melamine Foam Market
Specialty Materials
Specialty Silica Market
Specialty Materials
Asia-Pacific Colloidal Silica Market