
 UV Stabilized Films Market | 2026-2036
UV Stabilized Films Market Size, Share, and Industry Trends Forecast 2026-2036
UV Stabilized Films Market Analytics
Commercial greenhouse operators is unwinding legacy purchasing patterns from smallholder cooperatives toward integrated agribusiness chains with multi-hectare coverage requirements. Berry Global leverages its North American blown film infrastructure to serve controlled-environment agriculture customers with customized UV stabilization packages. Ginegar anchors the Middle Eastern and Mediterranean markets through its Israel-based manufacturing, where solar irradiance levels demand specialized additive loading. Polifilm competes on European greenhouse retrofit cycles, supplying replacement films with extended service-life guarantees.
UV stabilized films are polymer substrates incorporating hindered amine light stabilizers or benzotriazole absorbers at concentrations typically ranging from 0.1% to 2.0% by weight, manufactured through multi-layer coextrusion to achieve controlled photodegradation resistance over 3-5 year outdoor exposure cycles. Polyethylene formulations dominate volume flows due to cost efficiency in agricultural mulching and tunnel applications, while PET grades command margin premiums in photovoltaic backsheet and high-performance glazing laminates. The 100-200 micron thickness band captures the bulk of greenhouse cover demand, though above-300 micron architectural membranes represent the fastest-expanding value pool as building-integrated photovoltaics proliferate.
EPA guidelines govern additive migration thresholds for agricultural films in contact with soil and water tables, while REACH restricts certain benzophenone derivatives in European supply chains, compelling stabilizer suppliers to validate alternative chemistries. China's GB standards and MEE enforcement actions on plastic film recycling are reshaping domestic formulation requirements and import acceptance protocols. Stakeholders must monitor regulatory divergence between additive approval lists as formulation decisions made for one jurisdiction increasingly preclude market access in another.
Market Dynamics
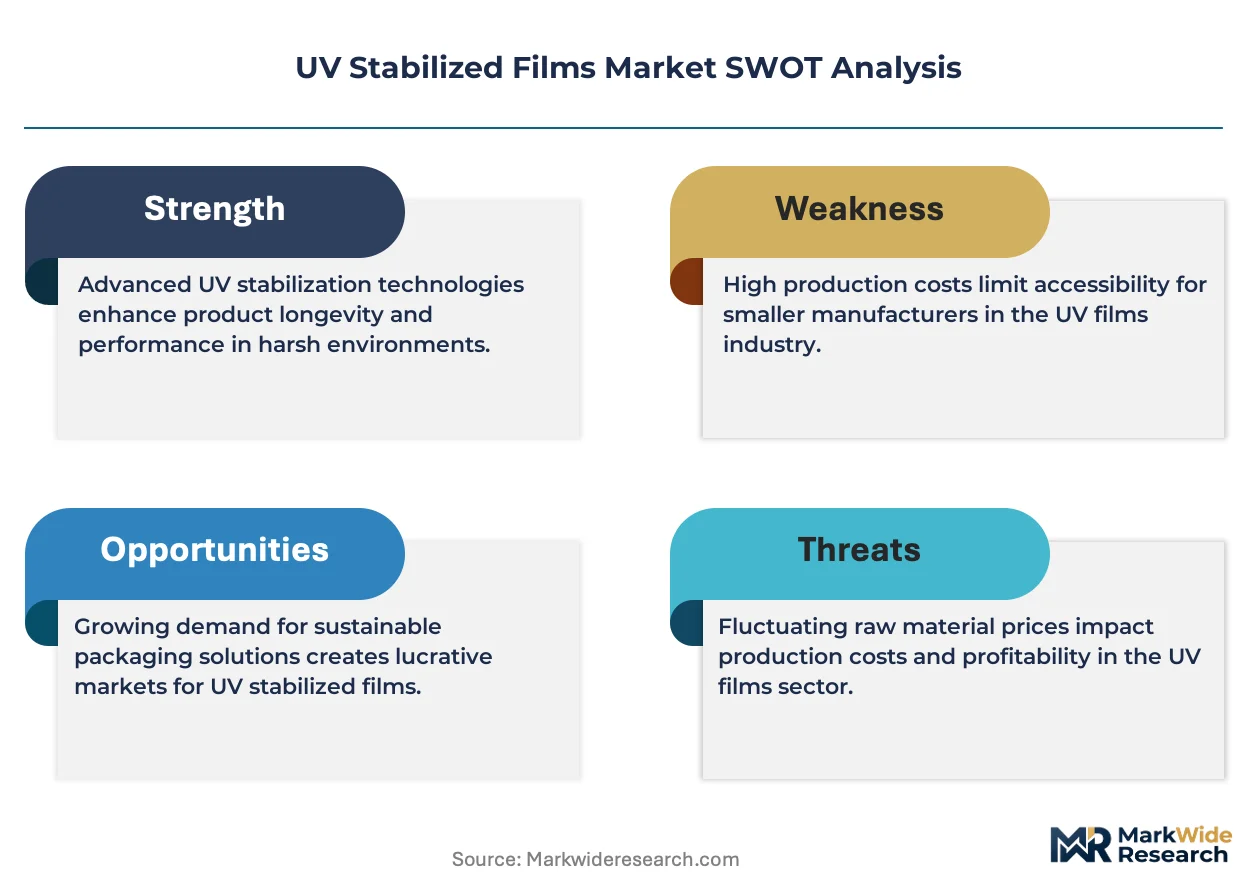
Reformulation pressure on hindered amine light stabilizer packages is compressing formulation flexibility as REACH and EPA additive migration limits tighten simultaneously, forcing suppliers to maintain parallel product portfolios for cross-border market access.
Growth Catalysts
- Climate volatility in agricultural belts:Greenhouse operators across Spain, Morocco, and California are accelerating replacement cycles for UV-stabilized covers as extreme weather events damage conventional films faster than historical baselines predicted.
- REACH compliance deadlines:European greenhouse retrofit mandates are pulling forward demand for certified replacement films with validated additive packages, creating a concentrated replacement window through 2027.
- Building-integrated photovoltaics:Architectural membrane specifications above 300 microns are absorbing UV-stabilized PET grades as BIPV installations in Germany and Japan require 25-year weathering guarantees.
Market Restraints
- Hindered amine raw material concentration:BASF and Clariant control over 60% of global HALS supply, creating single-source vulnerability for mid-tier film extruders in Turkey and Mexico.
- Regulatory fragmentation costs:Divergent additive approval lists between EPA soil-contact thresholds and REACH benzophenone restrictions force dual-validation expenditures that squeeze margin on standard agricultural grades.
- Mechanical recycling incompatibility:Stabilizer residues in post-consumer greenhouse films contaminate mechanical recycling streams, limiting circular economy pathways and exposing producers to China's MEE enforcement actions on plastic film waste.
Strategic Opportunities
- Saudi Arabia controlled-environment agriculture:NEOM and Red Sea Project developments are specifying high-load UV stabilization for desert greenhouse complexes with 50°C ambient operating conditions.
- Photovoltaic backsheet substitution:Fluoropolymer-free PET laminates with enhanced UV stabilization are penetrating utility-scale solar installations as module manufacturers seek supply chain decarbonization.
- India PLI scheme for specialty chemicals:Domestic HALS production incentives are enabling localized formulation for agricultural film exporters targeting Southeast Asian greenhouse markets.
Industry Challenges
- Formulation chemist scarcity:Expertise in photostabilizer synergy optimization for multi-layer coextrusion is concentrated among retiring specialists at European additive houses, constraining new product development timelines.
- Migration testing backlog:EPA and ECHA validation queues for novel benzotriazole alternatives extend 18-24 months, delaying market entry for reformulated products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Stabilized Films Market |
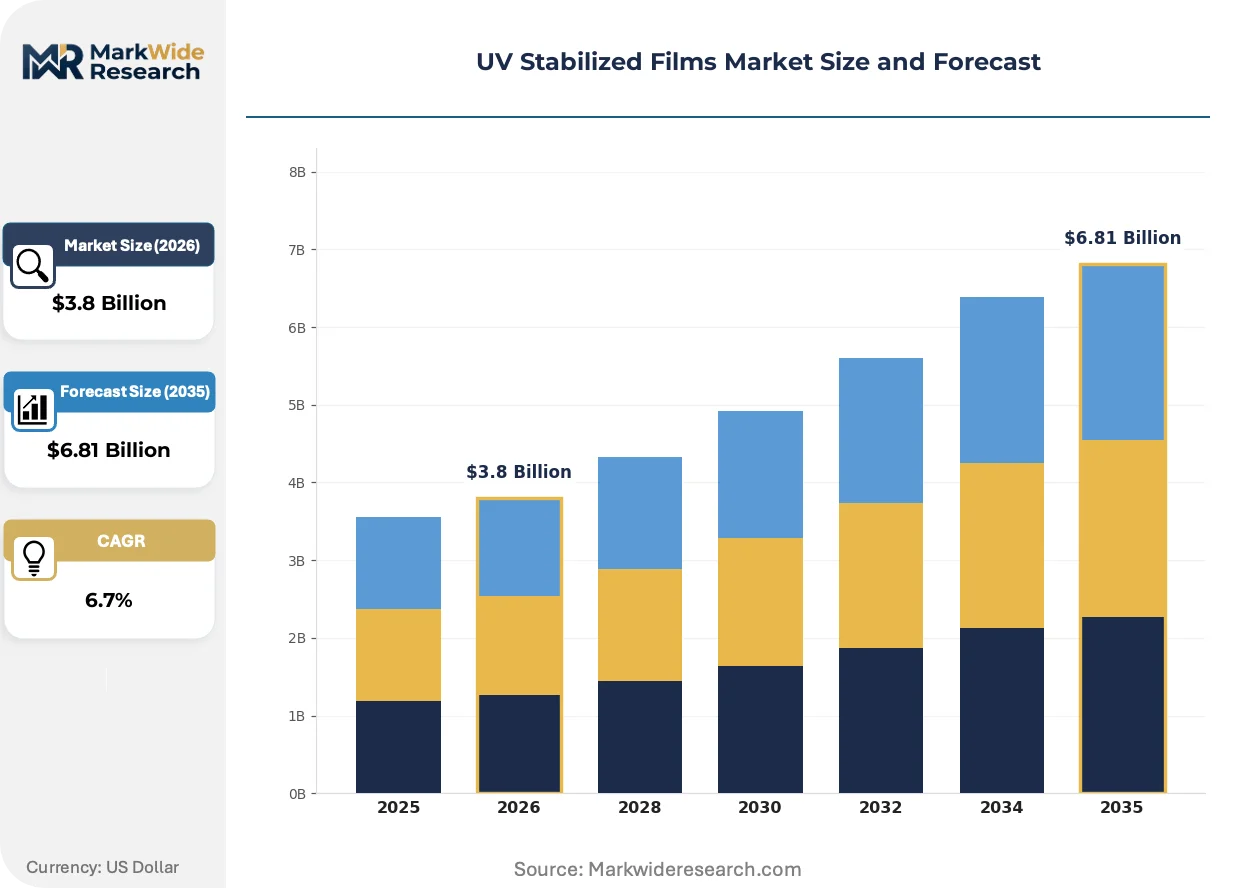
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, PET Application: Agricultural Films, Packaging, Building & Construction, Automotive End User: Manufacturers, Retailers, Distributors, Consumers Thickness: Below 100 Microns, 100-200 Microns, 200-300 Microns, Above 300 Microns |
| Companies Covered | Plastika Kritis, Armando Alvarez Group, Berry Global, Rani Group, Polifilm, Coveris, Ginegar, Novolex, RKW Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Stabilized Films Market Evolving Landscape
Active ingredient strategies are diverging between agricultural cost-optimization and architectural performance-premium tracks, with formulation architecture becoming the primary competitive differentiator.
Nano-dispersed HALS systems are bifurcating the stabilization technology landscape. These systems deliver extended service life at reduced loadings compared to conventional macro-dispersed additives. Greenhouse operators in the Netherlands and Japan are specifying nano-enhanced grades for 5-year replacement cycles versus standard 3-year intervals. The technology is compressing price competition on commodity polyethylene films while expanding margin pools in certified long-life segments.
ECHA's 2023 restriction proposal on certain benzophenone-3 derivatives is forcing immediate reformulation across European supply chains. Film converters must validate alternative UV absorber chemistries or exit soil-contact applications entirely. Agricultural mulch film producers in Italy and Poland are accelerating trials of triazine-class absorbers, though these carry 15-20% raw material cost premiums.
Integrated agribusiness chains are consolidating procurement authority previously dispersed through grower cooperatives. Berry Global and Ginegar now negotiate multi-hectare supply agreements directly with Chilean and Mexican berry producers, displacing distributor-mediated purchasing. This concentration is most visible in Almería's greenhouse cluster, where three buying groups now control 40% of regional cover film volume.
UV Stabilized Films Market Segmentation
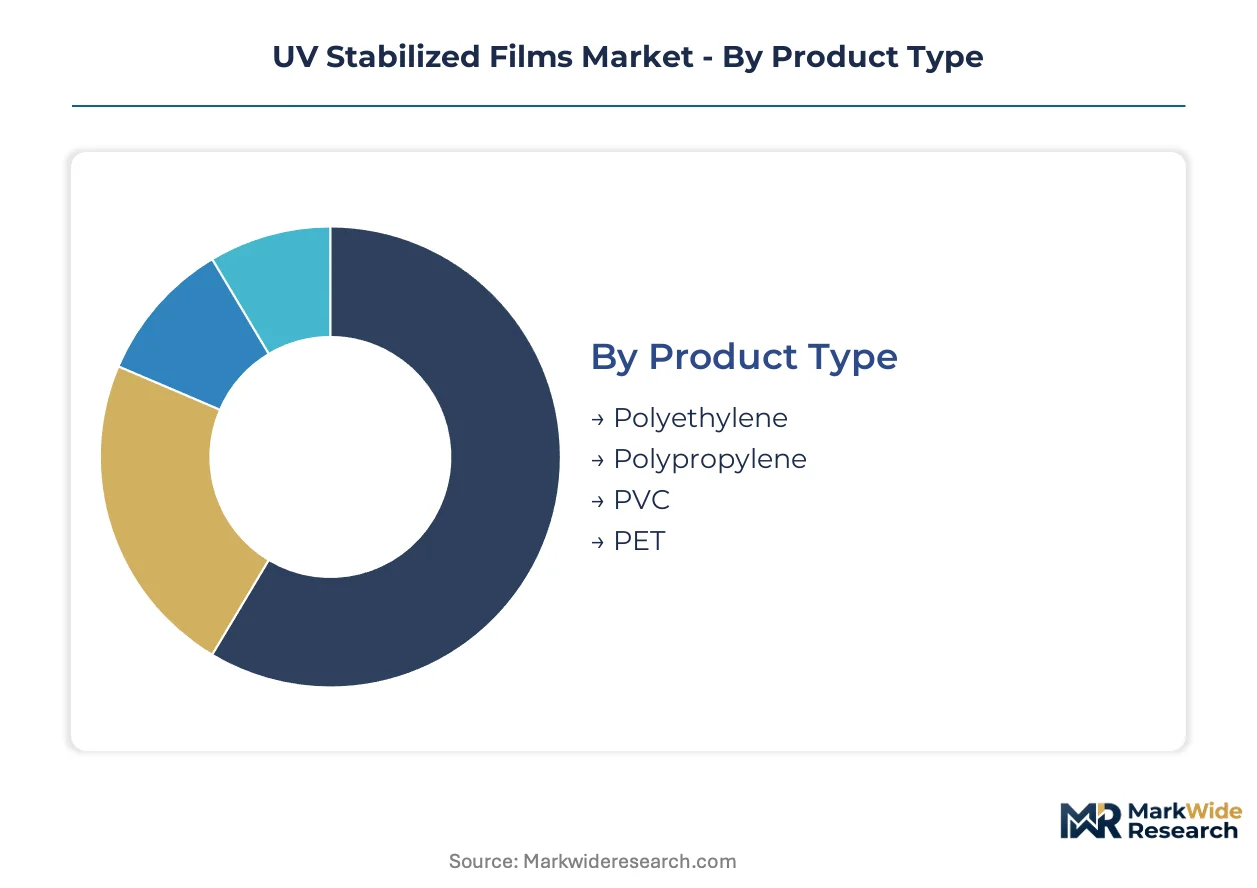
Segmentation in UV stabilized films reveals how additive loading, polymer selection, and thickness specifications map to divergent margin structures across agricultural, architectural, and industrial end-uses. Understanding these divides helps suppliers allocate formulation R&D and extrusion capacity toward the most defensible revenue pools.
Product Type:
Margin concentration sits with specialty grades where stabilization chemistry and polymer purity command specification premiums from regulated applications.
- Polyethylene:Linear low-density formulations carry hindered amine loadings of 0.1-0.5% for agricultural mulch and tunnel covers. China's Shandong province drives volume procurement as domestic greenhouse modernization accelerates replacement cycles.
- PET:Biaxially oriented grades with benzotriazole absorbers at 1.0-2.0% serve photovoltaic backsheet and architectural glazing laminates. Building-integrated photovoltaics in Germany and Japan specify 25-year weathering guarantees that absorb premium-grade volumes.
- Polypropylene:Cast and blown variants stabilize woven sacks and industrial packaging against warehouse UV exposure.
- PVC:Rigid and flexible formulations incorporate tin or calcium-zinc heat stabilizers alongside UV packages for construction membranes.
The dominant share belongs to Polyethylene, while PET is closing the gap fastest.
Application:
Cost tier stratification separates commodity agricultural covers from certified architectural membranes with validated additive migration profiles.
- Agricultural Films:Greenhouse covers, mulch films, and silage wraps incorporate HALS at loadings calibrated to 3-5 year service life. Almería's greenhouse cluster in Spain concentrates procurement through integrated buying groups controlling multi-hectare coverage requirements.
- Building & Construction:Architectural membranes above 300 microns and photovoltaic laminates demand extended UV resistance with REACH-compliant additive packages. Germany's BIPV retrofit mandates pull certified film volumes ahead of standard construction cycles.
- Packaging:Food-contact and industrial wrap applications prioritize optical clarity with minimal stabilizer migration.
- Automotive:Interior trim films and paint protection layers require color stability under dashboard and exterior exposure conditions.
Agricultural Films retain volume leadership, though Building & Construction exhibits the steepest expansion trajectory.
End User:
Customer type determines specification authority and contract structure, with direct manufacturer relationships displacing distributor-mediated purchasing.
- Manufacturers:Film extruders and converters source stabilized resin or masterbatch for in-house coextrusion. Berry Global's North American blown film infrastructure exemplifies captive formulation for controlled-environment agriculture customers.
- Distributors:Regional stocking intermediaries serve fragmented greenhouse operators and construction contractors with standard grades.
- Retailers:Home improvement and agricultural supply chains carry consumer-scale mulch and construction film SKUs.
- Consumers:Smallholder growers and DIY builders purchase finished films without technical specification input.
Manufacturers command the largest procurement volume, while Distributors face margin compression from direct channel expansion.
Thickness:
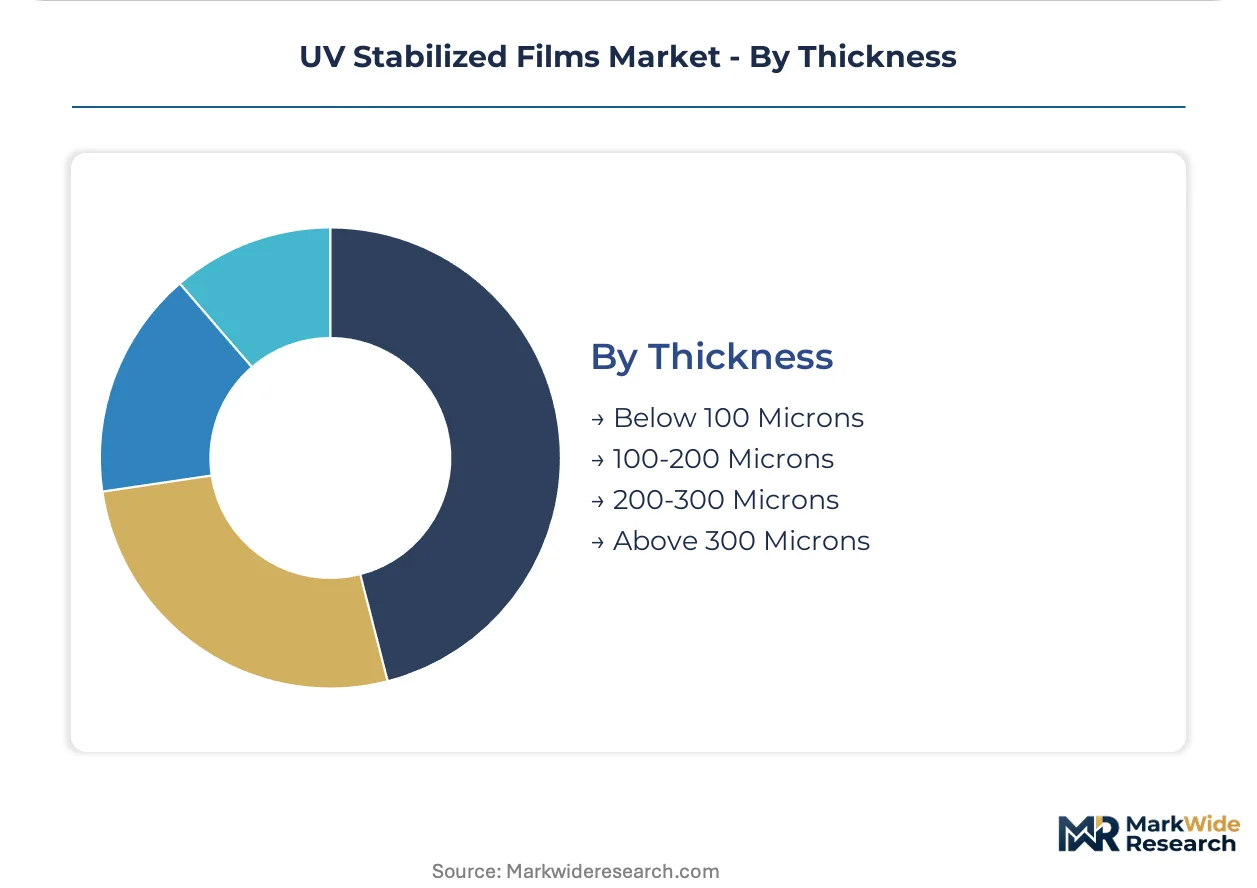
Volume flows concentrate in mid-range bands where agricultural greenhouse demand intersects with extrusion economics, while ultra-thick specifications serve emerging premium niches.
- 100-200 Microns:Standard greenhouse cover and agricultural tunnel specifications balance durability against material cost. Netherlands operators specify nano-dispersed HALS grades in this band for extended 5-year replacement cycles.
- Above 300 Microns:Architectural membranes and BIPV laminates require structural integrity with 25-year weathering performance. Japan's building codes mandate these thickness minimums for integrated photovoltaic installations.
- Below 100 Microns:Single-season mulch films and temporary protective sheeting prioritize cost minimization over longevity.
- 200-300 Microns:Intermediate grades serve industrial packaging and medium-duty construction applications.
The 100-200 Microns band anchors volume share, while Above 300 Microns gains share fastest on BIPV penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's polymer logistics infrastructure underwrites Europe's import dominance for UV-stabilized film feedstocks, while China's Qingdao port cluster serves Shandong province's extrusion belt with direct HALS raw material flows.
United States
California's Central Valley greenhouse operators are accelerating replacement cycles for UV-stabilized covers as drought-driven heat stress intensifies. EPA soil-contact migration thresholds for agricultural films are tightening additive validation requirements. Berry Global's blown film infrastructure in North Carolina serves controlled-environment agriculture customers with customized stabilization packages.
China
Shandong province's polymer film manufacturing clusters absorb both domestic agricultural modernization demand and export orders for Southeast Asian greenhouse markets. MEE enforcement actions on plastic film recycling are reshaping formulation requirements and import acceptance protocols. Qingdao's port facilities enable direct HALS raw material delivery from BASF's Asian supply points.
Germany
Building-integrated photovoltaic mandates in Bavaria and Baden-Württemberg are pulling certified PET laminate volumes with 25-year weathering guarantees. REACH benzophenone restrictions are forcing immediate reformulation of soil-contact agricultural grades. The Rhine-Ruhr industrial corridor hosts specialty chemical operations supplying triazine-class UV absorber alternatives.
Spain
Almería's greenhouse cluster concentrates procurement through three integrated buying groups controlling 40% of regional cover film volume. ECHA's 2023 restriction proposal on benzophenone-3 derivatives is accelerating trials of alternative absorber chemistries among Italian and Polish mulch film producers. Valencia's port infrastructure serves North African export markets for Mediterranean agricultural film specifications.
Saudi Arabia
NEOM and Red Sea Project developments are specifying high-load UV stabilization for desert greenhouse complexes with 50°C ambient operating conditions. SFDA compliance requirements for food-contact agricultural films are tightening migration testing protocols. Jeddah's industrial zone is attracting film extrusion investments to serve Gulf Cooperation Council controlled-environment agriculture expansion.
UV Stabilized Films Market Competitive Landscape
Listed leaders compete with private specialists across formulation expertise and geographic coverage, creating a tiered structure where scale-driven commodity producers coexist with application-specific solution providers. The vendor base segments into three strategic archetypes: integrated polymer conglomerates with captive film extrusion, regional specialists serving climate-specific agricultural belts, and additive-technology licensors controlling HALS intellectual property. Dominant competitive moves include backward integration into HALS masterbatch production and strategic partnerships with greenhouse operator buying groups to secure multi-hectare supply agreements.
Among Israel-based agricultural film specialists, Ginegar anchors Middle Eastern and Mediterranean markets where solar irradiance levels demand specialized additive loading configurations. Berry Global exemplifies the North American integrated conglomerate archetype, leveraging blown film infrastructure to serve controlled-environment agriculture customers with customized stabilization packages. Polifilm occupies a position within the European retrofit specialist tier, competing on greenhouse replacement cycles with extended service-life guarantees for certified REACH-compliant grades.
| Leading Market Players |
|---|
| Plastika Kritis |
| Armando Alvarez Group |
| Berry Global |
| Rani Group |
| Polifilm |
| Coveris |
| Ginegar |
| Novolex |
| RKW Group |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day HALS masterbatch lead times concentrate pricing power with BASF and Clariant, forcing mid-tier extruders in Turkey and Mexico to absorb inventory carrying costs or cede margin on rush orders. This supply-side tightness amplifies volume-tier premiums, as integrated agribusiness chains leverage multi-hectare commitments to extract price concessions unavailable to fragmented greenhouse cooperatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and volume scale. Premium tiers command substantial markups for REACH-validated additive packages with documented migration profiles, while economy tiers compete on raw material cost for undifferentiated agricultural mulch. Pricing pressure stems from dual-validation expenditures for cross-border market access, squeezing margins on standard polyethylene grades. Smallholder cooperatives exhibit acute price sensitivity, whereas integrated controlled-environment agriculture operators prioritize service-life guarantees over unit cost.
Supply Chain Analysis
Strategic stockpiling of hindered amine light stabilizers dominates inventory strategy, as film extruders buffer against BASF and Clariant supply allocation decisions. Manufacturing concentrates in China, Germany, and the United States, with Shandong province's extrusion belt absorbing domestic agricultural demand and Southeast Asian export orders. Raw material dependencies center on ethylene feedstocks, HALS masterbatch, and benzotriazole absorbers. Single-source vulnerability in specialty additive supply creates structural risk for mid-tier converters. Distribution runs through regional stocking intermediaries serving fragmented greenhouse operators, though direct manufacturer relationships are displacing this channel for large agribusiness accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation expertise in photostabilizer synergy optimization has become the constraining asset, as retiring chemists at European additive houses leave capability gaps that new entrants struggle to replicate. This scarcity dynamic rewards early movers who secure technical talent or proprietary compounding know-how.
For Market Incumbents: Shield margin position through backward integration into HALS masterbatch production, capturing additive cost structures currently controlled by BASF and Clariant. Prioritize certification investment for REACH-compliant soil-contact grades before ECHA restriction deadlines eliminate competing benzophenone formulations. Channel control through direct supply agreements with Almería's consolidated buying groups defends volume share against distributor-mediated competitors. For New Entrants and Emerging Players: Technical service gaps in formulation customization for desert greenhouse conditions present immediate white-space opportunity, as NEOM and Red Sea Project developers seek localized UV stabilization expertise for 50°C operating environments. India's PLI-enabled HALS production incentives offer the most penetrable manufacturing entry point for Southeast Asian export targeting. A go-to-market angle anchored in nano-dispersed systems for extended 5-year replacement cycles differentiates against commodity 3-year grades. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because formulation IP and regulatory validation timelines create durable moats around incumbent positions. Acquisition targets should exhibit captive HALS sourcing relationships or certified additive packages with validated migration profiles across multiple jurisdictions. The signal to watch is ECHA restriction implementation pace, as accelerated benzophenone phase-outs would force distressed asset opportunities among unprepared European converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HALS Production | Captures additive margin pools currently extracted by BASF and Clariant supply allocation. |
| REACH Certification Investment | Validates alternative benzotriazole chemistries before ECHA soil-contact restrictions take effect. |
| Direct Supply Agreement with Buying Groups | Secures multi-hectare volume commitments from Almería's consolidated greenhouse operators. |
| Nano-Dispersed Stabilizer Development | Extends service-life guarantees to 5-year cycles for Netherlands and Japan premium segments. |
| Desert Climate Formulation Center | Localizes technical service for Saudi Arabia's NEOM greenhouse complexes with extreme UV loading requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with polymer film extruders, agricultural greenhouse procurement managers, additive house formulation chemists, and regulatory affairs specialists at REACH compliance consultancies. Secondary validation drew from ECHA restriction proposals, EPA soil-contact migration guidelines, China's GB standards and MEE enforcement records, customs trade data for HALS raw material flows, and SEC filings from listed film manufacturers. Bottom-up volume modeling triangulated against top-down market sizing across polymer grade, thickness specification, and end-use application dimensions.
Across the analysis window, projections integrate segment-level demand drivers with capacity expansion announcements and regulatory implementation schedules. Segmentation dimensions modeled include polymer substrate type, additive loading tier, thickness specification, end-use application, and geographic production cluster. CAGRs were derived from regression analysis of historical replacement cycle data against climate volatility indices and regulatory mandate timelines. Industry-specific forecast inputs encompass greenhouse modernization rates in Shandong province and building-integrated photovoltaic installation permits in Germany and Japan.
Material uncertainties — ECHA restriction finalization timing, HALS raw material allocation decisions by dominant suppliers, and MEE enforcement intensity on plastic film recycling — sit outside the modeled envelope. Forecasts reflect assumptions about additive validation queue durations and cross-border formulation portability that may shift with regulatory divergence. Revision becomes warranted when benzophenone alternative approval timelines extend beyond current ECHA validation backlogs or when China's MEE actions disrupt Shandong export flows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Conductive Fluted Sheets Market
Specialty Materials
Barium Fluoride Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
India Collagen Market
Specialty Materials
Plastic Dielectric Films Market
Specialty Materials
Carrageenan Film Market
Specialty Materials
Engineered Quartz Surface Market
Specialty Materials
Silicone Gel Market
Specialty Materials
MLCC Silicone Release Film Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
Nitrocellulose Market
Specialty Materials
Asia-Pacific Colloidal Silica Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Marine Mineral Complexes from Mediterranean Shells Market