
 Mesoporous Silica Market | 2026-2036
Mesoporous Silica Market Size, Share, and Industry Trends Forecast 2026-2036
Mesoporous Silica Market Intelligence
Pharmaceutical-grade pore-size precision is redrawing competitive boundaries in mesoporous silica supply. Merck KGaA leverages its life-sciences distribution network to sustain premium positioning across European drug formulation labs. Evonik Industries AG specializes in surface-functionalized variants that command tighter specifications for biotech customers.
Mesoporous silica denotes porous silicon dioxide structures with ordered pore channels ranging from 2 to 50 nanometers, typically synthesized via sol-gel or soft-templating routes using surfactant micelles as structure-directing agents. These materials serve primarily as high-surface-area platforms for catalytic supports, controlled drug release matrices, and selective adsorption media. Silica spheres dominate current volume owing to established manufacturing scalability and reproducible batch uniformity, while drug delivery applications within the application dimension are expanding fastest as pharmaceutical formulators seek tunable release kinetics. The end-user split reveals biotechnology as the emerging margin pool, though the chemical industry still anchors baseline demand for standard-grade catalytic supports.
REACH registration requirements in Europe and FDA nanotechnology guidance in the United States impose escalating purity and characterization documentation burdens on importers and manufacturers. ISO 10993 biocompatibility standards further gate access to pharmaceutical and biotechnology end users, particularly for materials destined for implantable or injectable drug carriers. Stakeholders must monitor evolving regulatory convergence between EMA and FDA on nanomaterial characterization protocols, as harmonized testing requirements could reshape supplier qualification costs and competitive barriers.
Market Dynamics
Pharmaceutical-grade purity requirements are compressing supplier margins while concentrating procurement among certified manufacturers capable of ISO 10993 documentation and FDA nanotechnology guidance compliance.
Growth Catalysts
- Controlled-release drug formulations:Pharmaceutical formulators are adopting mesoporous silica matrices for tunable release kinetics in oral and injectable therapeutics, creating sustained demand for surface-functionalized variants.
- REACH registration mandates:European chemical registration requirements are disqualifying uncertified importers and consolidating supply among compliant domestic producers with established ECHA dossiers.
- Germany's chemical manufacturing clusters:Proximity to Merck KGaA and Boehringer Ingelheim headquarters in the Rhine-Main and Upper Bavaria regions sustains above-average procurement intensity for high-grade material.
Market Restraints
- Tetraethyl orthosilicate price volatility:Sol-gel synthesis feedstock costs fluctuate with semiconductor-grade silicon demand, squeezing batch economics for small-scale producers.
- Supplier concentration in Central Europe:Three specialized chemical manufacturers control the majority of pharmaceutical-grade capacity, creating single-source risk for North American formulators.
- Batch-to-batch reproducibility limits:Soft-templating synthesis yields pore-size distributions that deviate from tight pharmaceutical specifications, requiring costly reprocessing or discard.
Strategic Opportunities
- India's CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are building formulation capabilities that will import certified mesoporous silica for export-oriented generic drug production.
- Bioconjugation surface chemistry:Covalent attachment of antibodies and peptides to silica pore walls is opening oncology and immunology applications previously served by lipid nanoparticles.
- EU Green Deal solvent restrictions:Regulatory pressure to eliminate chlorinated solvents in surfactant-templated synthesis is rewarding producers with aqueous-phase process patents.
Industry Challenges
- ISO 10993 biocompatibility certification timelines:Cytotoxicity and sensitization testing for implantable drug carriers extends qualification cycles by 18-24 months, freezing supplier switching decisions.
- Cross-functional talent scarcity:Formulation scientists with simultaneous expertise in sol-gel chemistry, surface functionalization, and regulatory documentation command premium compensation and constrain R&D scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mesoporous Silica Market |
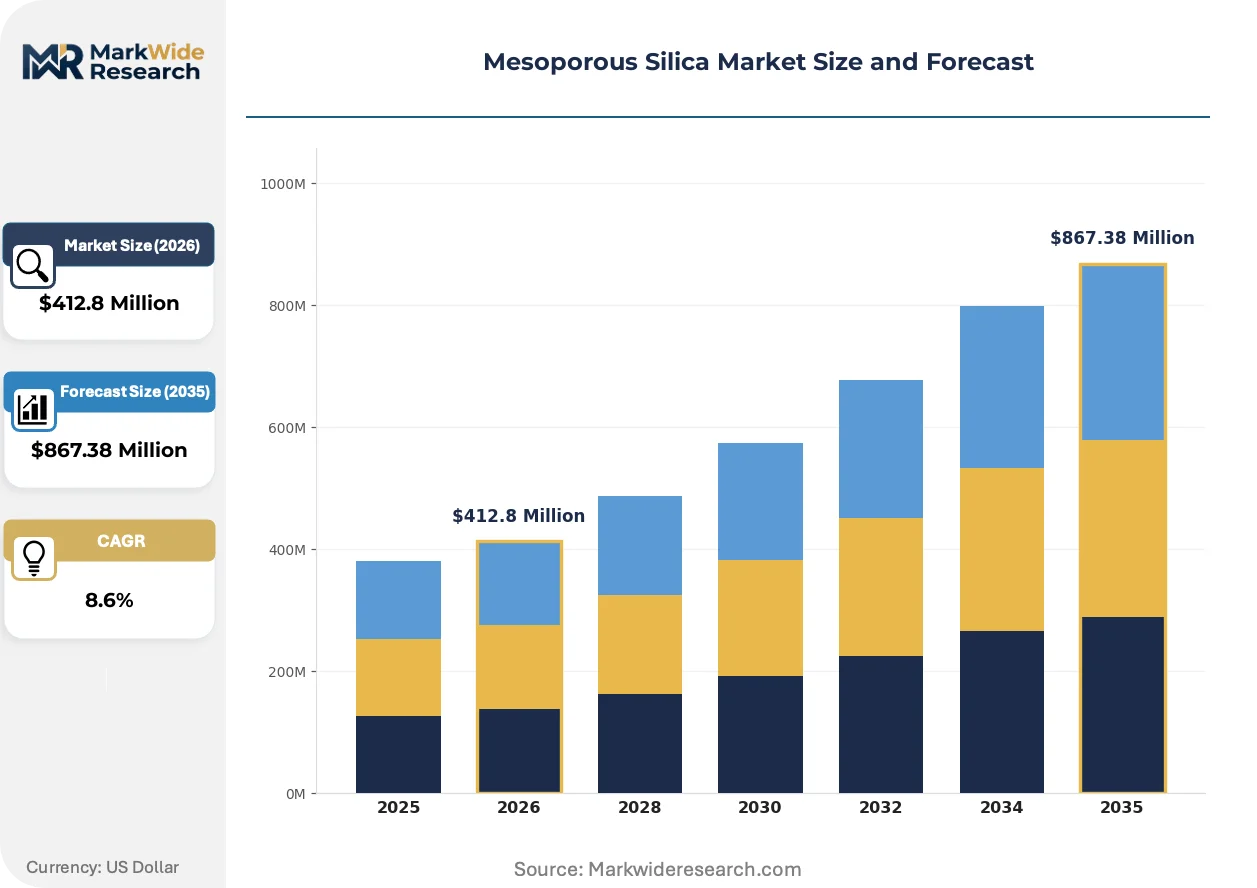
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $867.38 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica Spheres, Silica Rods, Silica Tubes, Silica Granules Application: Catalysis, Drug Delivery, Adsorption, Sensors End User: Pharmaceuticals, Biotechnology, Chemical Industry, Academia Size: Small Scale, Medium Scale, Large Scale, Bulk |
| Companies Covered | W.R. Grace & Co., PQ Corporation, Merck KGaA, Cabot Corporation, Mitsubishi Chemical Corporation, BASF SE, Fuji Silysia Chemical Ltd., Solvay S.A., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mesoporous Silica Market Strategic Shifts & Innovations
Manufacturing process intensification and regulatory documentation automation are compressing development cycles while elevating the technical bar for market participation. Three developments are reshaping competitive positioning.
Continuous-flow sol-gel synthesis is supplanting batch reactor production in high-volume applications. Catalysis and industrial adsorption buyers in the US Gulf Coast chemical corridor are adopting this technology for its tighter pore-size distribution control and reduced solvent waste. The shift is enabling toll manufacturers to capture share from established European suppliers by offering faster turnaround on custom specifications.
FDA's evolving nanotechnology guidance for drug products is mandating enhanced characterization of particle size distribution, surface area, and porosity for all materials below 100 nanometers. This documentation burden is filtering out commodity silica traders and consolidating procurement relationships with analytical-capable manufacturers. Biotechnology end-users in Massachusetts and California are now requiring quarterly stability data packages that exceed current ICH guidelines.
Formulation houses are consolidating supplier bases from multi-source to dual-source or single-source arrangements for critical excipients. This concentration reflects risk-management responses to pandemic-era supply disruptions and is compressing the vendor landscape. The pattern is most visible among mid-cap pharmaceutical companies in the Research Triangle and New Jersey corridor, where procurement teams now prioritize geographic proximity and redundant manufacturing sites over price competition.
Mesoporous Silica Market Segmentation
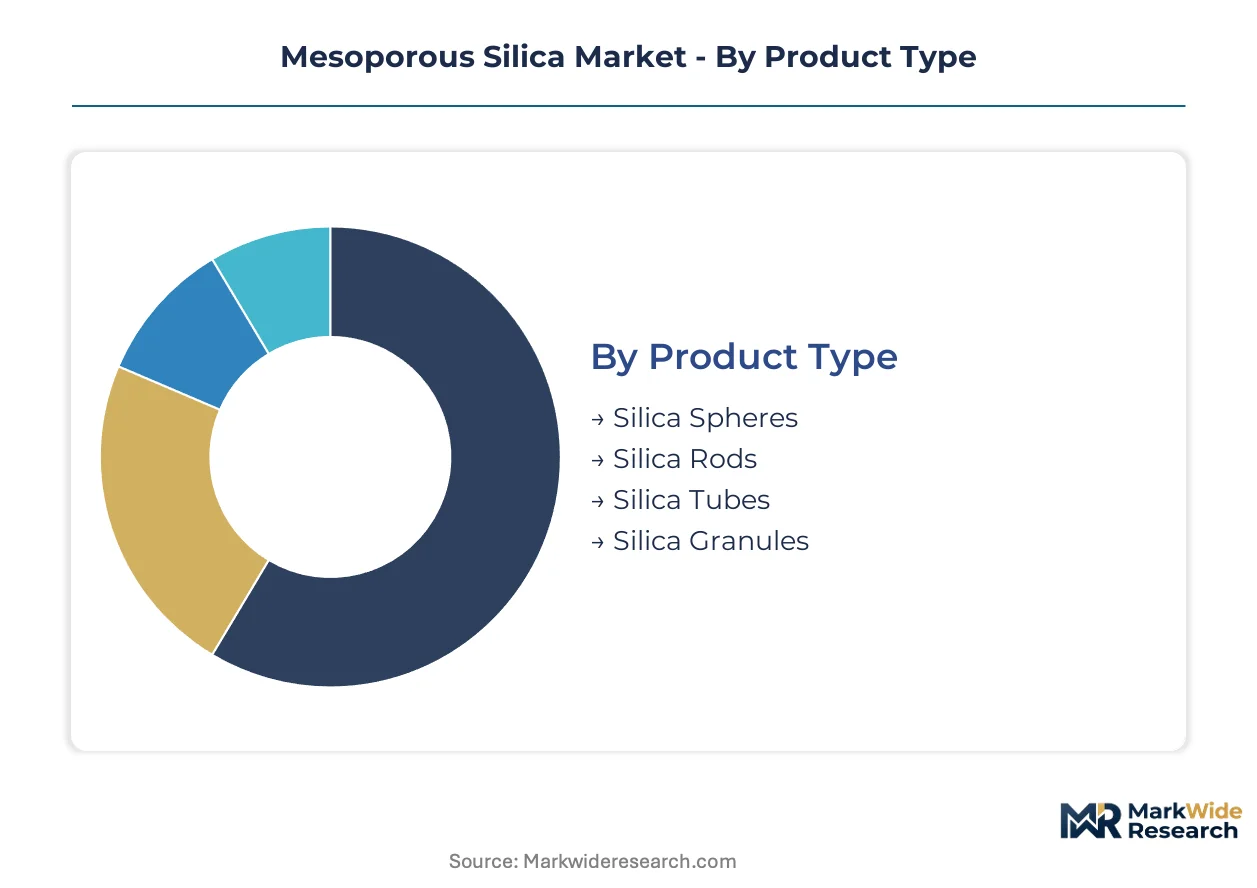
Mesoporous silica procurement splits across four dimensions that determine pricing power and technical qualification requirements. Product geometry dictates manufacturing scalability, while end-user certification standards gate access to premium margin pools.
Product Type:
Silica spheres command the widest margin expansion potential due to pharmaceutical formulation standardization and established analytical protocols for batch release.
- Silica Spheres:Monodisperse spherical morphology enables reproducible packing densities in chromatography columns and controlled-release matrices. German pharmaceutical formulators in the Rhine-Main corridor specify sub-5% coefficient of variation in particle diameter, tightening supplier qualification thresholds.
- Silica Rods:Anisotropic pore channels oriented along the long axis accelerate mass transport in catalytic applications. US Gulf Coast petrochemical operators are adopting rod-shaped supports for hydroprocessing units where diffusion limitations constrain spherical alternatives.
- Silica Tubes:Hollow cylindrical structures with radial pore connectivity serve encapsulation applications in agrochemical delivery systems.
- Silica Granules:Irregular fragmented morphology produced by mechanical milling offers cost-positioned options for industrial adsorption and desiccant applications.
Silica spheres hold installed capacity. Silica rods are rotating up the share rankings.
Application:
Drug delivery applications concentrate the steepest value-per-kilogram realization, though catalysis anchors absolute volume throughput.
- Drug Delivery:Mesoporous matrices enable zero-order release kinetics for poorly soluble APIs through tunable pore confinement. FDA nanotechnology guidance mandates enhanced characterization for injectable carriers, filtering out commodity suppliers lacking particle tracking analysis capability.
- Catalysis:High-surface-area supports distribute active metals for fine chemical and petrochemical transformations. BASF and Evonik operate dedicated production lines for heterogeneous catalyst precursors serving European automotive emissions control and specialty chemical markets.
- Adsorption:Selective capture of VOCs, CO2, and water vapor exploits ordered pore size distributions for molecular sieving.
- Sensors:Optical and electrochemical transduction platforms leverage refractive index changes upon analyte binding to functionalized pore surfaces.
Catalysis holds installed capacity. Drug delivery is rotating up the share rankings.
End User:
Biotechnology customers extract maximum value through surface-functionalized variants, while chemical industry procurement prioritizes throughput economics over specification tightness.
- Pharmaceuticals:Oral and parenteral formulation houses require ISO 10993 biocompatibility documentation and stability data packages exceeding ICH guidelines. New Jersey and Massachusetts procurement teams now mandate quarterly requalification for critical excipients.
- Biotechnology:Cell therapy and bioconjugation applications demand covalent attachment chemistries for antibodies and peptides. Surface silanol density and derivatization protocols differentiate qualified suppliers from commodity traders.
- Chemical Industry:Catalysis and process chemistry buyers prioritize batch-to-batch reproducibility and toll manufacturing flexibility over premium pricing.
- Academia:Research-scale procurement drives innovation in synthesis methodologies but contributes limited commercial volume.
Chemical industry holds installed capacity. Biotechnology is rotating up the share rankings.
Size:
Large-scale production configurations amortize regulatory documentation costs across greater output, compressing per-kilogram qualification overhead.
- Small Scale:Gram-to-kilogram quantities serve method development and preclinical formulation screening. Hyderabad CDMOs are building captive small-scale synthesis capabilities to reduce import dependency for early-stage programs.
- Medium Scale:Kilogram-to-hundred-kilogram batches bridge clinical trial material supply and commercial launch preparation.
- Large Scale:Multi-tonne campaigns for approved drug products require validated manufacturing processes and dedicated production suites. FDA inspection history and EMA GMP certification become non-negotiable selection criteria.
- Bulk:Industrial adsorption and catalysis applications purchase uncharacterized or loosely specified material on spot contracts.
Bulk holds installed capacity. Large scale is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Indian formulators scrutinize per-kilogram landed costs for clinical trial materials, while German pharmaceutical houses prioritize batch documentation over unit economics. This divergence shapes supplier qualification protocols and regional procurement patterns.
Germany
Rhine-Main and Upper Bavaria clusters sustain Europe's densest concentration of pharmaceutical-grade mesoporous silica consumption. REACH registration dossiers filed with ECHA now mandate enhanced nanomaterial characterization data, extending compliance timelines for non-domestic suppliers. Ludwigshafen and Darmstadt host integrated chemical manufacturing complexes where captive production of surface-functionalized variants serves Boehringer Ingelheim and Merck formulation programs.
United States
FDA nanotechnology guidance for drug products drives quarterly stability data requirements that exceed ICH baseline standards. Massachusetts and New Jersey procurement teams now mandate redundant manufacturing sites for critical excipients. The Research Triangle and Greater Boston biotechnology corridors concentrate demand for ISO 10993-certified material destined for injectable drug carriers.
China
NMPA alignment with ICH Q3D elemental impurity guidelines is elevating purity benchmarks for imported silica used in domestic generic drug production. Yangtze River Delta CDMOs in Suzhou and Shanghai are building formulation capabilities that will absorb certified mesoporous silica for export-oriented oncology programs. Zhejiang and Jiangsu provinces host toll manufacturers scaling aqueous-phase synthesis to meet EU Green Deal solvent restrictions.
India
Hyderabad and Ahmedabad contract development organizations are expanding formulation capabilities for US and EU generic drug markets. CDSCO import licensing requirements for nanomaterial-based excipients are tightening documentation burdens on uncertified traders. Gujarat's specialty chemical belt is attracting investment in small-scale synthesis capabilities to reduce import dependency for early-stage pharmaceutical programs.
Japan
PMDA consultation procedures for nanomaterial-containing drug products are extending pre-approval timelines for foreign silica suppliers. Osaka and Tokyo metropolitan areas concentrate biotech demand for surface-derivatized variants supporting antibody-drug conjugate programs. METI funding for continuous-flow manufacturing is accelerating adoption of process-intensified sol-gel synthesis among domestic chemical producers.
Mesoporous Silica Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the mesoporous silica supply base. Pharmaceutical-grade purity requirements have compressed the vendor landscape toward analytical-capable manufacturers with established regulatory dossiers. Three strategic archetypes dominate: diversified chemical conglomerates with captive life-sciences divisions, specialized silica producers with toll manufacturing flexibility, and regional chemical manufacturers scaling aqueous-phase process patents. Competitive dynamics center on M&A consolidation of analytical capabilities and geographic expansion through qualified toll manufacturing partnerships.
Among European chemical conglomerates, Merck KGaA, BASF SE, and Evonik Industries AG occupy positions defined by regulatory documentation depth and life-sciences distribution reach. Merck KGaA exemplifies the integrated archetype combining material production with pharmaceutical channel access. BASF SE represents scale-driven supply security for industrial catalysis applications. Evonik Industries AG sits within the surface-functionalization specialist tier where bioconjugation chemistry capabilities differentiate positioning. These three anchors collectively shape certification standards and procurement qualification protocols across European and North American pharmaceutical markets.
| Leading Market Players |
|---|
| W.R. Grace & Co. |
| PQ Corporation |
| Merck KGaA |
| Cabot Corporation |
| Mitsubishi Chemical Corporation |
| BASF SE |
| Fuji Silysia Chemical Ltd. |
| Solvay S.A. |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
ISO 10993 biocompatibility certification gates both supplier qualification and price stratification simultaneously, bifurcating the mesoporous silica market between analytical-capable manufacturers commanding documentation premiums and commodity traders competing on spot pricing alone. REACH registration dossiers and FDA nanotechnology guidance impose fixed compliance costs that compress margins at small scale while rewarding large-batch producers with amortized per-kilogram overhead.
Pricing Analysis
After-sales technical service and regulatory documentation packages drive lifetime value for pharmaceutical-grade mesoporous silica suppliers. Three-tier pricing structure across pharmaceutical-certified, industrial-grade, and bulk uncharacterized material reflects certification depth and characterization burden. Price differentiation rests on ISO 10993 documentation completeness and quarterly stability data provision. Cost compression in industrial-grade tiers is intensifying because toll manufacturers on the US Gulf Coast are capturing share through continuous-flow process economics. Biotechnology end-users in Massachusetts exhibit lowest price sensitivity, while Indian CDMOs scrutinize landed costs for clinical trial materials.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes and Rotterdam port congestion periodically extend lead times for tetraethyl orthosilicate feedstock deliveries. Supply concentrates in Germany, the United States, and China, with German manufacturers anchoring pharmaceutical-grade capacity. Raw material dependencies draw from semiconductor-grade silicon sources, surfactant templating agents, and chlorinated solvents facing EU Green Deal restrictions. Single-source vulnerability pervades North American formulator procurement given Central European supplier dominance. Distribution runs through life-sciences distributors for pharmaceutical channels and direct mill relationships for industrial adsorption buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades the mesoporous silica market as bioconjugation surface chemistry applications proliferate faster than incumbent capacity expansion, creating specialized niches for analytical-capable entrants.
For Market Incumbents: Shield formulation relationships by embedding regulatory documentation teams within customer quality departments, preempting supplier switching during ISO 10993 requalification cycles. Accelerate aqueous-phase synthesis patent deployment to neutralize EU Green Deal solvent restrictions as a competitive wedge. Capacity addition in US Gulf Coast toll manufacturing addresses single-source risk concerns among North American biotechnology customers. For New Entrants and Emerging Players: Anchor in Hyderabad and Ahmedabad CDMO corridors where import dependency for early-stage pharmaceutical programs creates immediate addressable demand. Surface-functionalized variants for bioconjugation applications represent the most penetrable segment given antibody-drug conjugate program expansion. Pursue qualified toll manufacturing partnerships with established analytical laboratories to bypass 18-24 month certification timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core life-sciences material divisions. Long-term viability frames around regulatory documentation depth as the primary moat, with analytical capability scarcity intensifying across the projection horizon. Watch FDA-EMA convergence on nanomaterial characterization protocols as the inflection signal for supplier qualification cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tetraethyl Orthosilicate | Captive feedstock supply insulates Evonik and Merck KGaA from semiconductor-grade silicon demand volatility. |
| Aqueous-Phase Synthesis Patent Portfolio | EU Green Deal solvent restrictions reward Zhejiang toll manufacturers with process-intensified production capabilities. |
| Regulatory Documentation Automation | FDA nanotechnology guidance compliance compresses batch release cycles for Massachusetts biotechnology formulators. |
| Continuous-Flow Manufacturing Scale-Up | US Gulf Coast chemical corridor adoption tightens pore-size distribution control for catalysis applications. |
| Bioconjugation Surface Chemistry R&D | Oncology and immunology program demand opens margin pools previously served by lipid nanoparticle competitors. |
Research Approach
Cross-validation between primary interviews with formulation scientists, regulatory affairs directors, and chemical procurement leads and secondary validation through ECHA registration databases, FDA nanotechnology guidance documents, and SEC 10-K filings anchors the qualitative findings. Bottom-up triangulation against top-down trade flow analysis from customs data and Cefic industry reports ensures segmentation integrity. The research synthesizes supply-side plant capacity disclosures with demand-side therapeutic pipeline tracking across oral and injectable controlled-release programs.
Sensitivity analysis on feedstock cost assumptions and regulatory timeline scenarios frames the analytical approach across the projection horizon. Segmentation dimensions modeled include product geometry, application category, end-user certification tier, and production scale configuration. CAGRs derive from elasticity-adjusted volume projections incorporating REACH registration completion rates and CDMO expansion trajectories in India. Forecast inputs incorporate tetraethyl orthosilicate price volatility bands and FDA inspection frequency trends for active pharmaceutical ingredient excipient facilities.
Material uncertainties — tetraethyl orthosilicate supply disruptions, REACH-EMA-FDA regulatory divergence on nanomaterial protocols, and biotechnology customer consolidation to single-source arrangements — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification timeline standardization and continuous-flow process adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Silicone Solutions for Leather and Textile Market
Specialty Materials
Jesmonite Market
Specialty Materials
Nanoencapsulation Market
Specialty Materials
Electroactive Polymers (EAP) Market
Specialty Materials
Methyl Silicone Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market
Specialty Materials
Global Beeswax Market
Specialty Materials
Compostable Cotton Swab Market
Specialty Materials
North America Solar Control Window Films Market
Specialty Materials
Gutta-Percha Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Polyester Medical Films Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
Solar Control Films Market