
 Cellulose Derivative Excipient Market | 2026-2036
Cellulose Derivative Excipient Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulose Derivative Excipient Market Outlook
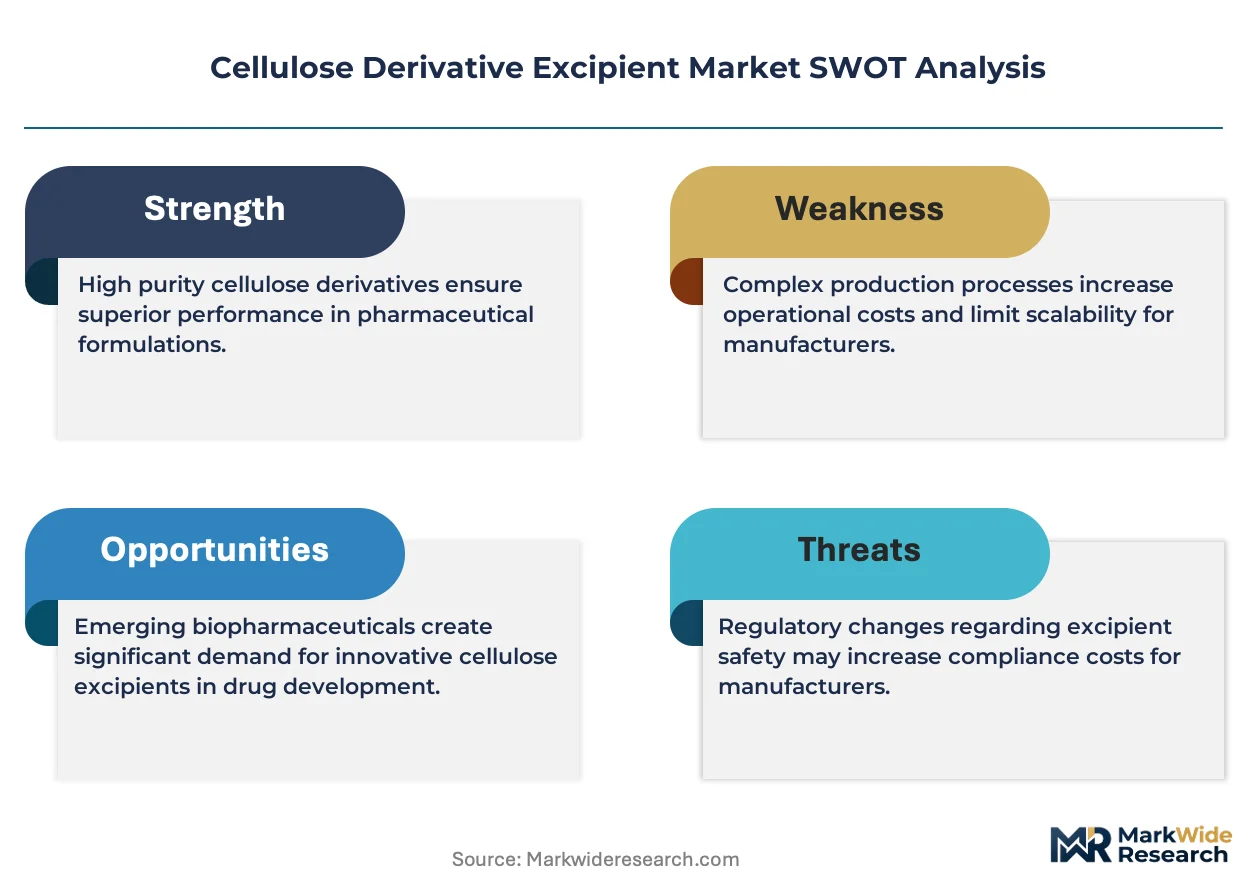
Hydroxypropyl methylcellulose is repositioning ethylcellulose in sustained-release matrix tablets due to superior hydration kinetics and broader pH stability. Ashland Global Holdings Inc leverages its vertical integration in cellulose ether production to control raw material quality from wood pulp through finished excipient. Dow Inc anchors North American supply through large-scale manufacturing infrastructure and long-standing pharmaceutical customer relationships. Daicel Corporation specializes in high-purity grades for Japanese and Asian pharmaceutical markets with exacting monograph standards.
Cellulose derivative excipients are modified polysaccharides derived from plant cellulose through etherification or esterification, with degrees of substitution typically ranging from 0.5 to 3.0 to control solubility, viscosity, and film-forming properties for pharmaceutical and food applications. Microcrystalline cellulose dominates tablet compression applications due to its established pharmacopeial status and direct compressibility, while hydroxypropyl methylcellulose leads growth in controlled-release and ophthalmic formulations where thermal gelation behavior commands premium positioning. Carboxymethylcellulose occupies mature volume pools in food thickening and oral care, with margin compression from commoditization offset by pharmaceutical-grade certifications in parenteral applications.
The US FDA enforces excipient cGMP compliance through IPEC-PQG guidelines, while the EMA's MDR framework tightens traceability requirements for materials contacting drug substances. India's CDSCO aligns with USP-NF and EP monographs through BIS certification pathways for domestically manufactured excipients. Manufacturers must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards, as divergence in heavy metal limits and substitution specifications creates formulation reformulation risks for multinational drug sponsors.
Market Dynamics
Pharmaceutical formulators are consolidating supply chains around IPEC-PQG certified excipients as FDA enforcement tightens, compressing vendor pools and elevating purity-grade premiums across oral solid dosage applications.
Growth Catalysts
- Controlled-release tablet expansion:Hydroxypropyl methylcellulose matrices are capturing sustained-release formulations from ethylcellulose due to superior hydration kinetics spanning gastric to intestinal pH environments.
- India's localization mandate:CDSCO alignment with USP-NF monographs through BIS certification pathways is accelerating domestic excipient manufacturing to serve pharmaceutical production scaling.
- Ophthalmic gelation demand:Thermal-reversible HPMC systems are commanding premium positioning in eye drop formulations where viscosity modulation at ocular surface temperature drives therapeutic efficacy.
Market Restraints
- Wood pulp supply volatility:Dissolving-grade cellulose feedstock concentration in Nordic and North American forestry operations creates input cost exposure for etherification processes.
- Substitution pressure from synthetic polymers:Polyvinylpyrrolidone and polymethacrylates are encroaching on film-coating applications where solvent processing flexibility outweighs natural-origin preferences.
- EMA MDR traceability burden:The Medical Device Regulation framework imposes documentation depth that smaller excipient manufacturers struggle to resource for European market access.
Strategic Opportunities
- Parenteral-grade CMC white space:Carboxymethylcellulose pharmaceutical certifications for injectable applications remain underdeveloped relative to oral-grade capacity, creating margin expansion potential.
- Continuous manufacturing compatibility:Direct-compressible microcrystalline cellulose grades engineered for hot-melt extrusion and twin-screw processing are aligning with FDA's quality-by-design initiatives.
- Japanese pharmacopeial convergence:PMDA's harmonization push between JP and USP heavy metal specifications is reducing reformulation burdens for multinational sponsors targeting dual filings.
Industry Challenges
- Substitution degree analytical capability gaps:Nuclear magnetic resonance spectroscopy expertise for verifying degrees of substitution between 0.5 and 3.0 remains scarce in quality control laboratories.
- Multinational pharmacopeial divergence:USP, EP, and JP specification misalignment on etherification endpoints forces sponsors to maintain parallel inventory grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulose Derivative Excipient Market |
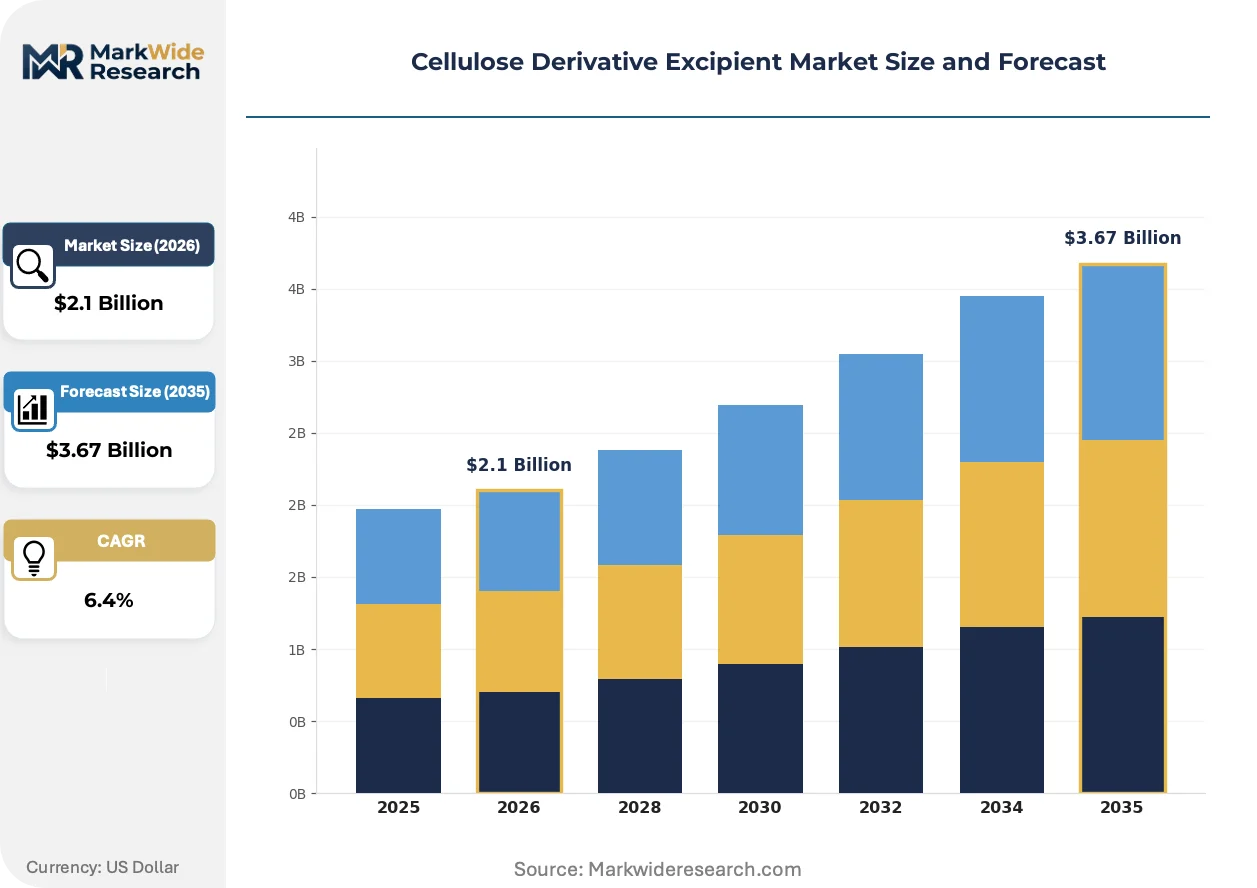
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
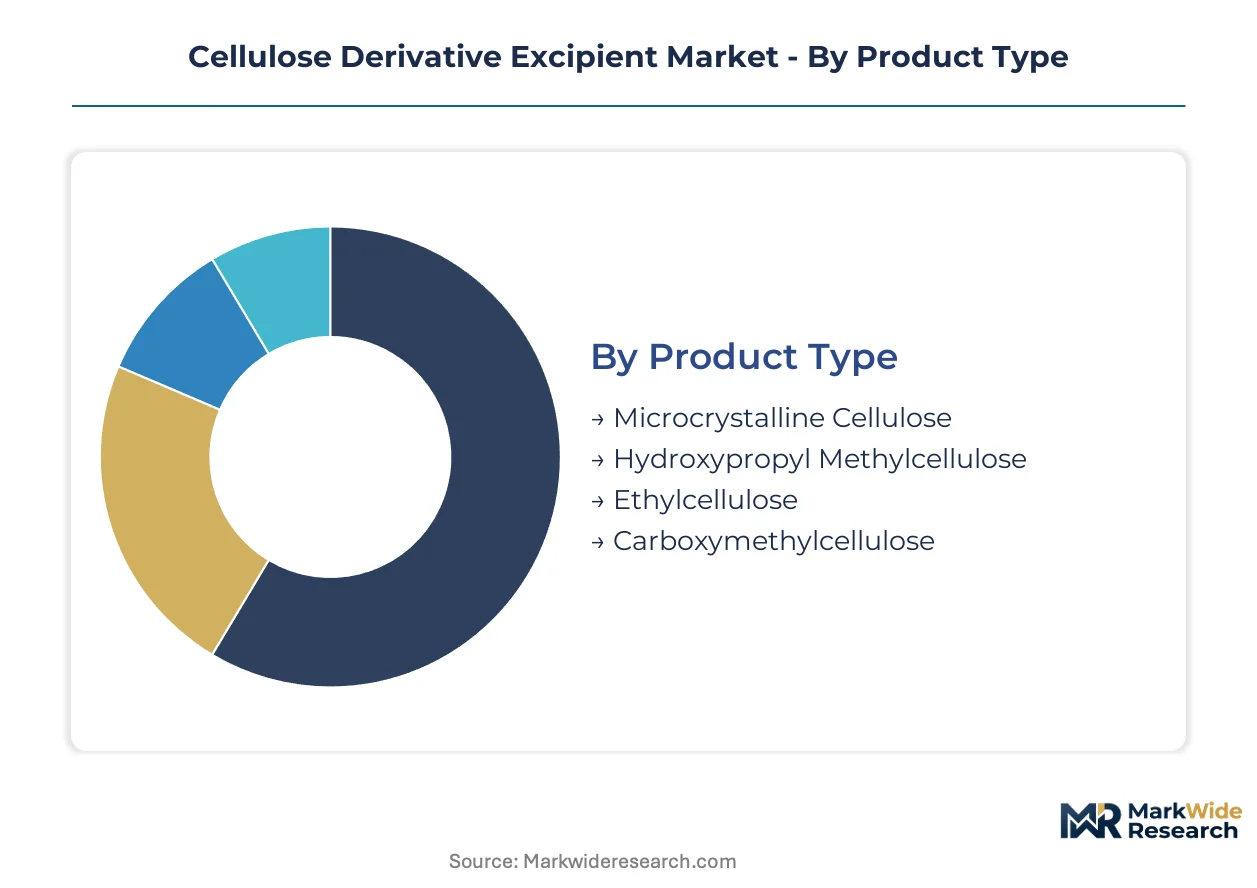
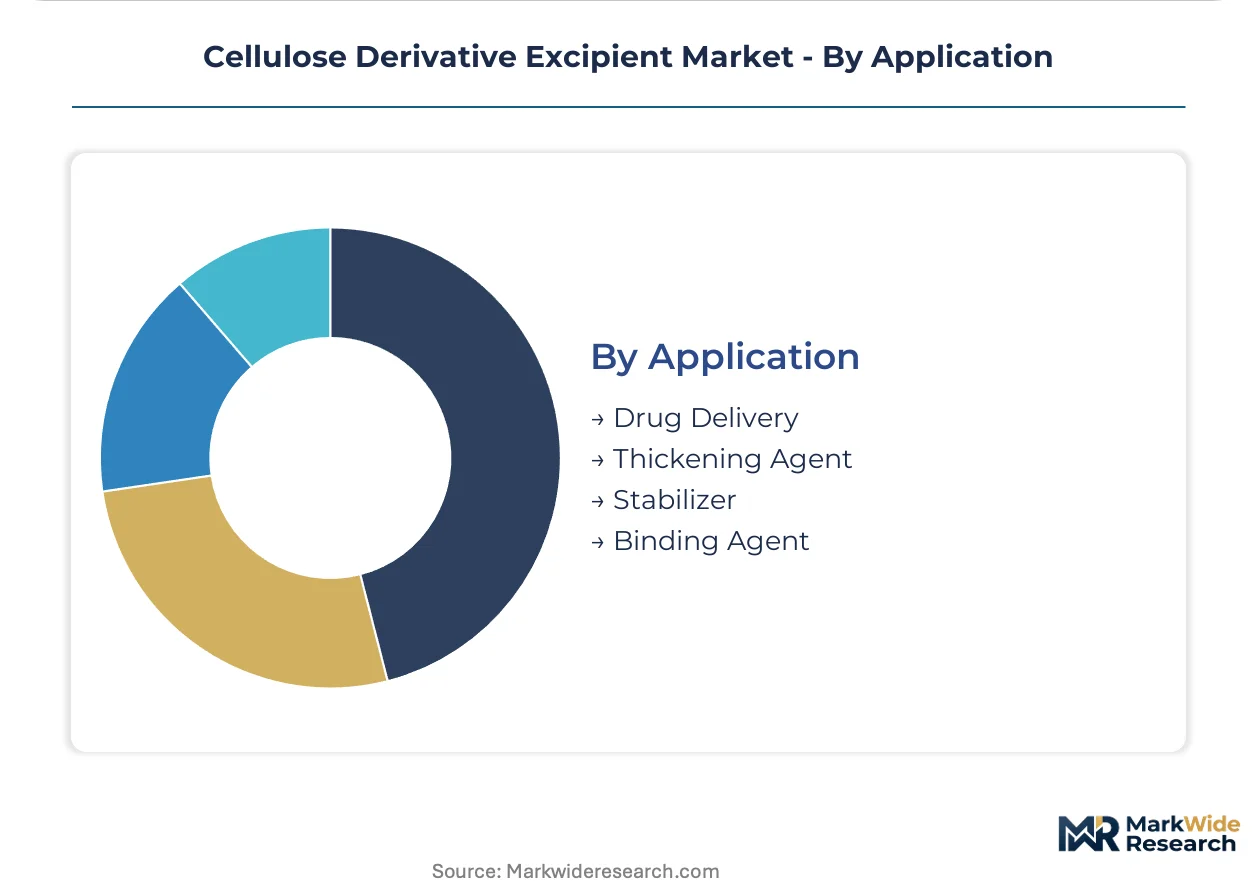
| Segmentation | Product Type: Microcrystalline Cellulose, Hydroxypropyl Methylcellulose, Ethylcellulose, Carboxymethylcellulose End User: Pharmaceuticals, Nutraceuticals, Food Industry, Cosmetics Form: Tablets, Powders, Granules, Coatings Application: Drug Delivery, Thickening Agent, Stabilizer, Binding Agent |
| Companies Covered | Ashland Global Holdings Inc, Dow Inc, Shin-Etsu Chemical Co., Ltd., Eastman Chemical Company, CP Kelco U.S., Inc., DuPont, Celanese Corporation, Daicel Corporation, FMC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulose Derivative Excipient Market Strategic Shifts
Process analytical technology integration is compressing batch release timelines while excipient functionality mapping is enabling quality-by-design formulation approaches that reduce development cycle risk.
Near-infrared spectroscopy coupled with chemometric modeling is automating real-time moisture and substitution degree verification during cellulose ether production. Contract manufacturers serving generic pharmaceutical clients are deploying these systems to compress batch release from days to hours. The technology is automating quality assurance labor and reducing offline laboratory testing bottlenecks that previously constrained throughput scaling.
EMA's F-Gas Regulation and REACH restrictions on chlorinated solvents are forcing reformulation of ethylcellulose coating systems toward aqueous or ethanol-based processes. Film-coating houses across Germany and the Netherlands are retrofitting spray systems to accommodate higher solids-load aqueous dispersions. This regulatory compression is elevating demand for low-viscosity HPMC grades that achieve equivalent film properties without organic solvent carriers.
Pharmaceutical sponsors are consolidating excipient qualification to dual-source strategies with locked specifications, displacing opportunistic spot purchasing. Generic drug manufacturers in India and Eastern Europe are responding by negotiating multi-year supply agreements with certified manufacturers. This procurement consolidation is most visible among top-twenty generic sponsors seeking to minimize pharmacopeial audit burden and supply interruption risk.
Cellulose Derivative Excipient Market Segmentation
Cellulose derivative excipients serve distinct functional roles across pharmaceutical and consumer applications, with substitution chemistry and physical form determining compatibility with processing equipment and regulatory pathways. Formulators select grades based on dissolution kinetics, compression behavior, and certification requirements for specific dosage forms.
Product Type:
Pharmaceutical manufacturers are upgrading from first-generation binders to performance-optimized cellulose ethers as controlled-release formulations multiply and FDA quality-by-design expectations tighten.
- Microcrystalline Cellulose:Partially depolymerized cellulose with crystalline regions intact delivers exceptional direct compressibility and flow properties. Tablet manufacturers in India rely on pharmacopeial-grade MCC to meet CDSCO certification requirements as domestic production scales.
- Hydroxypropyl Methylcellulose:Mixed ether substitution enables thermal gelation and pH-independent hydration kinetics. Sustained-release matrix demand in Germany and the Netherlands is accelerating HPMC displacement of ethylcellulose as EMA solvent regulations tighten.
- Ethylcellulose:Water-insoluble ethyl ether derivative retains film-forming integrity across broad pH ranges.
- Carboxymethylcellulose:Anionic polyelectrolyte with tunable viscosity grades spans oral, topical, and emerging parenteral applications.
Microcrystalline cellulose sits at the top of the volume ranking, with hydroxypropyl methylcellulose climbing the fastest.
End User:
Customer procurement patterns diverge sharply between regulated pharmaceutical channels and price-sensitive food and cosmetic applications, with certification premiums concentrating in injectable and ophthalmic supply chains.
- Pharmaceuticals:cGMP-compliant excipients for oral solid dosage, controlled-release, and ophthalmic formulations command the steepest certification premiums. US FDA and EMA enforcement of IPEC-PQG standards is consolidating vendor pools around qualified manufacturers.
- Food Industry:FSSAI and FDA food-grade certifications for thickeners and stabilizers operate at lower purity thresholds than pharmaceutical grades.
- Nutraceuticals:Dietary supplement manufacturers blend pharmaceutical and food-grade specifications depending on delivery format.
- Cosmetics:Film-forming and rheology-modifying applications in personal care formulations prioritize sensory performance over pharmacopeial compliance.
Pharmaceuticals dominates absolute consumption value, with nutraceuticals gaining share fastest as supplement delivery formats professionalize.
Form:
Physical presentation determines handling characteristics, dust exposure, and compatibility with continuous manufacturing platforms now favored by quality-by-design adopters.
- Tablets:Pre-compressed or direct-compressible grades engineered for specific crushing strength and disintegration profiles. Twin-screw extrusion compatibility is emerging as a selection criterion among sponsors pursuing FDA quality-by-design approvals.
- Powders:Fine particle size distributions for dissolution and wet granulation processes.
- Granules:Agglomerated forms reducing dust generation and improving flow for high-speed tableting.
- Coatings:Low-viscosity grades formulated for aqueous or solvent-based film-coating systems.
Tablets maintains the largest installed base, with coatings expanding most quickly as aqueous formulation conversions accelerate.
Application:
Functional role in the final dosage form dictates substitution degree, viscosity grade, and monograph compliance requirements across therapeutic categories.
- Drug Delivery:Matrix-forming and membrane-controlled release systems depend on precise hydration and erosion kinetics. Ophthalmic gelation applications in Japan are driving PMDA consultation volumes for thermal-reversible HPMC systems.
- Binding Agent:Intragranular and extragranular binder functionality in tablet compression.
- Thickening Agent:Rheology modification in liquid and semi-solid formulations.
- Stabilizer:Emulsion stabilization and suspension maintenance in complex formulations.
Drug delivery leads in technical complexity and margin contribution, with binding agent remaining the highest-volume application.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors excipient demand concentration as Indian pharmaceutical manufacturing scales and CDSCO localization mandates reshape procurement geography. Formulators across Germany and the United States are tightening IPEC-PQG compliance requirements, while Japanese ophthalmic innovators drive thermal-gelation HPMC specifications.
United States
Oral solid dosage manufacturers in New Jersey and Pennsylvania are consolidating vendor pools around FDA cGMP-certified cellulose ether suppliers. The US FDA's tightened excipient quality guidelines are compressing qualified supplier lists for controlled-release matrix applications. Indianapolis-based formulators are retrofitting continuous manufacturing lines with direct-compressible MCC grades engineered for hot-melt extrusion compatibility.
Germany
Film-coating houses in Ludwigshafen and Frankfurt are retrofitting spray systems to accommodate aqueous HPMC dispersions as EMA F-Gas Regulation restrictions eliminate chlorinated solvent processing. The EMA's MDR framework imposes documentation depth that smaller manufacturers struggle to resource. Bavarian excipient distributors are negotiating multi-year supply agreements with IPEC-PQG certified producers to minimize pharmacopeial audit burdens.
India
Domestic pharmaceutical production scaling in Gujarat and Maharashtra is accelerating excipient localization under CDSCO alignment with USP-NF monographs through BIS certification pathways. The country's national pharmaceutical regulator is enforcing traceability requirements that favor domestic manufacturing over import dependence. Hyderabad's formulation clusters are expanding HPMC matrix tablet capacity for export to regulated markets.
Japan
Ophthalmic gelation applications in Osaka and Tokyo are driving PMDA consultation volumes for thermal-reversible HPMC systems with viscosity modulation at ocular surface temperature. The PMDA's harmonization push between JP and USP heavy metal specifications is reducing reformulation burdens for multinational sponsors. Kanto-region excipient specialists are certifying high-purity grades for exacting monograph standards in regional pharmaceutical markets.
China
Dissolving-grade cellulose feedstock processing in Shandong and Jiangsu provinces is expanding to serve etherification demand from domestic and export pharmaceutical manufacturers. The country's national medical products administration is tightening excipient registration requirements for imported drug applications. Yangtze River Delta chemical parks are upgrading quality control laboratories with nuclear magnetic resonance spectroscopy capability for substitution degree verification.
Cellulose Derivative Excipient Market Competitive Environment
Global majors compete with regional champions across certification tiers and pharmacopeial compliance depth. The vendor base stratifies between multinational chemical conglomerates with captive cellulose ether capacity and specialized excipient houses focused on pharmaceutical-grade monograph adherence. Three archetypes dominate: vertically integrated pulp-to-ether producers, pharmaceutical-exclusive formulators, and diversified chemical suppliers with excipient divisions. Competitive intensity centers on IPEC-PQG certification acquisition and continuous manufacturing compatibility claims.
Within the multinational chemical tier, Ashland Global Holdings Inc and Dow Inc exemplify scale-driven positioning through backward integration into wood pulp supply chains. Daicel Corporation occupies a specialist position serving Japanese and Asian markets with exacting purity standards. These three anchors represent divergent strategic postures: captive raw material control, large-scale infrastructure leverage, and regional pharmacopeial specialization.
| Leading Market Players |
|---|
| Ashland Global Holdings Inc |
| Dow Inc |
| Shin-Etsu Chemical Co., Ltd. |
| Eastman Chemical Company |
| CP Kelco U.S., Inc. |
| DuPont |
| Celanese Corporation |
| Daicel Corporation |
| FMC Corporation |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical formulators in India and Germany are consolidating procurement around IPEC-PQG certified suppliers, compressing vendor pools and elevating purity-grade premiums across oral solid dosage applications. This buyer concentration enables certified manufacturers to command sustained price premiums while spot-market participants face margin compression from commoditized food-grade alternatives.
Pricing Analysis
Dissolving-grade wood pulp costs pass through directly to cellulose ether pricing, with Nordic and North American forestry operations anchoring input cost structures. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and food-grade levels separates IPEC-PQG certified excipients from standard monograph products. Cost compression in food-grade carboxymethylcellulose is intensifying because Asian manufacturers are expanding commoditized capacity. Generic pharmaceutical sponsors in Eastern Europe exhibit the highest price sensitivity, while ophthalmic formulators in Japan accept steep premiums for thermal-gelation HPMC specifications.
Supply Chain Analysis
India's CDSCO localization mandates are reshaping sourcing patterns for domestic pharmaceutical manufacturers, accelerating backward integration into captive cellulose ether production. Supply concentrates in the United States, Germany, and India for pharmaceutical-grade manufacturing, with China expanding dissolving-grade pulp processing capacity. The supply chain draws from Nordic wood pulp, specialized etherification catalysts, and pharmacopeial-grade solvents. Single-source vulnerability runs through concentrated dissolving-grade cellulose feedstock from Nordic forestry operations. Distribution runs through qualified excipient distributors serving cGMP-certified formulation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cellulose derivative excipient market functions as a stable compounder anchored by pharmaceutical quality-by-design mandates that perpetually elevate certification requirements and lock in recurring upgrade cycles.
For Market Incumbents: Anticipate displacement pressure from polymethacrylate film-coating systems by deepening IPEC-PQG certification moats and securing multi-year supply agreements with top-twenty generic sponsors. Ashland and Dow should expand high-purity HPMC capacity in India to capture CDSCO localization-driven demand. Certification investment represents the critical defensive lever against synthetic polymer substitution. For New Entrants and Emerging Players: Enter via parenteral-grade carboxymethylcellulose white space, where pharmaceutical certifications for injectable applications remain underdeveloped relative to oral-grade capacity. India's domestic production scaling under BIS certification pathways offers the most penetrable geography. A go-to-market angle anchored in continuous manufacturing compatibility claims aligns with FDA quality-by-design initiatives. For Investors and Strategic Acquirers: Chemical conglomerates with captive cellulose ether divisions are the most active acquirer in this space, seeking pharmaceutical-grade certification depth to complement industrial portfolios. The market exhibits durable 5-10 year viability driven by controlled-release formulation proliferation and ophthalmic gelation demand. Acquisition targets should display IPEC-PQG certification and NMR substitution-degree analytical capability. The signal to watch is PMDA harmonization progress between JP and USP heavy metal specifications, which would reduce reformulation burdens and consolidate multinational supplier relationships.| Strategic Initiative | Industry Significance |
|---|---|
| IPEC-PQG Certification Acquisition | CDSCO and FDA enforcement compresses qualified vendor pools, elevating certified manufacturers to preferred supplier status. |
| Backward Integration into Wood Pulp | Captive dissolving-grade cellulose supply insulates Ashland and Dow from Nordic forestry input volatility. |
| Continuous Manufacturing Compatibility | Direct-compressible MCC grades engineered for hot-melt extrusion align with FDA quality-by-design expectations. |
| Parenteral-Grade CMC Capacity Buildout | Injectable application certifications unlock margin expansion in undersupplied pharmaceutical-grade segments. |
| Aqueous Coating System Reformulation | EMA F-Gas Regulation compliance drives retrofit demand for low-viscosity HPMC film-coating grades. |
Study Parameters
Multiple input streams — excipient procurement managers at generic pharmaceutical manufacturers, regulatory affairs directors navigating IPEC-PQG compliance, quality control laboratory heads overseeing substitution-degree verification, and CDSCO licensing officers — were reconciled against secondary validation from USP-NF monograph databases, EMA MDR guidance documents, FDA cGMP inspection records, and BIS certification registries. Bottom-up capacity assessments at cellulose ether manufacturing facilities were cross-referenced with top-down pharmaceutical production forecasts across oral solid dosage, controlled-release, and ophthalmic formulation categories.
Historical capacity utilization trends were cross-referenced against panel input from procurement executives to establish baseline assumptions across the projection horizon. Segmentation dimensions modeled include product type, end-user industry, physical form, application function, and regional regulatory cluster. CAGRs were derived from demand elasticity analysis against pharmaceutical production scaling and excipient localization policy implementation. Forecast inputs incorporated CDSCO BIS certification pathway adoption rates and PMDA harmonization progress between JP and USP specifications.
Inputs from primary stakeholder interviews and pharmacopeial regulatory filings were available through the study window; gaps in real-time inventory data from confidential supply agreements introduce uncertainty bands around vendor consolidation velocity assumptions. Forecasts reflect documented substitution patterns between cellulose derivatives and synthetic polymers, with revision risk hinging on REACH solvent restriction enforcement and dissolving-grade pulp supply disruptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Mica Sheet Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Polyimide Films Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Barium Fluoride Market
Specialty Materials
United States Microspheres Market
Specialty Materials
Fumed Silica Market
Specialty Materials
Barium Borate Market
Specialty Materials
Global Flexible Substrates Market
Specialty Materials
Retro Reflective Materials Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Africa Collagen Market
Specialty Materials
Global Conductive Silicone Market
Specialty Materials
Global Fluorosilicone Market
Specialty Materials
Niobium Pentoxide Market
Specialty Materials
Advanced Green Septa Market