
 Absorbent Booms and Socks Market | 2026-2036
Absorbent Booms and Socks Market Size, Share, and Industry Trends Forecast 2026-2036
Absorbent Booms and Socks Market Analysis
Modular bundling of absorbent socks with containment berms and disposal bags is recalibrating buyer choice toward configured response kits rather than standalone purchases. New Pig Corporation leverages its direct-channel infrastructure to dominate industrial procurement workflows. Brady Corporation sustains brand strength through ANSI-compliant safety labeling integration. Oil-Dri Corporation anchors its position via backward integration into mineral absorbent mining.
Absorbent booms and socks are cylindrical containment devices filled with hydrophobic or universal absorbents, typically measuring 3-inch diameter for socks and 5-8 inch diameter for booms, designed to encircle spills or channel liquids in industrial and environmental settings. Polypropylene-filled variants dominate marine applications due to oil-selective wicking and flotation properties, while natural fiber compositions gain structural attention as EPA disposal regulations tighten. Environmental cleanup applications represent the fastest-growing segment as superfund site remediation accelerates, whereas standard booms remain the mature volume anchor across manufacturing plants and warehousing facilities.
EPA Oil Pollution Act requirements and OSHA 29 CFR 1910.120 standards shape product certification pathways and procurement mandates for hazardous material handlers. ISO 14001 environmental management systems further drive documented spill-response preparedness among industrial end-users. Stakeholders must monitor regulatory harmonization between state-level stormwater permits and federal spill prevention rules to anticipate compliance-driven replacement cycles.
Market Dynamics
Modular bundling of absorbent containment products with disposal infrastructure is restructuring procurement patterns across industrial facilities, as buyers prioritize pre-configured response systems over discrete component sourcing. This shift compresses vendor selection cycles while elevating certification and logistics integration as decisive purchase criteria.
Growth Catalysts
- OSHA 29 CFR 1910.120 mandates:Hazardous material handling facilities must maintain documented spill response capabilities, driving scheduled replacement of absorbent inventories and expanding the addressable base of compliant end-users.
- Superfund site remediation acceleration:EPA-directed environmental cleanup operations are consuming specialized absorbent booms for hydrocarbon containment at contaminated groundwater interfaces, creating dedicated demand outside traditional industrial channels.
- Polypropylene flotation chemistry:Hydrophobic wicking properties in marine-grade booms enable oil-selective recovery without water saturation, sustaining preference in Gulf Coast port operations and offshore supply chains.
Market Restraints
- Polypropylene feedstock volatility:Crude oil price fluctuations directly transmit to melt-blown nonwoven input costs, compressing margin stability for manufacturers without captive resin supply.
- Disposal regulatory tightening:EPA RCRA hazardous waste classifications for oil-saturated absorbents are extending landfill restrictions and elevating post-use handling costs for end-users.
- Mineral absorbent substitution:Diatomaceous earth and clay-based alternatives offer lower unit costs for non-marine applications, constraining pricing power in general industrial segments.
Strategic Opportunities
- India industrial corridor expansion:Petroleum refining capacity additions in Gujarat and Maharashtra are establishing new demand nodes for spill containment infrastructure as domestic HSE enforcement intensifies.
- Biodegradable fiber formulations:Cellulose and agricultural waste absorbents align with EU Green Deal circular economy targets, opening procurement channels within European sustainability-mandated facilities.
- E-commerce industrial distribution:Direct-to-facility digital procurement platforms are disintermediating traditional safety supply distributors, enabling margin capture and customer data accumulation for specialized manufacturers.
Industry Challenges
- ISO 14001 documentation complexity:Environmental management system certification requires auditable spill response protocols, forcing smaller facilities to outsource compliance preparation or abandon certification pursuit.
- Cross-contamination protocol training:Chemical-specific absorbent deployment demands differentiated handling procedures, creating workforce competency gaps that delay incident response effectiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorbent Booms and Socks Market |
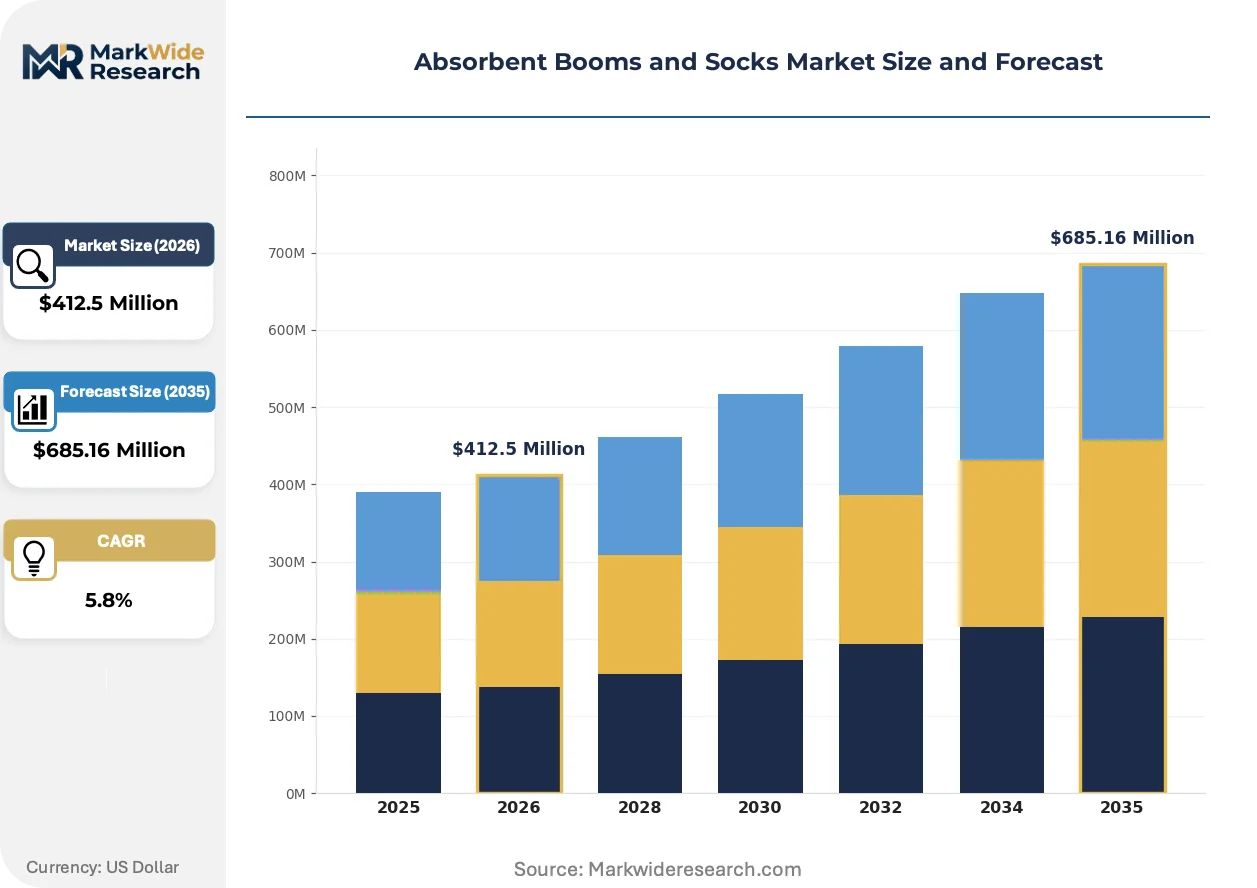
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Booms, Socks, Custom Length Booms, Eco-friendly Socks Material: Polypropylene, Cotton, Natural Fiber, Synthetic Fiber Application: Industrial Spills, Marine Uses, Construction Sites, Environmental Cleanup Distribution Channel: Direct Sales, Retail Outlets, Online Platforms, Third-party Distributors |
| Companies Covered | New Pig Corporation, Brady Corporation, SpillTech, 3M Company, Oil-Dri Corporation, PSI Parker Systems Inc., SPC, Wipeco Industries Inc., Absorbent Products Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorbent Booms and Socks Market Emerging Trajectories
Smart containment technologies and material science advances are redefining performance benchmarks across marine, industrial, and environmental remediation applications. These developments are compressing replacement cycles while elevating traceability and sustainability as purchase determinants.
Biodegradable absorbent cores derived from agricultural waste fibers are converging with compostable outer sleeves to create full-lifecycle sustainable containment products. Food processing facilities and municipal wastewater operations are piloting these systems to preempt disposal cost escalation. This convergence is pressuring conventional polypropylene suppliers to accelerate recycling program development or cede share in sustainability-sensitive accounts.
EPA stormwater permit renewals are incorporating numeric effluent limits for oil and grease discharges, compelling manufacturing facilities to upgrade from passive containment to active absorption systems. Metal fabrication plants and automotive service centers face the steepest compliance deadlines under revised Multi-Sector General Permit terms. Texas and Louisiana industrial clusters are responding with accelerated absorbent sock deployment around outdoor storage and loading areas.
Integrated service contracts bundling absorbent supply, waste pickup, and regulatory documentation are displacing transactional product purchases among multi-site industrial operators. Safety distributors are restructuring field service organizations to capture recurring revenue streams from facilities management teams. This pattern is most pronounced in petrochemical corridor operations where procurement consolidation centralizes vendor relationships.
Absorbent Booms and Socks Market Segmentation
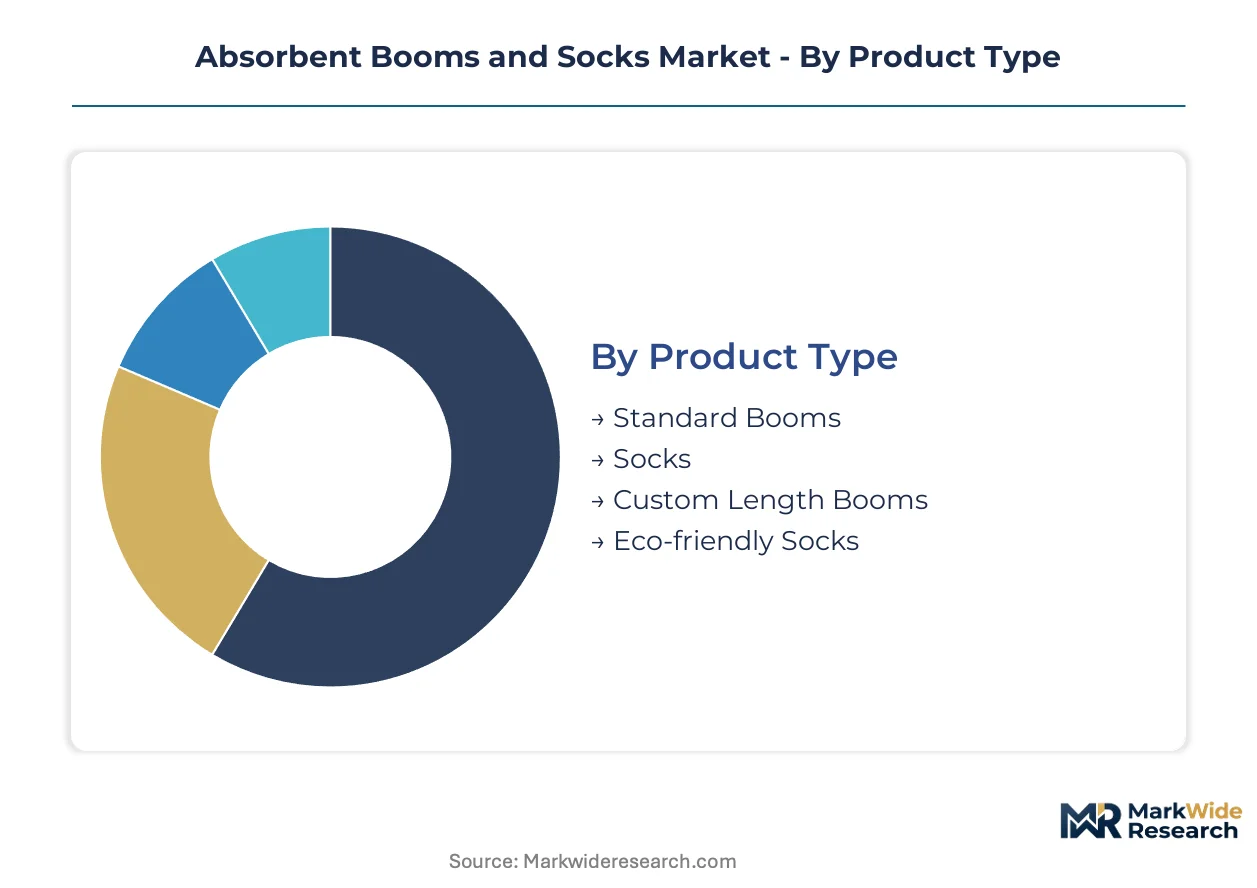
Absorbent containment procurement varies sharply by deployment environment, material chemistry, and compliance exposure. Segmentation reveals where polypropylene flotation commands premium pricing versus where mineral substitutes erode margins.
Product Type:
Volume anchors the mature standard formats while custom configurations capture specification-driven premiums.
- Standard Booms:Cylindrical containment devices measuring 5-8 inch diameter, filled with melt-blown polypropylene for oil-selective absorption. Demand concentrates in Texas petrochemical corridors and Gulf Coast marine terminals where EPA Oil Pollution Act mandates drive scheduled inventory replacement.
- Socks:Flexible 3-inch diameter tubes designed for machine base containment and aisle spill channeling. Manufacturing plants and warehousing facilities in Louisiana industrial clusters deploy these for OSHA 29 CFR 1910.120 compliance, with procurement accelerating around outdoor storage areas under revised stormwater permit terms.
- Custom Length Booms:Specification-cut configurations for irregular shoreline geometries or tank farm perimeters.
- Eco-friendly Socks:Biodegradable fiber cores with compostable outer sleeves for food processing and municipal wastewater operations.
Today's leader: Standard Booms. Tomorrow's challenger: Eco-friendly Socks.
Material:
Marine applications enforce strict hydrophobic performance standards that commodity alternatives cannot satisfy.
- Polypropylene:Hydrophobic melt-blown nonwoven with oil-selective wicking and inherent flotation properties. Gulf Coast port operations and offshore supply chains sustain preference despite feedstock volatility tied to crude oil pricing.
- Natural Fiber:Cellulose and agricultural waste formulations aligning with EU Green Deal circular economy targets. European sustainability-mandated facilities are piloting these systems to preempt disposal cost escalation under tightening RCRA classifications.
- Cotton:General-purpose absorbent for non-hazardous industrial spills where water saturation tolerance exists.
- Synthetic Fiber:Engineered blends for chemical-specific deployment protocols.
Polypropylene dominates marine revenue. Natural Fiber posts the steepest expansion trajectory in sustainability-sensitive accounts.
Application:
Environmental remediation is climbing fastest as superfund site work consumes specialized containment outside traditional industrial channels.
- Environmental Cleanup:Specialized booms for hydrocarbon containment at contaminated groundwater interfaces. EPA-directed superfund site remediation is creating dedicated demand nodes with distinct procurement workflows and technical specifications.
- Marine Uses:Oil-selective recovery operations requiring flotation stability in wave-action conditions. Harbor authorities and offshore logistics operators maintain standing inventory under Coast Guard contingency requirements.
- Industrial Spills:Manufacturing plant and warehouse deployment for routine maintenance and incident response.
- Construction Sites:Temporary containment for fuel transfer and equipment servicing in stormwater-regulated zones.
Environmental Cleanup is gaining share fastest. Industrial Spills remains the volume foundation.
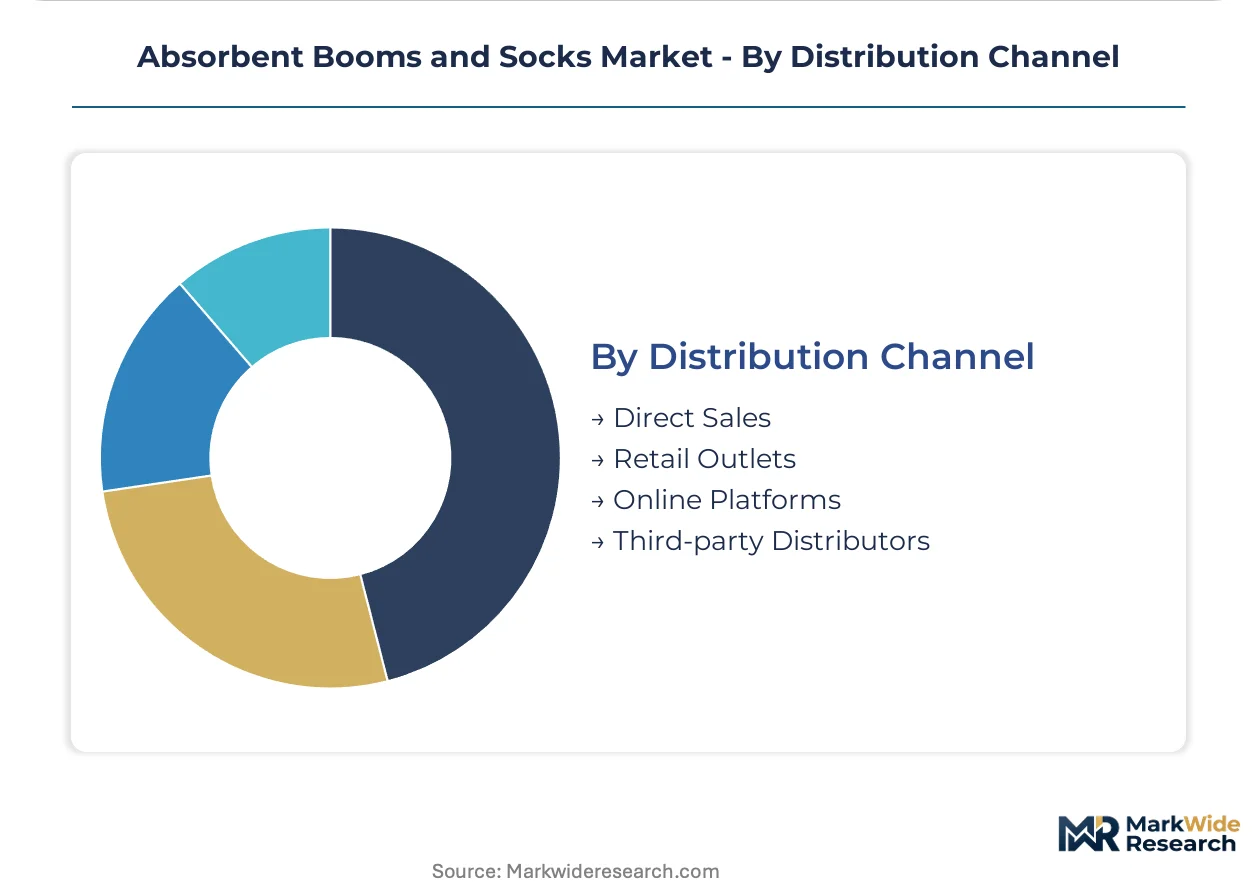
Distribution Channel:
Direct procurement is displacing traditional safety supply intermediaries as facilities management teams consolidate vendor relationships.
- Direct Sales:Manufacturer-to-facility relationships capturing recurring revenue through integrated service contracts bundling supply, waste pickup, and regulatory documentation. Petrochemical corridor operations with centralized procurement favor this channel.
- Online Platforms:Digital procurement interfaces disintermediating distributors and enabling customer data accumulation. Multi-site industrial operators use these for standardized SKU deployment across locations.
- Third-party Distributors:Traditional safety supply houses restructuring field service organizations to defend position.
- Retail Outlets:Transactional purchases for small facilities and emergency replenishment.
Direct Sales commands the premium relationship. Online Platforms are compressing distributor margins fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial spill containment infrastructure originated in the United States Gulf Coast petrochemical complexes during the 1970s environmental regulatory expansion, with polypropylene boom fabrication scaling first in Texas and Louisiana before diffusing to European marine terminals and Asian refining corridors.
United States
Texas petrochemical corridors and Louisiana marine terminals drive concentrated demand for oil-selective polypropylene booms under EPA Oil Pollution Act mandates. OSHA 29 CFR 1910.120 workplace safety standards enforce documented spill response capabilities across hazardous material handling facilities. Houston-Galveston port operations maintain standing inventory for Coast Guard contingency requirements, with procurement accelerating around outdoor storage areas under revised Multi-Sector General Permit terms.
Germany
Industrial manufacturing clusters in North Rhine-Westphalia and Bavaria deploy universal absorbent socks for machine base containment and chemical-specific deployment protocols. REACH chemical registration requirements and EU Green Deal circular economy targets are elevating scrutiny of polypropylene disposal pathways. Hamburg port authorities and Rhine River logistics operators sustain preference for flotation-stable marine-grade configurations despite feedstock cost volatility.
China
Petroleum refining capacity additions in Shandong Peninsula and Yangtze River Delta regions are establishing new demand nodes for spill containment infrastructure. MEE environmental enforcement intensification and dual carbon goals are pressuring facilities toward documented spill-response preparedness. Qingdao and Shanghai marine terminals represent concentrated procurement channels for oil-selective recovery operations.
India
Petroleum refining expansions in Gujarat and Maharashtra industrial corridors are creating dedicated demand outside traditional channels as domestic HSE enforcement intensifies. BIS certification requirements and state-level pollution control mandates are tightening compliance exposure for chemical processing facilities. Jamnagar and Mumbai refining complexes are accelerating absorbent sock deployment around outdoor storage and loading areas.
Netherlands
Rotterdam-Europoort marine terminal operations and Antwerp-Rhine logistics corridors sustain premium-tier demand for flotation-stable boom configurations. EU Green Deal sustainability mandates and tightening RCRA-equivalent waste classifications are pressuring conventional polypropylene suppliers toward recycling program development. Randstad industrial facilities are piloting biodegradable fiber formulations to preempt disposal cost escalation.
Absorbent Booms and Socks Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and direct-channel infrastructure, with tiered pricing separating ANSI-compliant safety labeling integrators from mineral absorbent miners and regional fabricators. The vendor base stratifies into three archetypes: direct-channel industrial specialists leveraging integrated service contracts, backward-integrated mineral absorbent miners controlling captive resin supply, and safety supply distributors restructuring field service organizations to defend position against disintermediation. Dominant competitive moves include M&A to capture recurring revenue streams from facilities management teams, and capacity expansion into biodegradable fiber formulations aligning with EU circular economy targets.
Within the direct-channel specialist tier, New Pig Corporation and Brady Corporation exemplify archetypes built on industrial procurement workflow dominance and safety labeling integration respectively. Oil-Dri Corporation anchors the backward-integrated mineral absorbent segment through upstream control over diatomaceous earth mining operations. These three entities occupy positions that represent the structural fault lines between configured response kit bundling and standalone component sourcing across petrochemical corridor procurement.
| Leading Market Players |
|---|
| New Pig Corporation |
| Brady Corporation |
| SpillTech |
| 3M Company |
| Oil-Dri Corporation |
| PSI Parker Systems Inc. |
| SPC |
| Wipeco Industries Inc. |
| Absorbent Products Ltd |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between ANSI-compliant safety labeling integrators and mineral absorbent miners manifests in both margin capture and upstream sourcing configurations. Premium-tier vendors command recurring revenue through integrated service contracts bundling supply with waste pickup and regulatory documentation, while commodity players compete on per-unit transactional pricing tethered to polypropylene feedstock volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates configured response kit bundling from standalone component sourcing. Price differentiation rests on certification depth and direct-channel infrastructure, with OSHA 29 CFR 1910.120 compliance documentation commanding premium positioning. Cost compression in economy-tier mineral absorbents is intensifying because diatomaceous earth alternatives undercut polypropylene on unit economics. General industrial buyers exhibit highest price sensitivity, whereas petrochemical corridor operators prioritize logistics integration over per-unit cost.
Supply Chain Analysis
Dual-sourcing requirements from multi-site industrial operators mandate qualified backup suppliers for both polypropylene resin and natural fiber formulations. Manufacturing concentration centers on the United States, China, and Germany, with melt-blown nonwoven production drawing from crude oil derivatives and agricultural waste fiber streams. Supply chain risk hinges on polypropylene feedstock volatility transmitting directly to input costs. Distribution runs through direct-to-facility digital platforms disintermediating traditional safety supply houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA stormwater permit renewals incorporating numeric effluent limits for oil and grease discharges accelerate replacement cycles across manufacturing facilities.
For Market Incumbents: Lock in recurring revenue streams through integrated service contracts bundling absorbent supply, waste pickup, and regulatory documentation. Deepen backward integration into mineral absorbent mining to offset polypropylene feedstock volatility threatening margin stability. Defend against biodegradable fiber substitution by accelerating recycling program development for sustainability-sensitive accounts.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium polypropylene marine booms and economy mineral absorbents offers white-space entry for cellulose-based formulations. Target European sustainability-mandated facilities piloting EU Green Deal circular economy alignment. Penetrate through e-commerce industrial distribution platforms disintermediating established safety supply distributors.
For Investors and Strategic Acquirers: Asymmetric upside sits with direct-channel specialists possessing captive field service organizations and documented compliance workflows. Long-term viability favors vendors controlling both absorbent manufacturing and post-use waste handling infrastructure. Watch for EPA RCRA hazardous waste classification tightening as inflection indicator for disposal-integrated business model premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Absorbent Mining | Oil-Dri Corporation's upstream control over diatomaceous earth operations insulates margin from polypropylene feedstock volatility. |
| Biodegradable Fiber Formulation Development | Cellulose and agricultural waste absorbents align procurement channels with EU Green Deal circular economy targets. |
| Direct-to-Facility Digital Platform Launch | New Pig Corporation leverages e-commerce infrastructure to disintermediate traditional safety supply distributors. |
| Integrated Service Contract Expansion | Brady Corporation bundles ANSI-compliant safety labeling with absorbent containment to capture facilities management recurring revenue. |
| Recycling Program Infrastructure Buildout | Conventional polypropylene suppliers preempt disposal cost escalation under tightening EPA RCRA classifications. |
Methodological Framework
Direct dialogue with plant managers, procurement leads at petrochemical facilities, distribution channel partners, and technical R&D directors grounded qualitative findings. Secondary validation drew from EPA enforcement databases, OSHA compliance records, customs trade data, and SEC 10-K filings from publicly traded industrial safety suppliers. Bottom-up facility-level demand assessment and top-down regulatory mandate sizing were triangulated to cross-verify volume estimates.
Bottom-up modeling tracked absorbent deployment rates by facility type, compliance deadline schedules, and replacement cycle frequencies across the projection horizon. Segmentation dimensions included product format, material chemistry, application environment, and distribution channel. CAGRs were derived from regression analysis against regulatory enforcement intensity indices and petrochemical capacity expansion pipelines. Forecast inputs incorporated polypropylene resin price trajectories and superfund site remediation funding allocations.
Caveats apply where EPA RCRA hazardous waste reclassifications or OSHA workplace safety standard revisions could materially shift the outlook. Deviation in polypropylene feedstock pricing or EU Green Deal implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Specialty and High Performance Films Market
Specialty Materials
Jesmonite Market
Specialty Materials
Silicone Solutions for Leather and Textile Market
Specialty Materials
Retro Reflective Materials Market
Specialty Materials
Electroactive Polymers (EAP) Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Polyester Medical Films Market
Specialty Materials
Sulphur Bentonite Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Rigid Polyurethane Foams Market
Specialty Materials
Activated Carbon Bags Market
Specialty Materials
Lab Grown Diamonds Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Global Cellulose Acetate Market
Specialty Materials
Metallic Hot Stamping Foils Market