
 Grease Additives Market | 2026-2036
Grease Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Grease Additives Market Foresight
Heavy equipment maintenance is pivoting toward longer-interval greases that reduce downtime in mining and construction fleets. BASF SE leverages its polymer chemistry portfolio to supply high-performance dispersant technologies for extreme operating conditions. The Lubrizol Corp anchors North American supply through specialized additive packages tailored to off-highway OEM specifications. Lanxess AG competes on sulfur-phosphorus chemistry leadership for heavy-load bearing applications.
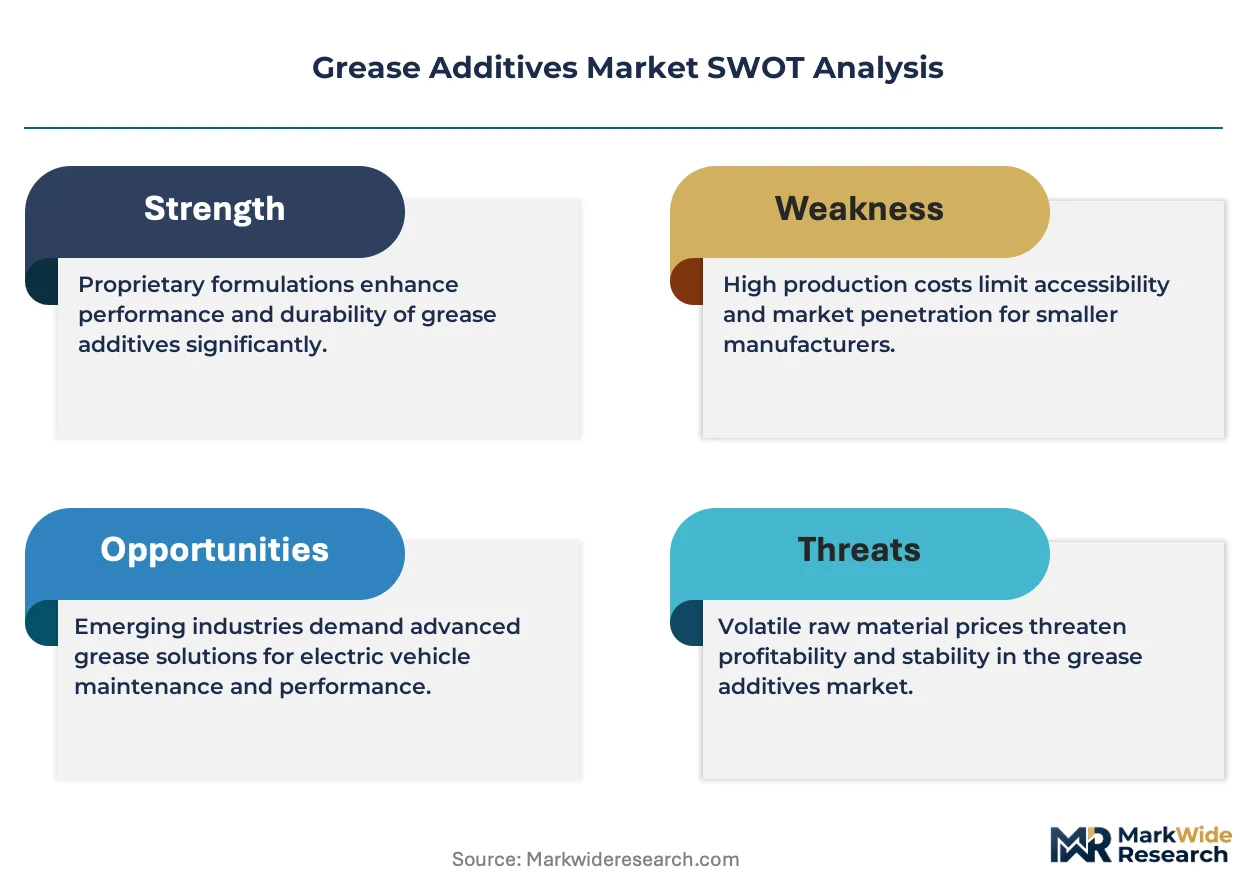
Grease additives are functional chemical compounds blended into lubricating greases to enhance load-carrying capacity, oxidation stability, and corrosion resistance under boundary lubrication conditions; typical formulations incorporate borate, sulfurized olefin, or zinc dialkyldithiophosphate chemistries at concentrations between one and fifteen percent by weight to meet NLGI consistency grades and ASTM D2265 dropping point thresholds. Extreme pressure additives dominate value pools due to their critical role in gear and bearing protection across industrial machinery, while biodegradable oil base stocks represent the fastest-growing formulation category as OEM sustainability procurement standards tighten. Anti-wear additives sustain mature volume demand in general manufacturing maintenance, where cost-per-unit sensitivity limits premium chemistry uptake.
REACH in Europe and EPA regulations in the United States constrain heavy metal content and biodegradability profiles in grease formulations, compelling reformulation investments among additive suppliers. ECHA substance evaluation processes extend lead times for novel chemistry registrations, advantaging incumbents with established dossier portfolios. ASTM International and ISO 6743 classification standards govern product interoperability, shaping R&D allocation toward globally certifiable additive platforms. Stakeholders must monitor evolving OEM factory-fill specifications and regional chemical restriction timelines to align portfolio development with compliance windows.
Market Dynamics
Electric vehicle drivetrain engineering is compressing traditional grease additive demand while simultaneously creating specifications for high-voltage compatible, thermally stable formulations that withstand inverter-adjacent operating temperatures.
Growth Catalysts
- REACH substance evaluation protocols:ECHA's tightening chemical disclosure requirements are accelerating reformulation cycles among European lubricant blenders, creating pull for pre-registered additive portfolios.
- Mining fleet automation:Autonomous haul trucks in Australian and Chilean open-pit operations demand extended-interval greases with sensor-compatible tribological signatures.
- Biodegradable base stock convergence:Synthetic ester chemistry advancement is enabling vegetable-oil-derived formulations that meet NLGI 2 consistency grades without sacrificing dropping point performance.
Market Restraints
- Zinc dialkyldithiophosphate feedstock volatility:Phosphorus and zinc commodity price swings compress additive supplier margins and destabilize annual contract pricing.
- Incumbent dossier concentration:ECHA registration portfolios cluster among established European chemical conglomerates, extending novel chemistry commercialization timelines for specialized entrants.
- Solid lubricant substitution:Molybdenum disulfide and graphite dispersions in polymer matrices are displacing conventional EP additives in sealed-for-life bearing applications.
Strategic Opportunities
- India precision manufacturing expansion:BIS certification requirements for automotive supplier parks in Pune and Chennai are creating factory-fill specification windows for additive packages meeting JIS K 2220 equivalents.
- Wind turbine main bearing re-lubrication systems:Centralized greasing infrastructure in offshore installations demands shear-stable thickeners compatible with remote monitoring diagnostics.
- EU Green Deal carbon border adjustments:Embedded emissions accounting for imported lubricants is incentivizing regional additive production and bio-based feedstock certification.
Industry Challenges
- Tribochemistry PhD scarcity:Formulation science expertise concentrated among retiring specialists in German and Japanese research institutes constrains R&D team scaling.
- ASTM D2265 certification backlog:Third-party testing laboratory capacity limitations in North America extend product qualification timelines for new dropping point formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grease Additives Market |
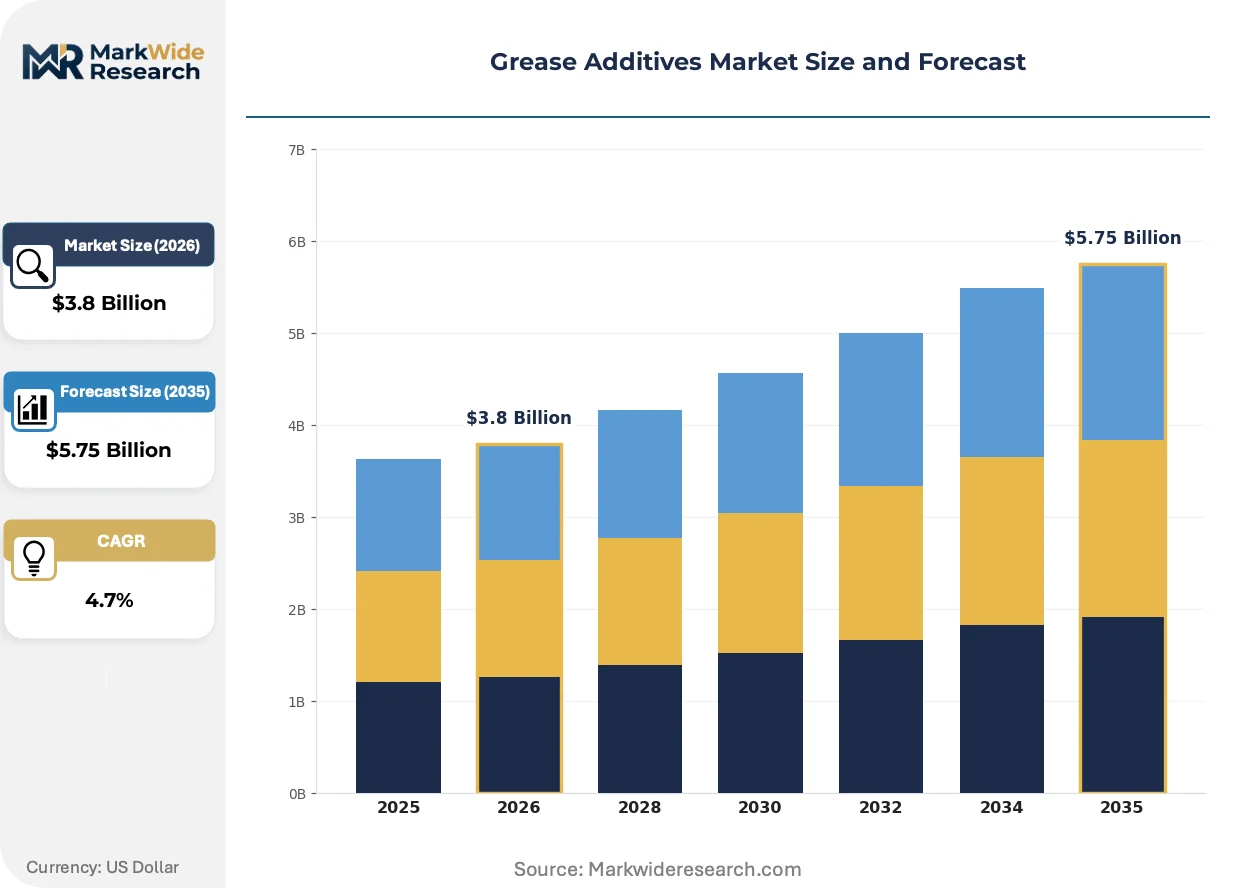
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extreme Pressure Additives, Anti-Wear Additives, Rust Preventive Additives, Dispersants Application: Aerospace, Automotive Manufacturing, Heavy Equipment, Marine Base Oil Type: Mineral Oil, Synthetic Oil, Biodegradable Oil, Ester-Based Oil End User: General Manufacturing, Transportation, Construction, Agriculture |
| Companies Covered | Afton Chemical Corp, BASF SE, Clariant AG, Croda International plc, Evonik Industries AG, The Lubrizol Corp, Lanxess AG, RT Vanderbilt Holding Co Inc, Shamrock Technologies Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grease Additives Market Shifts & Advancements
Formulation science is pivoting toward electrochemical compatibility and bio-derived feedstocks as end-use specifications diverge between legacy internal combustion applications and electrified drivetrain architectures.
Ionic liquid grease additives are electrifying thermal management strategies for electric vehicle reduction gearboxes. These non-volatile salts operate across wider temperature ranges than traditional borate complexes. Automotive OEMs in Germany and Japan are factory-filling axle assemblies with ionic liquid-enhanced greases. The technology is electrifying supplier qualification protocols by mandating electrical conductivity and copper corrosion resistance alongside mechanical performance metrics.
EPA Safer Choice program expansion is tightening biodegradability thresholds for greases used in municipal fleet maintenance. The framework now requires 60-day aquatic toxicity testing for products bearing the label. Municipal procurement departments in California and Washington are restricting purchases to certified formulations. Industrial maintenance contractors serving public infrastructure are reformulating inventory to retain eligibility for state-level contracts.
Buyer consolidation among North American mining operators is compressing supplier negotiation cycles and unbundling technical service from product pricing. Tier-one diversified miners now centralize lubricant procurement through corporate engineering standards rather than site-level discretion. This concentrates volume with additive suppliers offering integrated fluid analysis programs. The shift is most visible in Nevada and Saskatchewan potash operations where single-source agreements cover multiple mine sites.
Grease Additives Market Segmentation
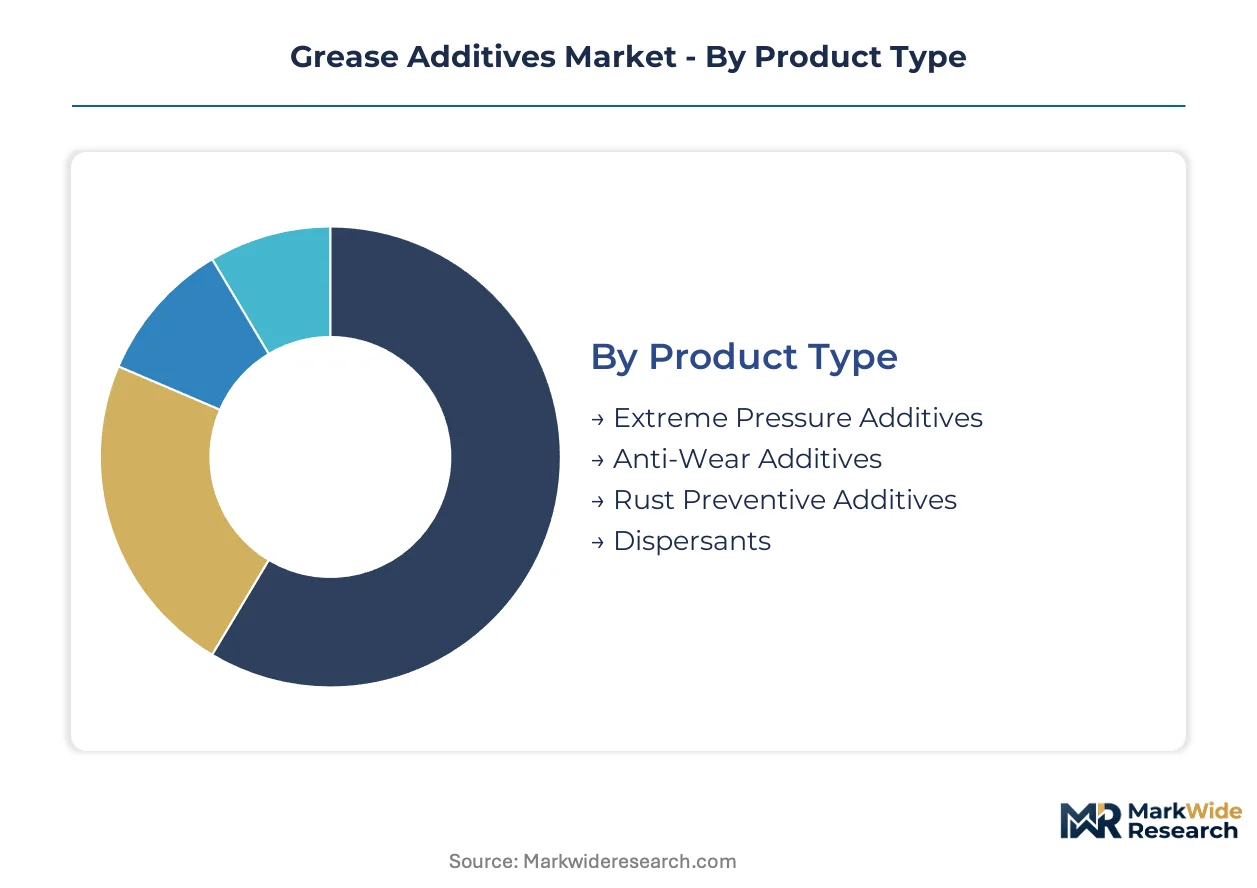
Grease additive specifications diverge sharply across end-use environments, with thermal stability demands from electric vehicle drivetrains pulling formulation chemistry away from legacy internal combustion requirements. Segment boundaries are hardening as OEM factory-fill certifications become gatekeepers to volume contracts.
Product Type:
Replacement cycles for industrial machinery are extending from 5,000-hour to 10,000-hour service intervals, forcing additive packages to deliver performance durability without proportional cost increases.
- Extreme Pressure Additives:Sulfurized olefin and borate complexes form sacrificial tribofilms under boundary lubrication conditions. Mining haul truck axles in Western Australia and Chile concentrate demand as autonomous fleet operators specify NLGI 2 greases with 15% EP additive loading for 12-month re-greasing intervals.
- Anti-Wear Additives:Zinc dialkyldithiophosphate chemistry dominates general manufacturing maintenance where cost-per-unit sensitivity limits premium formulation uptake. Automotive bearing plants in Germany and Japan specify reduced-zinc alternatives to meet REACH substance evaluation protocols for worker exposure limits.
- Rust Preventive Additives:Calcium sulfonate complexes protect offshore wind turbine main bearings from salt spray corrosion in North Sea installations.
- Dispersants:Polyisobutylene succinimide chemistry maintains grease homogeneity across temperature cycling in aerospace actuator mechanisms.
Extreme Pressure Additives sits at the top of the volume ranking, with Biodegradable Oil climbing the fastest.
Application:
Cost tier differentiation separates specification-grade factory-fill contracts from aftermarket maintenance volumes, with aerospace and automotive commanding 3-5x per-kilogram pricing over heavy equipment.
- Aerospace:MIL-PRF-23827 certified greases for landing gear and flight control actuators require ionic liquid thermal stability above 175°C. Boeing and Airbus supplier qualification protocols mandate 5,000-hour oxidation stability testing that eliminates commodity additive suppliers.
- Automotive Manufacturing:Electric vehicle reduction gearboxes specify electrically conductive greases with copper corrosion resistance below 0.5 rating per ASTM D4048. German OEMs factory-fill axle assemblies with ionic liquid-enhanced formulations that withstand inverter-adjacent operating temperatures.
- Heavy Equipment:Autonomous mining trucks in Nevada and Saskatchewan demand sensor-compatible tribological signatures for predictive maintenance algorithms.
- Marine:Stern tube bearing greases face EPA VGP discharge restrictions in US coastal waters, accelerating biodegradable base stock adoption.
Aerospace commands the premium pricing tier, while Heavy Equipment delivers the steepest volume expansion trajectory.
Base Oil Type:
Supply concentration in synthetic ester feedstocks is reshaping regional production economics, with European bio-refinery capacity determining biodegradable grease availability.
- Mineral Oil:Paraffinic base stocks from Group I and Group II refineries sustain cost-driven general manufacturing demand. Construction equipment fleets in India and Brazil specify mineral oil greases where procurement budgets prioritize unit cost over service interval extension.
- Synthetic Oil:Polyalphaolefin and polyalkylene glycol chemistry enables -40°C cold start performance for wind turbine main bearings in Scandinavian offshore installations. Lanxess AG and BASF SE anchor European supply through specialized PAO polymerization capacity.
- Biodegradable Oil:Vegetable oil-derived formulations meet EU Green Deal procurement mandates for municipal fleet maintenance in Germany and France.
- Ester-Based Oil:Synthetic diester and polyol ester chemistry delivers thermal oxidative stability above 200°C for aerospace turbine engine accessories.
Mineral Oil retains the largest volume footprint, with Ester-Based Oil gaining share fastest in specification-grade applications.
End User:
Customer procurement centralization is compressing supplier margins, with tier-one diversified manufacturers unbundling technical service from product pricing across multi-site agreements.
- General Manufacturing:Maintenance departments in precision machining and metal forming operations specify NLGI 2 consistency grades with 5% anti-wear additive loading. Cost-per-unit sensitivity limits premium chemistry uptake in mid-tier fabricators serving construction and agricultural OEM supply chains.
- Transportation:Class 8 truck fleets in the US Midwest and German long-haul operators specify extended-drain greases with 50,000-kilometer service intervals. Centralized procurement through corporate engineering standards concentrates volume with additive suppliers offering integrated fluid analysis programs.
- Construction:Excavator and crane OEMs in Japan specify factory-fill greases with molybdenum disulfide compatibility for pivot pin applications.
- Agriculture:Combine harvester manufacturers specify greases with water washout resistance above 80% per ASTM D1264 for seasonal field exposure.
General Manufacturing holds the broadest installed base, with Transportation expanding most quickly through fleet consolidation and predictive maintenance adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting grease additive production toward jurisdictions with streamlined chemical registration protocols, as ECHA dossier costs in Europe widen the compliance gap with Asian and North American alternatives. Manufacturers are relocating blending capacity to exploit these cost differentials while maintaining specification-grade output.
Germany
Precision manufacturing clusters in Stuttgart and Munich concentrate factory-fill demand from automotive OEMs specifying REACH-compliant reduced-zinc formulations. The EU Green Deal carbon border adjustment mechanism is incentivizing regional bio-based feedstock certification for municipal fleet suppliers. BASF SE and Lanxess AG anchor additive production in Ludwigshafen and Cologne, serving both domestic OEMs and export markets.
United States
EPA Safer Choice program expansion in California and Washington is tightening biodegradability thresholds for municipal procurement, compressing supplier qualification timelines. Mining fleet automation in Nevada concentrates demand for sensor-compatible greases with extended service intervals. The Lubrizol Corp maintains specialized additive packaging capacity near Cleveland, supplying off-highway OEM specifications across the Midwest.
China
Dual carbon policy implementation is accelerating synthetic ester capacity expansion in Zhejiang and Jiangsu provinces for biodegradable grease formulations. GB standards alignment with ISO 6743 classifications is streamlining export qualification for domestic additive blenders. Precision manufacturing parks in Shenzhen and Suzhou are specifying NLGI 2 greases for automation equipment maintenance.
Japan
METI industrial decarbonization roadmaps are pulling lubricant procurement toward carbon-accounted supply chains for automotive and machinery exporters. JIS K 2220 certification requirements govern factory-fill specifications in Toyota City and Nagoya manufacturing corridors. Ionic liquid additive research partnerships between Osaka-based chemical institutes and drivetrain OEMs are advancing high-voltage compatible formulations.
India
BIS certification mandates for automotive supplier parks in Pune and Chennai are creating specification windows for additive packages meeting JIS K 2220 equivalents. Construction equipment fleets in Gujarat and Maharashtra prioritize mineral oil greases where procurement budgets emphasize unit cost over service interval extension. PLI scheme incentives for precision manufacturing are gradually upgrading maintenance chemistry specifications in tier-one supplier facilities.
Grease Additives Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent chemical conglomerates extend their additive offerings into adjacent functional fluid categories. The vendor base clusters around three strategic tiers: integrated petrochemical majors with captive feedstock positions, specialized lubricant additive houses with formulation IP libraries, and regional blending operations serving cost-sensitive aftermarket segments. M&A activity and technology licensing agreements represent the primary competitive vectors, with established players acquiring niche chemistry capabilities to fill portfolio gaps rather than pursuing greenfield R&D.
Among European-based chemical majors, BASF SE and Lanxess AG exemplify the integrated petrochemical archetype, leveraging polymer chemistry and sulfur-phosphorus expertise to anchor supply relationships with precision manufacturing OEMs. The Lubrizol Corp occupies a specialized position within the North American additive house tier, maintaining qualification protocols tailored to off-highway equipment specifications. These three entities collectively represent the concentration of established dossier portfolios that advantage incumbents under ECHA substance evaluation timelines.
| Leading Market Players |
|---|
| Afton Chemical Corp |
| BASF SE |
| Clariant AG |
| Croda International plc |
| Evonik Industries AG |
| The Lubrizol Corp |
| Lanxess AG |
| RT Vanderbilt Holding Co Inc |
| Shamrock Technologies Inc |
| Others |
Supply & Pricing Matrix
Factory-fill certification tiers bifurcate the market into specification-grade premiums and commodity aftermarket volumes, with REACH-compliant reduced-zinc formulations commanding threefold per-kilogram pricing over mineral-oil-based maintenance greases while concentrating procurement leverage among German and Japanese automotive OEMs.
Pricing Analysis
Distributor margins absorb the primary margin compression as additive suppliers face zinc dialkyldithiophosphate feedstock volatility. A three-tier pricing structure across premium, standard, and economy levels separates ionic liquid-enhanced EV formulations from sulfur-phosphorus heavy-load chemistry and mineral-oil construction fleet products. Cost compression in the commodity tier intensifies because Indian and Brazilian procurement budgets prioritize unit cost over service interval extension. General manufacturing maintenance departments exhibit the highest price sensitivity, while aerospace MIL-PRF-23827 certified contracts tolerate minimal negotiation.
Supply Chain Analysis
Phosphorus and zinc chemical feedstock supply rests on Chinese mining operations and Moroccan phosphate rock processing, with European sulfur-phosphorus chemistry specialists drawing from regional petrochemical complexes. Synthetic ester biodegradable base stock production concentrates in Germany, the United States, and Zhejiang province facilities. Single-source vulnerability in phosphorus commodity markets exposes additive blenders to annual contract pricing destabilization. Distribution runs through specialized lubricant distributors serving off-highway OEMs and direct factory-fill agreements with automotive manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The grease additives market functions as a stable compounder anchored by irreversible regulatory tightening on chemical disclosure and biodegradability that perpetually refreshes reformulation demand.
For Market Incumbents: Deploy backward integration into phosphorus and zinc feedstock streams to insulate margin structures from commodity volatility. BASF SE and Lanxess AG should accelerate ECHA dossier extensions for ionic liquid chemistries before evaluation timelines extend, while locking multi-site factory-fill contracts with German automotive OEMs through integrated fluid analysis programs that substitute technical service bundling for pure price competition. For New Entrants and Emerging Players: Direct-to-OEM digital qualification platforms bypass incumbent distributor relationships and compress customer acquisition costs in the specification-grade segment. White-space opportunity concentrates in Indian BIS-certified automotive supplier parks where JIS K 2220 equivalent formulations face limited qualified competition, and in biodegradable base stock certification for EU Green Deal municipal fleet procurement in France and Germany. For Investors and Strategic Acquirers: Consolidation pressure builds where ECHA registration portfolios cluster among established European chemical conglomerates, extending novel chemistry commercialization timelines beyond specialized entrant capital endurance. The five-to-ten-year viability window favors additive houses with captive synthetic ester capacity and established OEM qualification protocols. Acquisition target archetype: regional blending operations with BIS or JIS certification assets in underpenetrated manufacturing corridors. Monitor ECHA substance evaluation timeline extensions as the critical inflection signal for incumbent pricing power expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Feedstock | Captive phosphate rock processing insulates BASF SE and Lanxess AG from Moroccan supply volatility. |
| Ionic Liquid Chemistry R&D Partnerships | Osaka-based chemical institutes collaborating with Toyota advance high-voltage compatible formulations for EV reduction gearboxes. |
| BIS Certification Investment in India | Pune and Chennai automotive supplier parks create factory-fill specification windows for qualified additive packages. |
| Synthetic Ester Capacity Expansion | Zhejiang province bio-refinery buildout enables biodegradable grease formulations meeting EU Green Deal procurement mandates. |
| Integrated Fluid Analysis Program Launch | Nevada mining fleet automation concentrates volume with suppliers offering predictive maintenance diagnostics alongside product. |
Research Methodology
Multiple input streams — executive interviews with lubricant blender procurement leads, technical discussions with automotive OEM specification engineers, and validation sessions with mining fleet maintenance directors — were reconciled against customs trade data, ACC and Cefic industry reports, and SEC 10-K filings from listed chemical conglomerates. Bottom-up volume modeling across extreme pressure, anti-wear, and biodegradable additive categories was cross-checked against top-down market sizing derived from NLGI consistency grade production statistics and ASTM D2265 certification records.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through segmented modeling by product type, application, base oil chemistry, and end-user procurement tier. CAGRs were derived from regression analysis of historical factory-fill specification adoption rates and replacement cycle extension trends in mining and construction equipment fleets. Industry-specific forecast inputs incorporated REACH substance evaluation timeline probabilities and electric vehicle drivetrain thermal stability specification trajectories.
The model assumes a particular technology adoption path; alternative pathways for ionic liquid grease additives would alter the outlook if high-voltage compatibility standards shift toward solid lubricant polymer matrices. Forecasts reflect assumptions on regulatory enforcement intensity for EPA Safer Choice and EU Green Deal procurement mandates. A small set of named triggers — ECHA dossier cost inflation, phosphorus commodity price spikes, and OEM factory-fill centralization — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Octane Improver Fuel Additives Market
Additives
Polyoxyethylene Sorbitan Monostearate Market
Additives
Encapsulated Citric Acid Market
Additives
Drilling Fluid Additives Market
Additives
China Citric Acid Market
Additives
United States Betaine Market
Additives
Canada Anti-Caking Market
Additives
Volatile Corrosion Inhibitors Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
Global Glass Additives Market
Additives
Dipotassium Guanylate Market
Additives
Ballast Tank Corrosion Inhibitors Market
Additives
Cosmetic Grade Color Additives Market
Additives
Caprylyl Glycol Market
Additives
Anti-Wear Additives Market
Additives
Combustion Clean-Up Additives for High-Mileage Fleets Market