
 Global PMMA Microspheres Market | 2026-2036
Global PMMA Microspheres Market Size, Share, and Industry Trends Forecast 2026-2036
Global PMMA Microspheres Market Foresight
Multi-source procurement for specialty polymer feedstocks is expanding as buyers reduce reliance on single-plant methyl methacrylate suppliers. Kuraray Co., Ltd. leverages captive acrylate production to secure cost-stable supply chains for its microsphere divisions. Matsumoto Yushi-Seiyaku Co., Ltd. anchors its position through decades of accumulated process knowledge in suspension polymerization. Cospheric LLC specializes in narrow particle-size distributions for aerospace and diagnostic applications where batch consistency commands premium positioning.
PMMA microspheres are spherical polymer particles synthesized from methyl methacrylate monomer, typically ranging from one micron to several hundred microns in diameter, manufactured through emulsion, suspension, or dispersion polymerization routes. These particles deliver controlled light diffusion, reduced density, and tunable surface chemistry for applications spanning biomedical carriers to reflective coatings. Solid microspheres currently dominate volume consumption in adhesives and sealants where load-bearing integrity matters, while functionalized variants capture disproportionate margin pools in pharmaceutical targeting applications. Emulsion polymerization leads technology deployment for sub-ten-micron biomedical grades, whereas suspension routes sustain economics in larger-diameter industrial segments.
REACH registration requirements under ECHA govern monomer purity and residual levels for European market access, while FDA biocompatibility ISO 10993 testing protocols shape qualification pathways for device-integrated microspheres in the United States. EPA emissions standards for acrylic monomer production additionally influence capital allocation decisions for North American manufacturing expansions. Stakeholders must monitor evolving MDR classification rules in Europe, as reclassified implantable devices could trigger additional clinical data requirements that reshape supplier qualification timelines and R&D budgets.
Market Dynamics
Pharmaceutical manufacturers are accelerating functionalized microsphere adoption for controlled-release drug delivery, tightening purity specifications across biomedical-grade supply chains and compressing qualification timelines for new material entrants.
Growth Catalysts
- MDR Reclassification Pressure:European Medical Device Regulation is elevating clinical data requirements for implantable carriers, pulling demand toward pre-qualified PMMA suppliers with established ISO 10993 documentation.
- Precision Polymer Processing:German medical device clusters are concentrating procurement among suppliers capable of sub-ten-micron emulsion polymerization with batch-to-batch consistency guarantees.
- Controlled-Release Formulations:Sustained-release oncology and ophthalmic therapies are expanding addressable volume for surface-functionalized microspheres with tunable degradation profiles.
Market Restraints
- Methyl Methacrylate Feedstock Concentration:Single-plant MMA supplier dependence in North America and Asia creates margin volatility when force majeure events disrupt monomer availability.
- REACH Registration Burden:ECHA monomer purity and residual-level documentation requirements extend European market entry timelines by twelve to eighteen months for new entrants.
- Bioresorbable Polymer Substitution:Polylactic acid and polycaprolactone microspheres are capturing select drug-delivery applications where complete degradation outweighs mechanical durability requirements.
Strategic Opportunities
- Indian CDMO Expansion:Contract development and manufacturing organizations in Hyderabad and Bangalore are building sterile microsphere formulation capabilities to serve export markets.
- Dual-Carbon Manufacturing Incentives:China's MIIT green polymer guidelines are subsidizing solvent-recovery and energy-efficient suspension polymerization retrofits.
- Diagnostic Assay Miniaturization:Lateral-flow and microfluidic platforms are adopting narrow-distribution PMMA particles for optical encoding and magnetic separation functions.
Industry Challenges
- Suspension Polymerization Expertise Scarcity:Decades of accumulated process knowledge at specialized Japanese and European manufacturers creates recruitment bottlenecks for competitors scaling comparable capabilities.
- Biocompatibility Certification Timelines:FDA ISO 10993 cytotoxicity and sensitization testing protocols extend product qualification cycles, delaying revenue recognition for new biomedical-grade formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PMMA Microspheres Market |
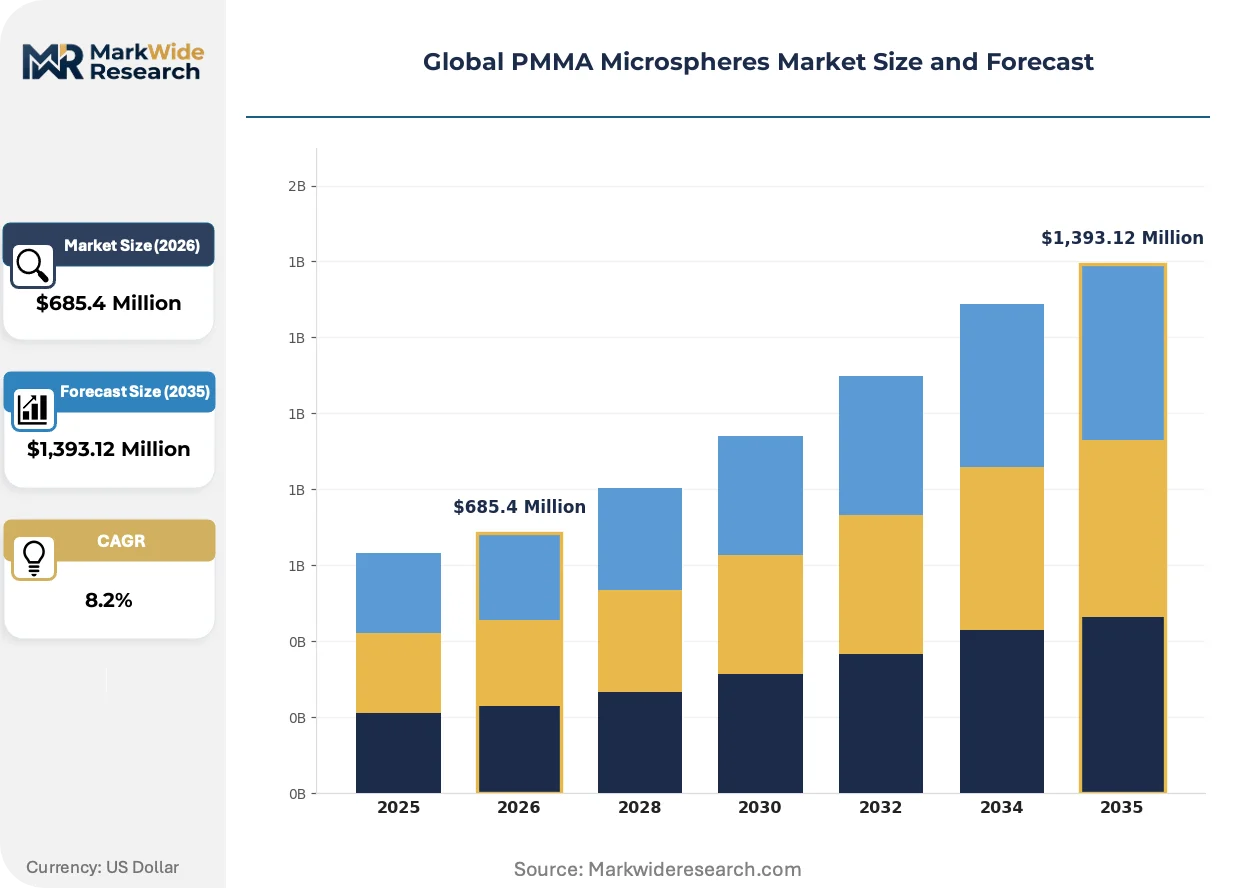
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hollow Microspheres, Solid Microspheres, Modified Microspheres, Porous Microspheres, Functionalized Microspheres Technology: Emulsion Polymerization, Suspension Polymerization, Dispersion Polymerization, Bulk Polymerization, Sol-Gel Process Application: Biomedical Devices, Adhesives & Sealants, Coatings, Cosmetics & Personal Care, Paints End User Industry: Pharmaceutical Manufacturers, Automotive Suppliers, Construction Firms, Electronics Producers, Packaging Companies |
| Companies Covered | Nippon Shokubai Co., Ltd., Kuraray Co., Ltd., Trinseo, Cospheric LLC, Microbeads AS, Polysciences Inc., Matsumoto Yushi-Seiyaku Co., Ltd., Sekisui Kasei Co., Ltd., Imperial Microspheres, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PMMA Microspheres Market Shifts & Advancements
Surface chemistry engineering and particle-size distribution control are converging to enable next-generation therapeutic and diagnostic applications, while regulatory data requirements are reshaping supplier qualification protocols across major markets.
Multifunctional surface modification is integrating reactive functional groups—carboxyl, amine, and epoxy terminations—onto PMMA microsphere architectures. Pharmaceutical formulators are adopting these platforms at accelerating pace for antibody conjugation and targeted payload attachment. This capability expansion is compressing development cycles for personalized medicine applications while elevating technical barriers for commodity producers.
REACH registration requirements under ECHA are tightening residual monomer and oligomer thresholds for European market access. Industrial consequence includes capital reallocation toward purification infrastructure and analytical testing capacity. Biomedical-grade microsphere segments are responding by consolidating procurement among established registrants with dossier completeness.
Buyer concentration among large pharmaceutical and medical device OEMs is compressing supplier qualification cycles and unbundling technical service from material supply contracts. Distributors with formulation support capabilities are displacing traditional resin brokers in North American and Western European channels. This pattern is most visible in Germany and Switzerland, where precision polymer processing clusters demand direct technical interface with material scientists.
Global PMMA Microspheres Market Segmentation
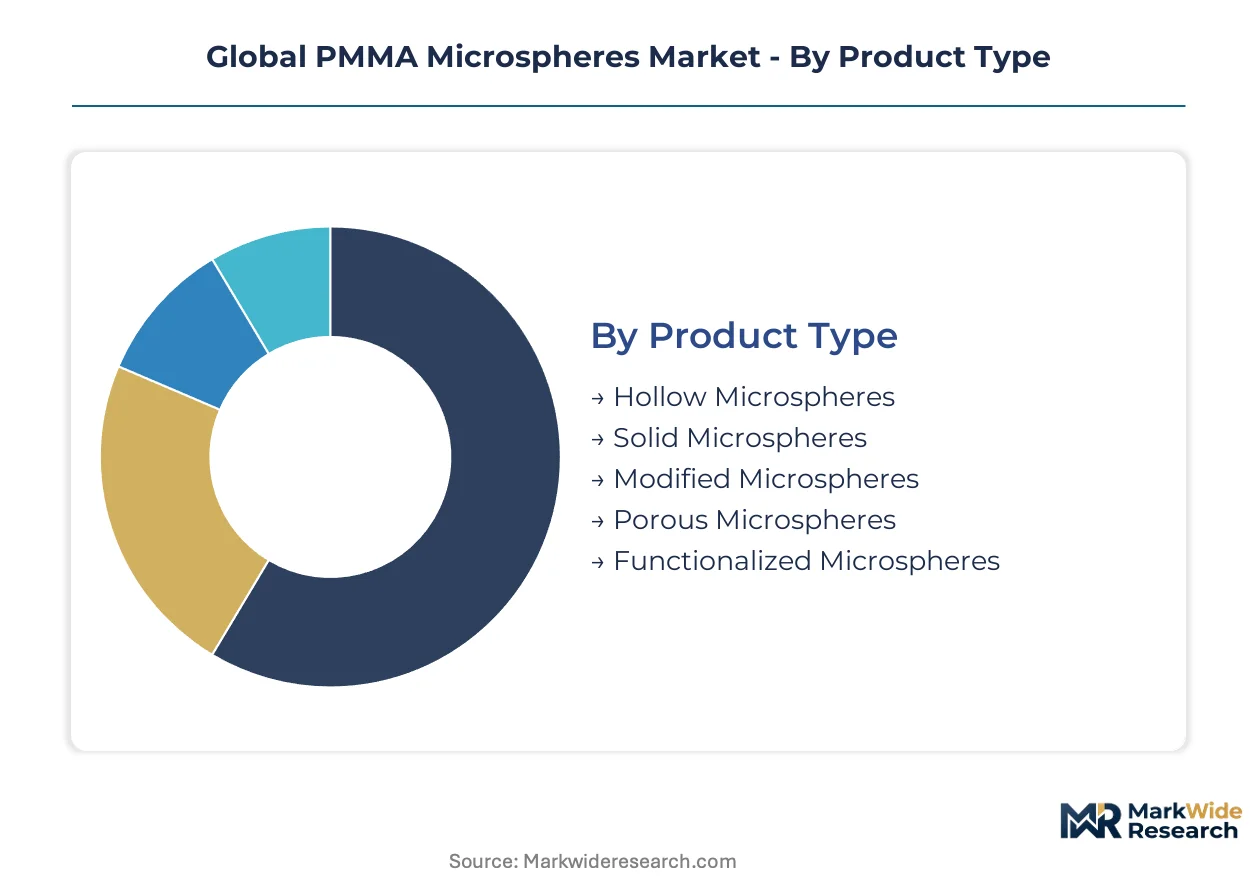
PMMA microsphere specifications diverge sharply across therapeutic, industrial, and cosmetic applications, with particle architecture and surface chemistry determining qualification pathways and margin capture. Manufacturers configure production routes around end-use purity requirements rather than pursuing commodity scale.
Product Type:
Structural configuration defines mechanical performance and functional versatility across application tiers.
- Solid Microspheres:Dense polymer matrices deliver load-bearing integrity in structural adhesives and sealants. Demand concentrates among German automotive suppliers seeking batch consistency for crash-resistant bonding applications. REACH-registered producers capture premium positioning through documented residual monomer compliance.
- Functionalized Microspheres:Surface-engineered architectures with carboxyl, amine, or epoxy terminations enable antibody conjugation and targeted drug attachment. Pharmaceutical manufacturers in Switzerland and Massachusetts are accelerating procurement for oncology and ophthalmic controlled-release formulations. FDA ISO 10993 documentation requirements compress supplier qualification timelines toward established registrants.
- Hollow Microspheres:Encapsulated gas cores reduce composite density for aerospace and marine coatings. Japanese producers dominate sub-50-micron specifications through accumulated suspension polymerization expertise.
- Modified Microspheres:Chemically altered surfaces or blended compositions address niche compatibility requirements in electronics potting compounds. South Korean display panel manufacturers drive specifications for optical clarity.
- Porous Microspheres:Interconnected void structures enable high surface-area drug loading and tissue scaffolding applications. Swiss medical device clusters concentrate procurement for orthopedic filler applications.
Solid microspheres lead on scale; functionalized variants lead on momentum.
Technology:
Polymerization route selection locks in particle-size distribution, purity ceiling, and capital intensity for decades.
- Emulsion Polymerization:Aqueous-phase synthesis achieves sub-ten-micron diameters with narrow distribution control. Biomedical-grade production in Germany and Japan concentrates here for parenteral drug delivery applications. ECHA residual monomer thresholds drive capital allocation toward purification infrastructure.
- Suspension Polymerization:Bead-forming in aqueous suspension sustains economics for 50-500 micron industrial grades. Matsumoto Yushi-Seiyaku and European specialists anchor supply through decades of accumulated process knowledge. Automotive adhesives and construction sealants represent volume anchors.
- Dispersion Polymerization:Organic-phase precipitation enables intermediate sizes with controlled porosity. Cosmetics manufacturers in France leverage this route for optical diffusion in premium skincare formulations.
- Bulk Polymerization:Mass polymerization without dispersing medium suits large-diameter spheres for grinding media and specialty fillers. Chinese producers are expanding capacity under MIIT green polymer guidelines.
- Sol-Gel Process:Hydrolytic condensation creates hybrid organic-inorganic architectures for diagnostic assay applications. Microfluidic platform developers in California and Bangalore evaluate these materials for magnetic separation functions.
Suspension polymerization retains volume dominance; emulsion routes are climbing the fastest on biomedical specification premiums.
Application:
End-use performance requirements fragment the supply base across regulated and industrial channels.
- Biomedical Devices:Implantable and injectable carriers demand ISO 10993 cytotoxicity, sensitization, and degradation documentation. European MDR reclassification is elevating clinical data requirements, consolidating procurement among pre-qualified suppliers with established dossiers.
- Adhesives & Sealants:Structural bonding applications prioritize compressive strength and thermal stability over purity. German automotive clusters specify sub-ten-micron grades for crash-resistant assembly.
- Coatings:Light diffusion and anti-slip functionality drive specifications in architectural and marine paints. South Korean shipbuilders procure hollow microspheres for buoyant barrier coatings.
- Cosmetics & Personal Care:Optical blurring and tactile enhancement guide particle-size selection. French and Italian formulators dominate premium positioning through narrow-distribution sourcing.
- Paints:Matting agents and rheology modifiers consume commodity-grade solid spheres. Chinese construction activity supports regional production economics.
Adhesives and sealants anchor volume consumption; biomedical devices command the steepest expansion trajectory.
End User Industry:
Procurement sophistication and regulatory exposure determine supplier relationship structures.
- Pharmaceutical Manufacturers:Controlled-release formulation development requires direct technical interface with material scientists. Large oncology and ophthalmic developers are unbundling technical service from material supply, favoring distributors with formulation support capabilities.
- Automotive Suppliers:Crash-performance bonding specifications demand batch-to-batch consistency guarantees. German OEMs concentrate procurement among REACH-registered producers with sub-ten-micron emulsion capabilities.
- Construction Firms:Commodity-grade hollow spheres for lightweight concrete and insulation prioritize cost over distribution precision. Chinese and Indian infrastructure spending supports regional supply chains.
- Electronics Producers:Display panel and semiconductor packaging applications specify optical clarity and low ionic contamination. South Korean and Taiwanese manufacturers drive purity requirements.
- Packaging Companies:Anti-block and anti-slip additives for films and coatings consume solid microspheres at industrial scale. European flexible packaging converters face CSRD disclosure pressure on polymer sourcing.
Pharmaceutical manufacturers lead on specification intensity; automotive suppliers anchor industrial volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting capital toward jurisdictions where REACH-equivalent compliance costs remain lower, even as German and Swiss precision polymer clusters retain premium-tier biomedical procurement dominance through accumulated certification depth.
Germany
Automotive crash-resistant bonding specifications and ophthalmic controlled-release formulations drive parallel demand streams. ECHA REACH registration requirements for monomer purity extend qualification timelines for new material entrants. The Baden-Württemberg and North Rhine-Westphalia medical device corridors concentrate procurement among ISO 10993-documented suppliers with sub-ten-micron emulsion capabilities.
United States
FDA biocompatibility testing protocols and EPA emissions standards for acrylic monomer production shape capital allocation decisions. Massachusetts and California pharmaceutical clusters accelerate functionalized microsphere adoption for oncology sustained-release therapies. Precision polymer processing capabilities in the Northeast corridor support diagnostic assay miniaturization demand.
Japan
Accumulated suspension polymerization expertise accumulated over decades anchors supply for hollow microsphere aerospace specifications. METI industrial standards and PMDA pharmaceutical quality frameworks govern market access pathways. The Kansai and Chubu manufacturing belts sustain batch consistency guarantees for narrow particle-size distribution requirements.
China
MIIT green polymer guidelines subsidize solvent-recovery retrofits in suspension polymerization operations. Yangtze River Delta and Pearl River Delta chemical parks expand bulk polymerization capacity for grinding media and specialty filler segments. Domestic pharmaceutical manufacturers build captive microsphere formulation capabilities for controlled-release generics export.
India
Hyderabad and Bangalore contract development organizations construct sterile microsphere formulation infrastructure for European and North American export markets. CDSCO quality frameworks and PLI scheme incentives redirect investment toward biomedical-grade production. The Maharashtra chemical corridor evaluates emulsion polymerization technology licensing for sub-ten-micron pharmaceutical grades.
Global PMMA Microspheres Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue functionalized biomedical grades where certification depth creates defensive moats. Market structure concentrates around Japanese and European specialists with decades of accumulated process knowledge, while North American and Chinese players scale industrial-grade volumes. Two strategic archetypes dominate: captive acrylate-integrated conglomerates securing feedstock stability, and suspension polymerization specialists commanding premium positioning through batch consistency guarantees. Competitive moves center on backward integration into methyl methacrylate supply and technology licensing partnerships for emulsion route capabilities.
Among Japanese specialists, Matsumoto Yushi-Seiyaku Co., Ltd. and Sekisui Kasei Co., Ltd. exemplify the accumulated expertise archetype, while Kuraray Co., Ltd. represents captive acrylate integration. These three anchors sit within a tier where process knowledge scarcity creates recruitment bottlenecks for competitors attempting comparable scale. Cospheric LLC occupies a position among North American narrow-distribution specialists serving aerospace and diagnostic applications where batch consistency commands premium positioning.
| Leading Market Players |
|---|
| Nippon Shokubai Co., Ltd. |
| Kuraray Co., Ltd. |
| Trinseo |
| Cospheric LLC |
| Microbeads AS |
| Polysciences Inc. |
| Matsumoto Yushi-Seiyaku Co., Ltd. |
| Sekisui Kasei Co., Ltd. |
| Imperial Microspheres |
| Others |
Supply & Pricing Matrix
Large pharmaceutical and medical device OEMs are consolidating procurement among pre-qualified suppliers, compressing channel margins and unbundling technical service from material supply contracts. This buyer concentration rewards established REACH registrants and ISO 10993-documented producers with pricing power, while squeezing commodity distributors.
Pricing Analysis
Distributor margins for biomedical-grade PMMA microspheres are compressing as large pharmaceutical formulators negotiate direct supply agreements with emulsion polymerization specialists. Pricing stratifies across FDA-documented premium grades, REACH-registered standard tiers, and industrial commodity levels, with certification depth commanding 40-60% spreads. Cost compression in industrial hollow microspheres is intensifying because Chinese bulk polymerization expansions under MIIT guidelines are adding regional capacity. Automotive adhesive buyers in Germany show lowest price sensitivity due to crash-performance liability exposure, while construction firms in India prioritize cost over distribution precision.
Supply Chain Analysis
Methyl methacrylate monomer supply rests on concentrated petrochemical complexes in Germany, Japan, and South Korea, with Kuraray and Mitsubishi Chemical anchoring regional feedstock availability. Specialty suspension polymerization expertise concentrates among Matsumoto Yushi-Seiyaku and European specialists with decades of accumulated process knowledge. Single-plant MMA supplier dependence in North America creates force majeure vulnerability when hurricane disruptions hit Gulf Coast production. Distribution runs through technical distributors with formulation support capabilities in Germany and Switzerland, displacing traditional resin brokers in premium biomedical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PMMA microspheres market represents a late-cycle quality story as pharmaceutical manufacturers accelerate procurement of surface-functionalized grades for controlled-release oncology and ophthalmic therapies.
For Market Incumbents: Cement defensive positioning by deepening backward integration into captive methyl methacrylate production and expanding sub-ten-micron emulsion capacity in Baden-Württemberg or North Rhine-Westphalia. Bioresorbable polymer substitution from polylactic acid microspheres threatens select drug-delivery applications; counter by accelerating ISO 10993 documentation depth for implantable grades ahead of European MDR reclassification deadlines. For New Entrants and Emerging Players: Capture white-space opportunity in Indian CDMO sterile formulation infrastructure, where Hyderabad and Bangalore contract developers are building export-facing capabilities without legacy suspension polymerization expertise requirements. Diagnostic assay miniaturization for lateral-flow and microfluidic platforms offers penetrable entry with lower certification barriers than implantable biomedical grades. Partner with German precision polymer clusters for technology licensing rather than greenfield emulsion route development. For Investors and Strategic Acquirers: Pharmaceutical CDMOs with sterile microsphere formulation capabilities are the most active acquirer in this space, seeking backward integration into material supply. Five-to-ten year viability hinges on regulatory data asset accumulation rather than commodity scale. Target acquisition archetype: Japanese or European suspension polymerization specialists with decades of batch consistency documentation and narrow particle-size distribution process knowledge. Watch FDA ISO 10993 cytotoxicity testing protocol revisions as inflection signal for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MMA Feedstock | Kuraray's captive acrylate production secures cost-stable supply chains against force majeure disruptions. |
| Emulsion Polymerization Capacity Expansion | Sub-ten-micron biomedical-grade production in Germany serves ophthalmic controlled-release formulation demand. |
| ISO 10993 Documentation Investment | Pre-qualified suppliers capture MDR reclassification-driven procurement consolidation among implantable device manufacturers. |
| CDMO Sterile Formulation Partnership | Indian contract developers in Hyderabad build export-facing infrastructure for European and North American pharmaceutical clients. |
| Surface Chemistry Engineering R&D | Carboxyl and amine functionalization capabilities enable antibody conjugation for personalized medicine applications. |
Research Methodology
Coverage spans Germany, United States, Japan, China, and India, with primary inputs from each regional cluster. The research combines structured interviews with pharmaceutical formulation scientists, medical device procurement managers, automotive adhesive specification engineers, and suspension polymerization plant operators with secondary validation from ECHA REACH registration databases, FDA 510(k) filings, SEC 10-K chemical sector disclosures, and MIIT green polymer guideline publications. Bottom-up volume modeling from application-specific consumption rates triangulates against top-down methyl methacrylate derivative demand allocations.
Granularity extends to five product type segments, five polymerization technology routes, five application categories, and five end-user industries across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by purity-tier pricing differentials. Forecast inputs include pharmaceutical pipeline analysis for controlled-release formulations, automotive lightweighting content-per-vehicle assumptions, and diagnostic assay platform adoption curves for narrow-distribution particle specifications.
Force majeure events in methyl methacrylate supply, REACH residual monomer threshold revisions, and bioresorbable polymer substitution acceleration are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about regulatory pathway timelines and OEM qualification cycle durations. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Organic Scintillators Market
Specialty Materials
Elastic Films Market
Specialty Materials
Nitrocellulose Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Absorbent Booms and Socks Market
Specialty Materials
Asia-Pacific Green Sic Market
Specialty Materials
Europe Textile Films Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
South America Polyether Ether Ketone (Peek) Market
Specialty Materials
Global Synthetic Zeolite Market
Specialty Materials
Solar Backsheet Films Market
Specialty Materials
Magnesium Fluoride Market
Specialty Materials
Water Soluble Film Market
Specialty Materials
Cellulose Derivative Excipient Market