
 Niobium Pentoxide Market | 2026-2036
Niobium Pentoxide Market Size, Share, and Industry Trends Forecast 2026-2036
Niobium Pentoxide Market Foresight
High-purity refining techniques are reconfiguring how niobium pentoxide integrates into superconductor wire and advanced ceramic supply chains. CBMM leverages captive pyrochlore mining in Brazil to sustain upstream cost advantages across the value chain. Neo Performance Materials anchors its position through specialized separation chemistry for electronics-grade material. JX Nippon Mining & Metals Corporation competes on metallurgical consistency for Japanese superconductor manufacturers.
Niobium pentoxide is a white crystalline oxide of niobium with the chemical formula Nb₂O₅, typically produced via hydrometallurgical extraction from pyrochlore ore followed by calcination at temperatures exceeding 800°C to achieve target purity levels. The compound serves primarily as a precursor for ferroelectric ceramics, optical coatings, and niobium metal reduction for superconducting alloys. High Purity Niobium Pentoxide dominates value capture due to stringent specifications in semiconductor and superconductor applications where trace element tolerance sits below ten parts per million. Superconductors represents the fastest-growing application segment as national laboratories and medical imaging OEMs scale niobium-titanium and niobium-tin wire production for next-generation magnets.
Brazil's National Mining Agency, China's Ministry of Ecology and Environment, and the EU REACH framework collectively shape extraction licensing, export quotas, and chemical registration requirements for niobium compounds. These regulations tighten market access for unqualified producers while concentrating supply relationships with vertically integrated refiners holding certified environmental and purity credentials. Stakeholders must monitor evolving critical minerals designations in multiple jurisdictions as these classifications increasingly determine financing availability and offtake priority for strategic material projects.
Market Dynamics
High-purity niobium pentoxide supply is consolidating around vertically integrated pyrochlore processors in Brazil, as semiconductor and superconductor OEMs impose sub-10 ppm trace-element specifications that disqualify secondary refiners lacking captive ore access.
Growth Catalysts
- Superconductor wire demand:MRI magnet manufacturers and particle accelerator projects are scaling niobium-titanium and niobium-tin alloy production, pulling high-purity Nb₂O₅ through long-term offtake contracts.
- China's dual carbon goals:Stricter rare earth and critical mineral processing standards under MEE oversight are accelerating substitution of unqualified suppliers with certified refiners holding ISO 14001 and REACH registration.
- Hydrometallurgical extraction advances:Solvent extraction and ion-exchange purification methods are lowering energy intensity in high-purity grade production, expanding viable feedstock beyond prime pyrochlore to lower-grade concentrates.
Market Restraints
- Pyrochlore supply concentration:Over 90% of niobium ore reserves sit in Brazil's Minas Gerais belt, creating single-source vulnerability for downstream processors lacking diversified offtake agreements.
- Fluorine reagent cost volatility:Hydrometallurgical refining relies on hydrofluoric acid for tantalum-niobium separation, with pricing tied to fluorspar mining disruptions and Chinese export quota fluctuations.
- Tantalum-niobium substitution in capacitors:Polymer aluminum and niobium monoxide technologies are displacing niobium pentoxide-based ceramic capacitors in consumer electronics voltage regulation applications.
Strategic Opportunities
- Underpenetrated Indian electronics manufacturing:India's PLI scheme for semiconductor and display fabrication is attracting specialty chemical investments, creating first-mover advantage for high-purity oxide suppliers establishing local blending facilities.
- Solid-state battery electrolyte applications:Niobium pentoxide-doped lithium lanthanum zirconate garnets are emerging as oxide-ceramic solid electrolyte precursors for next-generation lithium-metal batteries.
- EU Critical Raw Materials Act alignment:Strategic stockpiling mandates and domestic processing incentives are opening offtake channels for qualified suppliers meeting CSRD disclosure and REACH SVHC compliance thresholds.
Industry Challenges
- High-purity chemist talent scarcity:Separation chemistry expertise for sub-10 ppm impurity control is concentrated among retiring specialists at legacy tantalum-niobium refiners, constraining quality assurance team expansion.
- Superconductor OEM qualification timelines:Medical imaging and accelerator magnet manufacturers require 18-36 month certification cycles for new niobium pentoxide lots, locking out unproven suppliers from premium tier supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Niobium Pentoxide Market |
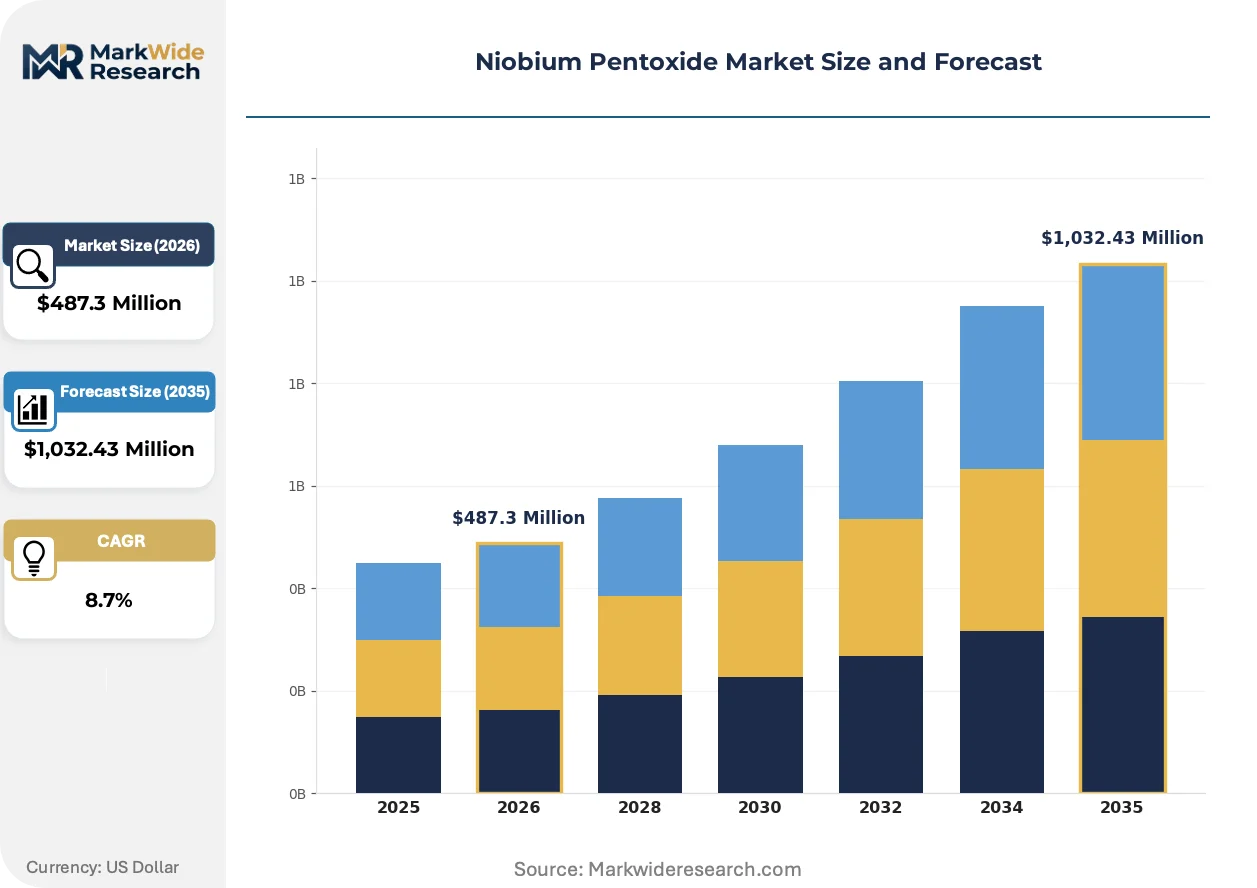
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity Niobium Pentoxide, Niobium Oxide, Niobium Titanium Alloy, Niobium Powder Application: Ceramics, Electronics, Steelmaking, Superconductors End User: Semiconductor Industry, Aerospace, Defense, Automotive Parts Distribution Channel: Direct Sales, Online Retail, Distributors, Marketplaces |
| Companies Covered | Merck Group, F&X Electromaterials Limited, CBMM, JSC Solikamsk Magnesium Plant, Neo Performance Materials, AMG, Taki Chemical Co., Ltd, JX Nippon Mining & Metals Corporation, XIMEI Resources Holding Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Niobium Pentoxide Market Shifts & Advancements
Refining technology and end-use specifications are diverging sharply between commodity-grade oxide for ferroelectric ceramics and ultra-high-purity material for superconductor precursor applications, splitting the market into distinct qualification tiers.
Solvent extraction circuits with mixer-settler cascades are migrating from batch hydrometallurgical processing toward continuous counter-current configurations. Superconductor wire producers in Japan and Germany are demanding lot-to-lot consistency below 5 ppm total metallic impurities, forcing refiners to retrofit legacy precipitation-calcination lines with real-time ICP-MS feedback loops. This migration from batch to continuous processing is compressing qualification timelines for new supply sources while raising capital barriers for market entry.
REACH authorization requirements for niobium compounds are tightening substance registration obligations across EU member states. ECHA's 2023 update to the Candidate List of Substances of Very High Concern introduced additional documentation burdens for niobium pentoxide importers, particularly affecting electronics-grade material destined for German automotive sensor manufacturers. The regulation is pushing non-EU refiners to establish EU-based legal entities and analytical laboratories to maintain market access.
Long-term offtake contracting is displacing spot purchasing for high-purity grades. Superconductor OEMs are consolidating supplier panels to three qualified sources per geography, replacing the previous five-to-seven vendor fragmentation. Japanese magnet manufacturers pioneered this concentration, with European particle physics laboratories now following suit through framework agreements indexed to pyrochlore concentrate pricing rather than oxide spot markets.
Niobium Pentoxide Market Segmentation
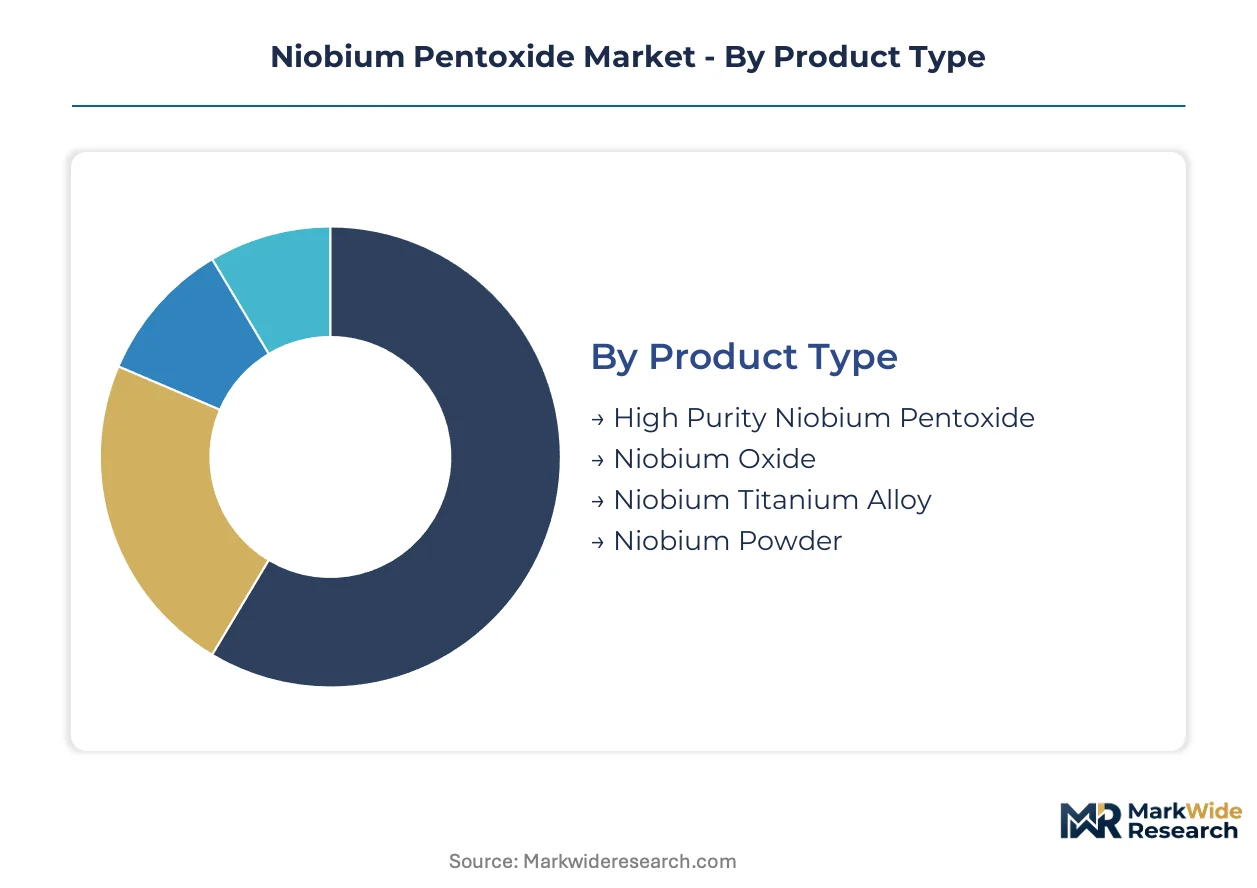
Niobium pentoxide segmentation reflects divergent purity requirements across superconductor wire, ferroelectric ceramics, and steel alloying applications. Each tier demands distinct hydrometallurgical processing intensity and trace-element tolerance thresholds that reshape supplier qualification barriers.
Product Type:
Mature commodity grades anchor volume throughput while emerging specialty alloys capture technology premiums in next-generation magnet systems.
- High Purity Niobium Pentoxide:Electronic-grade material with total metallic impurities below 10 ppm, produced via solvent extraction and ion-exchange purification. Demand concentrates in Japanese and German superconductor wire manufacturers scaling niobium-titanium alloy production for MRI magnets and particle accelerators. Sub-5 ppm lot-to-lot consistency requirements lock out secondary refiners lacking real-time ICP-MS feedback loops.
- Niobium Titanium Alloy:Metallurgical intermediate combining niobium pentoxide reduction with titanium sponge in vacuum arc remelting furnaces. Superconductor OEMs in Japan's Tohoku region and Germany's Bavaria cluster dominate offtake through 36-month qualification contracts indexed to pyrochlore concentrate pricing.
- Niobium Oxide:Technical-grade precursor for ferroelectric ceramics and optical coatings with moderate purity tolerances.
- Niobium Powder:Reduced metal form serving additive manufacturing feedstock and specialty welding applications.
High Purity Niobium Pentoxide retains volume leadership; Niobium Titanium Alloy holds the steepest expansion curve.
Application:
Cost tiers separate commodity-scale steel alloying from premium-priced superconductor precursor demand with 10x processing intensity differentials.
- Superconductors:Niobium-titanium and niobium-tin wire production for MRI magnets and accelerator systems demands the highest purity grades. National laboratories in Switzerland, Germany, and the United States consolidate procurement through framework agreements with three qualified suppliers per geography.
- Ceramics:Ferroelectric capacitor and piezoelectric sensor manufacturing consumes standard-purity oxide with 50-100 ppm trace element tolerance. Brazilian and Chinese ceramic manufacturers dominate volume offtake for consumer electronics substrates.
- Electronics:Semiconductor-grade material for gate dielectrics and diffusion barriers.
- Steelmaking:Microalloying additive for high-strength low-alloy steels in automotive and pipeline applications.
Steelmaking retains volume leadership; Superconductors holds the steepest expansion curve.
End User:
Customer type fragmentation splits between qualified OEMs with 18-36 month certification cycles and spot purchasers in commodity segments.
- Semiconductor Industry:Wafer fabrication facilities and thin-film deposition equipment operators require REACH-registered, ECHA-compliant material with full SVHC documentation. German automotive sensor manufacturers drive documentation burden escalation through CSRD-aligned supply chain disclosure mandates.
- Aerospace:Superalloy and turbine blade manufacturers source niobium powder and oxide for creep-resistant nickel-base alloys. French and German engine OEMs impose AS9100 quality system requirements that filter out uncertified refiners.
- Defense:Strategic stockpiling programs and classified magnet applications.
- Automotive Parts:Exhaust system and structural steel microalloying.
Automotive Parts retains volume leadership; Semiconductor Industry holds the steepest expansion curve.
Distribution Channel:
Supply concentration favors direct relationships with vertically integrated Brazilian refiners over fragmented intermediary networks.
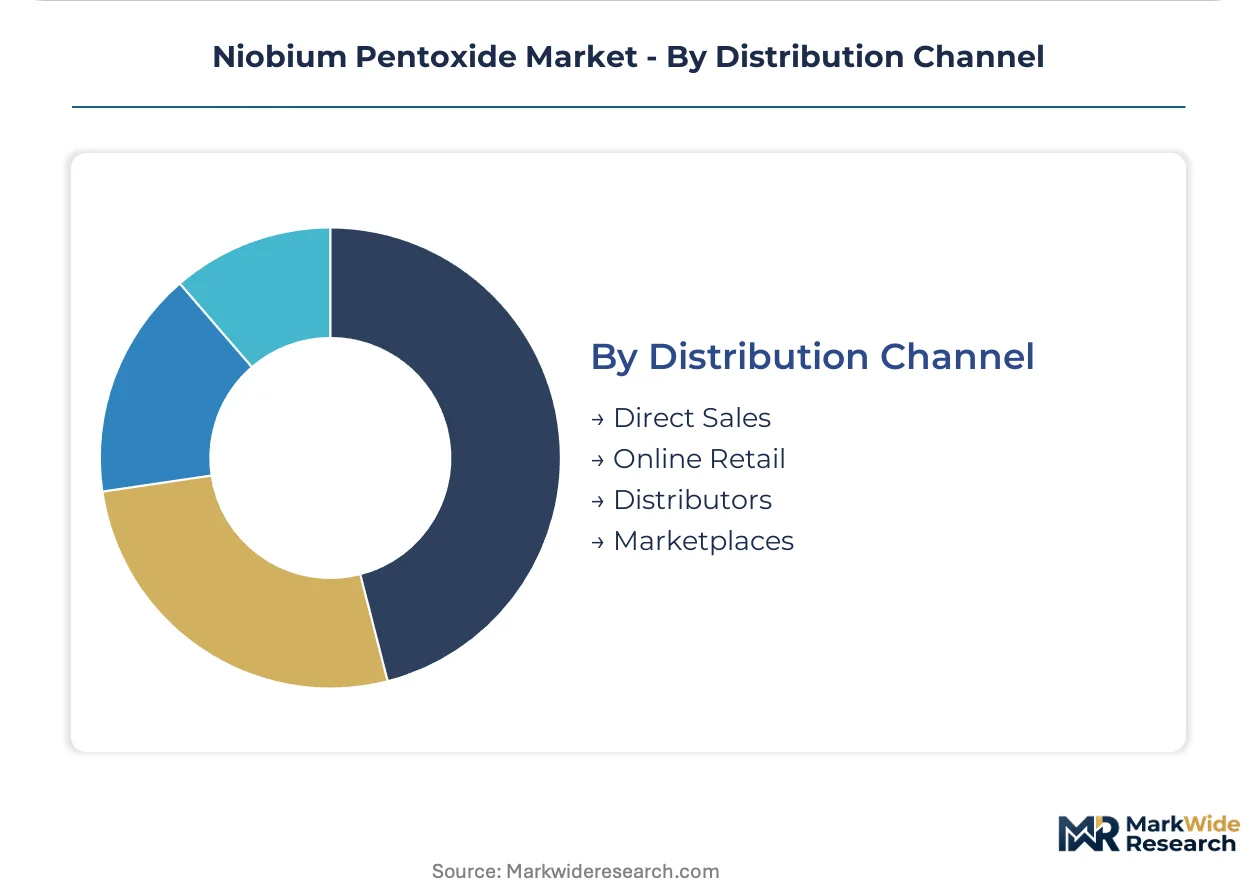
- Direct Sales:Long-term offtake contracts linking CBMM and other Minas Gerais-based processors to superconductor wire manufacturers. Japanese magnet producers pioneered this concentration model, now adopted by European particle physics laboratories.
- Distributors:Regional chemical distributors stock standard-purity grades for ceramics and steelmaking customers lacking direct refinery relationships.
- Online Retail:Small-lot technical sales for research institutions and additive manufacturing startups.
- Marketplaces:Spot trading platforms for commodity-grade material with relaxed purity specifications.
Direct Sales retains volume leadership; Distributors holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Superconductor OEMs and semiconductor fabricators concentrate procurement in four countries with distinct regulatory and industrial configurations. Each geography shapes supply access through critical minerals policy, environmental licensing, and specialized magnet manufacturing clusters.
Brazil
Minas Gerais hosts the Araxá pyrochlore mining belt where CBMM operates captive refining for global high-purity oxide supply. ANVISA and the National Mining Agency impose extraction licensing that filters out unqualified juniors. São Paulo's industrial corridor channels processed material toward export terminals serving Japanese and German superconductor manufacturers.
China
Domestic MRI magnet production and particle accelerator construction drive demand for electronics-grade niobium compounds. MEE oversight of rare earth and critical mineral processing standards under dual carbon goals is disqualifying uncertified refiners. Jiangxi and Hunan provinces concentrate hydrometallurgical capacity for tantalum-niobium separation serving domestic superconductor wire producers.
Japan
Tohoku region magnet manufacturers qualify niobium-titanium alloy feedstock through 36-month certification cycles indexed to pyrochlore concentrate pricing. METI's critical minerals strategy prioritizes long-term offtake security with Brazilian suppliers. Kobe and Osaka house thin-film deposition equipment operators requiring REACH-registered precursor material for semiconductor gate dielectrics.
Germany
Bavaria's particle physics laboratories consolidate procurement through framework agreements with three qualified suppliers per geography. ECHA's 2023 SVHC documentation update and CSRD-aligned supply chain disclosure mandates are escalating compliance burdens for non-EU refiners. Munich and Stuttgart automotive sensor manufacturers drive documentation requirements for electronics-grade material.
United States
National laboratories in Illinois and California scale niobium-tin wire production for next-generation accelerator magnets. EPA and Department of Energy critical minerals designations increasingly determine financing availability for strategic material projects. Texas and Arizona host emerging rare earth processing investments seeking to diversify pyrochlore supply dependence.
Niobium Pentoxide Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct qualification tiers. Brazilian vertically integrated refiners hold upstream pyrochlore access that downstream processors cannot replicate. Three archetypes dominate: captive miners with in-house refining, specialty chemical separators serving electronics-grade demand, and metallurgical processors converting oxide to superconductor alloys. Competitive moves concentrate on long-term offtake contracting and hydrometallurgical purification technology licensing.
Among Brazil-based integrated miners, CBMM anchors the upstream-controlled archetype through Minas Gerais pyrochlore access. Neo Performance Materials and JX Nippon Mining & Metals Corporation occupy positions within the specialty separation tier, with the former representing North American electronics-grade capability and the latter exemplifying Japanese metallurgical consistency standards for superconductor OEMs.
| Leading Market Players |
|---|
| Merck Group |
| F&X Electromaterials Limited |
| CBMM |
| JSC Solikamsk Magnesium Plant |
| Neo Performance Materials |
| AMG |
| Taki Chemical Co., Ltd |
| JX Nippon Mining & Metals Corporation |
| XIMEI Resources Holding Limited |
| Others |
Supply & Pricing Matrix
The Santos-Guarujá container corridor funnels processed niobium pentoxide from Minas Gerais refineries to Asian superconductor manufacturers, with freight cost volatility amplifying the pricing power of Brazilian integrated producers while forcing downstream buyers into long-term contract structures that insulate against spot concentrate swings.
Pricing Analysis
Cost-plus contracts indexed to pyrochlore concentrate pricing dominate high-purity grade procurement, with Japanese superconductor OEMs pioneering 36-month frameworks that transfer fluorspar and hydrofluoric acid cost exposure to refiners. Price differentiation hinges on lot-to-lot impurity consistency below 5 ppm and REACH SVHC documentation depth. Cost compression in standard-purity ceramics grades is intensifying as Chinese hydrometallurgical capacity expands, while superconductor wire manufacturers show minimal price sensitivity due to qualification lock-in effects.
Supply Chain Analysis
Contract manufacturing concentration rests with CBMM's captive Araxá refining complex, which feeds directly to Neo Performance Materials' Canadian separation circuits and JX Nippon's Japanese metallurgical processing lines. Raw material dependencies center on Brazilian pyrochlore, Chinese fluorspar for HF acid production, and German-made ICP-MS analytical equipment. Single-source vulnerability pervades the ore tier, with over 90% of reserves concentrated in Minas Gerais. Distribution runs through direct sales contracts for high-purity grades, while regional chemical distributors handle standard-purity ceramics feedstock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Superconductor magnet demand is accelerating market expansion beyond traditional ferroelectric applications, with China's dual carbon enforcement and EU Critical Raw Materials Act stockpiling mandates creating dual regulatory tailwinds that favor certified, vertically integrated suppliers.
For Market Incumbents: Pre-empt hydrometallurgical talent scarcity by acquiring retiring separation chemists from legacy tantalum-niobium refiners and embedding them into quality assurance teams. Secure captive fluorspar offtake or backward integration into HF acid production to insulate against Chinese export quota volatility. Lock in 5-year pyrochlore concentrate supply extensions before junior miners achieve ANVISA licensing. For New Entrants and Emerging Players: Pursue solid-state battery electrolyte precursors as the most penetrable white-space segment, where niobium pentoxide-doped lithium lanthanum zirconate garnets lack established supplier relationships and qualification timelines remain undefined. Target Indian electronics manufacturing zones under the PLI scheme for semiconductor fabrication, establishing local blending facilities before CBMM or Neo Performance Materials commit capital. Lead with REACH pre-registration and CSRD-aligned disclosure capabilities as the primary go-to-market wedge against unqualified Chinese competitors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified mining conglomerates with stranded niobium assets lacking downstream refining expertise or certification infrastructure. Five-to-ten year viability hinges on positioning ahead of national laboratory superconductor wire procurement cycles. Watch for ECHA SVHC list expansion signals that would trigger mandatory EU-based legal entity establishment and strain non-compliant refiners' market access.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Japanese magnet manufacturers lock in 36-month pyrochlore-indexed contracts to secure lot-to-lot consistency below 5 ppm. |
| Backward Integration | Refiners acquire captive fluorspar mining or HF acid production to hedge Chinese export quota volatility. |
| Green Manufacturing Transition | Solvent extraction circuit retrofits with continuous counter-current configurations reduce energy intensity for dual carbon compliance. |
| Joint Venture | Indian PLI scheme attracts specialty chemical partnerships for local high-purity oxide blending near semiconductor fabs. |
| Capacity Expansion | Real-time ICP-MS feedback loops expand qualified superconductor precursor output for MRI and accelerator magnet OEMs. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with hydrometallurgical plant managers, superconductor wire procurement leads at Japanese OEMs, Brazilian National Mining Agency licensing officers, and thin-film deposition equipment operators; and secondary validation through customs trade data, ANVISA extraction permit filings, ECHA REACH registration databases, and SEC 10-K disclosures from listed specialty chemical processors. Bottom-up capacity and offtake modeling triangulated against top-down end-use demand segmentation across superconductor, ceramics, and steelmaking applications.
Forecast inputs considered purity grade tier, end-use application intensity, regional regulatory cluster alignment, and OEM qualification status across the projection horizon. CAGRs derived from weighted average of annual capacity expansion announcements, national laboratory procurement pipeline visibility, and substitution elasticity estimates for tantalum-niobium capacitor technologies. Modeled variables included pyrochlore concentrate price trajectories, fluorspar supply disruption probabilities, and solid-state battery commercialization timelines.
Sensitivities concentrate around ECHA SVHC documentation escalation, Chinese MEE enforcement intensity under dual carbon goals, and superconductor OEM qualification cycle compression. Forecasts embed assumptions regarding ANVISA licensing continuity and Minas Gerais geological reserve stability. Quarterly review of Japanese magnet manufacturer procurement bulletins, EU Critical Raw Materials Act implementation guidance, and Indian PLI scheme beneficiary announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Open Cell Foam Market
Specialty Materials
Halloysite Market
Specialty Materials
Epoxy Encapsulation Material Market
Specialty Materials
Super Engineering Plastics Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Europe Microspheres Market
Specialty Materials
Metalized Biaxially Oriented Polypropylene Films Market
Specialty Materials
Gutta-Percha Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Super-Hard Material Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Global Cellulose Esters Market
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
Vegan Wax Market