
 Mica Sheet Market | 2026-2036
Mica Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Mica Sheet Market Insights
Project finance tied to critical mineral offtake agreements is reconfiguring competitive entry in mica sheet supply. Imerys S.A. leverages its integrated mining-to-processing footprint across European and Asian deposits. Von Roll Group anchors its position through specialized electrical insulation grades serving transformer and motor OEMs. Pamica Group Ltd. competes on synthetic mica capacity expansion aimed at high-temperature industrial applications.
Mica sheet consists of thin, flexible layers formed from phlogopite or muscovite crystal structures, typically bonded with silicone or epoxy resins to achieve dielectric strength exceeding 20 kV/mm and thermal stability above 500°C. These properties make it indispensable for electrical insulation, thermal management, and fire-resistant barriers across heavy industry. Natural mica dominates volume flows due to established mining infrastructure and lower raw material cost, while synthetic mica commands premium positioning in applications demanding zero iron content and consistent batch purity. The electronics application segment carries the fastest structural expansion as EV power electronics and battery thermal runaway protection multiply specification requirements.
EPA oversight of mining waste streams and OSHA silica exposure limits shape North American production economics, while REACH registration and RoHS substance restrictions govern European market access and product formulation. China's GB standards for electrical insulation materials and NMPA-aligned industrial chemical classifications create additional compliance layers for imported sheet products. Stakeholders must track evolving critical mineral designation debates, as mica's inclusion would trigger supply chain reporting obligations and strategic stockpile considerations across multiple jurisdictions.
Market Dynamics
Electric vehicle battery pack manufacturers are expanding mica sheet procurement for thermal barrier applications, creating a demand pull that is restructuring supply chain priorities across mining and processing tiers. This concentration of offtake volume is forcing capacity reallocation decisions at the deposit level.
Growth Catalysts
- REACH and RoHS compliance requirements:Tightening purity standards for electrical-grade mica in Europe are accelerating substitution away from lower-grade natural material toward certified synthetic alternatives.
- EV power electronics:Battery thermal runaway protection specifications are multiplying dielectric barrier layer counts in pack designs, directly expanding sheet consumption per vehicle.
- China:Domestic synthetic mica production scaling is serving Asia-Pacific electronics supply chains with shorter lead times and integrated processing.
Market Restraints
- Raw material concentration risk:Natural mica mining infrastructure clusters in specific deposit geographies, creating single-source exposure for unintegrated processors.
- OSHA silica exposure limits:North American production economics face compliance cost escalation for mining waste stream management and worker protection.
- Synthetic mica cost premium:Zero-iron batch consistency requirements command manufacturing process intensity that prices out cost-sensitive industrial insulation buyers.
Strategic Opportunities
- India:Underpenetrated domestic electrical equipment manufacturing is expanding import substitution programs for insulation materials under CEA and BIS alignment.
- High-temperature industrial applications:Furnace lining and metallurgical containment specifications are adopting synthetic mica for thermal shock resistance beyond natural material limits.
- Critical mineral designation debates:Inclusion of mica in strategic stockpile considerations across multiple jurisdictions would trigger supply chain reporting obligations and preferential procurement.
Industry Challenges
- Geologist and process engineer scarcity:Specialized talent for phlogopite deposit assessment and flake classification is concentrating at established mining houses.
- REACH registration timelines:European market access requires substance dossier completion that delays new entrant product launches by 18-24 months.
- Legacy equipment integration:Transformer and motor OEMs maintain qualified supplier lists that lock out uncertified sheet sources from maintenance contract flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mica Sheet Market |
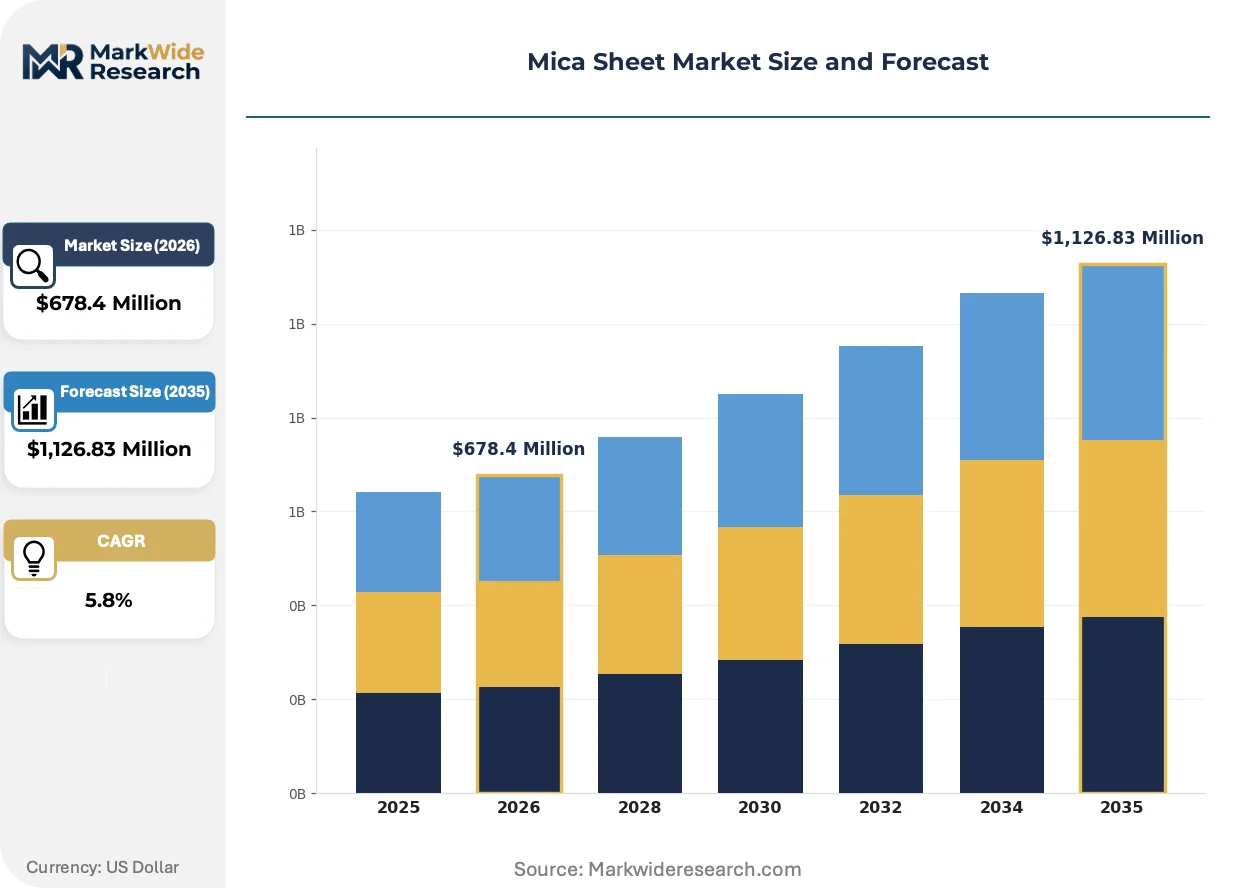
| Market Size in 2026 | $678.4 Million |
| Market Size in 2035 | $1,126.83 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Mica, Synthetic Mica, Mica Powder, Mica Flakes Application: Electronics, Construction, Cosmetics, Coatings End User: Manufacturers, Builders, Cosmetic Companies, Paint Producers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Von Roll Group, The Premier Mica Company, Imerys S.A., Pamica Group Ltd., Daruka International, Asheville Mica Company, Merck KGaA / SuSoNity, Cleveland Mica Co., Elmelin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mica Sheet Market Trends and Innovations
Digital process control and synthetic chemistry advances are compressing batch-to-batch variability in mica sheet production. These developments are enabling specification tightening that natural mining cannot match.
Fluorophlogopite synthetic mica is virtualizing traditional muscovite procurement in precision electrical applications. EV battery manufacturers in South Korea and Japan are qualifying synthetic sources for thermal barrier layers. This shift is virtualizing the historical cost advantage of natural flake deposits in high-purity segments.
China's GB standards for electrical insulation materials are tightening dielectric strength testing protocols. Domestic synthetic producers are capturing certification advantages over import competitors. The electronics application segment is responding with accelerated supplier qualification toward GB-aligned domestic sources.
Long-term offtake contracting is displacing spot market purchasing for battery-grade material. Tier-one cell manufacturers in Germany and Japan are securing multi-year supply agreements directly with synthetic mica processors. This concentration is most visible in procurement departments managing EV platform ramp schedules.
Mica Sheet Market Segmentation
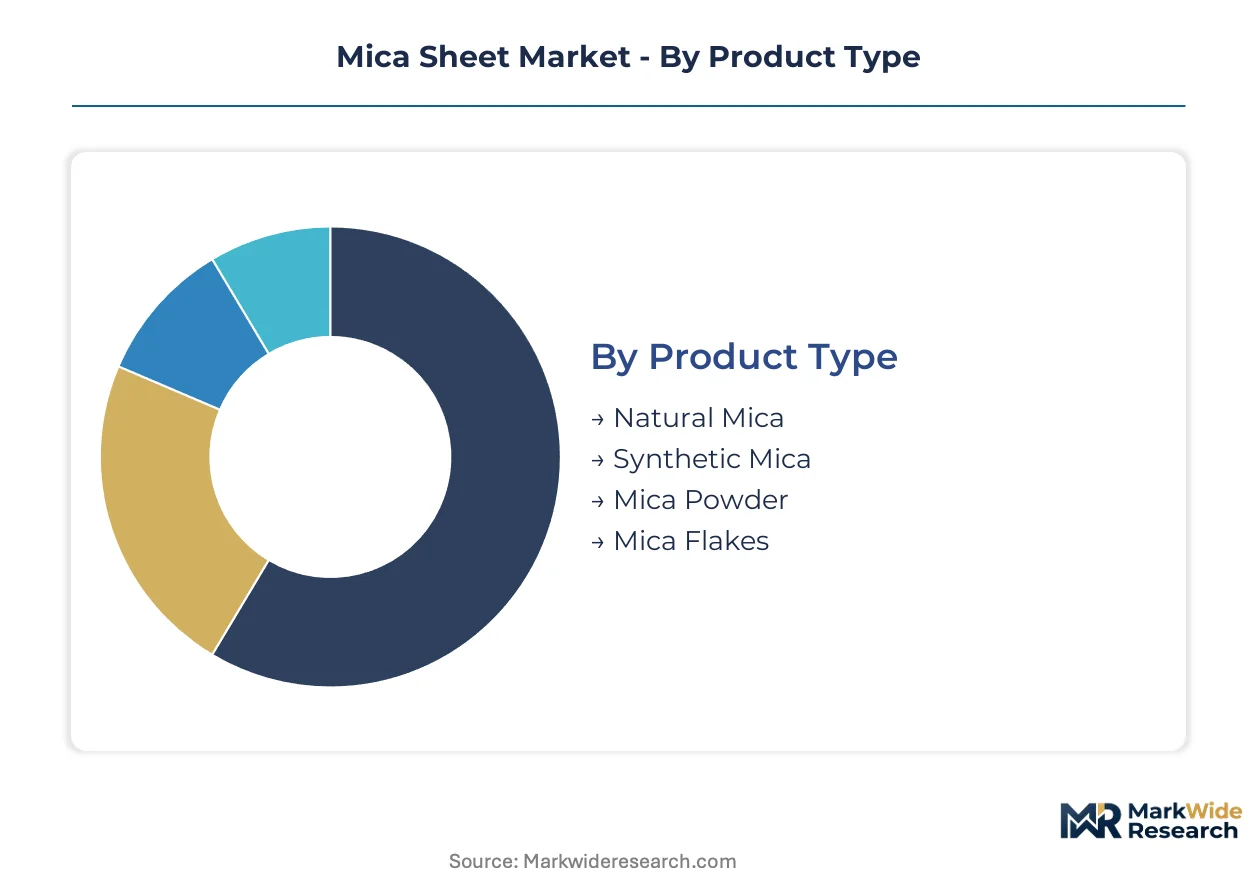
Mica sheet demand fragments across material purity grades, application thermal specifications, and procurement channel economics. Understanding these segment boundaries reveals where synthetic alternatives command premium positioning and where natural flake retains cost advantage.
Product Type:
Cost tier stratification separates mined feedstock from chemically synthesized alternatives, with purity premiums widening at the specification frontier.
- Natural Mica:Phlogopite and muscovite deposits yield flexible sheet layers bonded with silicone resins for dielectric applications below 20 kV/mm. Volume concentrates in transformer insulation and legacy motor rebuild programs where iron content tolerance exceeds 0.5%. Established mining infrastructure in India and Madagascar anchors supply.
- Synthetic Mica:Fluorophlogopite chemistry delivers zero-iron batch consistency for EV battery thermal barriers and precision power electronics. South Korean and Japanese cell manufacturers are qualifying these sources for thermal runaway protection layers. Manufacturing intensity commands price multiples that filter out cost-sensitive industrial buyers.
- Mica Powder:Ground flake serves filler applications in coatings and construction materials where aspect ratio matters less than chemical inertness.
- Mica Flakes:Unprocessed mineral splits into decorative and industrial grades for pearl pigment synthesis and welding rod coatings.
Natural Mica holds installed capacity. Synthetic Mica is rotating up the share rankings.
Application:
End-use thermal and electrical performance requirements determine material grade selection and supplier qualification pathways.
- Electronics:Dielectric barriers in EV power electronics and battery pack thermal management specify synthetic mica for consistent batch purity. German and Japanese tier-one cell manufacturers are locking in multi-year offtake agreements directly with processors. This segment climbs the fastest as platform ramp schedules multiply sheet counts per vehicle.
- Construction:Fire-resistant board and cementitious spray applications consume natural flake for cost-engineered thermal insulation. Building code adoption in India and Southeast Asia is expanding specification volumes for high-rise compartmentation.
- Cosmetics:Pearl pigment and personal care formulations demand cosmetic-grade mica with heavy metal certification.
- Coatings:Industrial paint and anticorrosion systems use ground mica for barrier protection and UV resistance.
Electronics captures margin expansion. Construction defends volume foundation.
End User:
Customer type dictates procurement sophistication, with qualified supplier lists locking out uncertified sources from maintenance contract flows.
- Manufacturers:Electrical equipment OEMs maintain rigorous incoming material testing protocols aligned with IEC and GB standards. Transformer and motor producers in Germany and Japan enforce qualified supplier lists that freeze out new entrants for 18-24 month qualification cycles.
- Builders:Construction contractors source through distributor networks with limited technical specification oversight.
- Cosmetic Companies:Personal care formulators audit supply chains for ethical sourcing certification and heavy metal compliance.
- Paint Producers:Industrial coating manufacturers optimize formulation cost with technical-grade natural powder.
Manufacturers anchor premium pricing. Builders rotate toward import substitution programs.
Distribution Channel:
Channel structure mirrors customer technical requirements and contract scale, with direct relationships dominating specification-grade flows.
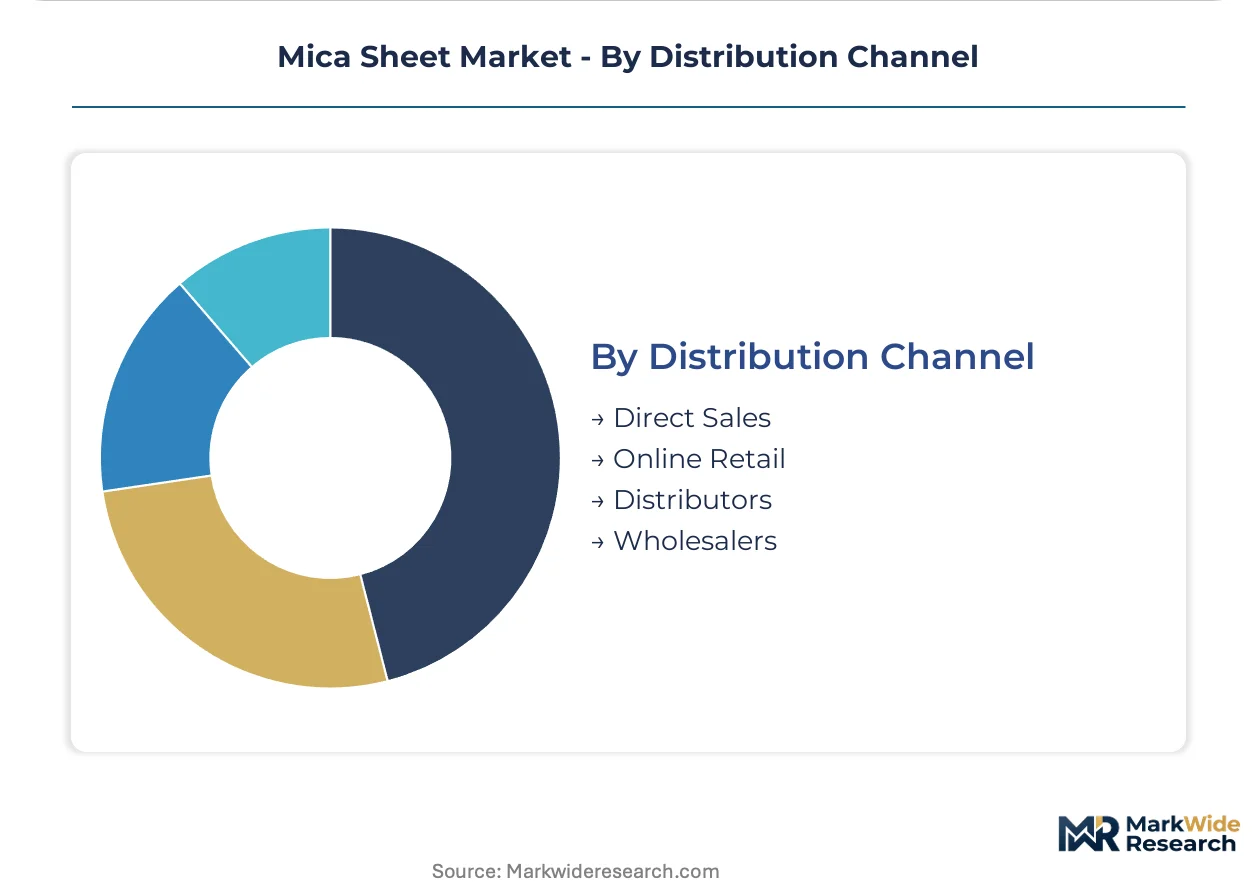
- Direct Sales:Long-term offtake agreements connect synthetic mica processors with EV battery and power electronics manufacturers. Tier-one procurement departments in Germany and South Korea are displacing spot purchasing with multi-year volume commitments.
- Distributors:Electrical insulation specialists stock certified grades for maintenance and repair contractors serving transformer fleets.
- Online Retail:E-commerce platforms serve small-laboratory and prototyping demand with limited volume significance.
- Wholesalers:Bulk material handlers move construction-grade natural flake through regional building supply networks.
Direct Sales holds contract value concentration. Distributors rotate up in aftermarket capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance deadlines and EV production incentives are restructuring procurement geography across mica sheet supply chains. Battery-grade material qualification is concentrating investment in jurisdictions with established synthetic processing infrastructure. Regulatory divergence between EPA silica limits and China's GB standards is fragmenting trade flows.
China
Domestic synthetic mica capacity is scaling to serve Asia-Pacific electronics supply chains with integrated processing advantages. MIIT industrial guidance and GB standards for electrical insulation materials are tightening dielectric strength testing protocols that favor certified domestic producers. The Yangtze River Delta hosts concentrated fluorophlogopite manufacturing serving South Korean and Japanese battery manufacturers.
Germany
Tier-one EV cell manufacturers are locking in multi-year offtake agreements directly with synthetic mica processors for thermal barrier specifications. ECHA REACH registration timelines and RoHS substance restrictions govern market access with 18-24 month dossier completion requirements. The industrial corridor between Cologne and Frankfurt anchors transformer OEM procurement departments enforcing qualified supplier lists.
United States
EPA oversight of mining waste streams and OSHA silica exposure limits are escalating compliance costs for domestic natural mica production. The Inflation Reduction Act's domestic content provisions are redirecting battery material sourcing toward North American qualified suppliers. Appalachian mining districts face production economics pressure from waste stream management requirements.
Japan
Power electronics and battery pack manufacturers are qualifying synthetic mica sources for thermal runaway protection layers with zero-iron batch consistency demands. METI technology roadmaps and JIS standards alignment are accelerating supplier qualification cycles toward domestic and South Korean processors. The Nagoya industrial zone concentrates motor and inverter OEMs with rigorous incoming material testing protocols.
India
Underpenetrated domestic electrical equipment manufacturing is expanding import substitution programs for insulation materials. CEA alignment with BIS standards and PLI scheme incentives for domestic manufacturing are redirecting procurement toward certified local sources. Gujarat and Maharashtra host emerging mica processing clusters serving transformer rebuild programs and construction fire-board applications.
Mica Sheet Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base distributes between integrated mining-to-processing houses, synthetic chemistry specialists, and regional fabrication workshops. Three archetypes dominate: vertically integrated mineral conglomerates with captive deposit access; synthetic mica processors with fluorophlogopite chemistry capabilities; and electrical insulation distributors with qualified supplier list relationships. Competitive moves center on capacity expansion in synthetic production and backward integration into phlogopite deposit control.
Within the integrated mining-to-processing tier, Imerys S.A. and Pamica Group Ltd. occupy positions anchored by multi-continental deposit portfolios. Von Roll Group exemplifies the product-specialist archetype through focused electrical insulation grade development. Among North American fabricators, Asheville Mica Company and Cleveland Mica Co. represent regional workshop-scale competitors serving maintenance and repair contractor networks with distributor-mediated channel access.
| Leading Market Players |
|---|
| Von Roll Group |
| The Premier Mica Company |
| Imerys S.A. |
| Pamica Group Ltd. |
| Daruka International |
| Asheville Mica Company |
| Merck KGaA / SuSoNity |
| Cleveland Mica Co. |
| Elmelin Ltd. |
| Others |
Pricing and Supply Chain Analysis
Madagascar and Indian phlogopite mining clusters anchor upstream feedstock availability, concentrating margin capture with integrated processors who command synthetic mica premiums downstream. Battery-grade thermal barrier specifications are compressing natural flake pricing power while elevating fluorophlogopite batch consistency premiums.
Pricing Analysis
Certification level creates the primary spread between REACH-registered synthetic grades and unregistered natural alternatives. Contract-based long-term offtake dominates EV battery procurement, while spot purchasing persists in construction-grade flake. Price differentiation rests on zero-iron batch consistency and GB standards alignment. Cost compression in natural mica feedstock is intensifying because Chinese synthetic capacity expansion is eroding volume premiums. Construction contractors exhibit highest price sensitivity; German tier-one cell manufacturers show lowest.
Supply Chain Analysis
Phlogopite deposits in Madagascar, India, and Brazil feed global flake processing. Synthetic mica production draws from fluorine chemistry and high-purity alumina inputs. Single-source vulnerability concentrates in Madagascar's weathered pegmatite zones where artisanal mining dominates extraction. Distribution runs through direct sales for battery-grade material and electrical insulation distributors for maintenance contract flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where REACH registration timelines and qualified supplier lists create switching costs that freeze out unqualified competitors. Incumbents possess durable moats through certification assets that require 18-24 month investment cycles to replicate.
For Market Incumbents: Entrench synthetic mica capacity in the Yangtze River Delta to serve South Korean and Japanese battery manufacturers. Secure backward integration into Indian phlogopite deposits to defend against raw material concentration risk. Lock in multi-year offtake agreements before emerging Chinese synthetic processors achieve GB certification parity.
For New Entrants and Emerging Players: India's underpenetrated transformer rebuild programs offer white-space access through CEA-aligned BIS certification. Target Gujarat and Maharashtra processing clusters for import substitution positioning. Pursue distributor partnerships with electrical insulation specialists rather than direct OEM qualification cycles.
For Investors and Strategic Acquirers: Capital is best deployed toward synthetic mica processors with fluorophlogopite chemistry capabilities and existing REACH dossiers. Long-term viability hinges on critical mineral designation outcomes across multiple jurisdictions. Monitor ECHA substance evaluation timelines as inflection indicators for regulatory moat expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phlogopite Deposits | Madagascar and Indian mining concessions secure feedstock against concentration risk. |
| Synthetic Mica Capacity Expansion | Yangtze River Delta fluorophlogopite plants capture GB certification advantages. |
| REACH Registration Completion | ECHA dossier finalization unlocks German tier-one cell manufacturer procurement. |
| Long-term Supply Agreement | Multi-year offtake contracts with South Korean battery producers displace spot purchasing. |
| Joint Venture with Electrical Insulation Distributors | Qualified supplier list relationships accelerate aftermarket channel penetration. |
Research Methodology
Cross-validation between synthetic mica processor interviews and customs trade data anchors the qualitative findings. Primary fieldwork engaged phlogopite mining operators, electrical insulation procurement leads at transformer OEMs, fluorophlogopite chemistry R&D directors, and battery pack thermal management engineers. Secondary sources included ECHA REACH registration databases, MIIT industrial guidance filings, GB standards documentation, and SEC 10-K disclosures from integrated mining houses. Bottom-up segment sizing triangulated against top-down mineral production estimates.
Calibration against historical capacity expansion timelines and qualification cycle durations informed the analytical framework. Segmentation dimensions spanned material purity grade, application thermal specification, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from installed capacity trajectories and EV platform ramp schedules. Forecast inputs incorporated synthetic mica yield improvements and REACH compliance cost escalation.
Practitioners should monitor ECHA substance evaluation timelines and critical mineral designation debates for early signals of regulatory moat shifts. Forecasts reflect assumptions about battery thermal barrier layer counts and synthetic mica yield curves. Cross-checking against MIIT capacity utilization disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Non-Semiconductor Neon Market
Specialty Materials
Surface Technology Market
Specialty Materials
Asia Pacific Cellulose Acetate Market
Specialty Materials
Global Conductive Silicone Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Retro Reflective Materials Market
Specialty Materials
Alginate Films Market
Specialty Materials
Asia-Pacific Colloidal Silica Market
Specialty Materials
Special Graphite Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Polyester Medical Films Market
Specialty Materials
Epoxy Encapsulation Material Market
Specialty Materials
Methyl Silicone Market