
 Inorganic Flame Retardants Market | 2026-2036
Inorganic Flame Retardants Market Size, Share, and Industry Trends Forecast 2026-2036
Inorganic Flame Retardants Market Foresight
China is narrowing its cost advantage in aluminum hydroxide and magnesium hydroxide processing as energy and environmental compliance expenses rise. Albemarle Corporation leverages its bromine-specialist heritage to compete in adjacent mineral-based formulations. ICL Group Ltd. anchors its position through integrated Dead Sea brine operations that supply magnesium feedstock. Huber Engineered Materials differentiates via precipitated ATH capacity in North America serving construction and automotive accounts.
Inorganic flame retardants comprise mineral compounds—principally aluminum hydroxide (ATH), magnesium hydroxide (MDH), zinc borate, and calcium carbonate—that release water vapor and form protective oxide layers when heated above decomposition temperatures, thereby suppressing combustion in polymers, textiles, and coatings. These materials function primarily as endothermic fillers that dilute fuel load, cool the pyrolysis zone, and reduce smoke density in fire-exposed substrates. Aluminum hydroxide dominates volume due to its low cost and broad compatibility with thermoset resins, while magnesium hydroxide commands premium positioning in high-temperature thermoplastic applications where ATH decomposes prematurely. Zinc borate concentrates in intumescent coating systems and synergistic blends where it enhances char stability and suppresses afterglow, capturing margin pools in specialized industrial and electronics segments.
EPA regulations under the Toxic Substances Control Act and OSHA combustible dust standards shape manufacturing facility requirements and product handling protocols in the United States. REACH registration obligations and the EU Green Deal's chemical sustainability targets compel European producers to document environmental fate and pursue cleaner production pathways for mineral flame retardants. ECHA restrictions on halogenated substances continue redirecting formulation demand toward ATH and MDH alternatives. Stakeholders must monitor evolving fire safety codes in major construction markets and assess backward integration into brine or bauxite feedstock sources as supply security considerations intensify.
Market Dynamics
Builders across commercial and residential construction are systematically replacing halogenated flame retardants with mineral-based alternatives as REACH and RoHS frameworks tighten restrictions on brominated compounds, redirecting formulation demand toward aluminum hydroxide and magnesium hydroxide systems while China maintains concentrated manufacturing control over raw material processing.
Growth Catalysts
- REACH restrictions on halogenated substances:European regulatory pressure is eliminating brominated compound formulations from electrical enclosures and building materials, forcing compounders to reformulate with ATH and MDH mineral fillers.
- Construction fire safety codes:Commercial and residential building standards in Germany, France, and the United States now mandate enhanced flame resistance in insulation, wiring, and structural composites without halogenated chemistry.
- Electric vehicle battery enclosures:Thermal runaway protection requirements for lithium-ion battery packs are consuming engineered magnesium hydroxide grades in polypropylene and thermoplastic elastomer housings.
Market Restraints
- Bauxite and brine feedstock concentration:China's dominance in aluminum hydroxide refining and Dead Sea magnesium sourcing creates single-point vulnerability for European and North American compounders.
- ATH thermal decomposition ceiling:Aluminum hydroxide releases water vapor at approximately 180°C, rendering it incompatible with high-temperature thermoplastic processing above this threshold where MDH commands premium positioning.
- Energy cost inflation in mineral processing:Calcination and precipitation operations for refined ATH and MDH grades face margin compression from natural gas and electricity price volatility in manufacturing clusters.
Strategic Opportunities
- India construction acceleration:Urban infrastructure investment and commercial real estate expansion in Mumbai, Delhi, and Bangalore are outpacing domestic flame retardant compounding capacity, creating import demand for mineral-based systems.
- Intumescent coating synergies:Zinc borate integration with phosphorus-based char formers is opening specialized margin pools in industrial steel protection and electronics enclosure applications.
- EU Green Deal chemical sustainability targets:Documentation requirements for environmental fate and cleaner production pathways favor established European mineral flame retardant producers with verified life-cycle assessments.
Industry Challenges
- Combustible dust compliance:OSHA standards for aluminum hydroxide and magnesium hydroxide powder handling require capital-intensive facility upgrades including explosion venting, suppression systems, and worker respiratory protection protocols.
- Polymer compatibility formulation:Achieving uniform mineral dispersion in polar and non-polar resin matrices demands specialized surface treatment chemistry and twin-screw extrusion expertise that concentrates among specialized compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inorganic Flame Retardants Market |
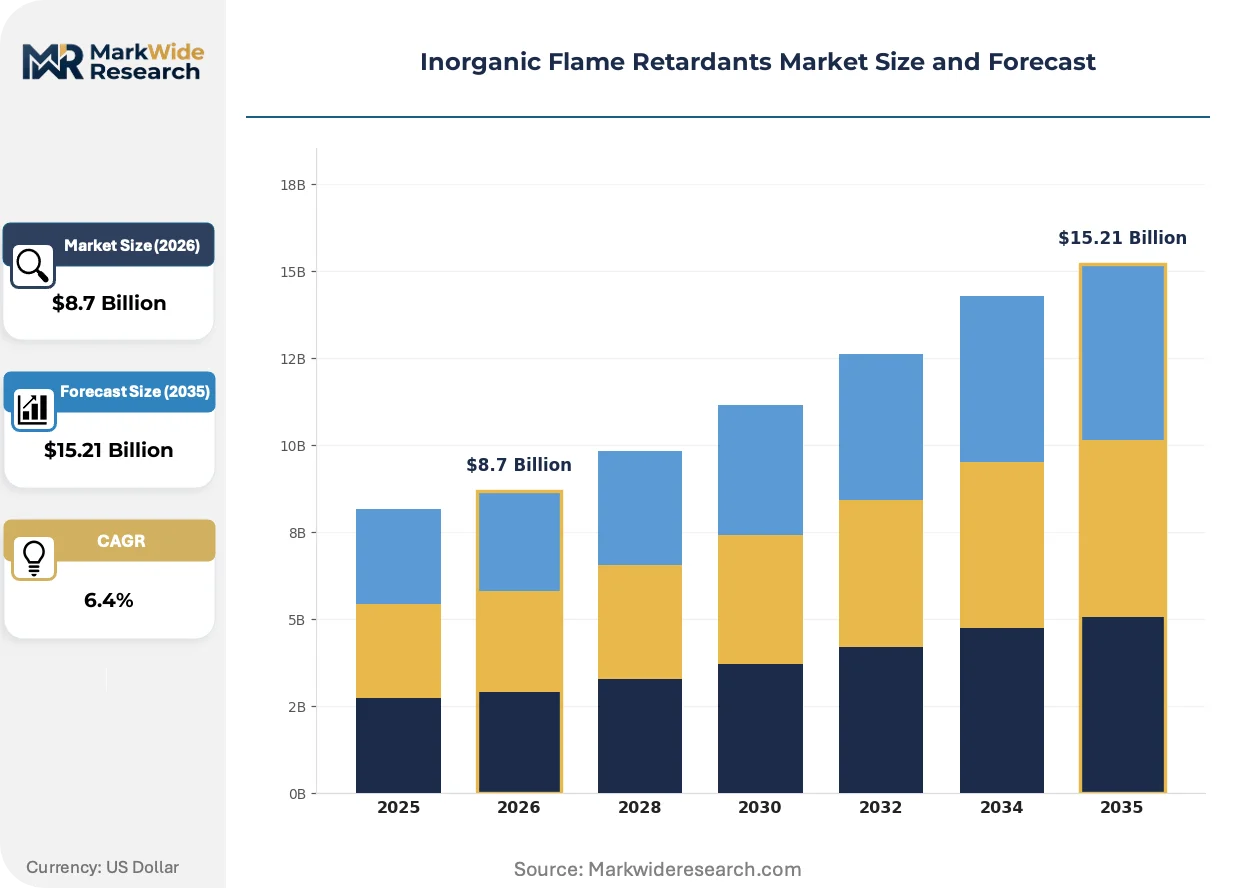
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Hydroxide, Magnesium Hydroxide, Zinc Borate, Calcium Carbonate Application: Construction, Automotive, Electronics, Textiles End User: Building Materials, Consumer Electronics, Automotive Manufacturers, Industrial Sector Form: Powder, Granules, Pellets, Aqueous Dispersion |
| Companies Covered | Albemarle Corporation, ICL Group Ltd., Nabaltec AG, BASF SE, Huber Engineered Materials, LANXESS AG, Clariant AG, Italmatch Chemicals S.p.A., ADEKA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inorganic Flame Retardants Market Shifts & Advancements
Surface-modified precipitated ATH grades with enhanced polymer compatibility are displacing ground mineral alternatives in automotive and construction applications, while regulatory pressure on halogenated chemistry accelerates mineral formulation adoption across electrical and electronic segments.
Nano-precipitated aluminum hydroxide with silane coupling agent surface treatment is rendering obsolete conventional ground ATH in thin-wall electrical conduit and automotive cable jacketing. Tier-1 automotive suppliers in Germany and Japan are specifying these grades for EV high-voltage harnesses. The technology is rendering obsolete legacy compounding approaches that relied on high mineral loadings at the expense of mechanical properties.
ECHA restrictions on halogenated substances under REACH Annex XVII are eliminating brominated flame retardant options from consumer electronics housings and household appliance enclosures. Compounders serving the European market must reformulate with ATH-MDH synergistic blends or phosphorus alternatives. Wire and cable manufacturers in Italy and Poland face the most acute transition pressure as legacy inventory depletes and certification retesting timelines compress.
Direct procurement relationships between polymer compounders and mineral processors are consolidating distributor intermediaries in the construction and automotive supply chains. Large thermoplastic converters in the United States and Germany now negotiate annual volume contracts with Huber Engineered Materials or Chinese precipitated ATH specialists rather than regional chemical distributors. This pattern is most visible in polyolefin masterbatch supply for building wire and roofing membrane applications where specification consistency outweighs spot-market flexibility.
Inorganic Flame Retardants Market Segmentation
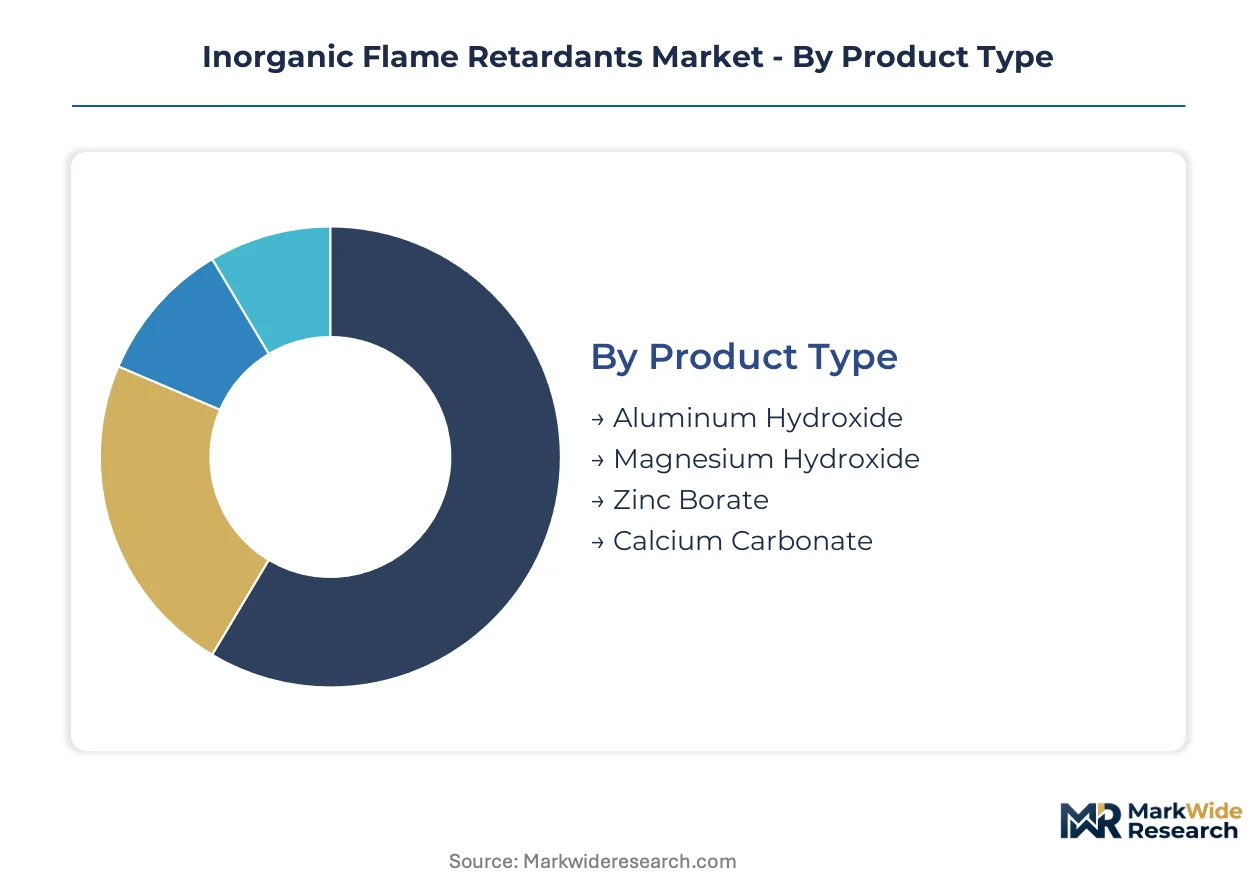
Segmentation in inorganic flame retardants reveals how mineral chemistry, physical form, and end-use specifications create distinct margin pools and technical service requirements across the value chain. Compounders and processors face divergent formulation challenges depending on which segment combination they target.
Product Type:
After-sales technical support intensity varies sharply across mineral chemistries, with precipitated grades demanding ongoing polymer compatibility troubleshooting while ground mineral alternatives require less intensive customer engagement.
- Aluminum Hydroxide:ATH decomposes endothermically at approximately 180°C, releasing water vapor that dilutes combustible gases and cools the pyrolysis zone. Demand concentrates in German and Italian wire and cable compounding, where REACH-driven halogen replacement has forced rapid reformulation of building wire insulation and roofing membranes. ATH thermal ceiling limits its use in high-temperature thermoplastics, creating a persistent specification boundary that compounders navigate through load-level optimization.
- Magnesium Hydroxide:MDH decomposes at roughly 330°C, enabling processing in polypropylene and engineering thermoplastics where ATH would degrade prematurely. Japanese and South Korean automotive suppliers specify surface-treated MDH grades for electric vehicle battery enclosures and high-voltage harness sheathing, driven by thermal runaway protection mandates. Premium positioning reflects both higher decomposition temperature and more complex surface modification requirements.
- Zinc Borate:Functions primarily as a synergist in intumescent coating systems, enhancing char stability and suppressing afterglow in steel protection applications.
- Calcium Carbonate:Serves as a low-cost diluent and smoke suppressant in select construction applications with limited temperature demands.
By volume, Aluminum Hydroxide leads. By growth pace, Magnesium Hydroxide is ahead.
Application:
Cost tier stratification separates specification-intensive electrical and automotive segments from price-sensitive construction bulk applications.
- Construction:Commercial and residential building codes in Germany, France, and the United States mandate enhanced flame resistance in insulation, structural composites, and roofing systems without halogenated chemistry. German facade insulation manufacturers represent the most concentrated demand cluster for ATH-based systems.
- Automotive:EV battery enclosure specifications from Japanese and German OEMs consume engineered MDH grades in polypropylene housings, with thermal runaway protection requirements driving material selection above cost considerations.
- Electronics:ECHA restrictions under REACH Annex XVII have eliminated brominated options from consumer electronics housings, forcing compounders serving European markets into ATH-MDH synergistic blends.
- Textiles:Industrial protective fabrics and transportation seating applications in France and Italy specify mineral-treated fibers for regulatory compliance.
Construction commands absolute volume. Automotive applications are expanding most quickly.
End User:
Customer type determines procurement sophistication, with automotive OEMs and electronics brands imposing qualification protocols that exclude commodity mineral suppliers.
- Building Materials:Roofing membrane and insulation manufacturers in Germany and Poland negotiate direct annual contracts with precipitated ATH specialists, bypassing distributor intermediaries.
- Consumer Electronics:Brands selling into Europe must document REACH compliance and life-cycle assessments, favoring established mineral processors with verified environmental fate data.
- Automotive Manufacturers:Tier-1 suppliers in Japan and Germany specify nano-precipitated ATH with silane surface treatment for thin-wall EV cable jacketing.
- Industrial Sector:Steel protection coating formulators integrate zinc borate with phosphorus-based char formers for intumescent systems serving petrochemical and infrastructure clients.
Building Materials dominates procurement volumes. Consumer Electronics faces the steepest compliance-driven reformulation pressure.
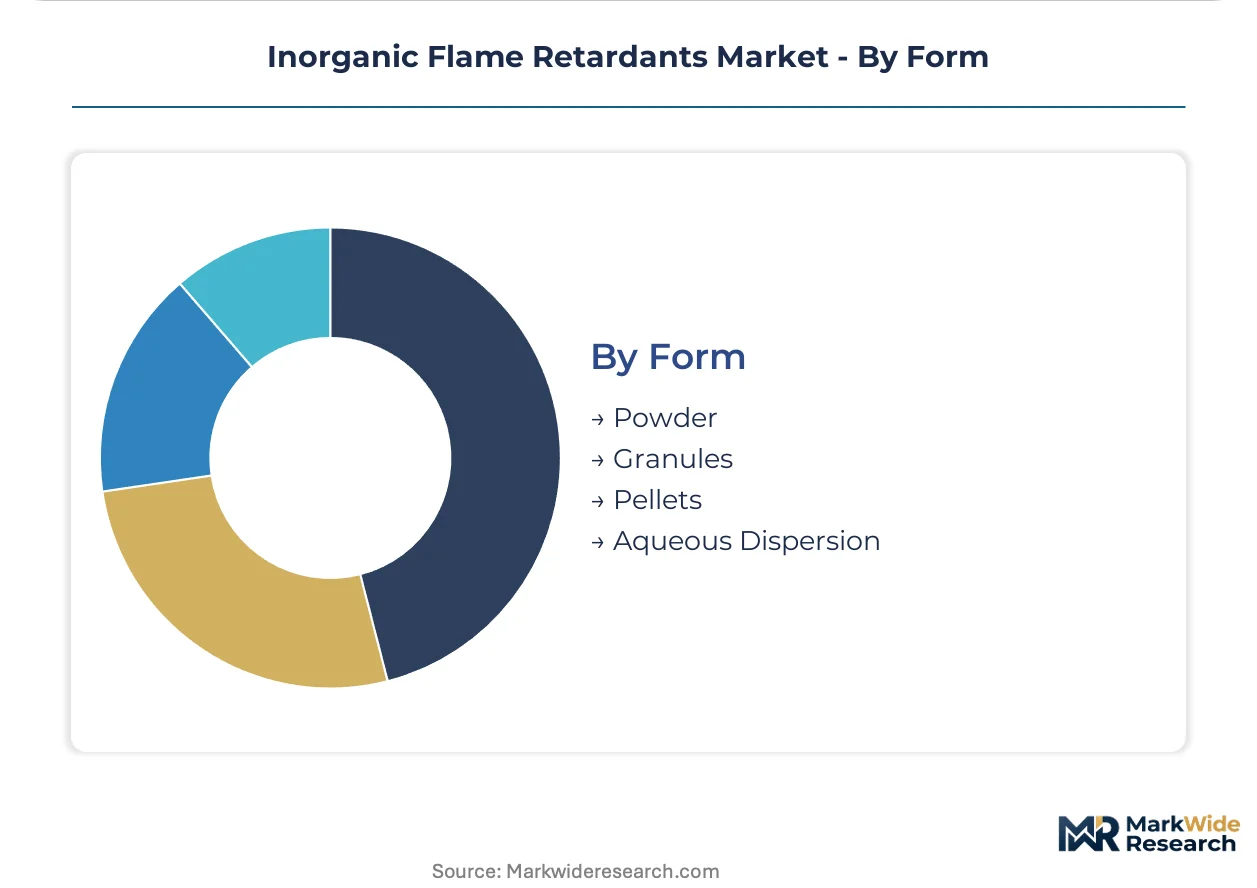
Form:
Supply concentration in precipitated powder grades contrasts with distributed compounding of masterbatch pellets and aqueous dispersions.
- Powder:Ground and precipitated mineral powders remain the baseline delivery form, though OSHA combustible dust standards impose capital-intensive handling requirements on US and European processors.
- Granules:Dust-suppressed agglomerated grades reduce workplace exposure risks while maintaining dispersion performance in twin-screw extrusion.
- Pellets:Polyolefin masterbatch concentrates from German and US compounders simplify downstream processing for construction wire and automotive applications.
- Aqueous Dispersion:Water-based suspensions serve textile treatment and coating applications where dry powder incorporation creates processing difficulties.
Powder forms lead on volume shipped. Pellet masterbatches are gaining share fastest among compounders seeking processing efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH and RoHS frameworks in Europe continue tightening restrictions on brominated compounds, redirecting formulation demand toward aluminum hydroxide and magnesium hydroxide systems while China maintains concentrated manufacturing control over raw material processing.
China
Shandong and Henan provinces host the dominant aluminum hydroxide refining clusters, supplying precipitated grades to European wire and cable compounders. The Ministry of Ecology and Environment enforces dual carbon goals that elevate energy costs for calcination operations. Qingdao and Zhengzhou processors are absorbing margin compression from natural gas price volatility while expanding surface-treatment capacity for automotive-grade exports.
Germany
Facade insulation manufacturers in North Rhine-Westphalia represent the most concentrated demand cluster for ATH-based systems in European construction. ECHA restrictions under REACH Annex XVII have eliminated brominated options from building materials, forcing rapid reformulation. The Cologne-Düsseldorf industrial corridor hosts compounders negotiating direct annual contracts with mineral processors, bypassing distributor intermediaries.
United States
OSHA combustible dust standards impose capital-intensive handling requirements on aluminum hydroxide and magnesium hydroxide powder processors. The EPA regulates mineral flame retardants under the Toxic Substances Control Act, shaping facility compliance protocols. Georgia and Ohio host precipitated ATH capacity serving construction wire and automotive cable jacketing markets.
Japan
Tier-1 automotive suppliers in the Nagoya-Toyota industrial zone specify nano-precipitated ATH with silane surface treatment for EV high-voltage harnesses. METI thermal runaway protection mandates for lithium-ion battery packs consume engineered magnesium hydroxide grades in polypropylene housings. Osaka-based compounders are qualifying surface-treated MDH for thin-wall electrical conduit applications.
India
Urban infrastructure investment in Mumbai, Delhi, and Bangalore is outpacing domestic flame retardant compounding capacity, creating import demand for mineral-based systems. The Bureau of Indian Standards enforces fire safety codes in commercial real estate that align with European halogen-free specifications. Gujarat and Maharashtra are emerging as construction chemical formulation clusters requiring ATH-MDH synergistic blends.
Inorganic Flame Retardants Market Competitive Landscape
Capability concentration sits with integrated mineral processors possessing brine or bauxite feedstock control; scale advantage sits with diversified chemical conglomerates with global distribution infrastructure. The vendor base organizes into three tiers: integrated Dead Sea and bauxite-based mineral specialists, diversified multinational chemical portfolios, and regional precipitated grade fabricators. Consolidation pressure is accelerating as compounders demand specification consistency and verified life-cycle assessments. Dominant competitive moves include backward integration into captive brine sources and direct procurement relationships that displace distributor intermediaries.
Among integrated mineral specialists, Albemarle Corporation and ICL Group Ltd. exemplify the feedstock-anchored archetype, while Huber Engineered Materials occupies a position within the precipitated grade fabrication tier. These three entities represent distinct strategic postures: brine-based magnesium sourcing, bromine-specialist heritage applied to adjacent mineral formulations, and North American precipitated ATH capacity serving construction and automotive accounts. LANXESS AG and Clariant AG sit within the diversified chemical conglomerate tier, leveraging existing polymer additive distribution channels. Nabaltec AG and Italmatch Chemicals S.p.A. exemplify European regional specialists with proximity to REACH-driven reformulation demand. BASF SE and ADEKA Corporation anchor the multinational scale tier with integrated research infrastructure for surface-modified grade development.
| Leading Market Players |
|---|
| Albemarle Corporation |
| ICL Group Ltd. |
| Nabaltec AG |
| BASF SE |
| Huber Engineered Materials |
| LANXESS AG |
| Clariant AG |
| Italmatch Chemicals S.p.A. |
| ADEKA Corporation |
| Others |
Supply & Pricing Matrix
Single-source dependency on Chinese aluminum hydroxide refining clusters determines both the widening premium-to-economy price spreads across mineral grades and the consolidation of procurement relationships around direct processor contracts. REACH-driven reformulation urgency in Europe and thermal runaway protection mandates in electric vehicle supply chains are compressing price negotiation windows while elevating specification premiums for surface-treated precipitated grades.
Pricing Analysis
Geographic price spreads between Chinese precipitated ATH exports and North American domestically processed material have widened as energy cost inflation and environmental compliance expenses narrow historical cost advantages. Three-tier pricing structure across premium surface-treated automotive grades, standard construction-grade precipitated ATH, and economy ground mineral alternatives reflects decomposition temperature thresholds and polymer compatibility certification levels. Cost compression in the economy tier is intensifying because European compounders are absorbing tariff and logistics exposure to secure non-Chinese supply alternatives. Construction wire and cable manufacturers represent the most price-sensitive buyer segment, while Japanese and German automotive Tier-1 suppliers prioritize thermal performance over unit cost in battery enclosure specifications.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculations for aluminum hydroxide processors, with German and Italian compounders accelerating qualification of alternative sourcing. Manufacturing gravity centers on Shandong and Henan provinces for ATH refining, the Dead Sea basin for magnesium hydroxide brine extraction, and Georgia and Ohio for North American precipitated capacity. Raw material dependencies draw from bauxite ore for aluminum hydroxide feedstock, magnesium-rich brine deposits, and natural gas for calcination energy inputs. Single-source vulnerability concentrates in Chinese intermediate processing, where Ministry of Ecology and Environment enforcement of dual carbon goals is constraining expansion permits. Distribution runs through direct annual volume contracts between mineral processors and large thermoplastic converters, displacing regional chemical distributor intermediaries in construction and automotive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across REACH, RoHS, and emerging battery safety codes is creating specialized formulation niches that favor mid-scale compounders with rapid certification capabilities over commodity mineral suppliers.
For Market Incumbents: Pre-empt margin erosion in standard ATH grades by securing captive bauxite or brine feedstock through backward integration into Australian or Turkish mining assets, while accelerating surface-treatment R&D investment to defend specification premiums against emerging Chinese precipitated grade specialists. ECHA's expanding Annex XVII restrictions on halogenated chemistry represent the most urgent regulatory threat, requiring immediate reformulation partnership agreements with European wire and cable manufacturers facing compressed retesting timelines. For New Entrants and Emerging Players: Mid-market commercial construction in Indian metropolitan clusters represents the most penetrable entry point, where Bureau of Indian Standards fire code enforcement is outpacing domestic compounding capacity and import substitution incentives favor local formulation partnerships. Zinc borate synergist blending for intumescent steel protection coatings offers a second white-space target with specialized margin pools and limited incumbent concentration. A technical service-led go-to-market approach emphasizing polymer compatibility troubleshooting and rapid sample qualification can differentiate against commodity mineral traders. For Investors and Strategic Acquirers: REACH Annex XVII expansion and EU Green Deal chemical sustainability documentation requirements reshape the acquisition landscape toward European regional specialists with verified life-cycle assessments and established ECHA registration dossiers. Long-term viability across the analysis window favors processors with integrated feedstock control and surface-modification capabilities over pure-play ground mineral distributors. The signal to watch is qualification timeline compression at German and Japanese automotive Tier-1 suppliers, where nano-precipitated ATH adoption rates indicate willingness to pay specification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite or Brine Sources | Captive feedstock secures margin stability against Chinese energy cost volatility and export restriction risk. |
| Surface Treatment Capacity Expansion | Silane coupling agent expertise commands automotive-grade premiums from EV battery enclosure suppliers. |
| Direct Procurement Relationship Development | Bypassing distributor intermediaries captures margin and ensures specification consistency for construction compounders. |
| EU Green Deal Compliance Documentation | Verified life-cycle assessments favor established European processors in REACH-driven reformulation tenders. |
| Intumescent Coating Synergist Formulation | Zinc borate integration with phosphorus char formers opens specialized industrial steel protection margin pools. |
Research Methodology
A spread of perspectives from plant managers at mineral processing facilities, procurement leads at downstream polymer compounders, distribution channel partners serving construction wire markets, and technical R&D directors at surface-treatment specialists converged on the working assumptions. Secondary validation drew from customs and trade flow data, SEC 10-K filings of listed chemical conglomerates, American Chemistry Council and Cefic industry reports, and ECHA registration dossiers. Bottom-up volume estimates from individual facility capacities and top-down demand modeling from end-use consumption patterns were triangulated to establish consensus figures.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation dimensions encompassing mineral chemistry type, decomposition temperature tier, end-use industry, surface treatment level, and regional production hub. CAGRs were derived from trend extrapolation of historical volume shifts and elasticity estimates around regulatory inflection points. Industry-specific forecast inputs included electric vehicle battery enclosure adoption curves, REACH restriction implementation timelines, and construction fire code enforcement intensity across German federal states.
Stress conditions across Chinese environmental policy enforcement severity, European natural gas price volatility, and automotive OEM qualification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation pace and substitution elasticity in polymer formulation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Water Based Acrylates Copolymer Rheology Modifiers Market
Specialty Chemicals
Crystal Hard Wax Market
Specialty Chemicals
Explosives and Pyrotechnics Market
Specialty Chemicals
Eco-Friendly Plasticizers Market
Specialty Chemicals
Hyaluronic Acid Products Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Global 28-Homobrassinolide Market
Specialty Chemicals
North America Sugarcane Wax Market
Specialty Chemicals
Global Hydroxy Ethyl Cellulose (HEC) Market
Specialty Chemicals
Brominated Flame Retardants Market
Specialty Chemicals
Protein Purification Resin Market
Specialty Chemicals
Colloidal Gold Suspension Market
Specialty Chemicals
Technical Aerosol Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Freeze-Thaw Stabilizers Market
Specialty Chemicals
Global Optical Brighteners Market