
 Advanced Green Septa Market | 2026-2036
Advanced Green Septa Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Green Septa Market Insights
REACH is rebalancing the cost-of-entry calculus for septa manufacturers serving European laboratories. Agilent leverages its captive chromatography ecosystem to anchor premium positioning in green-certified consumables. Merck sustains vertical control over silicone precursor supply, while Restek Corporation specializes in application-specific formulations for environmental compliance testing.
Advanced green septa are precision-manufactured barrier discs, typically 8–20 mm diameter, composed of platinum-cured silicone or fluoropolymer laminates engineered to minimize bleed and withstand repeated needle punctures at temperatures exceeding 200°C in gas chromatography and mass spectrometry inlets. Disposable septa dominate current procurement volumes across pharmaceutical analysis workflows, though specialty septa command disproportionate margin pools in high-sensitivity clinical diagnostics where lot-to-lot consistency governs method validation. Silicone leads material selection for thermal stability, while PTFE-silicone laminates are displacing pure butyl in environmental testing applications requiring solvent resistance.
FDA enforces extractables and leachables standards for septa contacting drug products, while ECHA REACH restricts phthalate and heavy-metal additives in polymer formulations sold within Europe. EPA method compliance for volatile organic compound analysis further segments demand between certified and uncertified product tiers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as pending regulatory reclassifications threaten PTFE-containing laminates and could force material transitions across the installed base of autosamplers.
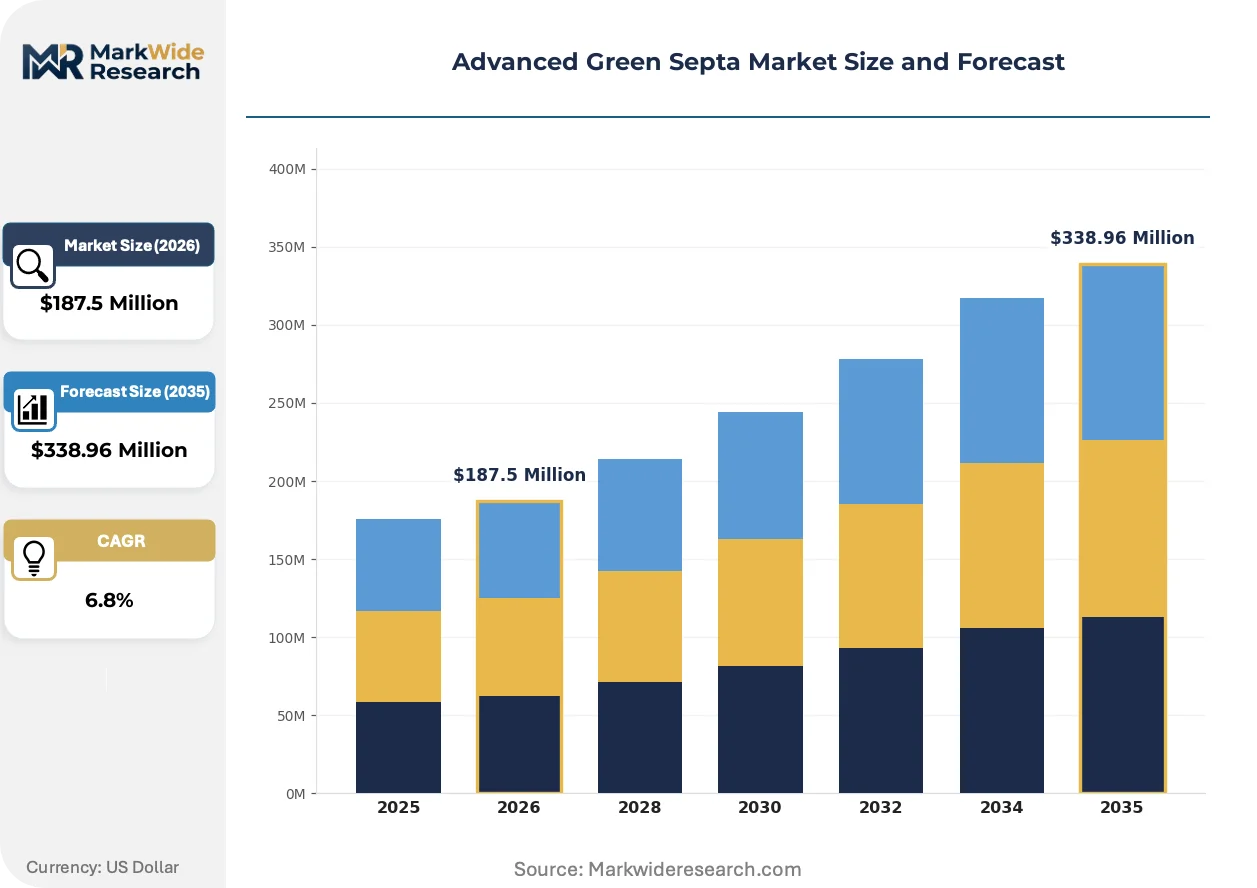
Market Dynamics
ECHA REACH restrictions on phthalate plasticizers are forcing immediate material transitions across European laboratory supply chains, compressing qualification timelines and concentrating procurement authority among buyers with certified green septa portfolios.
Growth Catalysts
- REACH compliance mandates:ECHA restrictions on phthalate additives in polymer formulations compel pharmaceutical laboratories across Germany, France, and the Netherlands to replace legacy septa stocks with platinum-cured silicone alternatives.
- Chromatography instrument density:Bavaria's analytical instrument cluster drives concentrated demand for premium-grade septa capable of withstanding repeated autosampler punctures at elevated temperatures.
- Environmental testing protocols:EPA Method 8260 and analogous volatile organic compound analysis standards require certified low-bleed septa for groundwater and air monitoring applications.
Market Restraints
- Platinum catalyst cost volatility:Platinum-cured silicone production depends on precious metal inputs subject to commodity price swings that compress manufacturer margins.
- Fluoropolymer supply concentration:PTFE laminate production concentrates among a limited set of chemical processors, creating vulnerability to feedstock allocation decisions.
- Pending PFAS reclassification:European and North American regulators are reviewing per- and polyfluoroalkyl substance restrictions that threaten PTFE-containing septa formulations and could force material obsolescence.
Strategic Opportunities
- Clinical diagnostics penetration:High-sensitivity mass spectrometry workflows in hospital laboratories present underdeveloped demand for lot-to-lot consistent septa with validated extractables profiles.
- Biopharma single-use systems:Integration of disposable septa into pre-sterilized fluid handling assemblies aligns with aseptic processing trends in mammalian cell culture operations.
- EU Green Deal procurement incentives:Public sector laboratory purchasing frameworks increasingly weight lifecycle environmental impact, advantaging certified sustainable septa suppliers in competitive tenders.
Industry Challenges
- Extractables validation timelines:FDA and EMA extractables and leachables documentation requirements extend product qualification cycles, delaying revenue recognition for new formulations.
- Legacy autosampler compatibility:Material transitions to fluoropolymer laminates must maintain dimensional tolerances across installed instrument bases with varying compression specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Green Septa Market |
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $338.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Septa, Reusable Septa, Specialty Septa, Crimped Septa Material: Silicone, Butyl, PTFE, Rubber Application: Pharmaceutical Analysis, Environmental Testing, Food Testing, Clinical Diagnostics End User: Laboratories, Research Institutions, Pharmaceutical Companies, Biotechnology Firms |
| Companies Covered | Shimadzu, Agilent, Merck, PerkinElmer, Restek Corporation, GL Sciences Inc., Chromatography Research Supplies, Worldwide Glass Resources, Pawling Engineered Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Green Septa Market Trends and Innovations
Material science advances and regulatory pressure are converging to redefine septa performance benchmarks, with thermal stability and chemical inertness now table stakes rather than differentiators.
Platinum-cured silicone is absorbing the functional requirements previously distributed across butyl, natural rubber, and fluorosilicone alternatives in high-temperature gas chromatography inlets. Pharmaceutical quality control laboratories in Germany and Switzerland are adopting these formulations at accelerated replacement cycles. The technology is absorbing margin compression from commodity-grade competitors while enabling premium positioning through validated bleed profiles.
REACH Annex XVII restrictions on phthalate plasticizers are eliminating flexible PVC and certain rubber formulations from European laboratory consumables. Manufacturers serving EEA markets must reformulate or exit, with Bavarian and Baden-Württemberg instrument clusters experiencing the tightest supply transitions. Specialty silicone compounders are capturing displaced volume by qualifying platinum-cured alternatives under accelerated regulatory timelines.
Consolidated procurement functions at multinational pharmaceutical headquarters are displacing distributed laboratory purchasing decisions, centralizing septa specification authority under global category managers. Regional distributors serving individual research sites are losing influence to direct manufacturer contracts with negotiated performance guarantees. This concentration is most visible across German and Swiss pharmaceutical manufacturing corridors where central procurement hubs coordinate multi-site consumable standards.
Advanced Green Septa Market Segmentation
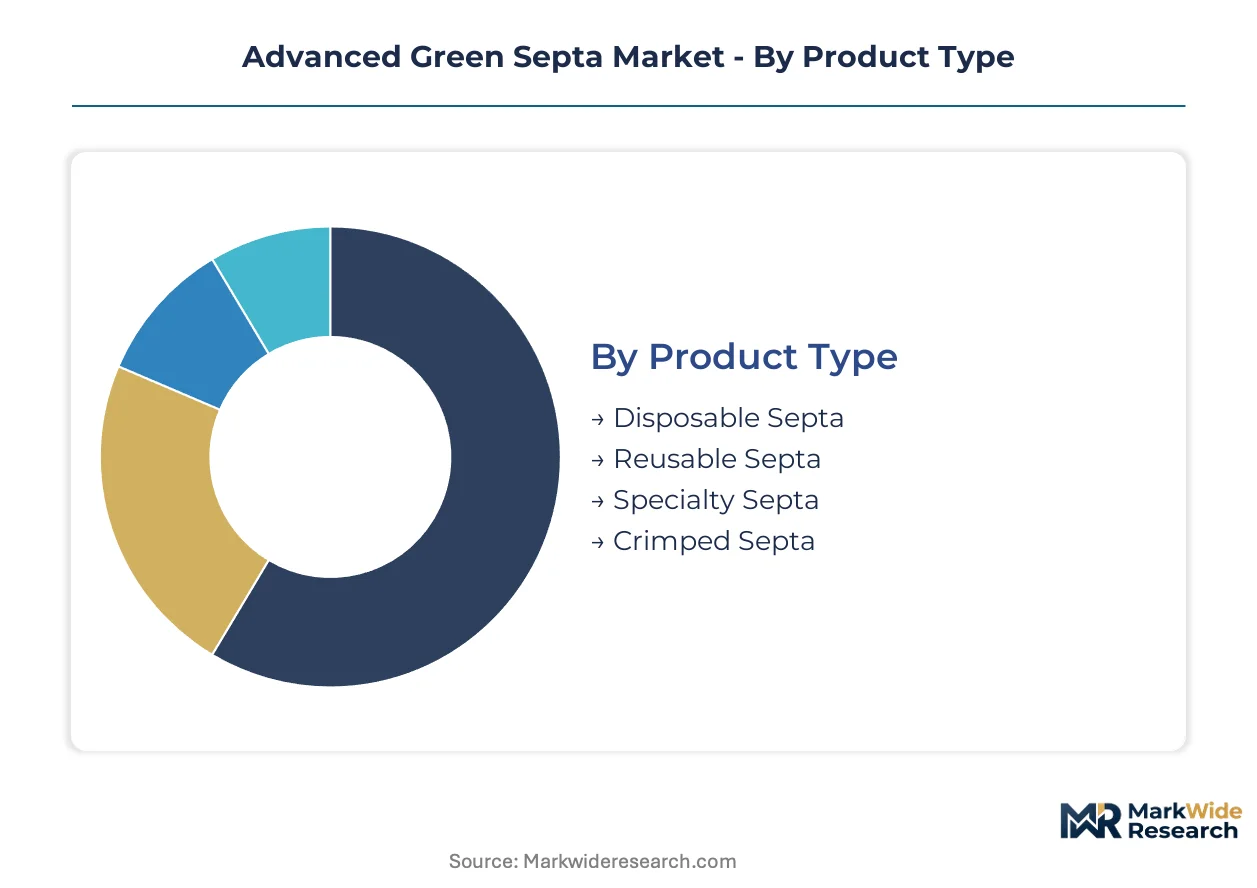
Septa procurement patterns diverge sharply between standalone consumable purchases and integrated fluid handling systems. Understanding these integration pathways clarifies where margin pools concentrate and which specifications govern vendor selection.
Product Type:
Standalone disposable formats dominate high-throughput workflows, while embedded reusable variants anchor capital-intensive instrument platforms.
- Disposable Septa:Single-use platinum-cured silicone discs, typically 9–11 mm diameter, serve autosampler vial sealing in pharmaceutical quality control labs across Germany and Switzerland. Bavarian chromatography clusters drive volume concentration as ECHA REACH deadlines accelerate replacement cycles for phthalate-containing legacy stocks.
- Reusable Septa:Engineered fluoropolymer laminates withstand 500+ puncture cycles in headspace analyzers and process gas chromatographs. Demand clusters in Swiss pharmaceutical manufacturing corridors where instrument uptime economics justify premium unit pricing over total cost of ownership calculations.
- Specialty Septa:Pre-slit or bonded configurations for specific autosampler models in environmental testing laboratories.
- Crimped Septa:Factory-assembled vial-seal combinations for biopharma aseptic processing lines requiring validated closure integrity.
Disposable formats lead volumes today; specialty configurations are gaining share fastest.
Material:
Material selection tracks thermal stability requirements against solvent compatibility constraints in target applications.
- Silicone:Platinum-cured formulations deliver thermal stability exceeding 300°C with minimal bleed profiles, absorbing functional requirements previously distributed across butyl and natural rubber alternatives. German pharmaceutical quality control laboratories have accelerated adoption timelines as ECHA REACH Annex XVII restrictions eliminate flexible PVC competitors.
- PTFE:Laminated fluoropolymer barriers provide chemical inertness for solvent-rich environmental testing protocols including EPA Method 8260 volatile organic compound analysis. Swiss groundwater monitoring labs and Dutch air quality stations specify these formulations for extractables-sensitive workflows.
- Butyl:Lower-cost option retained in legacy instrument bases with moderate temperature requirements.
- Rubber:General-purpose formulations declining in premium applications due to bleed characteristics.
Silicone dominates current procurement; PTFE laminates are expanding most quickly in environmental compliance testing.
Application:
Regulatory stringency tiers segment demand between certified and uncertified product specifications.
- Pharmaceutical Analysis:FDA extractables and leachables documentation requirements govern septa selection for drug product contact applications. German and Swiss quality control laboratories specify validated platinum-cured silicone with documented batch consistency for method transfer protocols.
- Environmental Testing:EPA Method compliance mandates certified low-bleed septa for volatile organic compound analysis in groundwater and air monitoring. Dutch environmental agencies and Bavarian state laboratories drive concentrated demand for PTFE-silicone laminates meeting documented performance thresholds.
- Food Testing:Migration testing protocols for packaging and contact materials.
- Clinical Diagnostics:High-sensitivity mass spectrometry workflows in hospital laboratories.
Pharmaceutical analysis anchors revenue today; clinical diagnostics shows steepest expansion trajectory.
End User:
Procurement authority concentration reshapes vendor relationships across customer categories.
- Pharmaceutical Companies:Consolidated global category management at headquarters level displaces distributed site purchasing, centralizing specification authority under negotiated performance guarantees. German and Swiss manufacturing corridors exhibit tightest procurement concentration with multi-site consumable standardization mandates.
- Laboratories:Independent analytical service providers and academic facilities with fragmented purchasing patterns.
- Research Institutions:Grant-funded operations with price-sensitive procurement and extended qualification timelines.
- Biotechnology Firms:Single-use system integrators driving pre-sterilized assembly demand for mammalian cell culture operations.
Pharmaceutical companies command largest contract values; biotechnology firms are scaling procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German analytical chemists and Swiss pharmaceutical technicians anchor the highest concentration of advanced green septa expertise in Europe, with Bavarian instrument clusters driving premium-grade specification authority.
Germany
Bavarian chromatography labs in Munich and Regensburg drive concentrated demand for platinum-cured silicone septa capable of withstanding repeated autosampler punctures above 200°C. ECHA REACH Annex XVII restrictions on phthalate plasticizers compel pharmaceutical manufacturers across Baden-Württemberg and North Rhine-Westphalia to replace legacy septa stocks before compliance deadlines. The country's national chemical regulator enforces strict extractables documentation for drug contact applications.
Switzerland
Swiss pharmaceutical quality control corridors around Basel specify validated low-bleed septa with documented batch consistency for method transfer protocols between manufacturing sites. Swissmedic maintains extractables and leachables standards for consumables contacting drug products throughout production workflows. The Basel-Land instrument cluster concentrates procurement authority for multi-site consumable standardization mandates.
United States
EPA Method 8260 compliance mandates drive certified septa procurement for volatile organic compound analysis in environmental testing laboratories across the Midwest and Southeast. FDA extractables documentation requirements govern septa selection for pharmaceutical applications in the Boston-Cambridge biotech corridor and New Jersey manufacturing belt. The Research Triangle analytical cluster in North Carolina anchors environmental compliance testing demand.
Netherlands
Dutch environmental agencies in Utrecht and air quality monitoring stations specify PTFE-silicone laminate septa for extractables-sensitive groundwater and atmospheric analysis workflows. The country's national environmental regulator enforces performance thresholds for certified low-bleed consumables in compliance testing applications. The Randstad laboratory services cluster concentrates procurement for multi-site analytical service providers.
Japan
Japanese pharmaceutical quality control laboratories in the Kanto region adopt platinum-cured silicone formulations at accelerated replacement cycles for high-temperature gas chromatography inlets. METI guidelines on chemical substance management influence material selection for laboratory consumables in domestic manufacturing operations. The Kansai analytical instrument corridor around Osaka drives demand for precision-manufactured barrier discs with validated thermal stability profiles.
Advanced Green Septa Market Competitive Landscape
The competitive structure tilts toward diversified analytical instrument manufacturers with captive consumables ecosystems. Market positioning concentrates among three archetypes: integrated instrument-consumables platforms, specialty chemical compounders with upstream silicone control, and application-focused formulation specialists. Dominant competitive moves include strategic partnerships between instrument OEMs and consumables suppliers, plus portfolio diversification into certified sustainable product tiers.
Among integrated platform providers, Agilent anchors the instrument-captive consumables archetype, while Merck exemplifies chemical compounders with in-house silicone precursor supply. Restek Corporation occupies a position within the application-specialist tier focused on environmental compliance testing formulations. These three represent distinct strategic postures rather than comparable scale positions, with each leveraging different control points across the value chain from raw material qualification through end-user method validation.
| Leading Market Players |
|---|
| Shimadzu |
| Agilent |
| Merck |
| PerkinElmer |
| Restek Corporation |
| GL Sciences Inc. |
| Chromatography Research Supplies |
| Worldwide Glass Resources |
| Pawling Engineered Products |
| Others |
Pricing and Supply Chain Analysis
Platinum catalyst costs cascade through three distinct pricing tiers as Bavarian pharmaceutical laboratories negotiate volume contracts against Swiss manufacturing corridors demanding validated batch documentation. This raw material anchor splits procurement between spot-market commodity silicone and captive precursor supply, with ECHA REACH compliance premiums widening spreads between certified and uncertified product lines.
Pricing Analysis
Bundled instrument-consumables contracts dominate enterprise procurement while unbundled standalone purchases persist in fragmented academic and independent laboratory channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with FDA-validated extractables documentation commanding substantial premiums over uncertified alternatives. Cost compression in economy tiers is intensifying because commodity silicone compounders from Asia-Pacific are qualifying REACH-compliant formulations under accelerated timelines. Academic research institutions exhibit highest price sensitivity, while Swiss pharmaceutical quality control corridors demonstrate lowest sensitivity due to method validation lock-in costs.
Supply Chain Analysis
Certification and qualification gating concentrates supply authority among platinum-cured silicone compounders with documented ECHA REACH Annex XVII compliance, freezing out flexible PVC and phthalate-containing legacy producers. Manufacturing gravity centers on Germany, Switzerland, and Japan, with German specialty chemical producers anchoring European supply and Osaka-area precision manufacturers serving Asian demand. Raw material flows draw from platinum group metal refiners, high-purity silicone precursor plants, and fluoropolymer laminate processors. Single-source vulnerability concentrates in PTFE feedstock allocation decisions among limited chemical processors. Distribution runs through direct manufacturer contracts with multinational pharmaceutical headquarters, displacing regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between German regulatory compliance costs and Swiss premium-validation pricing, with ECHA REACH enforcement timelines creating procurement urgency differentials across the European laboratory corridor.
For Market Incumbents: Acquire specialized silicone compounding facilities with existing ECHA REACH certification to secure precursor supply against platinum price volatility and emerging Asian competition. Consolidate procurement relationships with Bavarian chromatography clusters before qualification timelines compress further. Defend against specialty environmental testing entrants by locking EPA Method 8260 performance guarantees into multi-year contracts. For New Entrants and Emerging Players: Independent analytical service providers represent the most penetrable channel partner type, as fragmented purchasing patterns lack consolidated negotiation leverage and extended qualification timelines favor agile suppliers. Target Dutch environmental agencies and air quality monitoring stations with PTFE-silicone laminate formulations priced below incumbent premiums. Penetrate through direct technical sales emphasizing documented extractables profiles rather than brand heritage. For Investors and Strategic Acquirers: Consolidation pressure builds where specialty silicone compounders face margin compression from commodity-grade competitors while holding irreplaceable ECHA REACH certification assets. Long-term viability favors upstream-integrated players with captive precursor supply and validated regulatory documentation libraries. Watch for PFAS reclassification announcements as the critical inflection signal threatening PTFE-containing laminate valuations and forcing material transition investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Precursor Supply | Merck's captive raw material control insulates margins from platinum commodity swings. |
| Green Certification Program Expansion | EU Green Deal procurement weighting advantages certified sustainable suppliers in German tenders. |
| Long-term Supply Agreement with Instrument OEMs | Agilent's captive consumables ecosystem locks replacement revenue through platform bundling. |
| Specialist Firm Acquisition in Environmental Testing Formulations | Restek's application-specific focus captures EPA Method compliance demand in Dutch laboratories. |
| Joint Venture for PFAS-Free Material Development | Anticipatory PTFE transition partnerships hedge against European regulator reclassification risk. |
Research Methodology
Bottom-up pharmaceutical and environmental laboratory modeling reconciled against top-down platinum-cured silicone production tracking forms the analytical core of this study. Primary interviews with chromatography lab managers, pharmaceutical procurement directors, regulatory affairs specialists, and specialty chemical compounders combined with secondary validation from ECHA REACH registration databases, FDA extractables guidance documents, EPA Method compliance protocols, and German chemical industry association reports. Triangulation between demand-side instrument deployment counts and supply-side manufacturing capacity assessments calibrated volume estimates.
Historical trendline analysis of replacement cycle acceleration and regulatory compliance deadline clustering informed projection mechanics across the analysis window. Segmentation modeling incorporated product type integration level, material certification tier, application regulatory stringency, and end-user procurement concentration dimensions. CAGRs derived from instrument density growth rates, REACH enforcement phase-in schedules, and environmental testing protocol expansion trajectories. Platinum price volatility scenarios and pending PFAS regulatory reviews served as sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA enforcement intensity, PFAS reclassification timing, and platinum group metal supply disruptions. Forecasts reflect documented assumptions regarding regulatory implementation schedules and laboratory capital expenditure patterns. A model refresh is warranted upon material change in REACH Annex XVII amendment proposals or EPA Method revision announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
PVB Interlayers Market
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Jesmonite Market
Specialty Materials
Retro Reflective Materials Market
Specialty Materials
Nanoencapsulation Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Charge Generation Materials (CGM) Market
Specialty Materials
Special Graphite Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Global Flexible Substrates Market
Specialty Materials
Global Supplementary Cementitious Materials Market
Specialty Materials
Global Ajinomoto Build-Up Film Substrate Market
Specialty Materials
Silicone Gel Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Colloidal Silica Market