
 Electrode Paste Market | 2026-2036
Electrode Paste Market Size, Share, and Industry Trends Forecast 2026-2036
Electrode Paste Market Analysis
Buyer concentration among battery manufacturers is pivoting as tier-one cell makers consolidate electrode paste procurement through long-term offtake agreements. Energoprom Group leverages captive petroleum coke refining in Siberia to secure raw material cost advantages. Yangguang Carbon anchors its position through vertical integration into needle coke calcination, while Graphite India competes via specialized high-purity formulations for electric vehicle anodes.
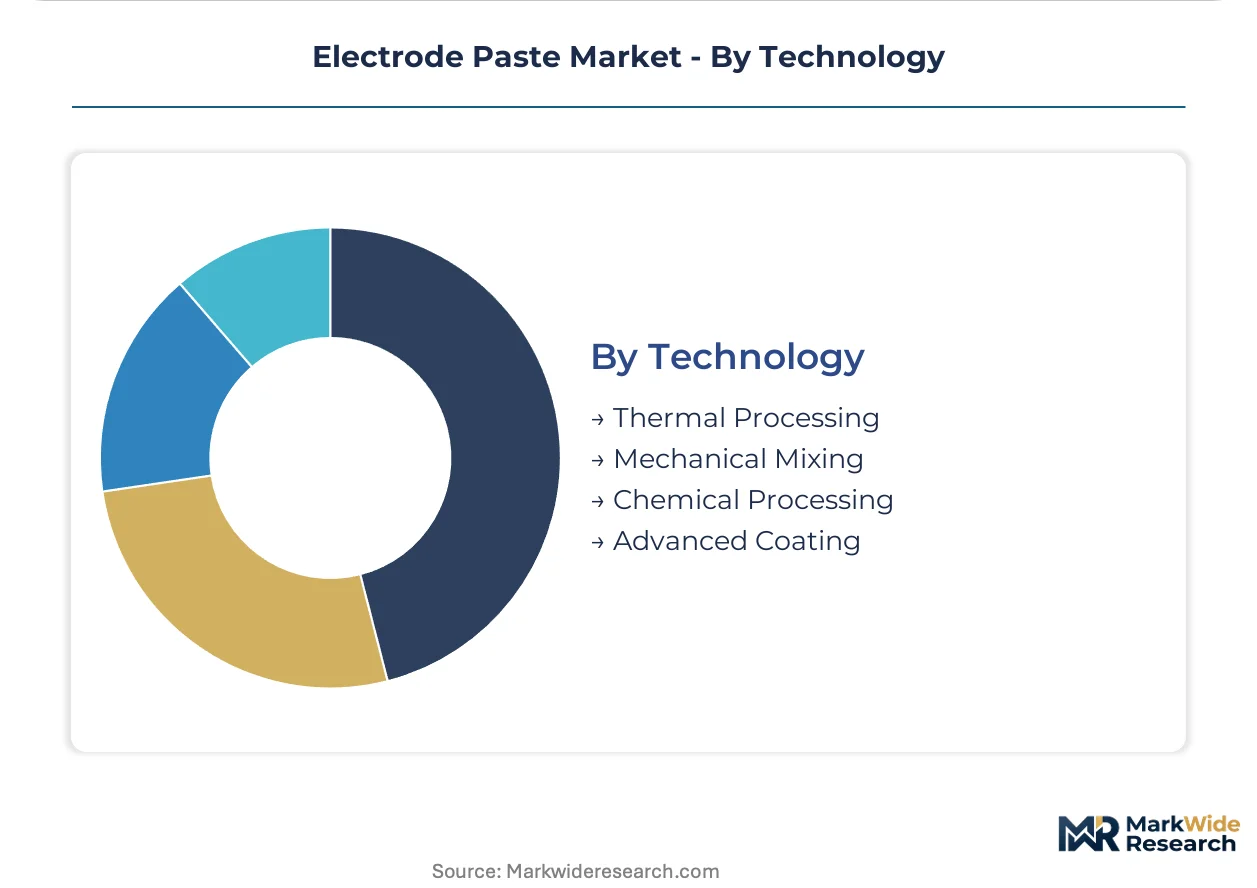
Electrode paste comprises a carbonaceous binder system—typically coal tar pitch, petroleum coke, and anthracite fines—thermally processed to achieve specific electrical resistivity below 60 μΩ·m and ash content under 3%, serving as the conductive interface in aluminum smelting and lithium-ion battery electrodes. Graphite paste leads product type revenue due to its established use in electric vehicle energy storage systems, though polymer paste represents the fastest-growing category as solid-state battery architectures demand compliant binder chemistries. Thermal processing technology dominates manufacturing scale, while advanced coating methods capture expanding margin pools from precision-thickness anode production.
China's MEE enforces GB standards on volatile organic compound emissions from pitch impregnation facilities, while the EU Green Deal's carbon border adjustments reshape export competitiveness for Indian and Ukrainian producers. India's BIS certification requirements for battery materials are tightening product consistency benchmarks for imports. Stakeholders must monitor how divergent carbon accounting rules across Beijing, Brussels, and New Delhi redefine cost structures for cross-border paste supply.
Market Dynamics
Battery-grade paste specifications are tightening as automakers impose sub-50 μΩ·m resistivity thresholds, forcing reformulation of coal tar pitch binders and calcination protocols across the supplier base.
Growth Catalysts
- GB 31570-2015 Emission Standards:China's MEE mandates closed-system pitch impregnation, accelerating capital deployment into compliant thermal processing infrastructure.
- Lithium-ion Gigafactory Expansion:Anode material clusters in Jiangsu and Shandong provinces concentrate demand for high-purity graphite paste feedstock.
- Dual Carbon Policy:Beijing's 2060 neutrality target redirects petroleum coke procurement toward low-sulfur Siberian and Middle Eastern sources.
Market Restraints
- Needle Coke Supply Concentration:Premium feedstock for ultra-high power electrodes remains captive to three integrated refiners in Japan and the United States.
- Pitch Volatility:Coal tar distillate prices swing with coking coal output from Shanxi province, compressing blending margin predictability.
- Synthetic Graphite Substitution:Silicon-carbon composite anodes threaten graphite paste volume in next-generation cells above 300 Wh/kg energy density.
Strategic Opportunities
- Solid-State Battery Architectures:Polymer paste compliant with sulfide electrolyte interfaces opens formulation contracts with Korean and Japanese cell developers.
- EU Carbon Border Adjustment:Indian calciners investing in renewable-powered kiln retrofits gain export price advantage into European anode supply chains.
- Direct Procurement Platforms:CATL and BYD are piloting blockchain-tracked offtake agreements, disintermediating traditional distributor networks.
Industry Challenges
- Carbon Footprint Certification:Scope 3 accounting for petroleum coke provenance requires metallurgical traceability systems most mid-tier blenders lack.
- Thermal Processing Talent:Retirements among pitch rheology specialists constrain plant commissioning schedules for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrode Paste Market |
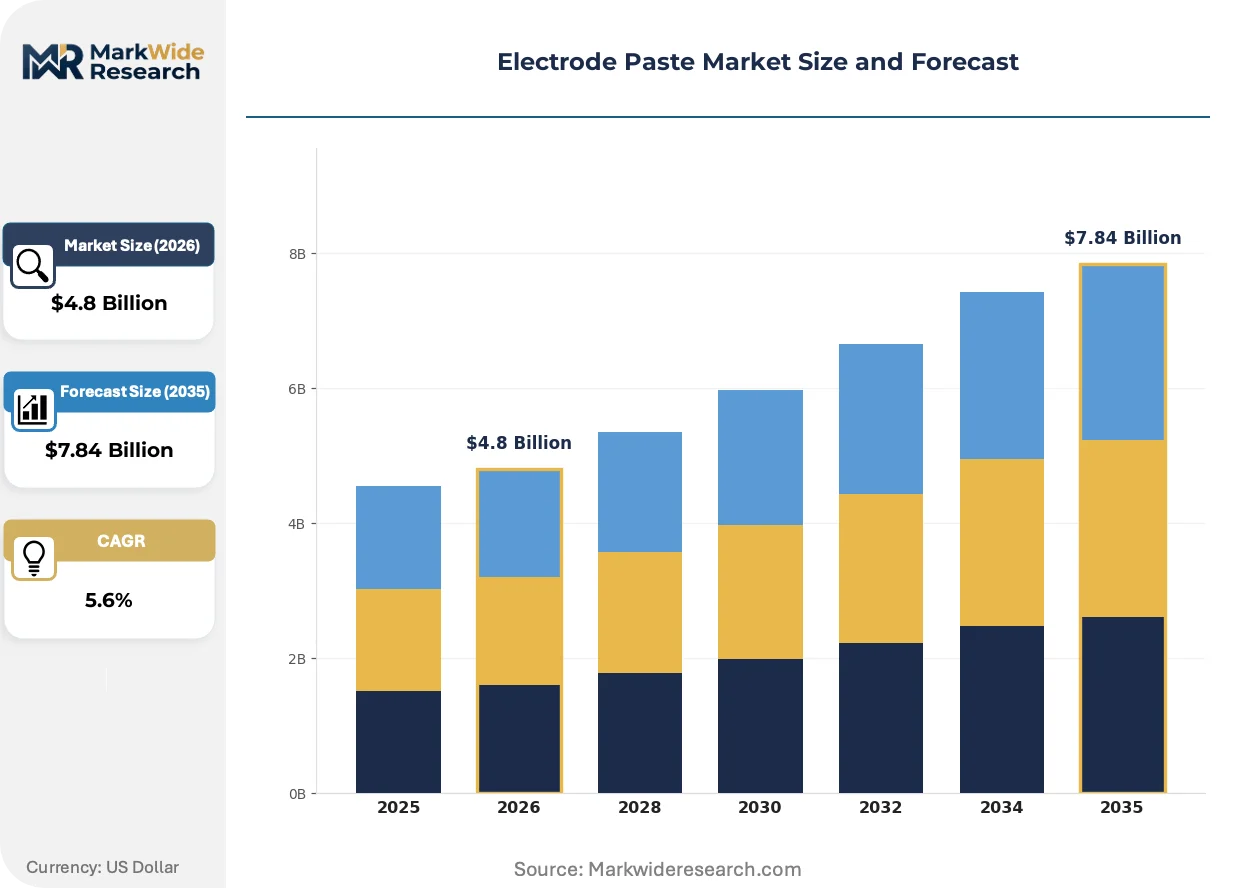
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphite Paste, Conductive Paste, Carbon Paste, Polymer Paste End User: Battery Manufacturers, Electronics Industry, Renewable Energy Companies, Automotive Sector Application: Electric Vehicles, Energy Storage Systems, Solar Panels, Industrial Equipment Technology: Thermal Processing, Mechanical Mixing, Chemical Processing, Advanced Coating |
| Companies Covered | Energoprom Group, Ukrainskiy Grafit, Yangguang Carbon, Graphite India, Rheinfelden Carbon, Elkem, Tokai COBEX, India Carbon, Rongxing Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrode Paste Market Emerging Trajectories
Formulation chemistry is pivoting toward solid-state compatibility while thermal processing equipment digitizes for precision thickness control. Regulatory carbon accounting is becoming a competitive differentiator in contract negotiations.
Polymer-based electrode paste is absorbing binder development resources previously allocated to conventional pitch systems. Solid-state battery developers in Japan and South Korea are qualifying sulfide-compatible polymer formulations for pilot production lines. This absorption of R&D capacity is compressing innovation timelines for legacy graphite paste architectures.
REACH SVHC disclosure requirements are forcing European importers to document coal tar pitch constituent toxicity down to 0.1% concentration thresholds. The industrial consequence is supplier consolidation toward integrated producers with in-house analytical laboratories. Battery anode applications face the steepest compliance cost escalation, redirecting some procurement toward Middle Eastern sources with pre-certified material streams.
Long-term offtake contracting is displacing spot market purchasing for battery-grade material. Tier-one cell makers now lock eighteen-to-thirty-six month supply agreements directly with calciners, bypassing regional distributors. This pattern is most visible in China's Yangtze River Delta, where CATL's procurement team maintains resident engineers at key paste production facilities.
Electrode Paste Market Segmentation
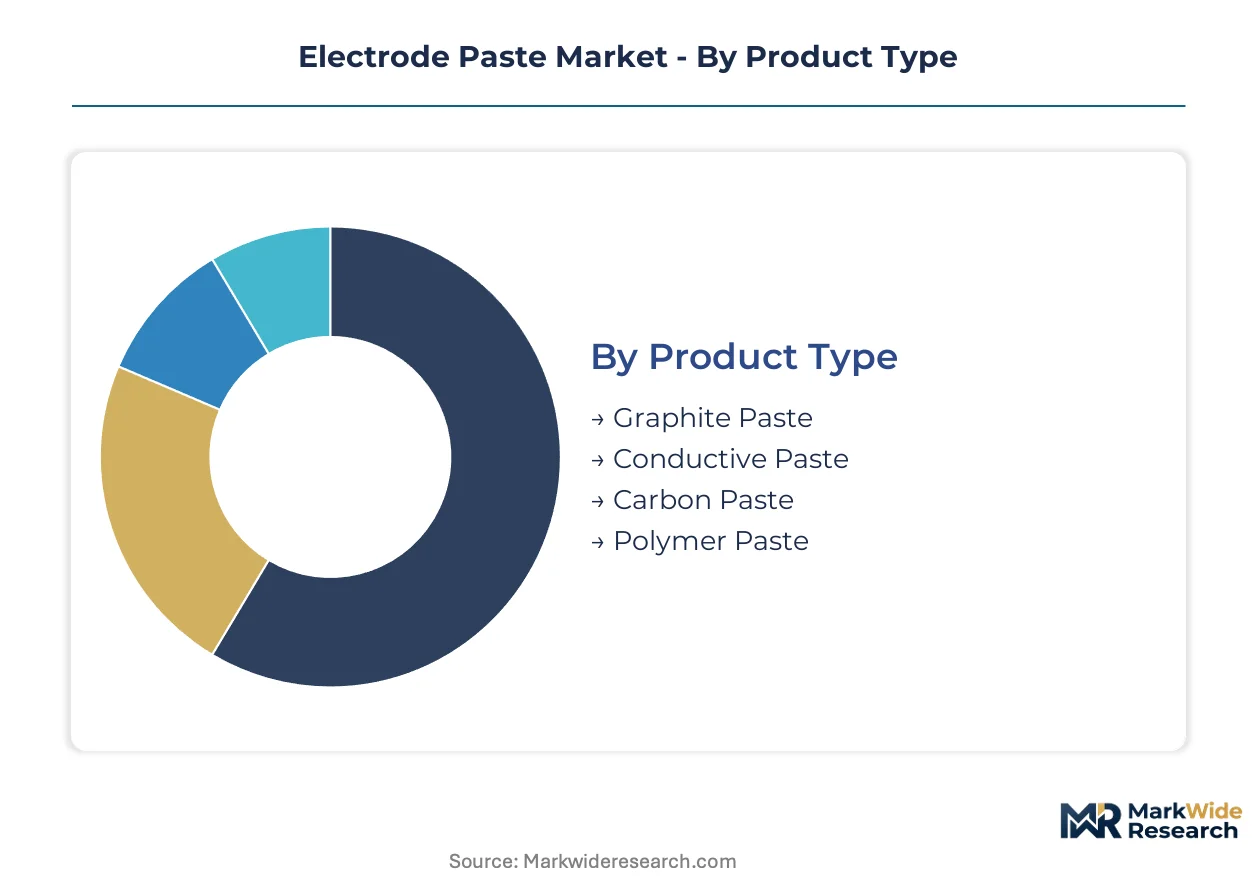
Electrode paste procurement patterns diverge sharply across formulation chemistry, end-use specifications, and processing technology. Understanding these segment boundaries clarifies where margin pools concentrate and which technical specifications command pricing premiums.
Product Type:
Supply concentration in needle coke and coal tar pitch refining creates divergent cost positions across paste categories, with captive feedstock access determining competitive viability.
- Graphite Paste:Formulated from calcined petroleum coke and coal tar pitch binders, achieving electrical resistivity below 60 μΩ·m and ash content under 3% for battery anode applications. Demand concentrates in East China's Jiangsu and Shandong provinces where CATL and BYD supply chains source high-purity formulations for lithium-ion cell assembly.
- Polymer Paste:Sulfide-compatible binder systems engineered for solid-state battery architectures, replacing conventional pitch chemistries with compliant polymer electrolyte interfaces. Korean and Japanese cell developers are qualifying these formulations for pilot production lines, absorbing R&D resources previously allocated to legacy graphite systems.
- Conductive Paste:Carbon black and graphite flake suspensions optimized for printed electronics and current collector coatings.
- Carbon Paste:Anthracite-based formulations serving aluminum smelting electrodes and industrial furnace applications.
Today's leader: Graphite Paste. Tomorrow's challenger: Polymer Paste.
End User:
Procurement scale and specification stringency vary dramatically across customer categories, with battery-grade contracts demanding sub-50 μΩ·m resistivity thresholds that exclude general industrial suppliers.
- Battery Manufacturers:Tier-one cell makers now lock eighteen-to-thirty-six month direct offtake agreements with calciners, bypassing regional distributors. CATL maintains resident engineers at key production facilities in China's Yangtze River Delta to enforce quality protocols.
- Automotive Sector:OEMs impose cascading specifications through their cell supplier tiers, requiring documented carbon footprint certification and Scope 3 petroleum coke provenance that mid-tier blenders struggle to provide.
- Electronics Industry:Printed circuit board and display manufacturers source conductive pastes for EMI shielding and flexible circuit applications.
- Renewable Energy Companies:Utility-scale solar and wind developers procure paste for inverter components and grid storage integration hardware.
Volume concentrates with Battery Manufacturers. Margin expansion tracks toward Automotive Sector certification requirements.
Application:
Performance specifications harden fastest in mobility and grid storage applications, where cycle life and energy density targets force reformulation of binder systems and calcination protocols.
- Electric Vehicles:Silicon-carbon composite anodes threaten graphite paste volume in next-generation cells above 300 Wh/kg energy density, though current generation vehicles sustain demand for established graphite formulations.
- Energy Storage Systems:Grid-scale battery installations require paste consistency across multi-gigawatt hour deployments, favoring suppliers with thermal processing equipment digitized for precision thickness control.
- Solar Panels:Conductive paste applications in photovoltaic cell metallization face price pressure from silver paste substitution trends.
- Industrial Equipment:Arc furnace electrodes and aluminum smelting consume carbon paste formulations with less stringent purity requirements than battery grades.
Electric Vehicles anchor current revenue. Energy Storage Systems offer the steepest expansion trajectory as grid deployment accelerates.
Technology:
Capital intensity and technical barrier height separate established thermal processors from entrants attempting to scale alternative manufacturing approaches.
- Thermal Processing:Rotary kiln and vertical shaft calcination dominates manufacturing scale, with China's MEE GB 31570-2015 emission standards mandating closed-system pitch impregnation that accelerates capital deployment into compliant infrastructure.
- Advanced Coating:Precision-thickness anode production for solid-state architectures captures expanding margin pools, requiring equipment integration with downstream cell assembly lines.
- Mechanical Mixing:Conventional blending operations serve industrial-grade paste specifications with lower barrier to entry.
- Chemical Processing:Solvent-based purification and surface modification techniques address specialized high-purity requirements.
Thermal Processing holds installed capacity advantage. Advanced Coating is climbing the fastest as solid-state qualification timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands electrode paste procurement volumes while India scales domestic calcination capacity to serve battery anode supply chains. Divergent carbon accounting rules across Beijing, Brussels, and New Delhi reshape cross-border competitiveness.
China
CATL and BYD procurement teams source graphite paste from anode material clusters in Jiangsu and Shandong provinces. The MEE enforces GB 31570-2015 emission standards mandating closed-system pitch impregnation, accelerating capital deployment into compliant thermal processing infrastructure. Yangguang Carbon anchors supply security through backward integration into needle coke calcination.
India
BIS certification requirements tighten product consistency benchmarks for battery material imports. Domestic calciners in Odisha and Jharkhand retrofit kilns with renewable power to capture EU Carbon Border Adjustment advantages. Graphite India competes via specialized high-purity formulations for electric vehicle anodes.
Germany
Automotive OEMs impose cascading specifications through cell supplier tiers, requiring documented Scope 3 petroleum coke provenance. REACH SVHC disclosure requirements force importers to document coal tar pitch constituent toxicity down to 0.1% thresholds. Rheinfelden Carbon serves industrial electrode applications from production facilities in the Baden-Württemberg region.
Japan
Solid-state battery developers in Nagoya and Osaka prefectures qualify sulfide-compatible polymer paste formulations for pilot production lines. METI procurement guidelines favor domestic suppliers with certified carbon footprint traceability. Tokai COBEX occupies a position within the premium electrode materials tier.
United States
Domestic anode producers seek needle coke supply alternatives as premium feedstock remains captive to integrated refiners. EPA emission standards for pitch impregnation facilities constrain greenfield project economics. Elkem exemplifies the diversified materials conglomerate archetype serving multiple industrial end-uses.
Electrode Paste Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and thermal processing capabilities. The supplier base fragments into three tiers: integrated refiners with captive petroleum coke supply, independent blenders serving regional industrial markets, and emerging polymer paste developers targeting solid-state architectures. Strategic differentiation hinges on backward integration into needle coke calcination, carbon footprint certification systems, and direct offtake contracting with tier-one cell makers.
Among Russian and Ukrainian producers, Energoprom Group and Ukrainskiy Grafit represent the resource-backed archetype leveraging Siberian petroleum coke refining for raw material cost advantages. Within the Asian pure-play tier, Rongxing Group exemplifies focused electrode paste specialization. These three anchors illustrate how geographic feedstock access and vertical integration depth determine competitive positioning in procurement negotiations with battery manufacturers.
| Leading Market Players |
|---|
| Energoprom Group |
| Ukrainskiy Grafit |
| Yangguang Carbon |
| Graphite India |
| Rheinfelden Carbon |
| Elkem |
| Tokai COBEX |
| India Carbon |
| Rongxing Group |
| Others |
Supply Flow & Price Mechanics
Performance-grade bifurcation between battery-certified and industrial-grade electrode paste manifests in divergent contract structures and sourcing footprints. Premium formulations commanding sub-50 μΩ·m resistivity thresholds lock into eighteen-to-thirty-six month offtake agreements with CATL and BYD procurement teams, while commodity carbon paste for aluminum smelting trades on spot-indexed coal tar pitch pricing.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for thermal-processed graphite paste as renewable-powered kiln retrofits compress production cost differentials. Three-tier pricing structure across premium, standard, and economy levels separates battery-grade certified material from industrial electrode formulations and uncertified commodity blends. Pricing pressure stems from silicon-carbon composite anode substitution in next-generation cells above 300 Wh/kg energy density. Battery manufacturers exhibit lowest price sensitivity due to qualification timelines, while aluminum smelters negotiate aggressively on volume.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's dual carbon goals are reshaping sourcing patterns toward captive petroleum coke refining and regional calcination clusters. Supply concentrates in China, India, and Japan as needle coke feedstock draws from integrated refiners in the United States and Japan. Raw material dependencies center on low-sulfur petroleum coke, coal tar pitch from Shanxi province coking operations, and anthracite fines. Single-source vulnerability in premium needle coke supply constrains formulation flexibility for ultra-high power grades. Distribution runs through direct procurement platforms piloting blockchain-tracked offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrode paste procurement functions as a geographic-arbitrage play between China's Yangtze River Delta clusters and India's emerging Odisha-Jharkhand calcination corridor, exploiting divergent carbon accounting rules under EU Green Deal border adjustments.
For Market Incumbents: Anchor market position through backward integration into needle coke calcination and captive petroleum coke refining, mirroring Yangguang Carbon's Siberian supply chain model. Invest in GB 31570-2015 compliant closed-system pitch impregnation infrastructure before regulatory enforcement tightens. Defend against polymer paste substitution by locking long-term offtake agreements with solid-state battery developers during qualification windows. For New Entrants and Emerging Players: Solid-state compatible polymer paste formulations offer the most penetrable wedge for Korean and Japanese cell developer supply chains, where sulfide electrolyte interfaces demand compliant binder chemistries. Target India's domestic calcination capacity expansion as BIS certification requirements displace import-dependent battery material sourcing. Pursue qualification partnerships with tier-two automotive cell suppliers lacking resident engineer resources at established facilities. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier blenders lack Scope 3 petroleum coke provenance systems for automotive OEM carbon footprint certification. Long-term viability favors integrated producers with in-house analytical laboratories capable of REACH SVHC disclosure down to 0.1% concentration thresholds. Acquisition target archetype: regional calciners with renewable power purchase agreements and EU Carbon Border Adjustment compliance positioning. Watch for inflection when CATL and BYD procurement teams extend blockchain-tracked direct offtake pilots beyond Yangtze River Delta clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle Coke Calcination | Captive feedstock access secures margin protection against premium petroleum coke supply concentration. |
| GB 31570-2015 Compliant Thermal Processing Infrastructure | Closed-system pitch impregnation capacity enables continued access to China's Jiangsu and Shandong demand clusters. |
| Solid-State Polymer Paste Qualification | Sulfide-compatible binder development opens formulation contracts with Korean and Japanese cell developers. |
| Renewable-Powered Kiln Retrofit | Clean energy transition positions Indian calciners for EU Carbon Border Adjustment export advantages. |
| Blockchain-Tracked Direct Procurement Platform | Disintermediation of distributor networks aligns with CATL and BYD procurement team preferences. |
Methodological Framework
Bottom-up battery manufacturer procurement modeling reconciled against top-down petroleum coke and coal tar pitch supply tracking forms the analytical core of this study. Primary interviews with electrode paste plant managers, procurement leads at CATL and BYD, distribution channel partners in East China, and technical R&D directors at solid-state battery developers combined with secondary validation from customs and trade data, SEC filings of diversified materials conglomerates, and GB standards documentation. Triangulation across these sources ensures demand-side consumption patterns align with supply-side production capacity.
Input-output matrices mapping needle coke and pitch feedstock flows through calcination, blending, and thermal processing stages generate volume and value outputs across the projection horizon. Segmentation dimensions modeled include formulation chemistry, end-use specification tier, thermal processing versus advanced coating technology, and regional production hub. CAGRs derive from regression analysis of historical procurement patterns and forward-looking gigafactory capacity announcements. Industry-specific forecast inputs incorporate silicon-carbon composite anode substitution curves and solid-state battery pilot production timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to divergence in carbon accounting rules across Beijing, Brussels, and New Delhi and to breakthroughs in sulfide-compatible polymer paste qualification. Forecasts reflect documented assumptions regarding petroleum coke supply concentration, pitch rheology specialist availability, and regulatory enforcement timelines for emission standards. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
PVB Interlayers Market
Specialty Materials
Spermaceti Wax Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Vegan Wax Market
Specialty Materials
Silicone Solutions Market
Specialty Materials
Engineered Foam Market
Specialty Materials
Elastic Films Market
Specialty Materials
Sulphur Bentonite Market
Specialty Materials
Edge Banding Materials Market
Specialty Materials
Silicone Gel Market
Specialty Materials
Global Polybenzimidazoles (PBI) Market
Specialty Materials
Europe Solar Control Window Films Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Silicone Film Market
Specialty Materials
Mesoporous Silica Market