
 Latin America International CEP Market | 2026-2036
Latin America International CEP Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America International CEP Market Foresight
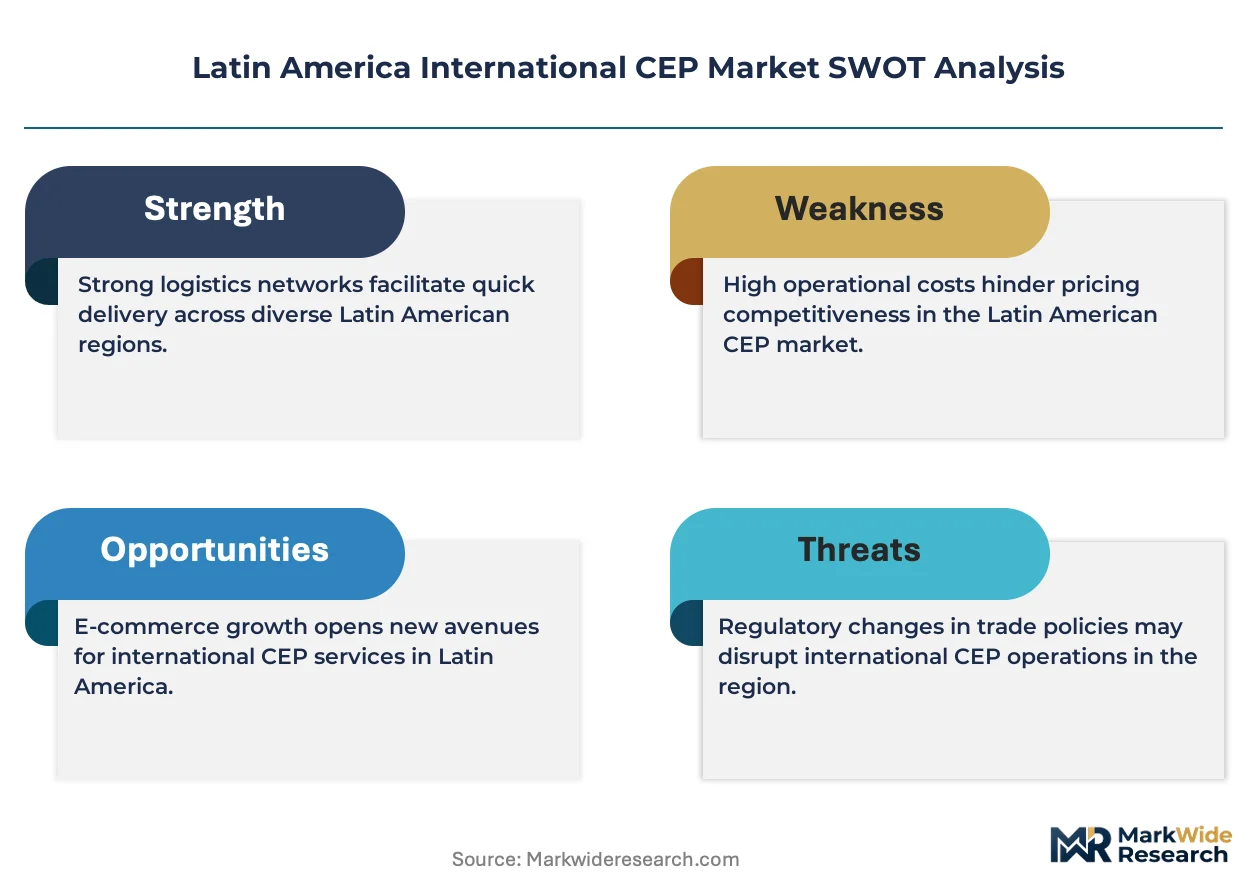
The EU Green Deal's extraterritorial emissions disclosure requirements for maritime and air cargo is consolidating compliance burdens onto Latin American logistics providers serving European trade lanes. DHL Express leverages its integrated customs brokerage network to preemptively certify carbon reporting across Brazilian and Mexican export hubs. FedEx Corporation anchors trans-Pacific capacity through its Miami gateway, sustaining direct connections to Colombian and Chilean manufacturing zones. DB Schenker specializes in automotive parts logistics, competing for contract wins with Mexican maquiladora operations supplying North American assembly plants.
Latin America International CEP encompasses cross-border courier, express, and parcel services moving shipments under seventy kilograms across international boundaries, typically utilizing multimodal coordination combining scheduled airline belly cargo, dedicated freighter aircraft, and last-mile ground distribution. The sector operates through time-definite service level agreements measured in delivery windows from next-morning to economy five-day options. Express Delivery dominates revenue contribution due to premium pricing on urgent shipments, while Freight Forwarding captures volume leadership on heavier consolidated consignments. E-commerce end users represent the fastest-expanding demand pool, though Business-to-Business delivery models still command superior per-unit margins from contractual enterprise accounts.
Receita Federal in Brazil, SAT in Mexico, and Chile's Aduana Nacional enforce divergent customs documentation standards that fragment cross-border operational templates. The EU's Carbon Border Adjustment Mechanism and forthcoming CSRD scope-three disclosure rules will compel Latin American CEP providers to invest in emissions tracking infrastructure. Stakeholders must monitor whether Mercosur-EU trade ratification accelerates harmonized customs protocols or preserves national regulatory fragmentation that favors localized specialists over integrated multinational networks.
Market Dynamics
Cross-border e-commerce volumes from Brazilian and Mexican digital marketplaces are compressing delivery windows and forcing multimodal network reconfigurations across the São Paulo–Santos logistics corridor.
Growth Catalysts
- Receita Federal electronic invoicing mandates:Brazil's customs modernization is accelerating clearance velocity for express parcels entering South America's largest consumer market.
- Maquiladora manufacturing clusters:Mexican border plants supplying North American automotive and electronics assembly lines are generating recurring time-definite freight demand.
- Scheduled freighter capacity expansion:Dedicated cargo aircraft deployments on trans-Pacific and trans-Atlantic lanes are absorbing e-commerce volume surges that belly cargo cannot accommodate.
Market Restraints
- Jet fuel price volatility:Express operators dependent on air cargo face margin compression when aviation kerosene benchmarks spike without contractual fuel surcharge recovery.
- Customs documentation fragmentation:Divergent SAT, Receita Federal, and Aduana Nacional standards force redundant compliance investments that standardized networks cannot amortize.
- Road infrastructure deficits:Last-mile ground distribution in Andean and Central American corridors suffers from inadequate highway maintenance and bridge capacity constraints.
Strategic Opportunities
- Colombian Pacific port development:Buenaventura container terminal expansions offer alternative Asia-Latin America routing that bypasses Panama Canal congestion.
- EU Carbon Border Adjustment Mechanism alignment:Early emissions tracking infrastructure investments position operators for preferred status on Europe-bound trade lanes.
- Chilean lithium supply chain integration:Battery component exports to Asian and North American EV manufacturers require temperature-controlled express logistics with customs pre-clearance.
Industry Challenges
- Licensed customs broker scarcity:Receita Federal and SAT certification requirements outpace training program output, creating clearance bottlenecks at peak volume periods.
- Legacy warehouse management system integration:Mid-tier logistics providers struggle to connect on-premise ERP platforms with cloud-based carrier tracking APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America International CEP Market |
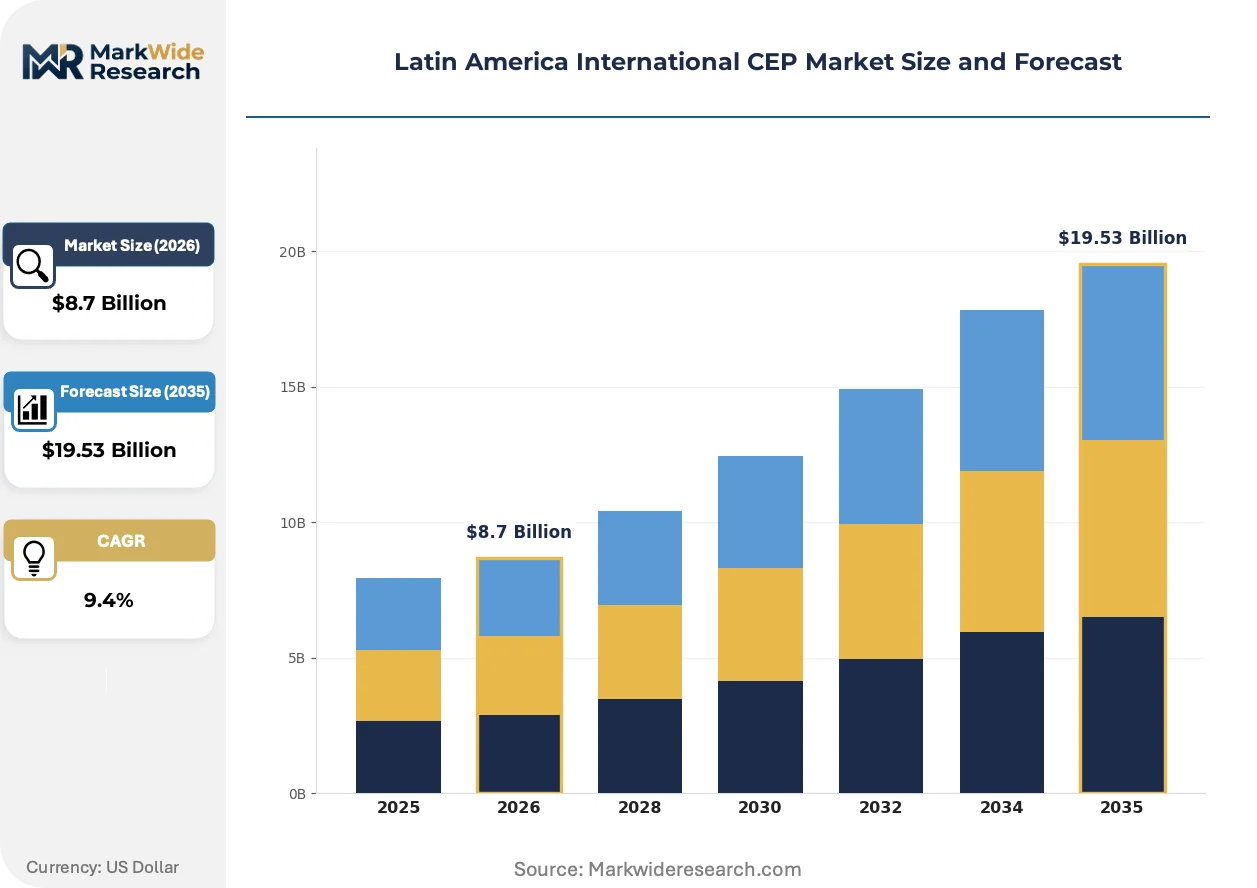
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Freight Forwarding, Warehousing, Same-Day Delivery End User: E-commerce, Retail, Automotive, Pharmaceuticals Technology: Mobile Tracking, Automated Sorting, Route Optimization, RFID Delivery Model: Business-to-Consumer, Business-to-Business, C2C, Hybrid |
| Companies Covered | DHL Express, Aramex, GEFCO, Deprisa, Correos de Chile, United Parcel Service of America, Inc., FedEx Corporation, Kuehne Nagel, DB Schenker, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America International CEP Market Shifts & Advancements
Digital freight platforms and predictive analytics are compressing transit time variability while regulatory emissions disclosure mandates are restructuring carrier selection criteria across European trade lanes.
Blockchain-enabled documentation systems are absorbing paper-based customs processes into immutable distributed ledgers. Brazilian electronics exporters and Colombian flower shippers are piloting these platforms for agricultural and high-value cargo. This technology is absorbing the verification delays that previously extended dwell times at Receita Federal and SAT checkpoints.
CSRD scope-three disclosure rules are compelling emissions tracking infrastructure investments across logistics networks serving European destinations. Latin American CEP providers must now capture and report carbon intensity per shipment-kilometer. Air cargo operators on trans-Atlantic lanes face the steepest compliance cost gradients as they retrofit legacy reporting systems.
Subscription-based delivery models are displacing transactional parcel economics among mid-market e-commerce merchants. Brazilian fashion marketplaces and Mexican consumer electronics platforms are locking in volume commitments with express operators in exchange for guaranteed capacity allocation. Chile and Argentina show the fastest adoption curves as cross-border shopper penetration deepens beyond metropolitan cores.
Latin America International CEP Market Segmentation
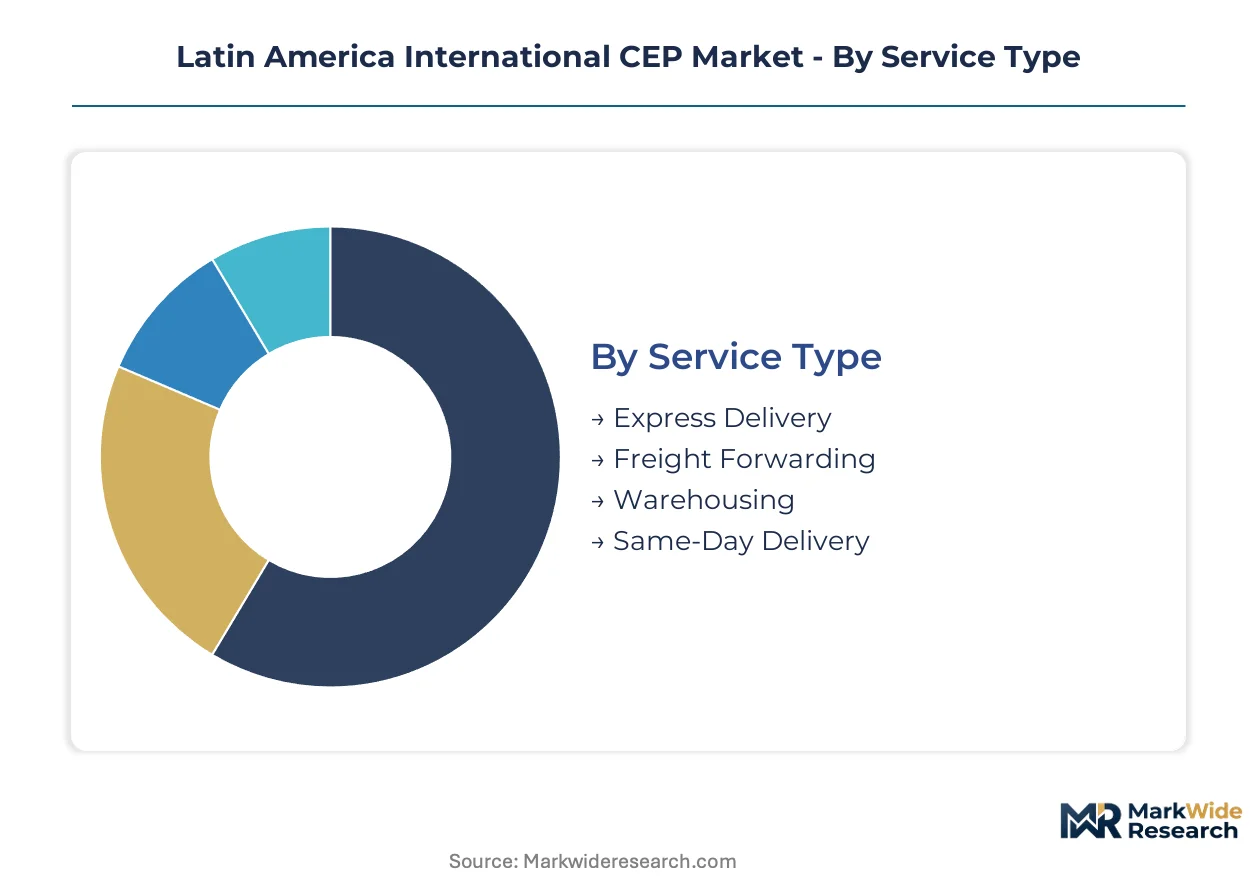
Latin American logistics buyers select CEP providers based on delivery velocity guarantees, customs clearance reliability, and modal flexibility across the São Paulo–Santos corridor. Segmentation reveals how express premiums, e-commerce volume concentration, and digital tracking infrastructure allocate competitive position among operators serving Brazilian, Mexican, and Chilean trade lanes.
Service Type:
Cost tier drives procurement decisions, with buyers trading speed guarantees against freight consolidation economics.
- Express Delivery:Time-definite services utilizing dedicated freighter aircraft and priority belly cargo for shipments requiring next-morning to 48-hour delivery windows. Brazilian fashion marketplaces and Mexican automotive suppliers concentrate demand here, paying premiums for Receita Federal and SAT pre-clearance integration that compresses dwell times.
- Freight Forwarding:Consolidated consignment management combining multiple shipper volumes into containerized or palletized units for cost-efficient trans-Pacific and trans-Atlantic routing. Heavier e-commerce returns and B2B replenishment cycles favor this tier, though margin compression intensifies during jet fuel price spikes.
- Warehousing:Bonded storage and inventory positioning at Miami, São Paulo, and Buenaventura hubs to enable last-mile distribution without repeated customs processing.
- Same-Day Delivery:Ultra-urgent courier services restricted to metropolitan corridors with sufficient ground infrastructure density.
Volume sits with Freight Forwarding; growth tilts toward Express Delivery.
End User:
Application-specific requirements reshape network configuration, from temperature protocols to delivery window flexibility.
- E-commerce:Cross-border parcel flows from Brazilian and Mexican digital marketplaces demanding subscription-based capacity commitments and real-time tracking visibility. Subscription models are displacing transactional economics as shopper penetration deepens beyond São Paulo and Mexico City metropolitan cores.
- Retail:Seasonal inventory replenishment and promotional event surges requiring flexible capacity scaling. Colombian flower exporters and Chilean fruit shippers drive perishable retail logistics with cold-chain express requirements.
- Automotive:Just-in-time parts delivery from Mexican maquiladora clusters to North American assembly plants.
- Pharmaceuticals:Temperature-controlled distribution with chain-of-custody documentation for regulatory compliance.
E-commerce captures volume leadership; pharmaceuticals show the steepest expansion trajectory on EV battery component exports.
Technology:
Customer experience differentiation increasingly depends on digital infrastructure investment depth.
- Mobile Tracking:Smartphone-based shipment visibility with predictive arrival notifications and delivery rescheduling interfaces. Brazilian and Chilean consumers expect this capability as standard, forcing mid-tier operators to upgrade legacy systems.
- Automated Sorting:High-speed parcel handling systems reducing processing time at São Paulo and Miami gateway facilities.
- Route Optimization:Algorithmic last-mile sequencing minimizing fuel consumption and delivery window variance.
- RFID:Contactless inventory verification accelerating customs clearance and reducing documentation errors.
Mobile Tracking dominates customer-facing investment; Automated Sorting delivers operational margin defense.
Delivery Model:
Customer type determines contract structure, with enterprise accounts commanding superior per-unit economics.
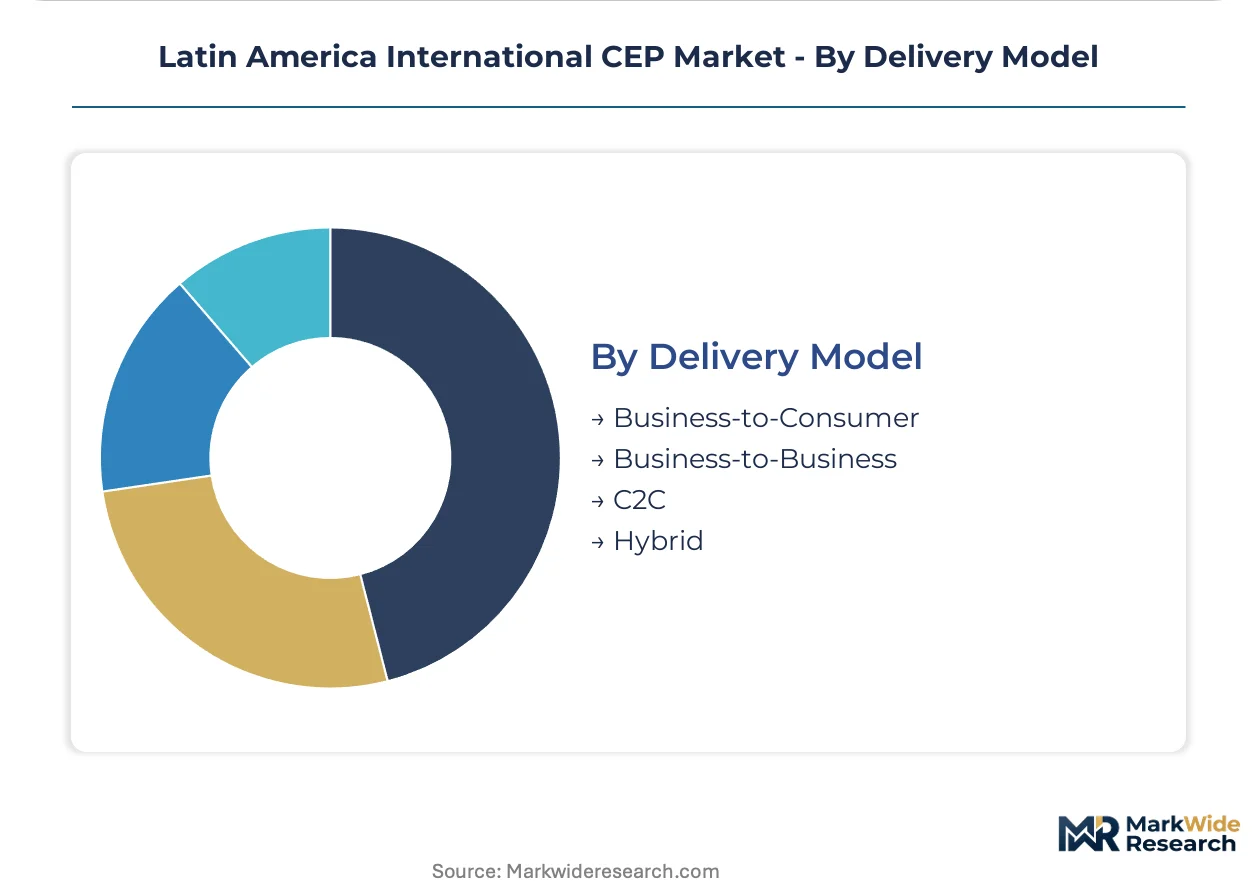
- Business-to-Business:Contractual enterprise relationships with automotive, electronics, and pharmaceutical manufacturers requiring scheduled pickup windows and dedicated account management. Mexican maquiladora operations and Chilean lithium processors anchor this segment with recurring volume commitments.
- Business-to-Consumer:Individual parcel delivery to end recipients, typically e-commerce shoppers, with residential address final-mile complexity. Brazilian cross-border fashion purchases and Mexican consumer electronics orders concentrate here, though per-shipment margins trail B2B benchmarks.
- C2C:Peer-to-peer shipment facilitation for individual sellers on marketplace platforms.
- Hybrid:Integrated models combining B2B origin consolidation with B2C destination distribution.
B2B commands margin superiority; B2C gains share fastest on e-commerce penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of time-definite express services concentrates in Brazilian and Mexican gateway hubs while consumption spreads across Andean and Central American corridors. The São Paulo–Santos logistics axis generates the highest parcel throughput. Cross-border e-commerce demand from Chilean and Colombian metropolitan zones is outpacing local fulfillment capacity.
Brazil
Cross-border fashion marketplace shipments and automotive parts exports drive express volume growth. Receita Federal's electronic invoicing mandates compress customs dwell times at São Paulo-Guarulhos International Airport. The São Paulo–Santos corridor anchors South America's largest air cargo gateway with dedicated freighter capacity expansion planned through 2026.
Mexico
Maquiladora manufacturing clusters generate recurring time-definite freight demand for North American automotive assembly lines. SAT documentation requirements for cross-border shipments enforce strict pre-clearance protocols at Tijuana and Ciudad Juárez border crossings. The Mexico City Metro zone concentrates e-commerce fulfillment infrastructure serving domestic and US-bound parcel flows.
Chile
Lithium battery component exports to Asian EV manufacturers require temperature-controlled express logistics with customs pre-clearance. Aduana Nacional enforces divergent documentation standards that fragment operational templates for European trade lanes. Santiago's Arturo Merino Benítez International Airport hosts expanding perishable cargo capacity for fruit and seafood exports.
Colombia
Flower exporters and coffee traders demand cold-chain express services with real-time tracking visibility. The national customs authority maintains paper-intensive processes that blockchain pilot programs aim to streamline. Buenaventura Pacific port development offers alternative Asia-Latin America routing bypassing Panama Canal congestion.
Argentina
Pharmaceutical and agricultural chemical exports require chain-of-custody documentation for regulatory compliance. The country's central bank foreign exchange restrictions complicate cross-border payment settlements for express operators. Buenos Aires metropolitan logistics zones suffer from last-mile infrastructure deficits and licensed customs broker scarcity.
Latin America International CEP Market Competitive Landscape
The competitive structure tilts toward integrated multinational networks with customs brokerage capabilities over localized specialists. Tiered service differentiation separates premium express operators from freight forwarding consolidators and mid-market ground distributors. Strategic archetypes include integrated global carriers, regional logistics specialists, and national postal operators with cross-border partnerships. Capacity expansion on trans-Pacific lanes and emissions tracking infrastructure investments represent the dominant competitive moves across the forecast window.
Among integrated global carriers, DHL Express, FedEx Corporation, and DB Schenker occupy distinct positioning vectors. DHL Express exemplifies the customs brokerage-integrated archetype with preemptive carbon certification capabilities. FedEx Corporation anchors trans-Pacific capacity through gateway infrastructure connecting to manufacturing zones. DB Schenker represents the automotive-specialized forwarder segment competing for maquiladora contract wins. Regional operators including Aramex and GEFCO sit within the middle tier, while national postal entities Correos de Chile and Deprisa leverage last-mile density for cross-border partnerships.
| Leading Market Players |
|---|
| DHL Express |
| Aramex |
| GEFCO |
| Deprisa |
| Correos de Chile |
| United Parcel Service of America, Inc. |
| FedEx Corporation |
| Kuehne Nagel |
| DB Schenker |
| Others |
Supply & Pricing Matrix
Express-economy service bifurcation creates divergent margin architectures across Brazilian and Mexican trade corridors. Premium operators command rate premiums through Receita Federal pre-clearance integration and dedicated freighter capacity, while commodity forwarding competes on jet fuel surcharge recovery and consolidation density. This tier divergence maps directly onto supply chain choices: premium tiers anchor in Miami and São Paulo gateway infrastructure, economy tiers disperse through ground distribution networks.
Pricing Analysis
Margin tightening in freight forwarding reflects jet fuel price volatility without contractual surcharge recovery mechanisms. Three-tier pricing structure across premium express, standard deferred, and economy consolidation levels stratifies buyer segments. Brazilian fashion marketplaces and Mexican automotive suppliers absorb premium pricing for time-definite guarantees, while mid-market e-commerce merchants drive price sensitivity in economy tiers. Certification investments for EU Carbon Border Adjustment Mechanism compliance widen the premium-commodity spread.
Supply Chain Analysis
Licensed customs broker scarcity in São Paulo, Mexico City, and Buenos Aires constrains clearance velocity at peak volume periods. Supply concentration rests on Brazil, Mexico, and Chile as primary gateway hubs, with Miami serving as the dominant trans-shipment node. Jet fuel, bonded warehouse capacity, and freighter aircraft availability constitute critical input dependencies. Single-source vulnerability concentrates in belly cargo contracts with scheduled passenger airlines. Distribution runs through multimodal corridors combining air gateways with last-mile ground networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America International CEP market operates as a cost-of-compliance arena where EU Green Deal extraterritorial mandates erect barrier-to-entry moats favoring operators with preemptive carbon certification infrastructure.
For Market Incumbents: Anticipate customs modernization acceleration under Receita Federal and SAT mandates by deepening licensed broker training pipelines and pre-positioning bonded capacity at Buenaventura and Santiago. Defensive consolidation should target mid-tier operators with established Aduana Nacional relationships to preempt regional specialist acquisition by global competitors. Carbon reporting infrastructure represents the critical lever for margin defense on Europe-bound lanes. For New Entrants and Emerging Players: Mid-market Chilean lithium processors and Colombian flower exporters present the most penetrable buyer archetypes underserved by integrated customs brokerage. White-space concentration sits in temperature-controlled express logistics with chain-of-custody documentation, where incumbent networks lack specialized cold-chain asset depth. A go-to-market angle anchored in blockchain-enabled documentation systems for agricultural and high-value cargo bypasses legacy clearance bottlenecks. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated global carriers seeking customs brokerage capabilities and regional last-mile density. Long-term viability favors operators with emissions tracking infrastructure aligned to CSRD scope-three disclosure rules. The signal to watch is Mercosur-EU trade ratification progress, which would accelerate harmonized customs protocols and compress margins for fragmentation-dependent specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Emissions Tracking Infrastructure Investment | Positions operators for EU Carbon Border Adjustment Mechanism compliance on Europe-bound trade lanes. |
| Licensed Customs Broker Training Program | Addresses Receita Federal and SAT certification bottlenecks constraining peak volume clearance velocity. |
| Bonded Warehouse Expansion at Pacific Ports | Captures Buenaventura container terminal growth bypassing Panama Canal congestion for Asia-Latin America routing. |
| Blockchain Documentation Platform Deployment | Absorbs paper-based SAT and Aduana Nacional processes into immutable ledgers reducing dwell times. |
| Subscription-Based Capacity Commitment Model | Locks in volume from Brazilian fashion marketplaces and Mexican consumer electronics platforms displacing transactional economics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with express operations directors, customs brokerage managers, e-commerce logistics procurement leads, and airline cargo capacity planners combined with secondary validation from Receita Federal electronic invoicing mandate documentation, SAT pre-clearance protocol filings, and EU Green Deal implementation guidance. Bottom-up volume modeling across service type, end user, and technology segments triangulated against top-down trade flow assessments.
Data-stream reconciliation integrated shipment volume tracking, carrier capacity deployment schedules, and customs clearance time series across the projection horizon. Segmentation dimensions modeled encompassed service tier, end-use application, technology infrastructure, and delivery model, with additional granularity on regulatory compliance tier. CAGRs derived from trend extrapolation of e-commerce penetration curves, freighter capacity expansion plans, and customs modernization implementation timelines. Jet fuel price volatility scenarios and carbon regulatory phase-in schedules informed sensitivity testing.
Revisions become necessary when Mercosur-EU trade ratification stalls, when jet fuel price spikes exceed contractual surcharge recovery mechanisms, or when licensed customs broker training output fails to match Receita Federal mandate expansion. Forecasts reflect documented assumptions on e-commerce volume growth, customs harmonization progress, and emissions disclosure rule enforcement intensity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Solar Control Films Market
Specialty Materials
Acrylic Fine Particle Market
Specialty Materials
Specialty Coating Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
Global Flexible Substrates Market
Specialty Materials
Global Consumer Foam Market
Specialty Materials
Barium Borate Market
Specialty Materials
Super-Hard Material Market
Specialty Materials
Medical Injection Molded Plastics Market
Specialty Materials
Nanocapsules Market
Specialty Materials
Africa Collagen Market
Specialty Materials
Europe Solar Control Window Films Market
Specialty Materials
Open Cell Foam Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Cellulose Gel Market