
 Specialty Carbon Black Market | 2026-2036
Specialty Carbon Black Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Carbon Black Market Intelligence
A shift toward multi-source procurement models is restructuring supply chain relationships for end-users in critical applications. This strategy mitigates risks associated with supply disruptions from a single provider. Cabot Corporation leverages its global manufacturing footprint to meet this diversified demand. Birla Carbon specializes in high-performance grades for niche applications, while Orion Engineered Carbons S.A. competes on both scale and specialized product development for coatings and polymers.
Specialty carbon black is a high-purity form of amorphous carbon, distinct from commodity grades due to its smaller particle size and surface chemistry. It is produced through the controlled, incomplete combustion of hydrocarbons and functions as a pigment, conductive agent, or UV stabilizer. The conductive product type is seeing rapid development for battery electrodes and antistatic electronics packaging. In application segments, demand for high-jetness grades in automotive paints and coatings commands premium pricing.
Regulatory frameworks significantly influence market access and product formulation. Compliance with the EU's REACH regulation, US EPA rules on emissions, and China’s GB standards for material safety is mandatory for major producers. These standards are increasingly shaping the development of cleaner production technologies and bio-based feedstocks. Future success will depend on navigating this complex regulatory environment while meeting demands for higher-performance materials.
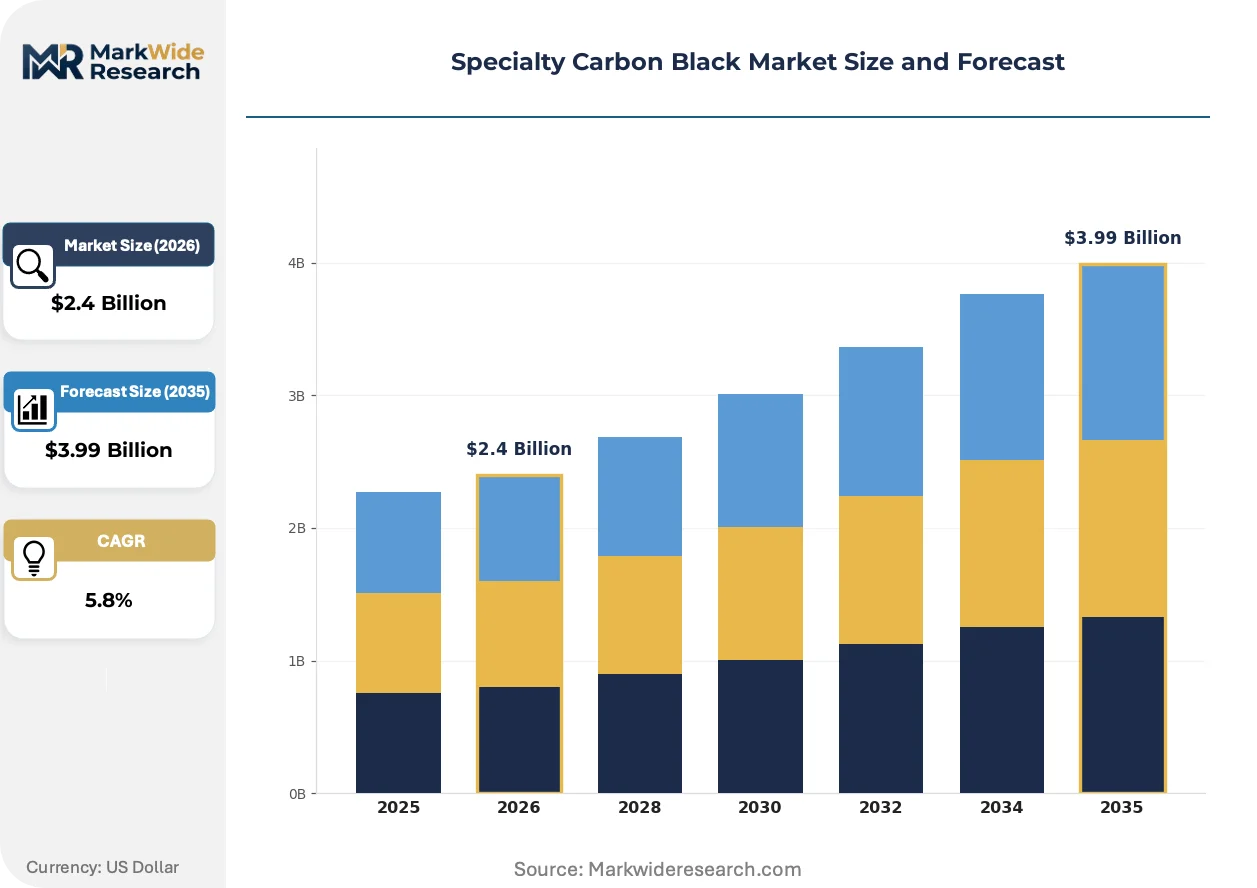
Market Dynamics
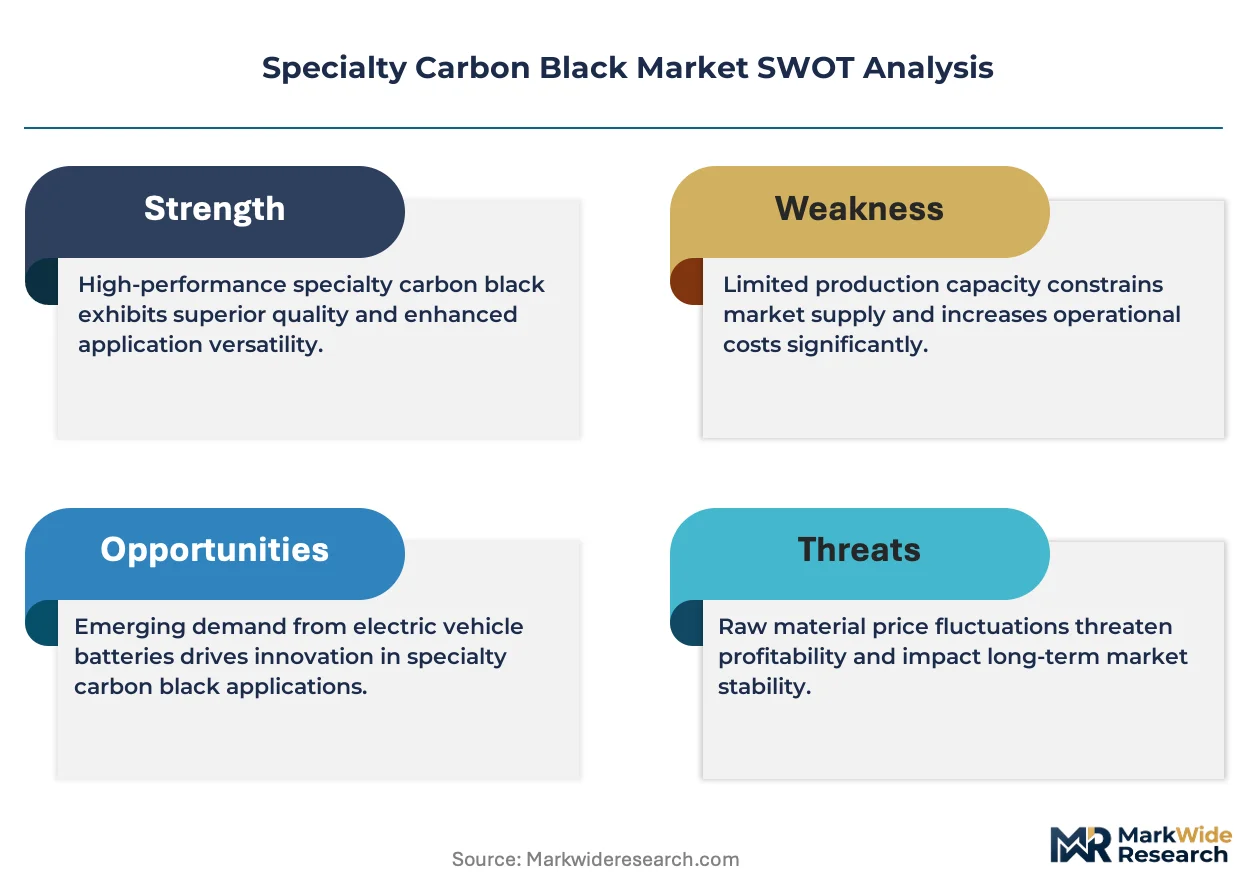
The market's structure is defined by the tension between demand for higher-performance conductive materials for battery electrodes and stringent environmental regulations like REACH, which are forcing a re-evaluation of hydrocarbon-based production processes and feedstocks.
Growth Catalysts
- Electric Vehicle Batteries:Demand from the automotive sector for conductive additives in lithium-ion battery electrodes is a primary growth engine, especially in China.
- High-Performance Coatings:The need for specialty grades that provide deep jetness and UV protection continues to expand in premium automotive paints and industrial coatings.
- Bio-Based Feedstocks:Research and development into renewable feedstocks, such as pyrolysis oils from biomass, is spurred by corporate sustainability goals and regulatory pressures.
Market Restraints
- Feedstock Price Volatility:Dependence on hydrocarbon feedstocks, such as aromatic oils, links production costs directly to volatile global oil and gas markets.
- Regulatory Compliance Costs:The expense and complexity of adhering to substance registration frameworks, including the EU's REACH, create significant barriers for producers.
- Substitution in Lower-Tier Applications:In less demanding uses like general-purpose plastics, lower-cost commodity carbon black or other colorants can serve as effective substitutes.
Strategic Opportunities
- Conductive Polymers for Electronics:Development of new grades for conductive polymers used in antistatic packaging, fuel lines, and sensitive electronic component housing represents a key growth area.
- Manufacturing in Southeast Asia:Establishing finishing or production facilities in markets like Vietnam and Thailand can serve the region's growing electronics and automotive manufacturing hubs.
- Water-Borne Coating Formulations:Creating grades optimized for dispersion in water-borne systems addresses demand driven by stricter VOC emission rules from the US EPA.
Industry Challenges
- Production Energy Intensity:The furnace black process is highly energy-intensive, posing a significant challenge amid rising energy costs and pressure to meet decarbonization goals.
- Dispersion Formulation Expertise:A persistent skills gap exists for polymer and coatings formulators who can effectively disperse ultra-fine specialty particles without agglomeration issues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Carbon Black Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive, Furnace, Thermal, Gas Black, Acetylene, Channel Application: Plastic Additives, Paints & Coatings, Ink Formulations, Battery Electrodes, Sealants, Printing Inks Technology: Pyrolytic, Thermal Decomposition, Chemical Vapor Deposition, Carbonization, Emulsion, Micro-dispersion End User Industry: Construction, Electronics Manufacturing, Adhesives, Packaging Solutions, Textile Production, Specialty Chemicals |
| Companies Covered | Cabot Corporation, Birla Carbon, Orion Engineered Carbons S.A., Tokai Carbon Co., Ltd., Phillips Carbon Black Limited, Continental Carbon Company, Himadri Specialty Chemical Ltd., Omsk Carbon Group, Imerys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Carbon Black Market Strategic Shifts & Innovations
Material innovation in specialty carbon black is driven by a dual mandate for enhanced functional performance and improved sustainability profiles. This creates a development pathway where new grades must simultaneously meet stricter application requirements and address environmental and regulatory pressures.
Advanced process control software provides real-time monitoring of reactor conditions during production. Furnace black producers are adopting these systems to manage particle morphology. This technology is automating the micro-adjustments of feedstock flow and temperature to ensure consistent quality and higher yields for demanding conductive grades.
The European Union's Corporate Sustainability Reporting Directive (CSRD) imposes new disclosure requirements on companies. This forces specialty carbon black producers selling into the EU to provide transparent data on their entire value chain's environmental footprint. The plastics and polymers segment is most affected, now demanding full lifecycle assessments from suppliers.
A shift toward mandatory dual-supplier qualification is altering supply agreements in high-stakes industries. This disrupts traditional single-source relationships for specific material grades, particularly in automotive coatings and electronics packaging. This risk mitigation strategy is most pronounced among end-users in Germany and the United States.
Specialty Carbon Black Market Segmentation
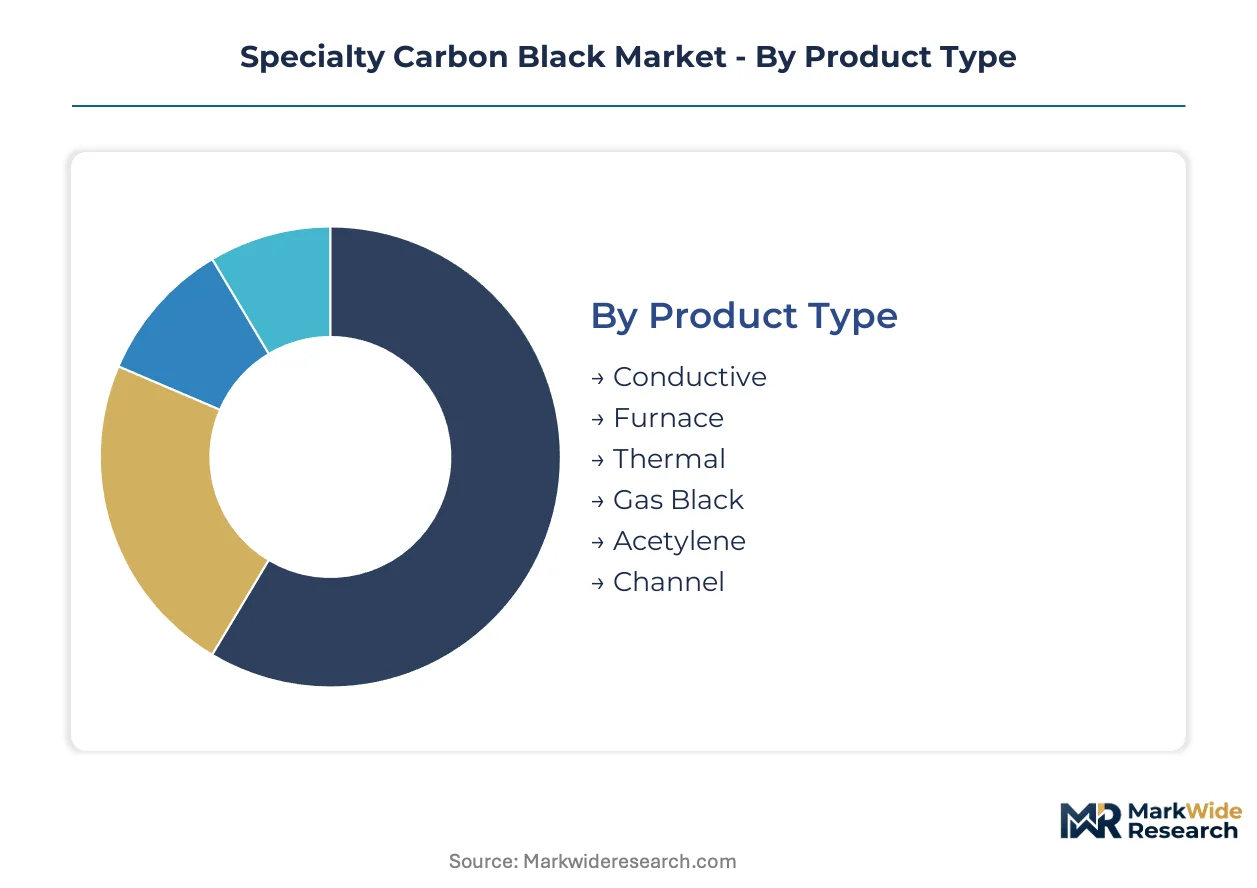
Specialty carbon black market segmentation reveals distinct value propositions across various product types, applications, technologies, and end-user industries. Understanding these segments is crucial for producers to align their high-purity material offerings with specific performance requirements and regulatory landscapes. This granular view highlights areas of concentrated demand and emerging opportunities.
Product Type:
The market for specialty carbon black product types is bifurcated by volume-driven commodity-like forms and highly specialized grades commanding premium pricing.
- Conductive:This high-purity carbon enhances electrical conductivity in matrices. Demand concentrates in lithium-ion battery electrodes for electric vehicles, driven by higher energy density.
- Furnace:Produced via controlled hydrocarbon combustion, this type offers diverse particle sizes. It is critical for demanding applications like high-jetness automotive paints, where consistent quality is paramount.
- Thermal:Large particle sizes characterize thermal black, used as a reinforcing filler or pigment in rubber and plastics.
- Gas Black:Impinging natural gas flames onto cool surfaces yields fine particles suitable for high-quality printing inks.
- Acetylene:Known for high purity and electrical conductivity, acetylene black is used in specialized battery applications.
- Channel:Historically used for pigments, channel black production has declined due to environmental concerns.
Mature deployment sits with Thermal and Gas Black. Newer deployment is concentrated in Conductive and Acetylene grades.
Application:
Application segments for specialty carbon black are differentiated by the specific functional properties required, ranging from pigmentation to electrical conductivity and UV stabilization.
- Battery Electrodes:Specialty carbon black acts as a conductive additive, improving electron flow and cycle life in lithium-ion batteries. Significant demand is in China's electric vehicle sector.
- Paints & Coatings:High-jetness grades provide intense black coloration and UV protection, particularly in automotive clearcoats. Premium pricing is for formulations requiring superior dispersion.
- Plastic Additives:Specialty carbon black enhances UV resistance, provides pigmentation, and imparts antistatic properties to plastics.
- Ink Formulations:Used as a pigment in printing and writing inks, specialty carbon black offers deep black color.
- Sealants:These materials benefit from specialty carbon black as a reinforcing filler and pigment, improving durability and UV stability.
- Printing Inks:Specialty carbon black provides intense blackness and specific rheological properties for high-quality graphic arts.
The Plastic Additives segment accounts for a substantial share, while Battery Electrodes exhibits the fastest expansion trajectory.
Technology:
The market's technology segments reflect varying levels of process maturity and capital intensity, influencing the purity and morphology of specialty carbon black produced.
- Pyrolytic:This technology involves thermal decomposition of hydrocarbon feedstocks, often for bio-based feedstock utilization. R&D focuses on consistent particle morphology for high-performance applications.
- Chemical Vapor Deposition:This advanced process deposits carbon from a gaseous precursor, enabling precise control over structure. It is utilized for specialized conductive materials in advanced electronics.
- Thermal Decomposition:A broad category breaking down hydrocarbons using heat, producing various carbon black grades.
- Carbonization:This converts organic materials into carbon through pyrolysis, associated with char or activated carbon.
- Emulsion:Not a direct production method, emulsion techniques are critical for dispersing carbon black particles in liquid formulations.
- Micro-dispersion:This technology focuses on achieving ultra-fine and stable dispersion of carbon black particles in various matrices.
Adoption of Thermal Decomposition technology is widespread, with Pyrolytic and Chemical Vapor Deposition gaining traction for advanced material requirements.
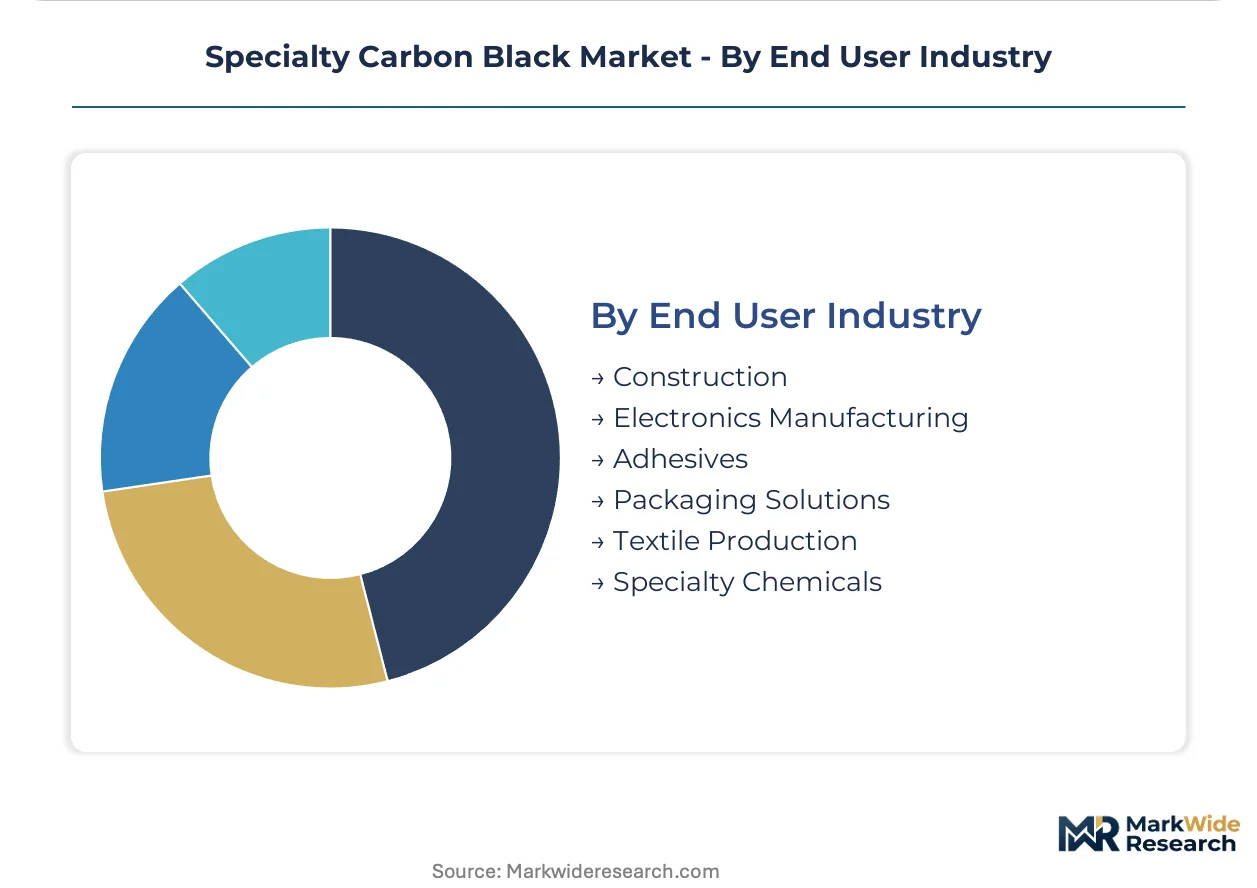
End User Industry:
End-user industries for specialty carbon black present diverse margin profiles, driven by application criticality, material specification, and regulatory compliance costs.
- Electronics Manufacturing:This sector utilizes specialty carbon black for conductive polymers, antistatic packaging, and component housing. Demand is strong in advanced manufacturing hubs like China.
- Specialty Chemicals:Specialty carbon black is a key ingredient in numerous chemical formulations, including catalysts and advanced material composites. Innovation focuses on tailor-made grades.
- Construction:Specialty carbon black pigments concrete, mortar, and roofing materials, offering UV resistance.
- Adhesives:Used as a reinforcing filler and pigment, specialty carbon black improves strength, durability, and UV stability.
- Packaging Solutions:Specialty carbon black provides UV protection and antistatic properties for packaging, particularly for sensitive electronics.
- Textile Production:Specialty carbon black dyes fabrics and fibers, providing deep black coloration and UV protection.
Demand from the Construction industry remains consistent, whereas Electronics Manufacturing is undergoing significant transformation due to new material requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for specialty carbon black is concentrating in advanced manufacturing and electronics production hubs globally. The electric vehicle battery sector, particularly in China, drives significant consumption. Stricter environmental regulations also influence material selection and production processes across major industrial nations.
China
China's electric vehicle battery production significantly boosts demand for conductive specialty carbon black. The country's GB standards for material safety and dual carbon goals shape product formulation. Manufacturing hubs like the Yangtze River Delta are advancing conductive polymer applications for electronics.
Germany
Germany's automotive sector requires high-jetness grades for premium paints and coatings. Compliance with the EU's REACH framework dictates material composition and sourcing within the nation. Industrial regions such as Bavaria and North Rhine-Westphalia focus on specialized product development for polymers.
United States
United States demand arises from conductive polymer applications in antistatic electronics packaging. US EPA rules on emissions drive the development of water-borne coating formulations. Technology clusters in Silicon Valley and Midwest automotive centers are advancing material integration.
Japan
Japan requires high-purity acetylene black for specialized battery applications and fine particles for printing inks. METI initiatives and JIS standards ensure stringent material quality and performance. The Kanto region and Chubu industrial areas drive innovation in advanced material composites.
India
India's growing plastics industry utilizes specialty carbon black for UV resistance and pigmentation. The BIS standards for industrial materials and the PLI scheme support domestic manufacturing. Manufacturing zones in Maharashtra and Gujarat are expanding production for various end-user segments.
Specialty Carbon Black Market Key Industry Players
Geographic expansion dominates the current landscape, driven by the need to serve diversified demand across continents. The market structure is moderately consolidated, with a few large players holding significant global presence. Strategic archetypes include integrated global suppliers, specialized high-performance material providers, and regional commodity producers. Companies are engaging in both capacity expansion and portfolio diversification to meet evolving application requirements.
Within the integrated global supplier archetype, Cabot Corporation exemplifies broad market reach with its extensive manufacturing footprint. Birla Carbon represents the specialized high-performance material providers, focusing on niche application grades. Orion Engineered Carbons S.A. occupies a position across both scale and specialized product development, catering to diverse needs in coatings and polymers. These entities collectively anchor the market’s competitive dynamics, responding to shifts in multi-source procurement models. Their strategies reflect the industry's dual mandate for performance and sustainability, influencing material availability and innovation across different regions.
| Leading Market Players |
|---|
| Cabot Corporation |
| Birla Carbon |
| Orion Engineered Carbons S.A. |
| Tokai Carbon Co., Ltd. |
| Phillips Carbon Black Limited |
| Continental Carbon Company |
| Himadri Specialty Chemical Ltd. |
| Omsk Carbon Group |
| Imerys |
| Others |
Cost & Logistics Intelligence
Specialized chemical engineers in advanced manufacturing hubs globally influence pricing-tier spreads, reflecting the scarcity of expertise in developing high-purity grades. This workforce concentration impacts the cost structure for complex conductive materials, driving differentiation in value propositions across the market.
Pricing Analysis
After-sales technical support, often unbundled from the base material price, influences the perceived value of specialty carbon black grades. The dominant pricing model involves contract-based long-term offtake agreements for major industrial buyers. Price differentiation stems from quality grade, particularly for high-jetness and conductive materials, alongside customization levels for specific application matrices. Pricing softness reflects persistent feedstock price volatility, linking material costs directly to global oil and gas markets. Buyers in general-purpose plastic additives exhibit the most price sensitivity, while lithium-ion battery electrode manufacturers demonstrate lower sensitivity for performance-critical grades.
Supply Chain Analysis
Single-source vulnerability sits with specialized feedstock suppliers for aromatic oils and natural gas, impacting the stability of the specialty carbon black supply chain. Geographic supply concentration for production largely resides in China, the United States, and Germany, reflecting established industrial infrastructure. The market draws from specific raw materials like hydrocarbon feedstocks, which directly link production costs to global energy markets. Commodity price volatility, therefore, represents a significant structural risk across the value chain. Distribution runs through a combination of direct sales to large-volume industrial end-users and specialized chemical distributors serving smaller formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specialty carbon black market is evolving into a consolidation play, driven by the intense capital requirements for cleaner production technologies and regulatory compliance.
For Market Incumbents:
Lock in long-term supply agreements with key battery and coatings manufacturers to secure stable demand for high-performance grades. Invest in R&D for bio-based feedstocks and cleaner production technologies to mitigate risks from stricter environmental regulations like EU REACH and US EPA rules. Expand capacity in strategic regions such as Southeast Asia to serve growing electronics and automotive manufacturing. Pursue certification investments to maintain market access against evolving material safety standards.
For New Entrants and Emerging Players:
Capture niche opportunities in advanced conductive polymers for antistatic packaging and specialized battery applications. Target the Southeast Asian electronics manufacturing sector as a penetrable segment due to its rapid expansion and demand for localized supply. Develop grades optimized for water-borne coating formulations, aligning with global VOC emission reduction mandates. Prioritize a go-to-market angle emphasizing sustainability credentials and superior dispersion properties for specific applications.
For Investors and Strategic Acquirers:
Re-rating potential sits with specialized high-performance material providers given the accelerating demand for EV battery electrodes and advanced coatings. Long-term viability remains strong for companies innovating in sustainable production methods and high-purity conductive materials over the next decade. Identify acquisition targets with proprietary pyrolysis technology or advanced micro-dispersion expertise for complex matrices. Increased M&A activity in bio-based feedstock processing serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Supports regional electronics and automotive manufacturing growth. |
| R&D in Bio-Based Feedstocks | Addresses regulatory pressures and corporate sustainability goals. |
| Advanced Process Control Adoption | Enhances consistency and yield for demanding conductive grades. |
| Strategic Partnerships for Dispersion | Mitigates the skills gap in formulating ultra-fine particles. |
| Dual-Supplier Qualification Programs | Strengthens supply chain resilience for critical end-users. |
Research Approach
Multi-period observation of production capacities, regulatory filings, and patent activity anchored the trend analysis, supplemented by interviews with industry stakeholders. This approach combined primary insights from R&D directors, procurement leads for automotive paints, battery cell manufacturers, and regulatory compliance officers. Secondary validation drew from EU REACH registrations, US EPA emission reports, China GB standards documents, and corporate sustainability reports, integrating both bottom-up and top-down triangulation.
Segment-specific weighting was applied to product types, applications, technologies, and end-user industries to build a comprehensive market model. The analytical framework incorporated segmentation dimensions such as conductive and furnace black grades, battery electrode and paints & coatings applications, pyrolytic and thermal decomposition technologies, and electronics and automotive end-user industries. Compound annual growth rates were derived from historical data and projected demand drivers, including EV production forecasts and new material development timelines across the modeling period.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts and raw material price volatility. Forecasts reflect documented assumptions regarding technological advancements and regulatory evolution within the specialty carbon black market. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market
Specialty Materials
Carbon Mold Market
Specialty Materials
EVA Interlayer for Photovoltaic Market
Specialty Materials
Sheath Materials Market
Specialty Materials
Silicone Solutions Market
Specialty Materials
Nitrocellulose Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Global Conductive Silicone Market
Specialty Materials
Global Liquid Crystal Polymer (LCP) Films and Laminates Market
Specialty Materials
Lab Grown Diamonds Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Solar Control Films Market
Specialty Materials
Super Engineering Plastics Market
Specialty Materials
Carbon Blacks for Non-Rubber Applications Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Latin America International CEP Market