
 Eptfe in Spotlight-Poly-Vents Market | 2026-2036
Eptfe in Spotlight-Poly-Vents Market Size, Share, and Industry Trends Forecast 2026-2036
Eptfe in Spotlight-Poly-Vents Market Foresight
China is tilting ePTFE membrane capacity toward automotive-grade poly-vent output as domestic EV headlamp production scales. W.L. Gore & Associates leverages its Delaware-based resin-to-membrane vertical integration to sustain premium positioning in medical device vents. Donaldson Company anchors Midwest industrial distribution with filtration-adjacent venting expertise, while Nitto Denko dominates Asian electronics sealing through laminated material R&D intensity.
Expanded polytetrafluoroethylene in spotlight-poly-vents consists of microporous membranes manufactured via mechanical stretching of sintered PTFE resin, achieving pore sizes of 0.1 to 10 micrometers while maintaining oleophobic and hydrophobic barrier performance against liquid water and particulate intrusion. The primary industrial purpose is pressure-equalization and environmental protection for sealed enclosures subject to thermal cycling, altitude changes, or humidity exposure. Membrane filters lead product-type margin pools due to qualification stickiness in medical device OEM supply chains, while automotive components within the application dimension represent the fastest-growing demand vector as LED and laser headlamp architectures proliferate. Composite films technology commands pricing premiums through multi-layer barrier customization for aerospace firms requiring combined thermal and acoustic management.
EPA oversight of fluoropolymer precursor emissions shapes US manufacturing site selection and capital allocation for ePTFE resin producers. REACH registration requirements in Europe constrain raw material sourcing flexibility, while China's GB standards for automotive lighting enclosure integrity create compliance-driven specification upgrades for membrane suppliers. Stakeholders must monitor evolving fluoropolymer chemistry restrictions across multiple jurisdictions to anticipate reformulation timelines and qualification cycle impacts on existing supply agreements.
Market Dynamics
LED headlamp thermal management requirements are compressing qualification timelines for ePTFE membrane suppliers serving Stuttgart-based Tier-1 automotive clusters, while EU F-Gas Regulation compliance costs restructure fluoropolymer precursor sourcing across European resin producers.
Growth Catalysts
- Automotive LED proliferation:Laser and matrix headlamp architectures require pressure-equalization membranes that withstand rapid thermal cycling. German OEM specification upgrades drive membrane qualification volumes.
- EU F-Gas Regulation:Tightening fluoropolymer manufacturing standards push suppliers toward cleaner production chemistries, creating first-mover advantage for compliant resin-to-membrane operations.
- Medical device enclosure protection:Implantable electronics and diagnostic equipment OEMs specify oleophobic barrier membranes for humidity and particulate defense in portable units.
Market Restraints
- Fluoropolymer precursor cost volatility:Tetrafluoroethylene monomer supply concentrates among a limited set of chemical producers, exposing membrane manufacturers to input price swings.
- REACH registration constraints:European raw material sourcing flexibility narrows as ECHA registration requirements expand for PTFE resin additives and processing aids.
- Silicone membrane substitution:Lower-cost thermoplastic elastomer alternatives capture price-sensitive industrial venting applications where extreme chemical resistance is not mandatory.
Strategic Opportunities
- China EV headlamp localization:Domestic electric vehicle production scales create demand for automotive-grade ePTFE membrane capacity within Chinese manufacturing corridors.
- GB standards compliance upgrades:China's automotive lighting enclosure integrity regulations mandate specification improvements that qualified membrane suppliers can capture.
- Aerospace thermal-acoustic composites:Multi-layer barrier customization for combined heat and noise management opens premium pricing tiers in aircraft cabin and avionics sealing.
Industry Challenges
- Fluoropolymer chemistry reformulation timelines:Anticipating multi-jurisdiction restriction evolutions requires R&D coordination with ECHA, EPA, and MEE regulatory calendars.
- Qualification cycle compression:Automotive OEMs accelerate membrane validation schedules while maintaining ISO 10993 biocompatency documentation for medical crossover applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eptfe in Spotlight-Poly-Vents Market |
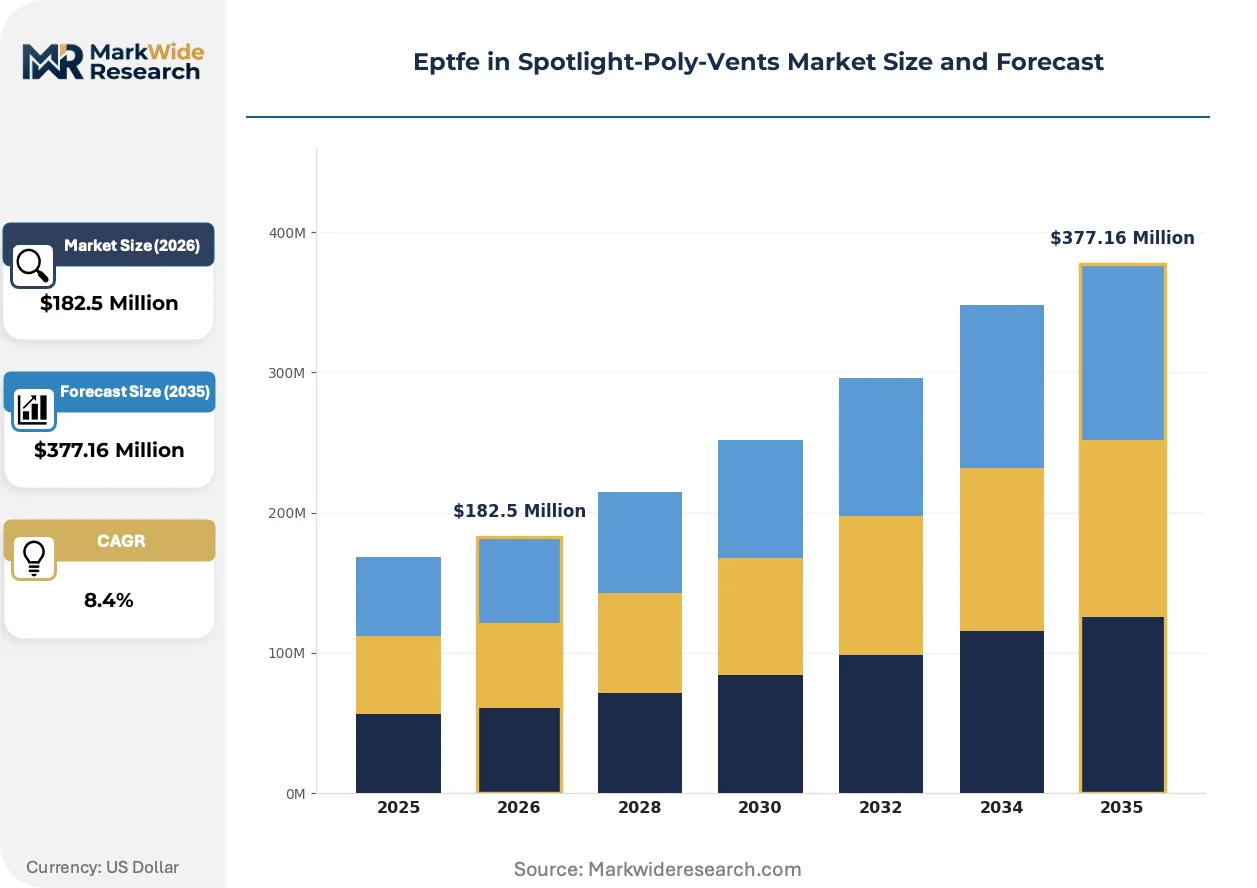
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $377.16 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filters, Adhesives, Gaskets, Seals Application: Medical Devices, Automotive Components, Industrial Equipment, Electronics End User: OEMs, Medical Manufacturers, Aerospace Firms, Construction Companies Technology: Hollow Fiber, Composite Films, Laminated Materials, Coated Fabrics |
| Companies Covered | W.L. Gore & Associates, Inc., Donaldson Company, Inc., Compagnie de Saint-Gobain S.A., Nitto Denko Corporation, Rogers Corporation, Markel Corporation, Parker-Hannifin Corporation, Teadit Group, Zeus Industrial Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eptfe in Spotlight-Poly-Vents Market Shifts & Advancements
Membrane manufacturing is virtualizing process control and quality assurance, while regulatory chemistry restrictions and procurement centralization reshape supplier-buyer relationships across automotive and medical end-uses.
Multi-layer composite ePTFE films are virtualizing single-membrane architectures in aerospace and premium automotive applications. Boeing and Airbus cabin system suppliers specify these laminates for simultaneous thermal insulation and acoustic dampening. The technology is virtualizing traditional material stacking approaches, compressing part count and assembly labor in sealed enclosure designs.
EPA oversight of fluoropolymer precursor emissions is reshaping US manufacturing site selection for resin producers. New capital allocation favors Delaware and Gulf Coast locations with existing emissions control infrastructure and proximity to chemical feedstock pipelines. Medical device venting applications face the tightest compliance scrutiny, with FDA 510(k) submissions now requiring detailed perfluorinated compound traceability documentation.
Automotive lighting OEMs consolidate membrane procurement under single-source agreements with qualification-locked suppliers. Tier-1 buyers in Germany and China now specify multi-year supply contracts with embedded volume flexibility clauses, displacing spot-market purchasing. This concentration is most visible in Stuttgart engineering corridors, where Bosch, Hella, and ZKW Lighting coordinate specification harmonization across LED and laser headlamp platforms.
Eptfe in Spotlight-Poly-Vents Market Segmentation
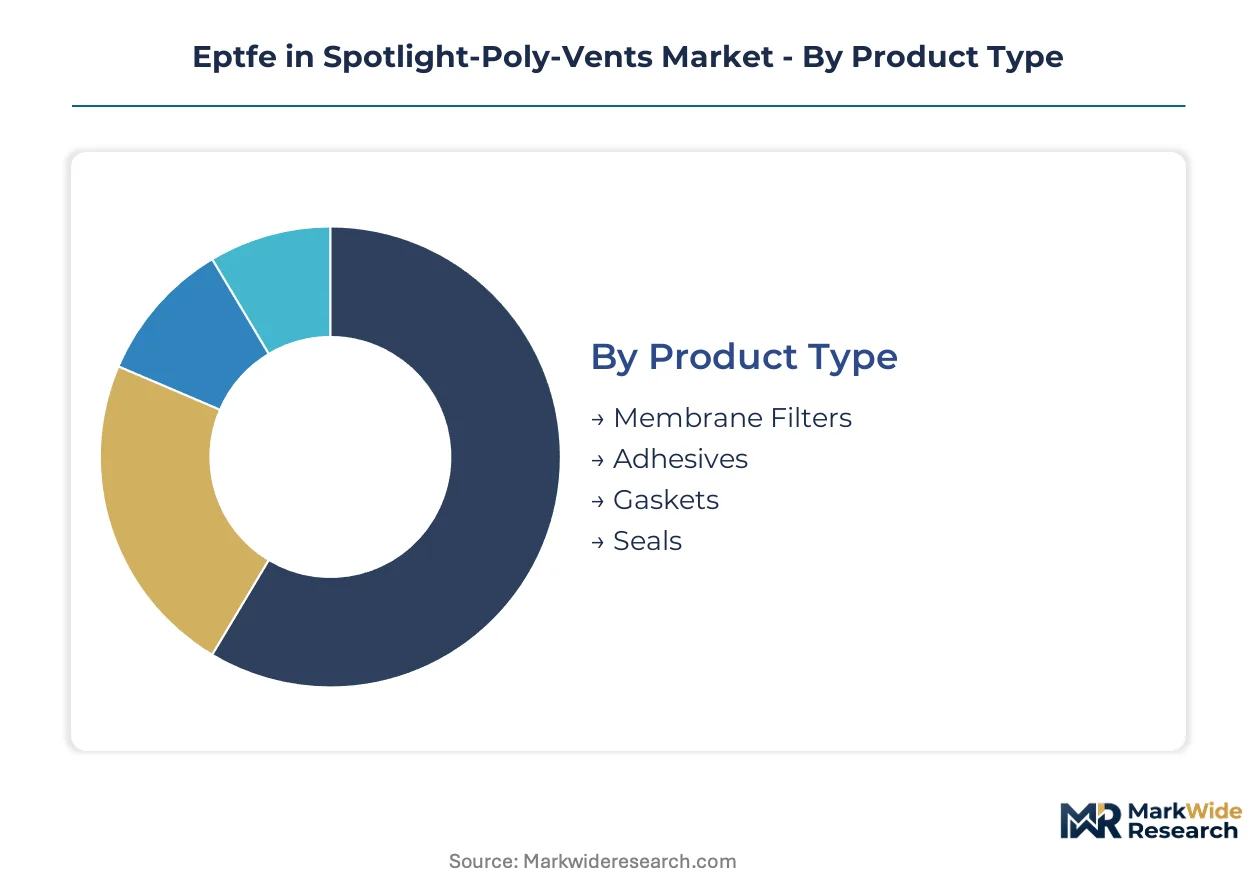
ePTFE membrane performance varies sharply across pressure-equalization use cases, from sterile medical enclosures to thermally cycled automotive headlamps. Segmentation reveals where qualification stickiness creates margin pools and where substitution threats concentrate.
Product Type:
Use-case spectrum spans sterile barrier filtration through mechanical sealing, with qualification intensity determining supplier lock-in duration.
- Membrane Filters:Microporous structures achieving 0.1-10 micrometer pore sizes via mechanical stretching of sintered PTFE resin. Medical device OEMs in Germany and the US specify these for implantable electronics humidity defense, with ISO 10993 biocompatency documentation creating multi-year qualification cycles. FDA 510(k) traceability requirements for perfluorinated compounds tighten procurement specifications.
- Adhesives:Pressure-sensitive formulations bonding ePTFE substrates to metal and plastic housings. Automotive lighting manufacturers in Stuttgart engineering corridors specify high-temperature acrylic and silicone hybrid chemistries for LED assembly thermal cycling resistance.
- Gaskets:Compressible sealing elements for industrial enclosure interfaces. Chemical processing and power generation OEMs specify filled PTFE variants for flange sealing in corrosive environments.
- Seals:Radial and axial shaft sealing configurations protecting rotating equipment bearings. Wind turbine gearbox manufacturers specify lip seal architectures with ePTFE wear surfaces.
The dominant share belongs to Membrane Filters, while Adhesives is closing the gap fastest as automotive LED architectures proliferate.
Application:
End-use concentration tracks regulatory stringency and thermal management complexity across medical, mobility, and industrial domains.
- Medical Devices:Diagnostic equipment and portable monitoring systems require oleophobic barrier membranes for particulate and humidity defense. FDA and EMA documentation requirements for biocompatency and chemical traceability extend supplier qualification timelines.
- Automotive Components:LED and laser headlamp pressure-equalization vents withstand rapid thermal cycling and altitude changes. German Tier-1 suppliers cluster around Stuttgart and Munich engineering corridors, with Chinese EV production scaling domestic membrane demand.
- Industrial Equipment:Outdoor electrical enclosures and telecommunications cabinets specify ePTFE vents for IP-rated environmental protection. Silicone membrane substitution captures price-sensitive segments where chemical resistance requirements moderate.
- Electronics:Consumer device and semiconductor manufacturing equipment utilize miniature vent formats for moisture management. Asian electronics sealing specialists emphasize laminated material R&D for miniaturized form factors.
Medical Devices commands the highest margin tier through qualification stickiness, though Automotive Components exhibits the steepest expansion trajectory as headlamp architectures multiply.
End User:
Procurement centralization and technical specification authority vary dramatically across customer archetypes.
- OEMs:Automotive and industrial original equipment manufacturers consolidate membrane procurement under single-source agreements with embedded volume flexibility clauses. German lighting OEMs coordinate specification harmonization across LED and laser platforms.
- Medical Manufacturers:Implantable electronics and diagnostic equipment producers demand ISO 10993 biocompatency documentation and perfluorinated compound traceability. FDA 510(k) submission requirements constrain supplier switching.
- Aerospace Firms:Boeing and Airbus cabin system suppliers specify multi-layer composite films for combined thermal insulation and acoustic dampening. Premium pricing tiers reflect part count compression and qualification rigor.
- Construction Companies:Building envelope and infrastructure sealing applications specify ePTFE membrane roofing and facade systems. Cost sensitivity relative to performance requirements limits penetration in commodity construction segments.
OEMs dominate procurement volume through centralized buying, while Medical Manufacturers sustain the highest pricing premiums via regulatory documentation requirements.
Technology:
Manufacturing process selection determines pore architecture precision and multi-functional layering capability.
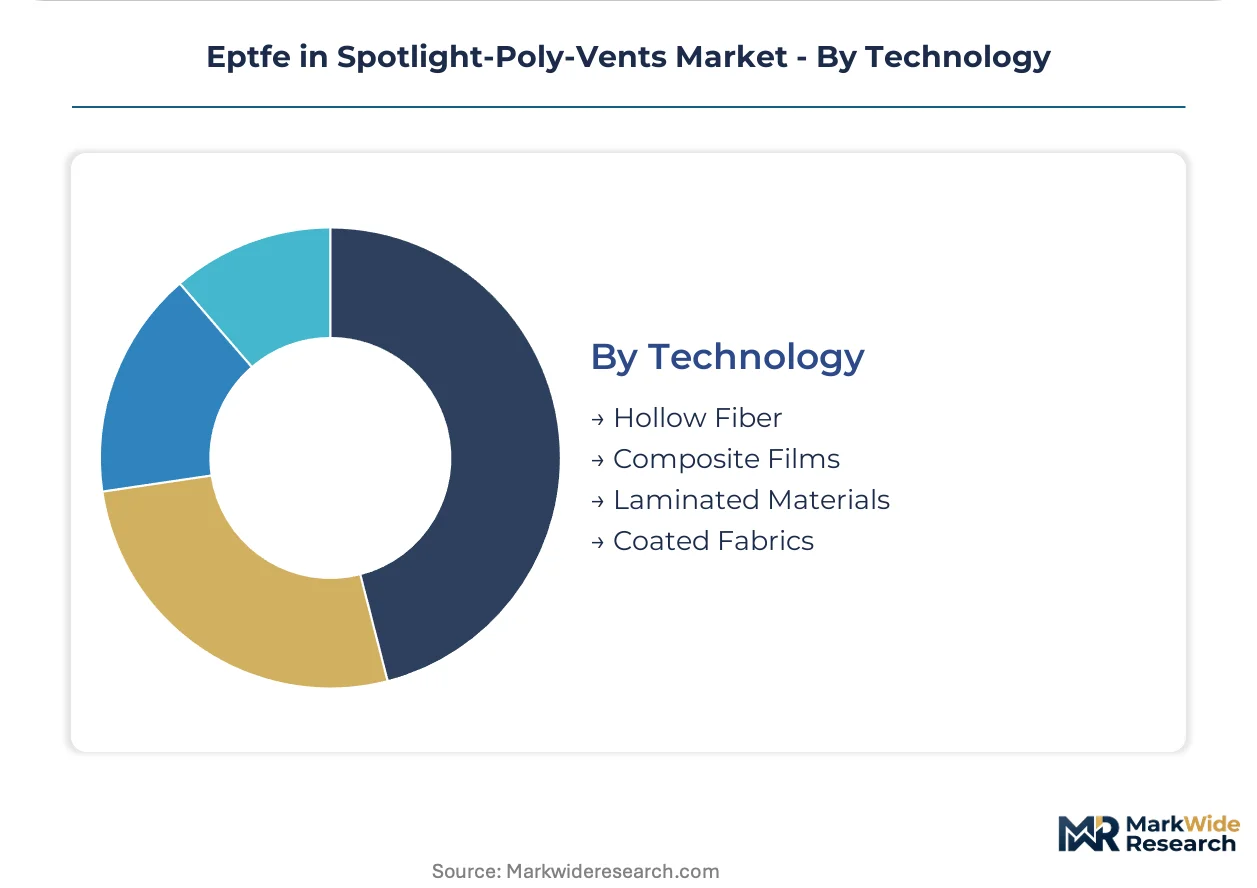
- Hollow Fiber:Tubular membrane geometries for high-surface-area filtration in medical and industrial fluid processing. Bioreactor and dialysis equipment manufacturers specify these configurations for sterile barrier applications.
- Composite Films:Multi-layer laminates combining ePTFE with polyimide, polyester, or metal foils for simultaneous thermal, acoustic, and barrier management. Aerospace cabin and avionics sealing commands premium positioning through customized layer stacking.
- Laminated Materials:Adhesive-bonded multi-ply structures for electronics sealing and automotive gasketing. Asian manufacturers emphasize R&D intensity for miniaturized consumer device applications.
- Coated Fabrics:ePTFE membranes bonded to textile substrates for architectural and protective clothing applications. Building membrane and emergency responder garment producers specify these for weatherproof breathability.
Composite Films captures the most aggressive pricing premiums, while Laminated Materials gains share fastest through electronics miniaturization demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA oversight of fluoropolymer precursor emissions anchors United States manufacturing strategy, while EU F-Gas Regulation compliance costs restructure European resin sourcing. Chinese GB standards for automotive lighting enclosure integrity create specification-driven demand corridors across three continents.
Germany
Tier-1 automotive suppliers cluster around Stuttgart and Munich engineering corridors for LED headlamp membrane qualification. EU F-Gas Regulation tightening pushes resin producers toward cleaner production chemistries. Bosch, Hella, and ZKW Lighting coordinate specification harmonization across laser headlamp platforms in Baden-Württemberg.
United States
Delaware-based resin-to-membrane vertical integration sustains premium positioning in medical device vents. EPA emissions control infrastructure shapes capital allocation toward Gulf Coast chemical feedstock corridors. FDA 510(k) submissions now require perfluorinated compound traceability documentation for implantable electronics applications.
China
Domestic EV headlamp production scales demand for automotive-grade ePTFE membrane capacity. MIIT and MEE regulatory calendars drive reformulation timelines for fluoropolymer chemistry. Yangtze River Delta manufacturing corridors concentrate membrane output as GB standards mandate specification upgrades.
Japan
Electronics sealing specialists emphasize laminated material R&D intensity for miniaturized consumer devices. METI industrial policy supports advanced materials development in Kanto and Kansai regions. Osaka-based fabricators supply multi-layer barrier customization for semiconductor manufacturing equipment.
Eptfe in Spotlight-Poly-Vents Market Competitive Landscape
Resin-to-membrane integrators and filtration-adjacent specialists split the market between premium qualification-locked tiers and industrial volume segments. The structure concentrates around three strategic archetypes: vertically integrated fluoropolymer producers, automotive-tier membrane fabricators, and electronics sealing laminators. Competitive moves center on multi-year supply contract consolidation with embedded volume flexibility clauses, and geographic capacity expansion toward Chinese EV manufacturing corridors.
Among US-based fabricators, W.L. Gore & Associates, Inc. and Donaldson Company, Inc. exemplify the integrated-resin and filtration-adjacent archetypes respectively. Nitto Denko Corporation represents Japanese laminated-material specialization. These three anchors occupy positions across medical device qualification intensity, Midwest industrial distribution, and Asian electronics miniaturization demands.
| Leading Market Players |
|---|
| W.L. Gore & Associates, Inc. |
| Donaldson Company, Inc. |
| Compagnie de Saint-Gobain S.A. |
| Nitto Denko Corporation |
| Rogers Corporation |
| Markel Corporation |
| Parker-Hannifin Corporation |
| Teadit Group |
| Zeus Industrial Products, Inc. |
| Others |
Supply & Pricing Matrix
Tetrafluoroethylene monomer supply concentration among a limited set of chemical producers determines both pricing tier spreads and supply chain shape in the ePTFE spotlight-poly-vents market, compressing margins for membrane fabricators while rewarding backward-integrated resin-to-membrane operators with cost pass-through insulation.
Pricing Analysis
German automotive OEMs pay substantial premiums over Chinese industrial buyers for identical membrane specifications due to embedded qualification documentation and ISO 10993 biocompatency certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates medical device-grade membranes from automotive LED vents and industrial gasketing alternatives. Pricing pressure stems from silicone membrane substitution in cost-sensitive industrial applications where extreme chemical resistance is not mandatory. Industrial equipment buyers exhibit highest price sensitivity, while medical device manufacturers accept premium positioning due to regulatory lock-in and multi-year qualification cycles.
Supply Chain Analysis
Export-control restrictions on fluoropolymer precursor technologies limit resin flow from US and European producers to Asian membrane fabricators, forcing Chinese manufacturers toward domestic TFE sourcing. Supply concentrates in the United States, Germany, and China, with Delaware-based resin-to-membrane integrators and Stuttgart-area automotive Tier-1 clusters anchoring respective regional networks. Raw material dependencies center on tetrafluoroethylene monomer, sintered PTFE resin, and high-temperature acrylic adhesive formulations. Single-source vulnerability concentrates around TFE production, where plant outages ripple through membrane pricing within weeks. Distribution runs through direct OEM procurement agreements with embedded volume flexibility clauses, displacing spot-market purchasing in automotive and medical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ePTFE spotlight-poly-vents market sits in early-cycle expansion as automotive LED and laser headlamp architectures proliferate, creating fresh demand corridors for pressure-equalization membrane suppliers qualified to thermal cycling specifications.
For Market Incumbents: Build regulatory documentation moats by accelerating ISO 10993 biocompatency certification investments ahead of FDA 510(k) traceability requirement tightening. Deepen backward integration into TFE resin production to insulate margin structures from monomer price volatility. Capture Chinese EV membrane demand through Yangtze River Delta capacity additions before domestic competitors achieve automotive-grade qualification.
For New Entrants and Emerging Players: Establish a beachhead in industrial equipment venting segments where silicone substitution has created pricing softness and incumbent qualification stickiness is weakest. Target price-sensitive outdoor electrical enclosure applications in Southeast Asian manufacturing corridors. Pursue laminated material R&D partnerships with Asian electronics sealing specialists to bypass resin-production capital barriers.
For Investors and Strategic Acquirers: EU F-Gas Regulation Phase-Down reshapes the acquisition landscape toward compliant resin-to-membrane operations with existing emissions control infrastructure. Long-term viability favors vertically integrated mid-cap specialists with captive TFE supply and medical device qualification portfolios. Watch for MIIT and MEE regulatory calendar announcements as inflection indicators for Chinese membrane demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into TFE Resin | Captive monomer supply insulates margin compression from tetrafluoroethylene price volatility. |
| Medical Device Certification Investment | ISO 10993 documentation creates multi-year supplier lock-in with diagnostic equipment OEMs. |
| China EV Corridor Capacity Expansion | Domestic membrane output captures GB standards-driven specification upgrades in Yangtze manufacturing clusters. |
| Multi-Layer Composite Film Development | Aerospace thermal-acoustic laminates open premium pricing tiers with Boeing and Airbus cabin suppliers. |
| Long-Term Supply Agreement Consolidation | Embedded volume flexibility clauses displace spot purchasing among Stuttgart Tier-1 automotive buyers. |
Research Methodology
Initial hypotheses were tested against primary input from membrane fabrication plant managers, automotive Tier-1 procurement directors, medical device regulatory affairs leads, and fluoropolymer resin technical R&D directors, and refined through secondary validation against SEC 10-K filings, EPA emissions disclosure databases, ECHA REACH registration records, and customs trade flow data. Bottom-up segment sizing triangulated with top-down market reconstruction across product type, application, end user, and technology dimensions.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation across membrane filters, adhesives, gaskets, and seals by product type; medical devices, automotive components, industrial equipment, and electronics by application; and hollow fiber, composite films, laminated materials, and coated fabrics by technology. CAGRs derived from regression analysis of historical qualification cycle compression and regulatory-driven specification upgrade patterns, incorporating automotive LED penetration curves and medical device enclosure protection demand as industry-specific forecast inputs.
Sensitivities concentrate around EU F-Gas Regulation enforcement intensity, Chinese GB standards implementation timelines, and tetrafluoroethylene monomer supply disruption scenarios. Forecasts reflect documented assumptions on qualification stickiness duration and substitution elasticity in industrial segments. Material shifts in fluoropolymer chemistry restriction schedules across EPA, ECHA, and MEE jurisdictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Plastic Dielectric Films Market
Specialty Materials
Sulphur Bentonite Market
Specialty Materials
Silicone Film Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Charge Generation Materials (CGM) Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Electroactive Polymers (EAP) Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
United States Neoprene Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Europe Green Sic Market
Specialty Materials
Organic Scintillators Market
Specialty Materials
Medical Injection Molded Plastics Market
Specialty Materials
Nanoencapsulation Market
Specialty Materials
Halloysite Market