
 Global Conductive Silicone Market | 2026-2036
Global Conductive Silicone Market Size, Share, and Industry Trends Forecast 2026-2036
Global Conductive Silicone Market Foresight
Aftermarket service revenue for EMI shielding retrofit and calibration is reshaping margin distribution across the conductive silicone value chain. Dow Inc. leverages its integrated silicone precursor network to control raw material quality from silicon metal through finished elastomer. Shin-Etsu Chemical Co., Ltd. dominates high-purity silver-filled formulations for semiconductor packaging applications. Momentive Performance Materials Inc. specializes in rapid-cure systems that reduce cycle times for automotive electronics assemblers.
Conductive silicone comprises polydimethylsiloxane matrices loaded with metallic or carbonaceous fillers to achieve volume resistivities typically spanning 10^-3 to 10^2 ohm-cm, depending on filler loading and morphology. Its primary commercial purpose is to provide elastic electrical pathways, electromagnetic interference attenuation, and static dissipation in assemblies where rigid conductors would fracture under thermal or mechanical stress. Silver-filled silicone commands the dominant value share due to its unmatched conductivity and reliability in aerospace and medical device interconnects, while carbon-filled variants represent the fastest-expanding volume pool as cost-sensitive automotive and consumer electronics applications multiply. Screen printing technology leads in deposition method adoption for thin-film sensor and wearable circuit fabrication, though injection molding is displacing compression molding in high-throughput automotive gasket production.
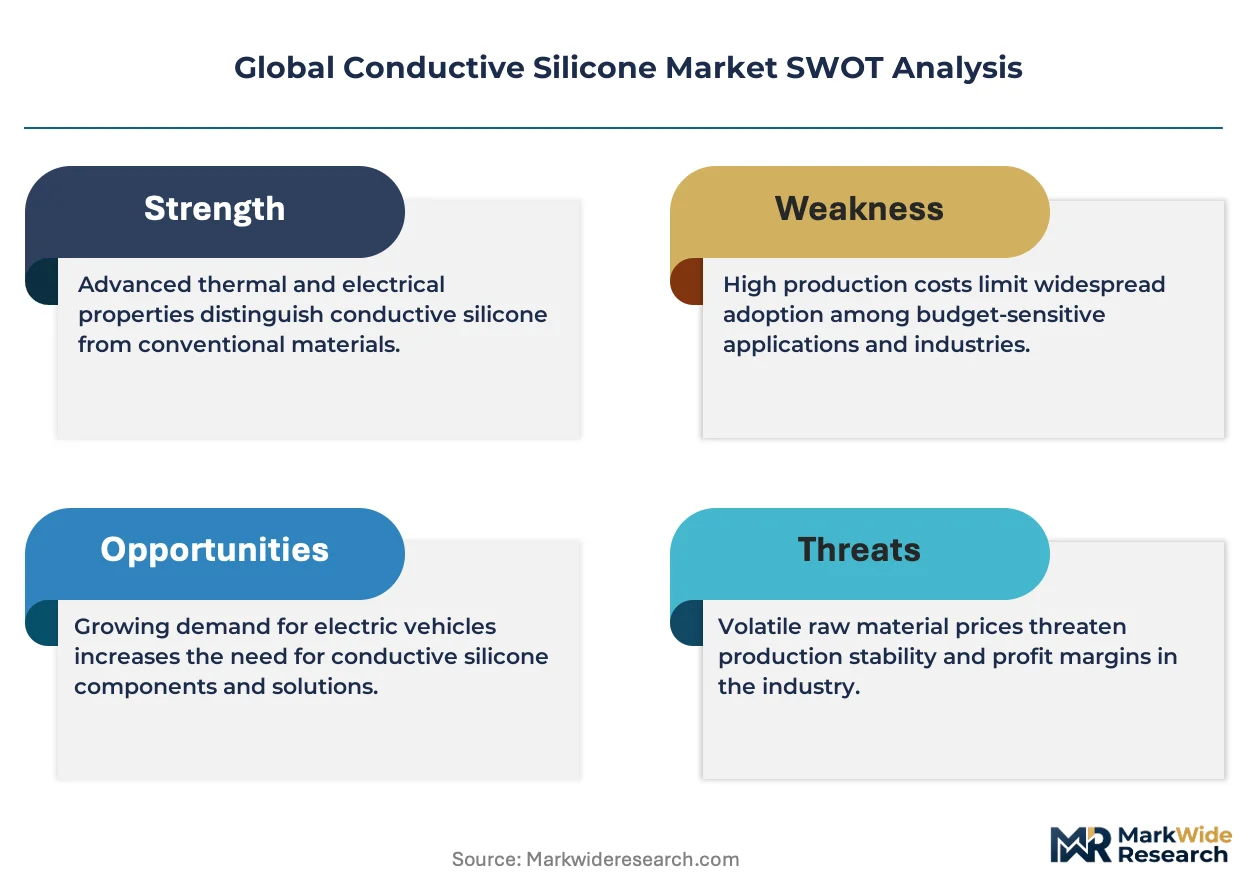
EPA guidelines under the Toxic Substances Control Act govern filler handling and volatile organic compound emissions during silicone curing operations in the United States, while REACH restrictions on nickel and certain silver compounds in Europe constrain formulation choices for exporters. China's GB standards and MIIT directives on electronic material purity create separate compliance thresholds for products entering that supply chain. Stakeholders must monitor regulatory divergence across these jurisdictions to avoid reformulation costs that could erase technology-specific margin advantages.
Market Dynamics
Miniaturization mandates in wearable electronics are compressing form factors below 0.5 millimeters, forcing formulators to balance filler loading against elastomer elasticity in ways that reshape competitive capability requirements.
Growth Catalysts
- Wearable Electronics Miniaturization:Device manufacturers in China and South Korea demand sub-millimeter conductive traces that tolerate repeated flex cycling without conductivity degradation.
- EPA VOC Emission Standards:Tightening limits on volatile organic compound releases during silicone curing operations are accelerating water-based and UV-cure system adoption across United States automotive electronics suppliers.
- Silver Nanowire Morphology Advances:High-aspect-ratio filler geometries achieve percolation thresholds at 15-20% lower loading than conventional flake, preserving mechanical properties in medical interconnect applications.
Market Restraints
- Silver Price Volatility:Precious metal cost swings exceeding 30% annually compress formulation margins and force hedging overhead onto mid-tier compounders lacking captive metal sourcing.
- High-Purity Silicone Precursor Concentration:Five integrated chemical conglomerates control 70% of D4/D5 cyclosiloxane supply, creating single-source vulnerability for specialized conductive grade production.
- Thermal Curing Energy Intensity:Conventional platinum-catalyzed systems require 150°C for 30 minutes, limiting compatibility with temperature-sensitive polyimide substrates in flexible hybrid electronics.
Strategic Opportunities
- India Electronics Manufacturing Incentives:PLI scheme disbursements for semiconductor packaging and mobile device assembly are creating first-mover advantage for localized conductive silicone compounding capacity.
- Biocompatible Implantable Applications:Long-term implantable neurostimulator leads represent an underserved segment where ISO 10993-5 cytotoxicity compliance creates defensible positioning.
- Photonic Curing Convergence:Integration of UV-LED arrays with roll-to-roll processing is hybridizing deposition and curing into single-pass manufacturing for stretchable sensor arrays.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Compound expertise spanning silicone rheology, filler surface chemistry, and electrical percolation modeling concentrates among retiring specialists at major integrated producers.
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA 510(k), EMA MDR, and NMPA registration for medical-grade conductive adhesives extends commercialization cycles to 24-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Conductive Silicone Market |
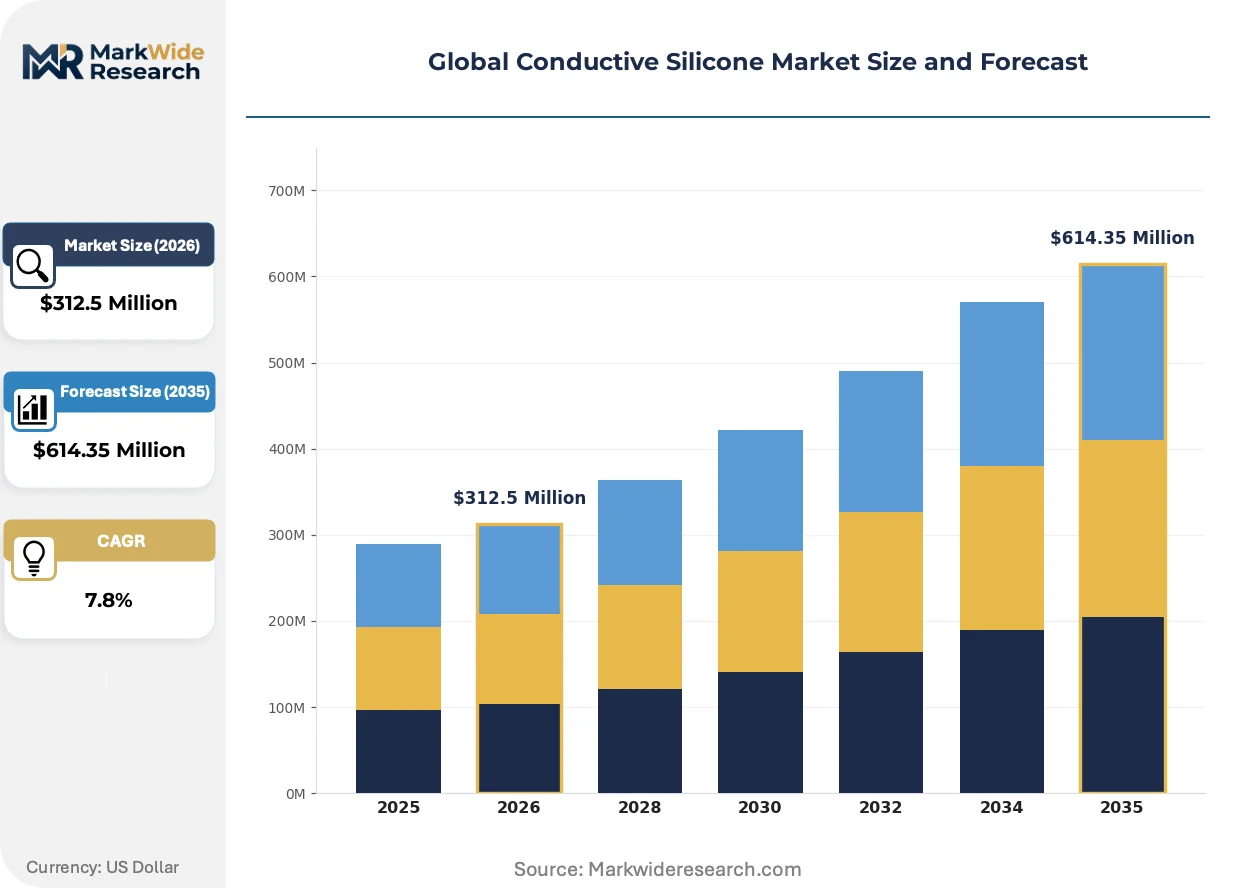
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $614.35 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver-Filled Silicone, Carbon-Filled Silicone, Aluminum-Filled Silicone, Copper-Filled Silicone, Nickel-Filled Silicone Technology: Screen Printing, Injection Molding, Extrusion, Compression Molding, Transfer Molding Application: Antistatic Coatings, EMI Shielding, Sensors, Wearable Electronics, Automotive Electronics End User: Consumer Electronics Manufacturers, Aerospace Suppliers, Defense Contractors, Telecommunications Providers, Industrial Automation Firms |
| Companies Covered | Dow Inc., Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., Momentive Performance Materials Inc., Avantor Inc., KCC Corporation, Elkem AS, China National Bluestar (Group) Co., Ltd., Nusil Technology LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Conductive Silicone Market Shifts & Advancements
Formulation science is converging with advanced deposition equipment to enable geometries previously unattainable, while regulatory fragmentation across major economies is forcing modular compliance architectures.
Carbon nanotube-silver hybrid fillers are hybridizing conductivity and mechanical resilience in ways that pure metal loadings cannot match. Medical device manufacturers in Switzerland and Germany are qualifying these systems for neurostimulation leads requiring 10 million flex cycles. The structural consequence is compression of conventional silver-flake formulations into commodity price tiers.
REACH restrictions on nickel release rates are eliminating nickel-coated graphite from European medical and consumer wearable supply chains. Formulators must reformulate with silver-coated alternatives or conductive carbons, increasing raw material costs by 40-60% for affected product lines. German automotive suppliers are responding by consolidating qualified material lists to reduce testing redundancy.
Aftermarket calibration and retrofit services are unbundling from original equipment supply contracts in aerospace EMI shielding applications. Maintenance, repair, and overhaul providers in the United States and France are capturing recurring revenue streams previously retained by material suppliers. This shift is most visible in satellite and defense electronics where field service life exceeds 15 years.
Global Conductive Silicone Market Segmentation
Conductive silicone procurement patterns diverge sharply across application contexts, with aftermarket service intensity and formulation complexity driving fundamentally different sourcing behaviors. Understanding these segment boundaries clarifies where margin pools concentrate and where commoditization pressures intensify.
Product Type:
Aftermarket service intensity peaks with silver-filled systems requiring periodic conductivity verification and filler replenishment in long-life aerospace installations.
- Silver-Filled Silicone:Polydimethylsiloxane matrices loaded with silver flake or nanowire fillers achieve volume resistivities below 10^-3 ohm-cm. Demand concentrates in Swiss and German medical device manufacturing for neurostimulation leads requiring ISO 10993-5 cytotoxicity compliance alongside electrical reliability.
- Carbon-Filled Silicone:Carbon black, graphite, or carbon nanotube loadings trade conductivity for mechanical flexibility and cost efficiency. Automotive electronics assemblers in Germany and the United States are expanding procurement fastest as EPA VOC standards tighten and water-based curing systems gain qualification.
- Aluminum-Filled Silicone:Moderate conductivity at reduced material cost serves industrial automation applications where electrical performance thresholds are less stringent.
- Copper-Filled Silicone:Oxidation sensitivity limits deployment to protected environments, primarily telecommunications infrastructure with controlled atmospheric conditions.
- Nickel-Filled Silicone:REACH restrictions on nickel release rates are eliminating this formulation from European medical and consumer wearable supply chains, forcing reformulation toward silver-coated alternatives.
Silver-filled silicone holds the largest share; momentum sits with carbon-filled variants as cost-sensitive automotive and consumer electronics applications multiply.
Technology:
Cost tier stratification separates capital-intensive molding equipment from lower-barrier deposition methods, with volume scale determining technology selection.
- Screen Printing:Stencil-based deposition of viscous conductive pastes enables sub-millimeter trace geometries on flexible substrates. Wearable electronics manufacturers in South Korea and China demand this capability for stretchable sensor arrays tolerating repeated flex cycling.
- Injection Molding:High-pressure injection of low-viscosity compounds into precision cavities supports complex gasket geometries. Automotive suppliers in Germany are displacing compression molding with this approach to reduce cycle times in high-throughput electronics housing production.
- Extrusion:Continuous profile generation serves cable shielding and gasket cord applications where uniform cross-sections suffice.
- Compression Molding:Lower capital requirements persist in aerospace and medical device prototyping where batch sizes remain small and tooling flexibility matters.
- Transfer Molding:Intermediate complexity serves defense electronics with moderate volume requirements and exacting dimensional tolerances.
Injection molding dominates automotive volume; screen printing is climbing the fastest in wearable electronics fabrication.
Application:
Customer type differentiation separates specification-driven aerospace procurement from price-sensitive consumer electronics sourcing, with certification burden as the dividing line.
- EMI Shielding:Conductive gaskets and coatings attenuate electromagnetic interference across frequency ranges critical for defense and telecommunications equipment. Aftermarket calibration and retrofit services in the United States and France are unbundling from original supply contracts, creating recurring revenue streams in satellite electronics with field service life exceeding 15 years.
- Wearable Electronics:Stretchable interconnects and sensors require formulations balancing filler loading against elastomer elasticity. Miniaturization mandates in China and South Korea are compressing form factors below 0.5 millimeters, forcing formulators to preserve conductivity through repeated deformation cycles.
- Antistatic Coatings:Surface resistivity control prevents electrostatic discharge damage in electronics assembly environments.
- Sensors:Piezoresistive and capacitive sensing elements leverage conductive silicone's mechanical compliance for pressure and strain measurement.
- Automotive Electronics:Battery management system gaskets and ADAS sensor housings combine thermal stability with electrical functionality.
EMI shielding holds the largest share; wearable electronics is gaining share fastest as miniaturization requirements intensify.
End User:
Supply concentration varies dramatically, with defense contractors consolidating qualified material lists while consumer electronics manufacturers fragment procurement across multiple compounders.
- Consumer Electronics Manufacturers:High-volume, cost-sensitive procurement of carbon-filled formulations for device housings and internal interconnects. Chinese and South Korean device makers are driving specification evolution toward sub-millimeter trace capabilities.
- Aerospace Suppliers:Silver-filled systems for satellite and aircraft electronics with 15-25 year service life requirements. United States and French maintenance providers are capturing aftermarket service revenue previously retained by material suppliers.
- Defense Contractors:Stringent qualification protocols and long certification timelines favor established suppliers with proven track records.
- Telecommunications Providers:Infrastructure shielding and antenna gasket applications with moderate performance requirements at scale.
- Industrial Automation Firms:Robotics and process control applications prioritizing mechanical durability over electrical optimization.
Consumer electronics manufacturers hold the largest share; aerospace suppliers are expanding most quickly as aftermarket service unbundling reshapes revenue capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies. Switzerland and Germany prioritize medical-grade silver formulations for implantable neurostimulators. China and South Korea drive carbon-filled volume for cost-sensitive wearable electronics. The United States splits procurement between aerospace EMI shielding and automotive electronics gaskets.
United States
Defense contractors and satellite manufacturers in California and Colorado sustain demand for silver-filled systems with 15-25 year service life. EPA guidelines under the Toxic Substances Control Act govern filler handling and VOC emissions during curing operations. Dallas-Fort Worth hosts maintenance, repair, and overhaul providers capturing aftermarket calibration revenue previously retained by material suppliers.
Germany
Automotive electronics assemblers in Stuttgart and Munich are displacing compression molding with injection molding to reduce cycle times in high-throughput production. REACH restrictions on nickel release rates eliminate nickel-coated graphite from medical and consumer wearable supply chains. Bavarian medical device manufacturers qualify carbon nanotube-silver hybrid fillers for neurostimulation leads requiring 10 million flex cycles.
China
Wearable electronics manufacturers in Shenzhen and Dongguan compress form factors below 0.5 millimeters for stretchable sensor arrays. GB standards and MIIT directives on electronic material purity create separate compliance thresholds for products entering domestic supply chains. The Yangtze River Delta concentrates formulation development for sub-millimeter conductive traces tolerating repeated flex cycling.
Switzerland
Neurostimulator lead manufacturers in the Lake Geneva region demand ISO 10993-5 cytotoxicity compliance alongside electrical reliability. Swissmedic regulations govern long-term implantable applications where material purity thresholds exceed general industrial grades. Basel anchors high-purity silver-filled formulation development for cardiac and neural stimulation devices.
South Korea
Consumer electronics giants in Seoul and Suwon drive specification evolution toward sub-millimeter trace capabilities for foldable displays and wearable devices. MFDS registration requirements extend commercialization timelines for medical-grade conductive adhesives. The Seoul Capital Area concentrates screen printing technology adoption for stretchable interconnect fabrication.
Global Conductive Silicone Market Competitive Landscape
Capability concentration sits with integrated chemical conglomerates controlling silicone precursor networks; scale advantage sits with specialized compounders serving high-volume automotive and consumer electronics. Five integrated producers control 70% of D4/D5 cyclosiloxane supply, creating single-source vulnerability for specialized conductive grade production. Strategic archetypes include backward-integrated material giants, high-purity formulation specialists, and rapid-cure system innovators. Dominant competitive moves encompass geographic expansion into India under PLI scheme incentives and portfolio diversification toward biocompatible implantable applications.
Within the integrated precursor tier, Dow Inc. and Wacker Chemie AG occupy positions spanning silicon metal through finished elastomer, enabling raw material quality control across the value chain. Shin-Etsu Chemical Co., Ltd. anchors the high-purity formulation segment, representing the specialist archetype focused on semiconductor packaging and medical device applications. Momentive Performance Materials Inc. exemplifies the rapid-cure innovation vector, sitting within the automotive electronics supplier ecosystem where cycle time reduction commands premium positioning.
| Leading Market Players |
|---|
| Dow Inc. |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd. |
| Momentive Performance Materials Inc. |
| Avantor Inc. |
| KCC Corporation |
| Elkem AS |
| China National Bluestar (Group) Co., Ltd. |
| Nusil Technology LLC |
| Others |
Supply & Pricing Matrix
Yantian-Shenzhen port freight corridors transmit silver price volatility directly into formulation costs, amplifying margin compression for compounders lacking captive metal sourcing while reinforcing price differentiation between integrated producers and specialized compounders across automotive and medical supply chains.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated silicone producers and Tier 1 automotive suppliers, insulating volume buyers from silver spot market swings while spot purchasing prevails among mid-tier compounders serving fragmented electronics manufacturers. Price differentiation separates ISO 10993-5 certified medical grades from industrial formulations, with cytotoxicity compliance commanding substantial premiums. Cost compression in carbon-filled tiers is intensifying as Chinese wearable electronics manufacturers consolidate procurement around fewer qualified suppliers. Consumer electronics assemblers exhibit highest price sensitivity, demanding annual cost reductions; aerospace contractors show lowest sensitivity, prioritizing 15-25 year service life reliability over unit economics.
Supply Chain Analysis
Export control regimes limiting high-purity silicone precursor technology flows from Germany and the United States to Chinese compounders are fragmenting formulation capability development across jurisdictions. Manufacturing concentrates in China, Germany, and the United States, with D4/D5 cyclosiloxane supply anchored in five integrated chemical conglomerates. Raw material dependencies span silicon metal from Norway and Brazil, silver flake from Mexican and Polish refiners, and platinum catalysts from South African suppliers. Single-source vulnerability in specialized conductive grade production creates structural risk. Distribution runs through authorized distributor networks for medical and aerospace grades, with direct procurement relationships dominating high-volume automotive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The conductive silicone market sits at an inflection where REACH nickel restrictions and EPA VOC mandates are simultaneously eliminating legacy formulations and accelerating qualification of water-based and hybrid filler systems, creating asymmetric opportunity for first-movers in compliant chemistry.
For Market Incumbents: Harden supply security through backward integration into D4/D5 cyclosiloxane production or binding long-term precursor agreements with Wacker Chemie AG and Dow Inc., eliminating single-source exposure that threatens specialized conductive grade output. Deepen certification moats by accelerating ISO 10993-5 cytotoxicity data packages for implantable neurostimulator applications before regulatory timelines extend further.
For New Entrants and Emerging Players: Build out compounding capacity in India under PLI scheme disbursements for semiconductor packaging, capturing first-mover positioning before established producers localize. Target carbon-filled formulations for automotive battery management system gaskets where EPA VOC compliance requirements are disqualifying incumbent water-based systems and creating qualification windows for rapid-cure alternatives.
For Investors and Strategic Acquirers: Rapid-cure formulation specialists with automotive OEM validation represent the most defensible acquisition archetype, given cycle time reduction premiums and sticky supplier relationships. Watch for inflection when water-based curing systems achieve qualification thresholds comparable to thermal-cure alternatives in flexible hybrid electronics applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Precursors | Captive D4/D5 supply eliminates raw material quality variability for medical-grade output. |
| Water-Based Curing System Qualification | EPA VOC compliance opens automotive electronics procurement previously closed to solvent-based systems. |
| Silver Nanowire Filler Adoption | High-aspect-ratio geometries reduce precious metal loading while preserving conductivity in sub-millimeter traces. |
| India PLI Scheme Localization | Domestic compounding capacity captures semiconductor packaging demand from government-incentivized assembly. |
| Biocompatible Implantable Certification | ISO 10993-5 compliance creates defensible positioning in underserved neurostimulator lead segments. |
Research Methodology
Initial hypotheses were tested against primary input from silicone formulation chemists, automotive electronics procurement directors, medical device regulatory affairs leads, and conductive filler suppliers, then refined through secondary validation against SEC 10-K filings, customs trade data, EPA enforcement actions, and REACH substance restriction updates. Bottom-up triangulation across end-use demand modeling and top-down supply capacity assessment anchored volume and value estimates.
Demand-supply-balance framing structured the analytical framework across the projection horizon, with segmentation modeling spanning filler type, deposition technology, application function, and end-user industry. CAGRs were derived from elasticity-adjusted growth rate synthesis. Key inputs included silver price forward curves, automotive electronics content-per-vehicle trajectories, and wearable device shipment forecasts by form factor class.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed chemical conglomerates would shift outcomes substantially. Material shifts in REACH substance restriction scope or EPA VOC emission thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Africa Collagen Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
UK Lab-Grown Diamonds Market
Specialty Materials
Fumed Silica Market
Specialty Materials
Semiconductor O-Rings Market
Specialty Materials
Non-Semiconductor Neon Market
Specialty Materials
Global Liquid Crystal Polymer (LCP) Films and Laminates Market
Specialty Materials
Retro Reflective Materials Market
Specialty Materials
Nitrocellulose Market
Specialty Materials
Global Flexible Substrates Market
Specialty Materials
Vegan Wax Market
Specialty Materials
North America Solar Control Window Films Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market
Specialty Materials
Global Graphic Film Market