
 Solar Control Films Market | 2026-2036
Solar Control Films Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Control Films Market Intelligence
The proliferation of advanced nano-ceramic coating technologies is fragmenting the established market for purely metalized films, creating new performance tiers. Saint-Gobain leverages its deep expertise in glass and building materials to offer integrated solutions. 3M Company differentiates with its extensive patent portfolio in multilayer optical films, while Eastman Chemical Company competes on manufacturing scale and a vast global distribution network.
Solar control films are thin, multi-layered polymer laminates applied to glass surfaces to manage solar radiation. These films often incorporate sputtered ceramic particles or vapor-deposited metals to selectively block UV and infrared wavelengths. Their primary function is to reduce heat gain, minimize glare, and lower cooling costs in buildings and vehicles. While reflective films for commercial buildings constitute a large segment, the automotive windshields application shows strong uptake of advanced ceramic coatings.
Building energy codes are a primary market driver, with frameworks like the US EPA's ENERGY STAR program and the EU's Energy Performance of Buildings Directive setting performance benchmarks. In China, national GB standards for green buildings mandate specific levels of solar heat gain control. Navigating these divergent regional material standards and certification requirements is a critical challenge for manufacturers seeking to maintain broad market access.
Market Dynamics
The market's primary dynamic is the global push for energy efficiency, codified in building regulations like the EU's EPBD and China's GB standards. This creates a powerful demand pull that manufacturers must meet while navigating technological fragmentation between advanced ceramic and traditional metalized films.
Growth Catalysts
- Energy Efficiency Mandates:The European Union's Green Deal and its building renovation targets accelerate film adoption as a cost-effective method to improve the energy performance of existing building stock.
- Automotive Sector Demand:The automotive industry's focus on electric vehicle range and passenger comfort drives uptake of high-performance nano-ceramic films for windshields and panoramic roofs to reduce HVAC load.
- Construction Activity:Rapid urbanization and new construction projects in Southeast Asian economies, particularly Vietnam and Indonesia, create significant installation opportunities for both architectural and automotive applications.
Market Restraints
- High Initial Cost:The premium price of advanced nano-ceramic and multi-layer sputtered films compared to standard tinted glass or basic dyed films can be a barrier for budget-sensitive construction projects.
- Performance Durability:Lower-quality films are susceptible to degradation, including discoloration, peeling, and bubbling, from UV exposure over time, which can damage brand reputation and deter adoption.
- Substitution by Smart Glass:In new high-end architectural projects, electrochromic or "smart" glass presents a direct substitution threat, offering dynamic tinting control without the need for aftermarket film application.
Strategic Opportunities
- Architectural Retrofitting:A vast opportunity exists in retrofitting the existing global commercial building stock, which is often energy-inefficient, to meet modern energy codes and corporate sustainability goals.
- Product Function Integration:There is significant potential in developing hybrid films that combine solar control with other functionalities, such as security, anti-graffiti, or radio-frequency transparency for 5G signals.
- Geographic Expansion:Markets in Latin America, including Brazil and Mexico, offer substantial growth potential due to high solar irradiance, a growing vehicle fleet, and developing green building standards.
Industry Challenges
- Divergent Regional Standards:Manufacturers face complexity and cost in certifying products to meet varying regional performance benchmarks, such as the US ENERGY STAR program versus European CE marking requirements.
- Installer Skill Gap:A shortage of properly trained and certified technicians for applying large-format architectural films can lead to installation errors, reducing performance and damaging customer satisfaction.
- Intellectual Property Protection:Protecting proprietary formulations and complex multi-layer coating processes from infringement is a persistent challenge, particularly for innovators in nano-ceramic technology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Control Films Market |
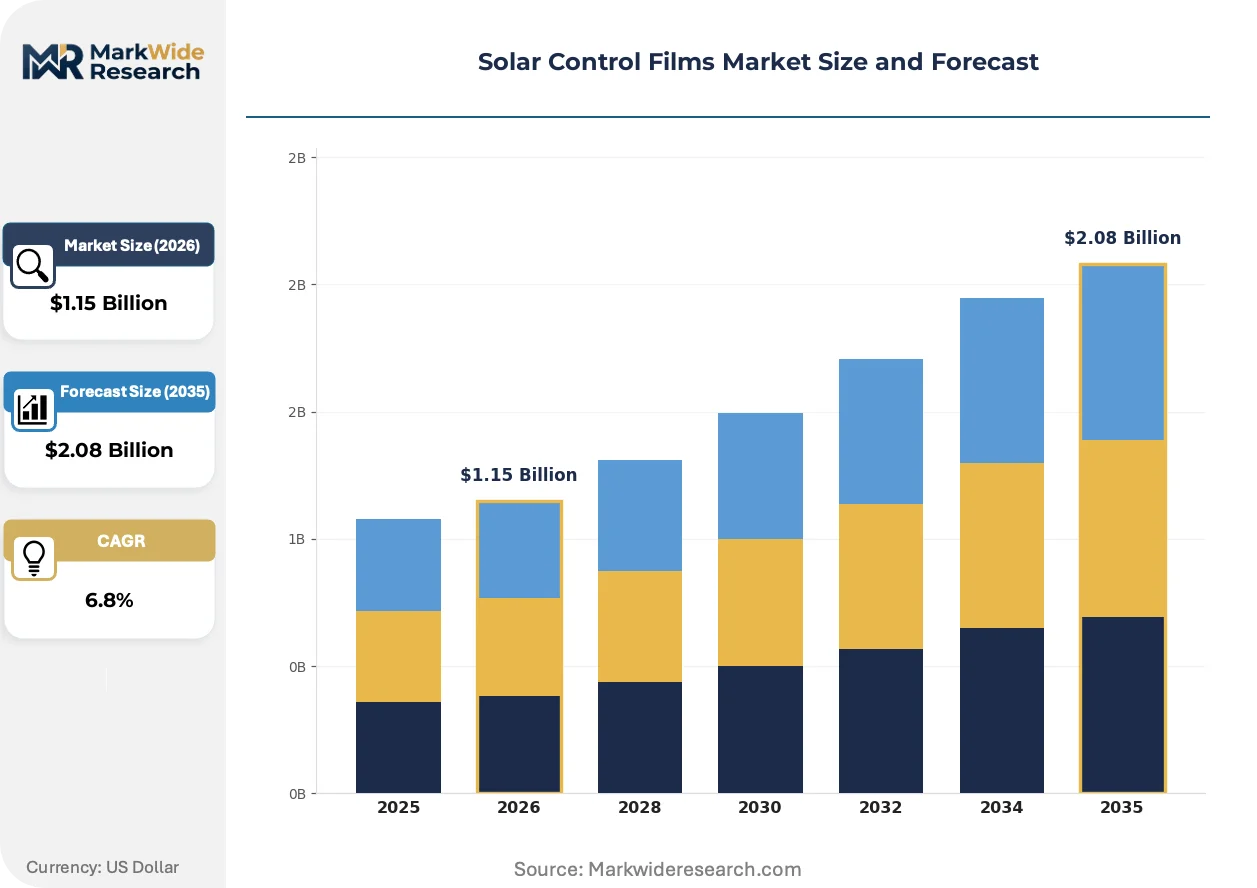
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reflective Films, Tinted Films, Clear Films, Hybrid Films Application: Commercial Buildings, Automotive Windshields, Residential Windows, Electronic Devices End User: Facade Installers, Vehicle Manufacturers, Construction Companies, Electronics OEMs Technology: Metalized Coatings, Ceramic Coatings, Dyed Films, Multilayer Laminates |
| Companies Covered | 3M Company, Eastman Chemical Company, Saint-Gobain, Avery Dennison Corporation, Garware Hi-Tech Films, Madico Inc, Johnson Window Films, The Window Film Company, Solar Control Films Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Control Films Market Strategic Shifts & Innovations
Innovation in solar control films is moving beyond simple reflectivity towards selective solar spectrum management. This transition is driven by advances in material science and a global regulatory focus on decarbonizing the built environment and transportation sectors.
Sputtered multi-layer films use nano-scale ceramic or metallic particles to selectively block infrared and UV radiation while allowing high visible light transmission. The automotive and premium architectural sectors are adopting these for superior heat rejection without a highly reflective appearance. This development is hybridizing the market, creating a distinct performance tier that coexists with traditional dyed or metalized films.
The European Union's Energy Performance of Buildings Directive (EPBD) sets stringent requirements for reducing energy consumption in buildings. This mandate directly incentivizes retrofitting windows with high-performance films as a cost-effective compliance pathway. Architectural film sales in EU member states like Germany and France are consequently seeing increased specification for projects seeking to meet these standards.
Building owners are shifting purchasing criteria from upfront product cost to total lifecycle performance and verifiable energy savings. This change favors solution-based sales over transactional, commoditized film distribution, disrupting traditional wholesale channels. The trend is most pronounced in the North American commercial real estate market, where ESG reporting increasingly influences procurement decisions.
Solar Control Films Market Segmentation
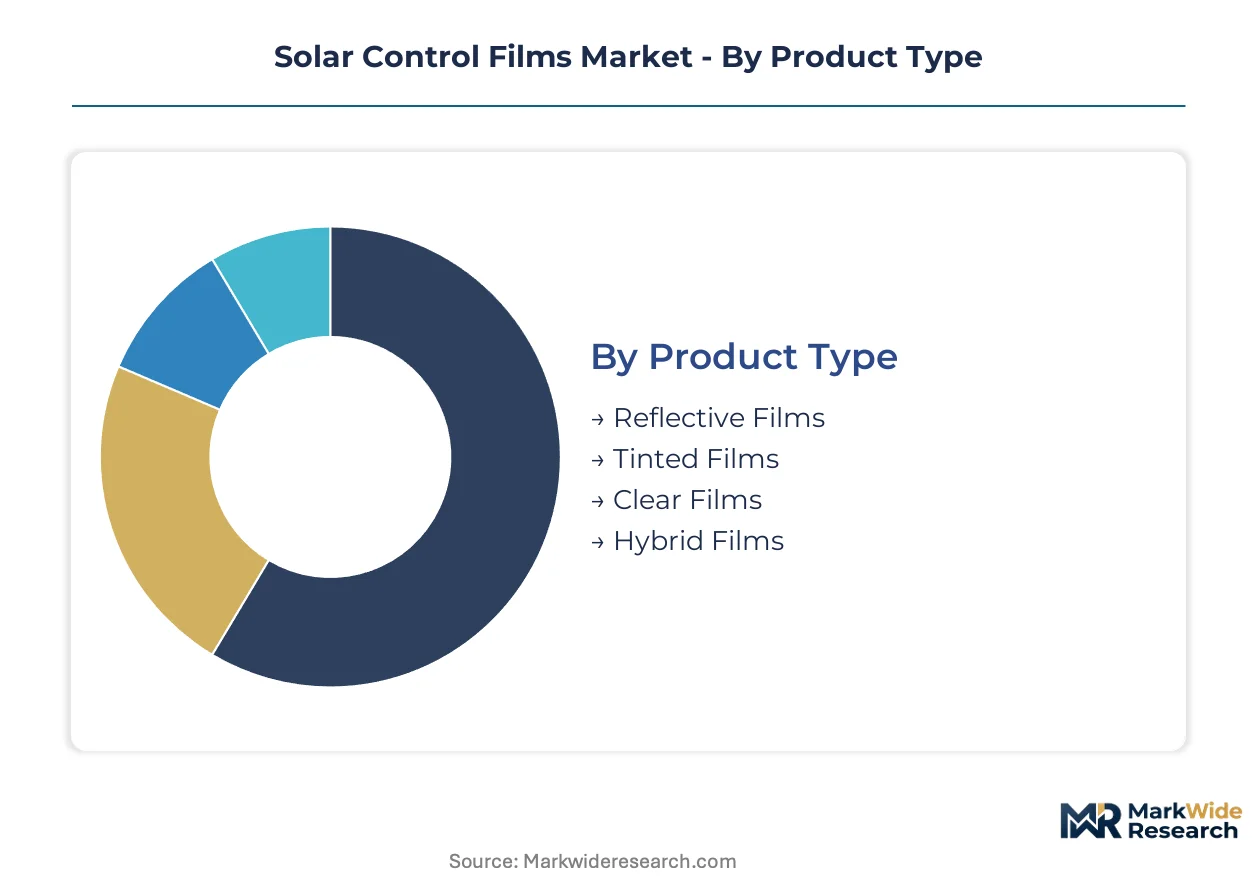
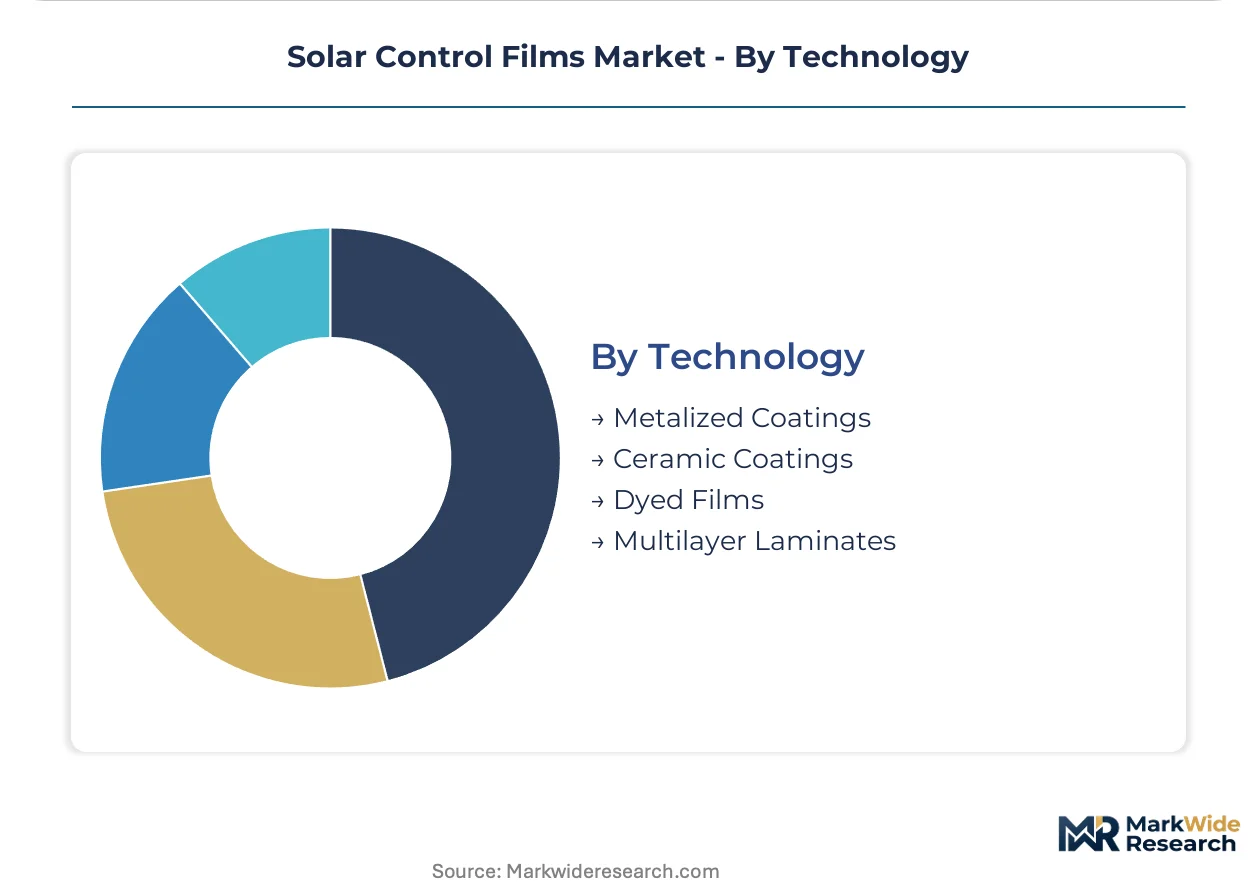
The solar control films market segments across various product types, applications, end users, and underlying technologies. Analyzing these distinct segments reveals specific demand patterns, technological preferences, and competitive dynamics influencing market growth. Understanding this segmentation is crucial for manufacturers to align product development with evolving market needs and regulatory pressures.
Product Type:
The product type segmentation highlights the blend of mature and emerging film solutions available to consumers and businesses.
- Reflective Films:These films incorporate vapor-deposited metals to reflect solar energy, providing significant heat rejection and glare reduction. Commercial buildings in sun-intensive climates like Brazil widely deploy reflective films to manage internal temperatures.
- Hybrid Films:Combining dyed layers with metalized or ceramic particles, hybrid films offer a balance of performance, aesthetics, and cost. Demand for these films is concentrating in architectural retrofitting projects seeking improved energy efficiency without a highly reflective exterior.
- Tinted Films:These films use dyes to absorb solar energy, reducing visible light transmission and glare. Residential window applications in Mexico frequently utilize tinted films for basic privacy and moderate heat control.
- Clear Films:Designed for minimal visible impact, clear films primarily block UV and infrared radiation using advanced ceramic or multi-layer structures. Their use is growing in museums and retail spaces in Germany to protect interiors from sun damage.
Reflective Films retains volume leadership; Hybrid Films holds the steepest expansion curve.
Application:
Application segments delineate where solar control films are integrated, reflecting diverse functional requirements and performance expectations.
- Automotive Windshields:Advanced nano-ceramic films are engineered for automotive windshields to reduce heat gain and UV exposure, directly impacting vehicle cabin comfort and HVAC efficiency. The automotive sector's focus on electric vehicle range in the US drives demand for these high-performance solutions.
- Commercial Buildings:Films for commercial buildings address energy efficiency, glare reduction, and security, often applied to large glass facades. The EU's Energy Performance of Buildings Directive (EPBD) is a primary driver for film adoption in existing European commercial structures.
- Residential Windows:These films are applied to home windows for privacy, heat control, and UV protection, enhancing living comfort. Rapid urbanization in Southeast Asian economies like Vietnam fuels new installations in residential construction.
- Electronic Devices:Specialized films protect electronic displays from glare and heat build-up, extending device lifespan and improving user experience. Demand for these films is increasing in portable consumer electronics in South Korea.
Automotive Windshields shows the most dynamic growth; Commercial Buildings maintains the largest installed base.
End User:
The end user segmentation illustrates the primary purchasers and specifiers of solar control film products across various industries.
- Vehicle Manufacturers:These entities integrate solar control films directly into new vehicle production lines, particularly for premium models and electric vehicles. Vehicle manufacturers in Japan prioritize films that meet stringent optical clarity and durability standards.
- Facade Installers:Specializing in architectural glazing, facade installers apply solar control films to building exteriors and interiors during construction or renovation. The trend towards sustainable building certifications in France drives their procurement of high-performance films.
- Construction Companies:General construction firms procure solar control films for new building projects, often as part of the overall glazing package. New construction activity in Indonesia creates significant opportunities for these companies to specify film solutions.
- Electronics OEMs:Original Equipment Manufacturers in the electronics sector incorporate films into their devices for thermal management and display enhancement. Consumer electronics companies in China are a significant customer group for these specialized films.
Vehicle Manufacturers demonstrates the most significant expansion; Facade Installers represents a stable demand source.
Technology:
Technology segmentation differentiates films by their core material science and manufacturing processes, impacting performance characteristics.
- Ceramic Coatings:These films utilize nano-ceramic particles embedded within multiple layers to selectively block infrared and UV radiation while maintaining high visible light transmission. Demand for ceramic coatings is accelerating in the automotive sector for windshields due to superior heat rejection.
- Multilayer Laminates:Comprising multiple thin polymer layers, often with sputtered metals or ceramics, these films achieve precise solar spectrum control. Companies like 3M leverage extensive patent portfolios in multilayer optical films to cater to premium architectural projects.
- Metalized Coatings:These films feature a thin layer of metal, such as aluminum or silver, deposited onto a polymer substrate to reflect solar energy. They are widely used in commercial buildings for effective heat and glare reduction.
- Dyed Films:Produced by infusing dyes into film layers, these products primarily absorb solar energy and reduce visible light. Dyed films offer a cost-effective solution for basic tinting and UV protection in residential markets.
Ceramic Coatings exhibits the most rapid market penetration; Metalized Coatings remains a foundational technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in the solar control films market varies significantly by region, driven by distinct regulatory environments and construction or automotive manufacturing hubs. Government mandates for energy efficiency and consumer preferences for comfort shape demand patterns across diverse geographies. This regional variability necessitates tailored market approaches for manufacturers.
United States
Demand for high-performance solar control films in the United States is strong, particularly from the automotive sector and commercial building retrofits. The US EPA's ENERGY STAR program encourages the adoption of energy-efficient windows, indirectly boosting film sales. Major metropolitan areas like New York and Los Angeles drive architectural film demand for both new construction and existing building upgrades.
Germany
Germany exhibits robust demand for advanced ceramic and multi-layer films, particularly in its stringent building and automotive sectors. The European Union's Energy Performance of Buildings Directive (EPBD) mandates energy efficiency, accelerating film adoption in commercial and residential properties. The automotive manufacturing cluster in Bavaria integrates high-performance films into premium vehicle production lines.
China
China's solar control films market expands rapidly, fueled by extensive new construction and a growing automotive industry. National GB standards for green buildings increasingly mandate specific levels of solar heat gain control for new projects. Major urban centers like Shanghai and Beijing represent significant installation opportunities for both architectural and automotive applications.
Japan
Japan's market prioritizes high-quality, durable solar control films for both vehicle manufacturers and commercial buildings. Vehicle manufacturers in Japan integrate films that meet stringent optical clarity and longevity standards for new models. The dense urban environments of Tokyo and Osaka drive demand for films that enhance energy efficiency and occupant comfort in high-rise structures.
Vietnam
Rapid urbanization and expanding construction activity in Vietnam create substantial opportunities for solar control films in residential and commercial applications. The government's focus on sustainable development encourages the use of energy-efficient building materials. Cities like Ho Chi Minh City and Hanoi experience high demand for films to manage heat gain in new housing and commercial complexes.
Solar Control Films Market Key Industry Players
Channel-controlling players compete with product-specialist players in the solar control films market, creating a tiered competitive structure. Large diversified materials companies often leverage their existing distribution networks and brand recognition. Niche innovators focus on proprietary coating technologies or specialized film functionalities. Strategic partnerships and targeted M&A activity are common competitive moves.
Among global materials science companies, 3M Company and Eastman Chemical Company exemplify firms with broad product portfolios and extensive research capabilities. Saint-Gobain, a French multinational, represents a vertically integrated player leveraging its glass and building materials expertise. These companies anchor the premium and high-performance segments, often differentiating through patent portfolios and global manufacturing scale.
| Leading Market Players |
|---|
| 3M Company |
| Eastman Chemical Company |
| Saint-Gobain |
| Avery Dennison Corporation |
| Garware Hi-Tech Films |
| Madico Inc |
| Johnson Window Films |
| The Window Film Company |
| Solar Control Films Inc |
| Others |
Cost & Logistics Intelligence
The Trans-Pacific shipping lanes' volatility in freight costs directly influences the pricing of raw materials like polymer films and specialty chemicals, impacting supply concentration and downstream price differentiation for solar control films. This dynamic affects both automotive and architectural film segments.
Pricing Analysis
Cost-plus contract patterns, often indexed to polymer resin prices, govern long-term agreements for solar film manufacturers. Pricing stratifies across premium, standard, and economy tiers, driven by performance differences in nano-ceramic versus traditional metalized films and specific building certifications like ENERGY STAR. Cost compression in basic dyed films intensifies due to commoditization and increased competition. Residential consumers exhibit the highest price sensitivity, while vehicle manufacturers for high-end electric vehicles prioritize performance over initial cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common, reflecting the capital-intensive nature of advanced film manufacturing. Supply concentrates in China for polymer substrates and specialty chemicals, while Germany provides advanced sputtering equipment. The market relies heavily on PET films, various metals, and nano-ceramic particles as key raw materials. Single-source vulnerability for highly specialized ceramic precursors represents a structural risk. Distribution runs through a dual channel of architectural film installers and direct automotive OEM partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar control films market is at a platform-economics inflection point, driven by the increasing interoperability between building management systems and smart window solutions. This shift creates new opportunities for integrated energy efficiency ecosystems.
For Market Incumbents: Insulate core architectural and automotive segments by accelerating investment in proprietary nano-ceramic formulations to counter smart glass substitution. Deepen R&D efforts in multi-layer optical films to enhance performance beyond basic heat rejection. Pursue strategic partnerships with large construction firms to secure long-term supply contracts. Emphasize stringent certification processes, particularly for compliance with the EU's Energy Performance of Buildings Directive.
For New Entrants and Emerging Players: Establish a beachhead in the Southeast Asian residential retrofit market by offering cost-effective hybrid films. Target underpenetrated segments like films combining solar control with anti-graffiti or security features. A go-to-market strategy focusing on bundled energy audit services and verifiable savings will resonate with budget-conscious property owners. Focus on niche applications where dynamic tinting from smart glass is overkill or too expensive.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized coating firms with proprietary nano-ceramic and multi-layer film intellectual property. Long-term viability is strong, driven by global energy efficiency mandates and electric vehicle adoption over the coming decade. Acquisition targets should be mid-sized innovators possessing unique application expertise, such as radio-frequency transparent films for 5G signals. The signal to watch is the expansion of government incentives for existing building decarbonization programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Nano-Ceramic R&D | This enhances heat rejection capabilities for automotive and premium architectural applications. |
| Global Certification Compliance | This ensures market access across diverse regulatory environments like the EU and US. |
| Hybrid Film Portfolio Expansion | This captures demand from cost-sensitive retrofitting projects in developing economies. |
| Strategic OEM Partnerships | This secures long-term supply contracts with major vehicle manufacturers for new models. |
| Integrated Building Solutions | This combines solar films with smart building systems for enhanced energy management. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through a series of primary interviews, complemented by extensive secondary validation. Architectural film installers, automotive OEM procurement leads, building energy consultants, and polymer film manufacturers provided critical insights. Secondary research drew from EU EPBD reports, US EPA ENERGY STAR program data, and national GB standards for green buildings. This approach ensured robust bottom-up and top-down triangulation of market data.
Quantitative models were calibrated against historical market performance and qualitative assessments of emerging trends across the analysis window. Segmentation dimensions modeled included product type, application, end-user, technology, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trends and projected market drivers. Key forecast inputs included global building construction starts and electric vehicle production forecasts.
Stress conditions across geopolitical trade tensions and smart glass adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory stability and technological evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Dysprosium Oxide Sputtering Target Market
Specialty Materials
Nanoencapsulation Market
Specialty Materials
Dura Substitute Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Microwave Absorbing Materials Market
Specialty Materials
Lab Grown Diamonds Market
Specialty Materials
Europe Green Sic Market
Specialty Materials
Vegan Wax Market
Specialty Materials
Specialty and High Performance Films Market
Specialty Materials
Hornbeam Market
Specialty Materials
Africa Collagen Market
Specialty Materials
Mica Sheet Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Absorbent Booms and Socks Market