
 Vulcanized Fiber Market | 2026-2036
Vulcanized Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Vulcanized Fiber Market Intelligence
Original equipment manufacturers in electric vehicle powertrains are collapsing their reliance on legacy thermoset plastics and redirecting specifications toward vulcanized fiber for slot liners and phase separators. Sachsenröder dominates European supply for laminated insulation sheets used in traction motors. DYNOS GmbH leverages captive cotton fiber pulping to sustain cost stability across rod and tube geometries. Franklin Fibre-Lamitex Corporation specializes in custom-pressed components for transformer manufacturers seeking tighter dimensional tolerances.
Vulcanized fiber consists of regenerated cellulose derived from cotton linters or wood pulp, cross-linked through zinc chloride treatment and calendering to produce dense, arc-resistant material with dielectric strength exceeding 10 kV/mm and tensile properties rivaling thermoset composites. Its primary purpose centers on electrical insulation, mechanical gasketing, and structural components where non-tracking, oil-resistant performance matters. Sheet formats lead volume shipments for transformer and switchgear applications, while tube segments capture expanding demand from fuse manufacturers and bushing fabricators. Laminated grades concentrate margin pools where multi-ply bonding creates premium pricing for high-voltage direct current infrastructure.
EPA regulations on chlorinated chemical handling shape North American manufacturing configurations for zinc chloride processing lines. ECHA REACH restrictions on substance of very high concern classifications constrain European import pathways for certain resin-coated formulations. ISO 9001 and IEC 60641 certification requirements filter market access for suppliers serving tier-one electrical equipment assemblers. Stakeholders must monitor evolving flammability standards from Underwriters Laboratories and IEC working groups, as revised test protocols will determine which fiber grades retain qualification in next-generation grid infrastructure.
Market Dynamics
Electric vehicle manufacturers are collapsing their reliance on legacy thermoset plastics and redirecting specifications toward vulcanized fiber for slot liners and phase separators, compressing qualification timelines from years to months.
Growth Catalysts
- ECHA REACH substance restrictions:European chemical regulations are filtering out resin-coated alternatives and elevating pure cellulose-based insulation materials in transformer and switchgear procurement specifications.
- HVDC infrastructure buildouts:Transmission network operators in Germany and China are expanding orders for laminated fiber grades that withstand extreme voltage gradients in converter stations.
- Cotton linter supply concentration:Captive pulping operations in Central Europe are stabilizing input costs for rod and tube manufacturers serving fuse and bushing fabricators.
Market Restraints
- Zinc chloride input volatility:EPA handling regulations on chlorinated chemicals are constraining North American processing line configurations and elevating compliance capital requirements.
- German supply concentration:Precision-engineered fiber component manufacturing clusters heavily in Saxony and Bavaria, creating geographic vulnerability for automotive and industrial automation supply chains.
- Aramid fiber substitution:Meta-aramid papers from DuPont and Teijin are capturing share in high-temperature motor slot applications above 180°C continuous operation.
Strategic Opportunities
- Indian electric mobility:CEA insulation standards for traction motors are creating first-mover advantage for suppliers establishing local lamination and pressing capabilities ahead of domestic EV platform ramp-ups.
- Offshore wind nacelle components:Laminated fiber structural elements are displacing thermoset composites in generator insulation systems where salt-fog resistance and oil compatibility converge.
- Underwriters Laboratories revised flammability protocols:Anticipated test standard updates for grid infrastructure will disqualify incumbent grades and open qualification windows for next-generation arc-resistant formulations.
Industry Challenges
- IEC 60641 certification timelines:Tier-one electrical equipment assemblers require 18-24 month qualification cycles for new fiber grades, compressing product development returns.
- Calendering equipment capex intensity:Multi-ton hydraulic pressing lines for laminated grades require seven-figure capital commitments that strain mid-cap manufacturer balance sheets.
- Cellulose fiber supply integration:Backward integration into cotton linter sourcing demands agricultural commodity expertise absent from traditional chemical processing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vulcanized Fiber Market |
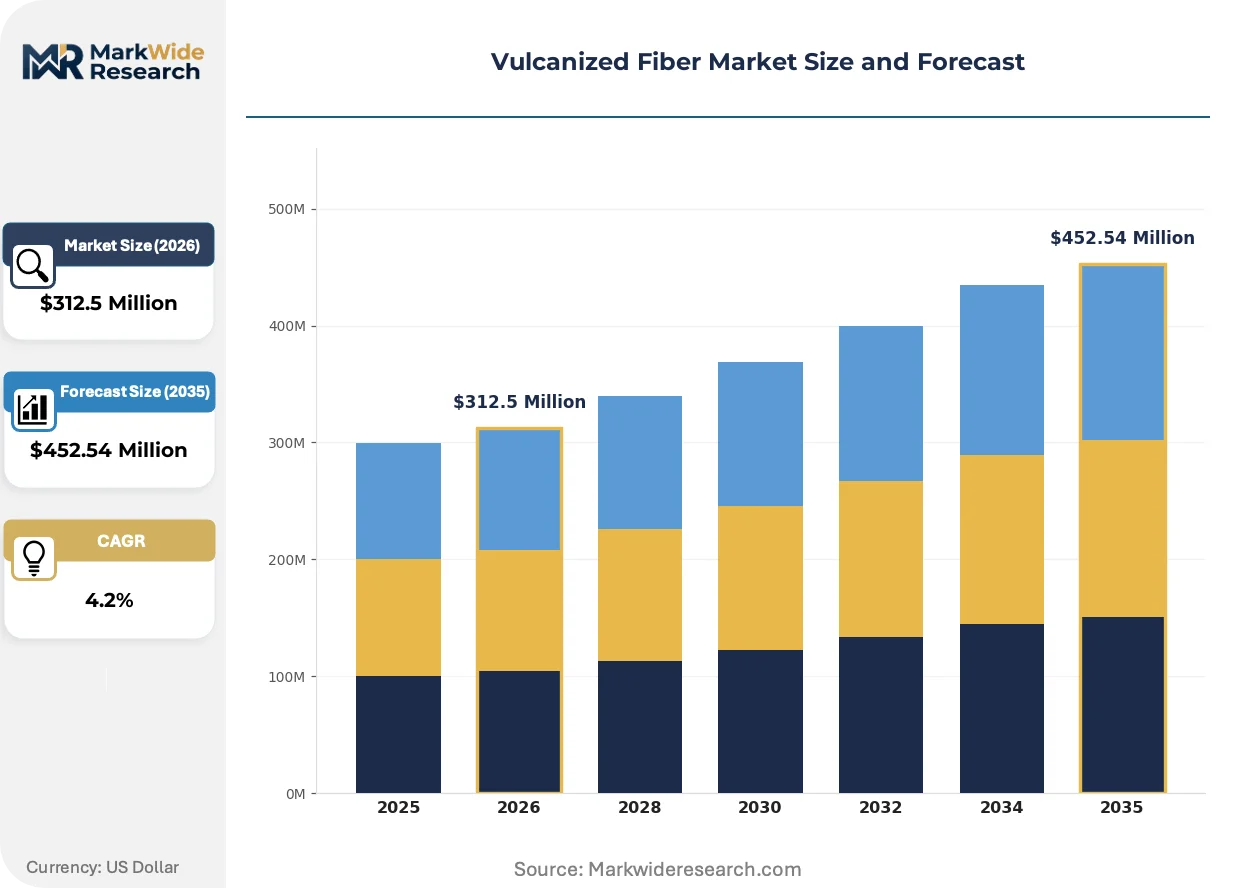
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $452.54 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, Rod, Tube, Laminated, Customized Application: Electrical Insulation, Automotive Components, Industrial Gaskets, Consumer Electronics, Stationery End User Industry: Electronics Manufacturing, Vehicle Assemblers, Industrial Fabricators, Office Supplies, Packaging Form: Dry, Impregnated, Resin-Coated, Colored, Reinforced |
| Companies Covered | DYNOS GmbH, New Process Fibre Company, Inc., ITEN Industries, Sachsenröder, ESPE Manufacturing Co., Inc., Oliner Fibre Co., Inc., Franklin Fibre-Lamitex Corporation, Spaulding Composites, Hokuetsu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vulcanized Fiber Market Strategic Shifts & Innovations
Active reshaping in this market centers on material science convergence with electrification architectures, where fiber manufacturers must simultaneously satisfy tighter electrical tolerances and mechanical performance envelopes.
Ultra-thin vulcanized fiber sheets below 0.25mm thickness are miniaturizing slot liner geometries in high-speed traction motors. Tier-one EV powertrain assemblers in Germany and Japan are qualifying these reduced-thickness grades for 800V architectures. This dimensional compression is miniaturizing motor packages while maintaining dielectric integrity across wider temperature swings.
EPA chlorinated chemical handling rules are forcing zinc chloride processing line reconfigurations across Ohio and Pennsylvania manufacturing sites. Smaller North American producers face six-figure retrofit burdens or outsourcing to Mexican toll processors. Transformer insulation sheet suppliers serving FERC-regulated utilities are absorbing these compliance costs through multi-year supply agreements.
Direct mill relationships are displacing distributor intermediaries for laminated grade procurement. Large transformer OEMs in Germany and China are establishing annual volume contracts with Sachsenröder and domestic Chinese pulping operations. This channel consolidation is most visible in HVDC converter station projects where material traceability requirements exceed distributor certification capabilities.
Vulcanized Fiber Market Segmentation
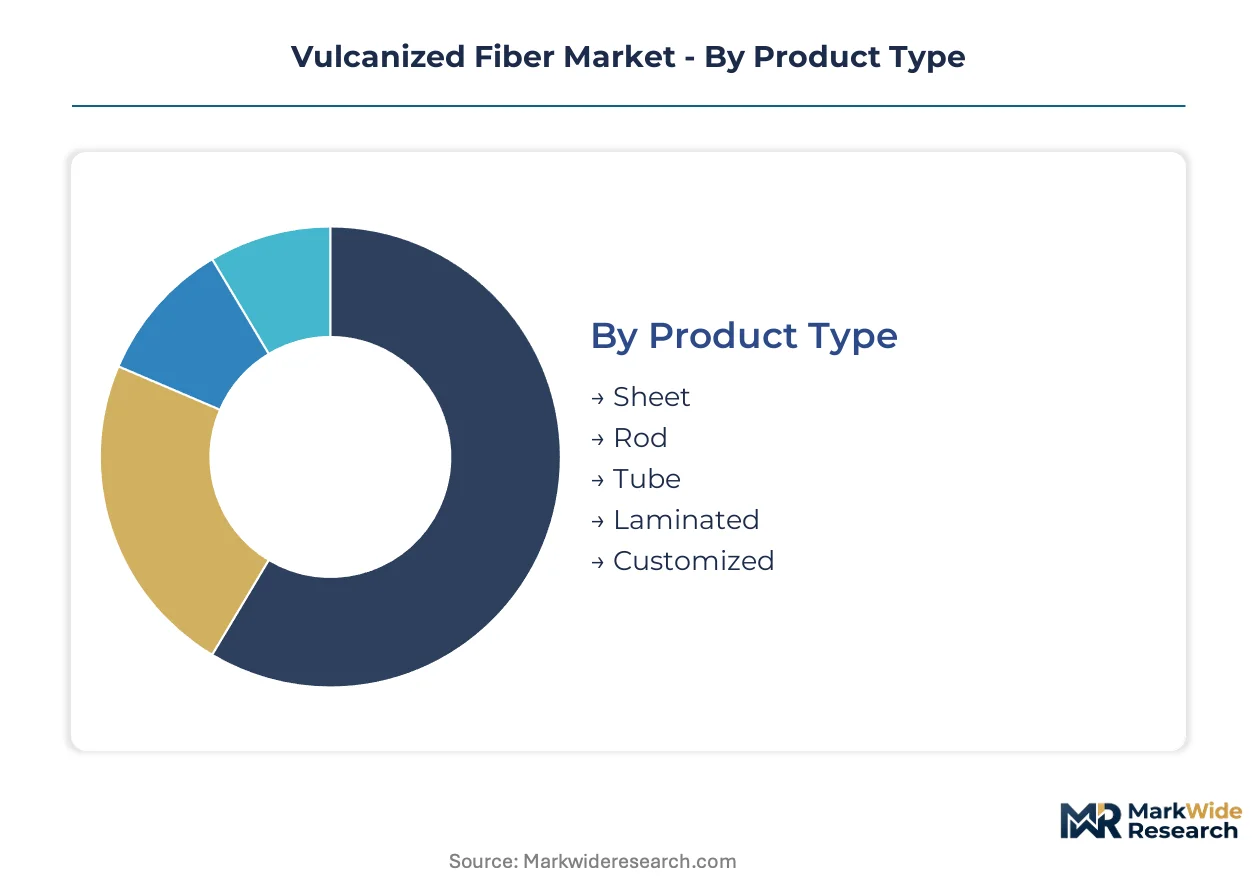
Vulcanized fiber manufacturers must navigate divergent substitution pressures across product geometries and application contexts. Material specifications tighten fastest where electrical performance requirements intersect with mechanical durability demands, compressing margins for undifferentiated grades while amplifying returns for certified formulations.
Product Type:
Sheet formats face mounting pressure from aramid fiber papers in high-temperature motor slots, while tube geometries defend their position in fuse and bushing assemblies where dimensional precision matters more than thermal ceiling.
- Sheet:Flat-rolled vulcanized fiber produced through continuous calendering delivers dielectric strength exceeding 10 kV/mm for transformer winding insulation and switchgear barriers. Demand concentrates in Germany for traction motor slot liners where EV powertrain assemblers specify thinner gauges under 0.25mm for 800V architectures.
- Laminated:Multi-ply bonded constructions created through hydraulic pressing achieve superior dimensional stability for HVDC converter station bushings. German and Chinese transmission operators specify these grades for extreme voltage gradient environments where material traceability requirements exceed standard certification.
- Rod:Extruded solid profiles serve mechanical structural applications requiring high tensile strength and oil resistance in industrial automation equipment.
- Tube:Hollow cylindrical forms precision-machined for fuse bodies and electrical bushings where arc resistance and tight tolerances prevent tracking failures.
- Customized:Engineered-to-order pressed components for transformer manufacturers seeking application-specific geometries and performance envelopes.
Sheet retains volume leadership; Laminated holds the steepest expansion curve.
Application:
Cost stratification across applications separates premium electrical grades from commodity industrial uses, with certification requirements acting as the primary pricing differentiator.
- Electrical Insulation:Arc-resistant barrier materials and slot liners for transformers, motors, and switchgear where non-tracking performance prevents catastrophic failure. IEC 60641 certification requirements filter market access for suppliers serving tier-one electrical equipment assemblers in Germany and Japan.
- Automotive Components:Phase separators and structural elements in EV powertrains where oil compatibility and mechanical durability replace legacy thermoset plastics. OEM qualification timelines have compressed from years to months as powertrain electrification accelerates.
- Industrial Gaskets:Compression-resistant sealing elements for fluid handling equipment where chemical resistance and conformability matter more than electrical properties.
- Consumer Electronics:Thin-gauge insulating washers and spacers for circuit protection devices where miniaturization drives specification toward sub-millimeter thicknesses.
- Stationery:Traditional applications in file folders and tag boards facing steady displacement by synthetic alternatives in cost-sensitive procurement.
Electrical Insulation commands the highest unit values; Automotive Components are expanding most quickly.
End User Industry:
Customer concentration patterns favor direct mill relationships over distributor channels where volume scale and material traceability requirements converge.
- Electronics Manufacturing:Tier-one electrical equipment assemblers require 18-24 month qualification cycles for new fiber grades, creating sticky supplier relationships.
- Vehicle Assemblers:EV powertrain divisions collapsing thermoset plastic specifications toward vulcanized fiber for slot liners and phase separators.
- Industrial Fabricators:Diverse mechanical gasket and structural component buyers with less stringent certification requirements.
- Office Supplies:Stationery converters facing margin compression from synthetic material substitution.
- Packaging:Specialty protective applications where fiber's mechanical properties justify premium positioning.
Electronics Manufacturing anchors procurement volume; Vehicle Assemblers show the strongest share gain.
Form:
Supply-side capabilities concentrate in dry and impregnated grades, while resin-coated formulations face regulatory headwinds from ECHA REACH substance restrictions.
- Dry:Unfinished vulcanized fiber in natural cellulose state serving applications where subsequent processing or coating occurs downstream.
- Impregnated:Oil or synthetic fluid-saturated grades for transformer applications where compatibility with insulating liquids extends service life.
- Resin-Coated:Thermoset-bonded surfaces facing ECHA REACH filtering as pure cellulose alternatives gain procurement preference in European transformer specifications.
- Colored:Pigmented formulations for identification and aesthetic applications in consumer goods and electrical equipment marking.
- Reinforced:Composite constructions with embedded fibers or fabrics for enhanced mechanical properties in structural applications.
Dry forms dominate shipment tonnage; Impregnated grades climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German vulcanized fiber exports supply transformer manufacturers across Central Europe and China, while cotton linter sourcing corridors run from Central Asian suppliers into Saxon processing facilities.
Germany
HVDC converter station projects from transmission operators drive laminated grade procurement, with ECHA REACH substance restrictions filtering resin-coated alternatives from transformer specifications. Sachsenröder anchors precision-engineered fiber component supply from Saxony, serving automotive and industrial automation clusters in Bavaria with slot liners for 800V EV architectures.
United States
FERC-regulated utilities absorb compliance costs through multi-year supply agreements for transformer insulation sheets, as EPA chlorinated chemical handling rules force zinc chloride processing line reconfigurations across Ohio and Pennsylvania. Franklin Fibre-Lamitex Corporation occupies custom-pressed component supply for transformer manufacturers seeking tighter dimensional tolerances in the Midwest industrial corridor.
China
State Grid Corporation expansion of ultra-high voltage direct current infrastructure elevates laminated fiber orders for converter station bushings, with GB standards on electrical insulation materials tightening procurement specifications. Yangtze River Delta manufacturing clusters concentrate domestic pulping and calendering capacity for rod and tube geometries serving fuse fabricators.
India
CEA insulation standards for traction motors create qualification windows for suppliers establishing local lamination capabilities ahead of domestic EV platform ramp-ups by Tata Motors and Mahindra. Maharashtra and Gujarat industrial zones attract pressing line investments from European fiber specialists seeking to bypass import duty structures on finished electrical insulation components.
Japan
METI carbon neutrality roadmaps accelerate thermoset plastic displacement in automotive powertrains, with tier-one EV powertrain assemblers qualifying ultra-thin vulcanized fiber sheets below 0.25mm for high-speed traction motors. Kanto manufacturing clusters around Tokyo maintain precision calendering expertise for sub-millimeter gauge insulation serving consumer electronics and circuit protection device makers.
Vulcanized Fiber Market Key Industry Players
Player mix skews toward mid-cap specialists with captive cotton fiber pulping operations and hydraulic pressing capabilities for laminated grades. Market structure concentrates margin pools in certified electrical insulation supply, with tier-one electrical equipment assemblers requiring 18-24 month qualification cycles that create sticky supplier relationships. Three archetypes dominate: pulping-integrated European manufacturers, North American custom pressing specialists, and Asian scale producers. Competitive moves center on backward integration into cotton linter sourcing and direct mill relationships displacing distributor channels for HVDC infrastructure procurement.
Among German-based fabricators, DYNOS GmbH and Sachsenröder exemplify the pulping-integrated archetype with captive fiber supply chains stabilizing input costs. Franklin Fibre-Lamitex Corporation occupies a position within the North American custom pressing tier, representing specialists in application-specific geometries for transformer OEMs. These three anchors illustrate how geographic concentration in Saxony and the Midwest industrial corridor shapes competitive positioning around regulatory compliance capabilities and qualification track records with tier-one electrical equipment assemblers.
| Leading Market Players |
|---|
| DYNOS GmbH |
| New Process Fibre Company, Inc. |
| ITEN Industries |
| Sachsenröder |
| ESPE Manufacturing Co., Inc. |
| Oliner Fibre Co., Inc. |
| Franklin Fibre-Lamitex Corporation |
| Spaulding Composites |
| Hokuetsu Corporation |
| Others |
Cost & Logistics Intelligence
IEC 60641 certification requirements gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified grades while amplifying returns for validated formulations serving tier-one electrical equipment assemblers. ECHA REACH substance restrictions further stratify the market by filtering resin-coated alternatives and elevating pure cellulose-based insulation materials in European procurement specifications.
Pricing Analysis
800V architecture-grade sheets command substantial premiums over legacy 400V formulations, while sub-0.25mm ultra-thin gauges for high-speed traction motors price at multiples of standard thicknesses. Three-tier pricing structure across IEC-certified premium, ISO-compliant standard, and uncertified economy levels separates qualified electrical insulation from industrial gasket grades. Pricing pressure stems from zinc chloride input volatility and EPA compliance retrofit burdens on North American processors. Automotive OEMs show least price sensitivity for qualified slot liner grades, while stationery converters face severe margin compression from synthetic substitution.
Supply Chain Analysis
Extended lead times for laminated HVDC grades stretch to six months as hydraulic pressing capacity concentrates in Saxony and the Yangtze River Delta. Raw material flows draw from Uzbek cotton linter corridors into Central European pulping operations, with zinc chloride supply anchored in domestic Chinese and North American chemical processing clusters. Single-source vulnerability concentrates in German precision-engineered component manufacturing, where Sachsenröder and DYNOS GmbH control qualified supply for automotive traction motor programs. Distribution runs through direct mill relationships displacing distributor channels for large transformer OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as 800V EV architectures standardize slot liner specifications, creating interoperability lock-in for qualified fiber grades across powertrain ecosystems.
For Market Incumbents: Compound certification moats by accelerating IEC 60641 validation for next-generation arc-resistant formulations ahead of Underwriters Laboratories revised flammability protocols. Deepen captive cotton fiber pulping to offset zinc chloride cost volatility threatening margin stability. Prioritize direct mill relationships with State Grid Corporation and TenneT to secure HVDC converter station procurement pipelines against emerging Asian scale producers. For New Entrants and Emerging Players: IEC 60641 fast-track partnerships with German TÜV or DEKRA certification bodies compress 18-24 month qualification timelines for Indian CEA traction motor standards. Target Maharashtra and Gujarat industrial zones for pressing line investments ahead of Tata Motors and Mahindra domestic EV platform ramp-ups. Lead with laminated grade capabilities for offshore wind nacelle components where salt-fog resistance specifications remain underpenetrated by established suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-ton hydraulic pressing lines for laminated grades, straining mid-cap manufacturer balance sheets and creating consolidation catalysts. Acquisition targets should prioritize pulping-integrated European specialists with captive cotton linter supply and existing tier-one electrical equipment assembler relationships. Monitor Underwriters Laboratories test standard publication timelines as inflection signals for next-generation grade qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cotton Linter Sourcing | Captive fiber supply stabilizes input costs against agricultural commodity volatility for rod and tube manufacturers. |
| IEC 60641 Certification Investment | Validated formulations access sticky procurement relationships with tier-one EV powertrain assemblers in Germany and Japan. |
| Direct Mill Relationship Establishment | Material traceability requirements for HVDC infrastructure exceed distributor certification capabilities. |
| Ultra-Thin Gauge Production Scale-Up | Sub-0.25mm sheets miniaturize motor packages while maintaining dielectric integrity across wider temperature swings. |
| Indian Lamination Capability Localization | CEA insulation standards create first-mover advantage ahead of domestic EV platform ramp-ups by established automotive OEMs. |
Research Approach
Desk research of customs and trade data, SEC filings from electrical equipment manufacturers, and IEC standard documentation preceded structured interviews with transformer procurement directors, EV powertrain engineers, and cotton fiber trading specialists. Primary fieldwork with calendering equipment operators and zinc chloride processing plant managers combined with secondary validation from ECHA regulatory databases and EPA enforcement records. Bottom-up volume modeling across product geometries triangulated against top-down value estimates from electrical insulation procurement spend analysis.
Variance decomposition isolates segment-specific growth contributions from sheet, laminated, rod, tube, and customized formats across the projection horizon. Modeled dimensions span product type, application context, end-user industry, and regional production hub. CAGRs derive from elasticity-calibrated demand functions incorporating EV powertrain penetration rates and HVDC infrastructure buildout pipelines. Zinc chloride price trajectories and cotton linter harvest forecasts feed industry-specific input cost scenarios.
The analysis sits within stated boundaries; outcomes outside sustained electrification capital expenditure and stable cellulose fiber supply would require recalibration. Forecasts reflect assumptions around ECHA REACH enforcement continuity and EPA chlorinated chemical handling rule stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Light Diffusion Materials Market
Specialty Materials
Halloysite Market
Specialty Materials
Melamine Foam Market
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Alginate Films Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Carrageenan Film Market
Specialty Materials
Specialty Polyamides Market
Specialty Materials
Global Montan Wax Market
Specialty Materials
Solar Backsheet Films Market
Specialty Materials
Silicone Solutions for Leather and Textile Market
Specialty Materials
Latin America International CEP Market
Specialty Materials
Dura Substitute Market
Specialty Materials
Electroactive Polymers (EAP) Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Semiconductor O-Rings Market