
 Nitrocellulose Market | 2026-2036
Nitrocellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Nitrocellulose Market Analysis
Waterborne polyurethane dispersions is shifting formulation economics in decorative and protective coatings, pressuring traditional nitrocellulose binders on volatile organic compound grounds. Synthesia a.s. leverages its integrated cellulose supply chain to sustain cost competitiveness across European ink markets. Hagedorn AG anchors its position through specialty-grade production for pharmaceutical tablet coatings. Nitrex Chemicals India Pvt. Ltd. dominates South Asian supply for adhesives and leather finishes.
Nitrocellulose is a nitrated cellulose ester produced by treating purified cellulose with mixed nitric and sulfuric acids, typically yielding nitrogen contents between 10.5% and 12.5% that determine solubility, flammability, and end-use suitability. The material functions primarily as a film-forming binder in coatings and inks, a propellant base in ammunition, and a controlled-release agent in pharmaceutical tablets. Soluble nitrocellulose leads the product type landscape due to its dominance in wood lacquers and flexographic inks, while stable nitrocellulose represents the fastest-growing category as military and civilian propellant specifications tighten. Coatings and inks together capture the deepest margin pools, though adhesives applications are gaining traction in automotive interior assembly.
EPA hazardous air pollutant standards and OSHA process safety management rules govern U.S. manufacturing and handling protocols, while REACH and the EU F-Gas Regulation constrain solvent-based formulations that depend on nitrocellulose carriers. China's MIIT enforces GB standards for chemical safety in production facilities, creating divergent compliance burdens across major supply regions. Stakeholders must monitor solvent substitution trajectories and regulatory tightening in their primary export markets to preserve product qualification and access.
Market Dynamics
Waterborne polyurethane dispersions are compressing nitrocellulose's position in decorative coatings, forcing reformulation investments across European and North American suppliers. REACH solvent restrictions and EPA hazardous air pollutant standards are tightening simultaneously, raising qualification barriers for legacy producers.
Growth Catalysts
- Military propellant modernization:Stable nitrocellulose specifications are tightening in NATO-standard ammunition programs, pulling volume from civilian-grade production lines.
- REACH authorization timelines:European solvent-based ink producers face restricted substance sunset dates, creating qualification windows for compliant nitrocellulose suppliers.
- Flexographic packaging expansion:Food-contact ink formulations in Southeast Asia are absorbing soluble nitrocellulose volumes as barrier coating demand rises.
Market Restraints
- Cellulose feedstock concentration:Purified cotton linters supply concentrates in South Asian and Chinese processors, exposing cost volatility to climate and trade policy shocks.
- Waterborne substitution economics:Polyurethane and acrylic dispersions achieve comparable film properties at lower volatile organic compound burden in wood furniture coatings.
- Nitration capacity scarcity:Mixed acid handling infrastructure requires specialized permitting under OSHA process safety management and EU Seveso III thresholds.
Strategic Opportunities
- Pharmaceutical controlled-release:Tablet coating applications in oral dosage forms present margin expansion potential beyond commodity coatings.
- India leather finishing:Domestic footwear and automotive upholstery production is absorbing specialty-grade nitrocellulose for high-gloss finishes.
- GB standard alignment:China's MIIT enforcement of chemical facility safety codes is consolidating sub-scale producers, opening share capture for compliant multinationals.
Industry Challenges
- Nitration chemistry expertise:Mixed acid process engineering talent pools are aging in Western Europe and North America, constraining capacity expansion timelines.
- Dual-use export controls:Military-grade nitrocellulose falls under multilateral munitions licensing regimes, complicating cross-border shipment documentation and compliance staffing.
- Legacy equipment retrofit costs:Solvent recovery and abatement systems require capital deployment that stretches payback periods beyond private equity holding horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitrocellulose Market |
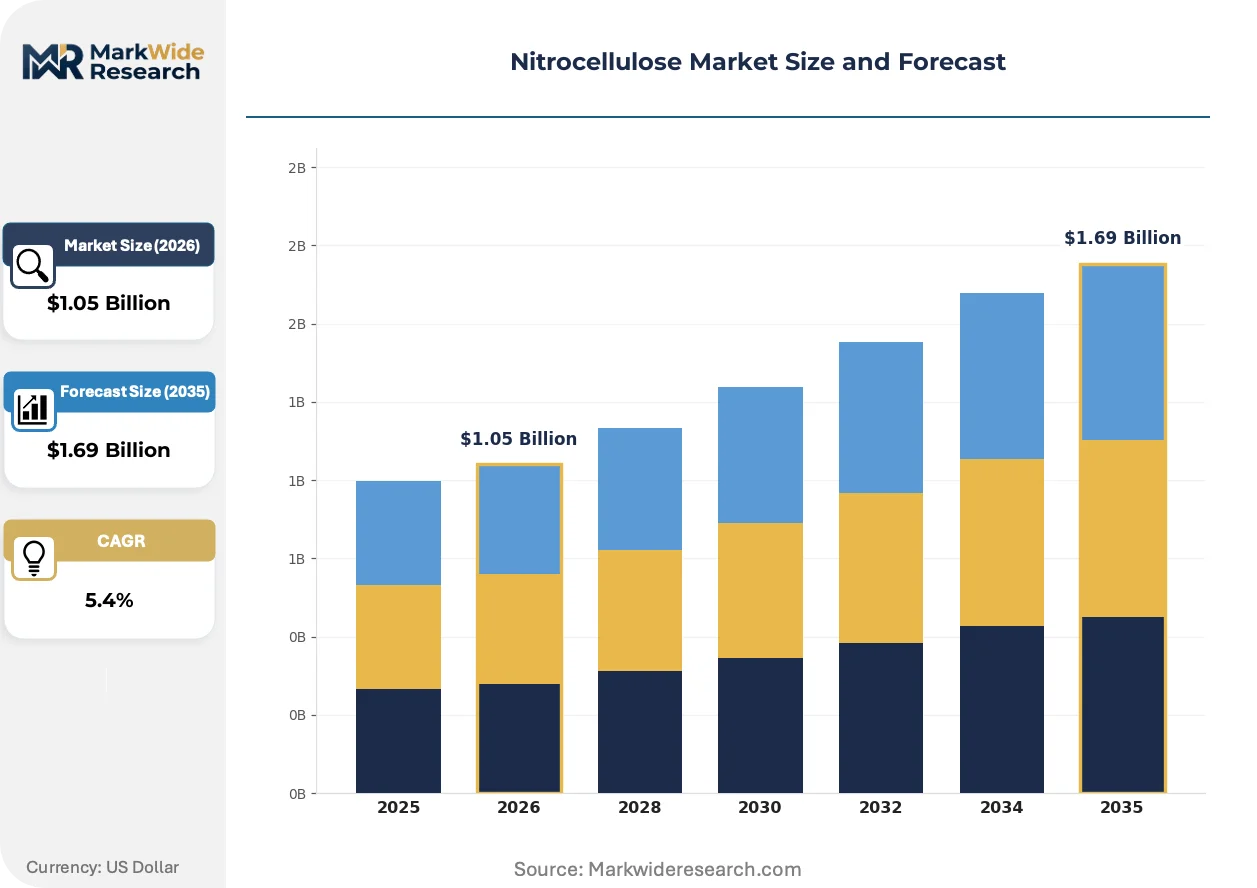
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.69 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soluble Nitrocellulose, Unstable Nitrocellulose, Stable Nitrocellulose, Microcrystalline Nitrocellulose Application: Coatings, Inks, Adhesives, Nitrocellulose Lacquers End User: Aerospace, Automotive, Pharmaceuticals, Consumer Goods Grade: Industrial Grade, Laboratory Grade, Technical Grade, Specialty Grade |
| Companies Covered | TNC Industrial Co., Ltd., Nitrex Chemicals India Pvt. Ltd., Nitro Química, Hagedorn AG, Hubei Xufei Chemical Co., Ltd., Hengshui Orient Chemical Co., Ltd., Synthesia a.s., Atomax Chemicals Co., Ltd., Nobel NC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitrocellulose Market Emerging Trajectories
Reformulation chemistry and regulatory compliance architecture are diverging sharply between solvent-dependent and waterborne coating platforms, fragmenting supplier technical roadmaps.
Low-nitrogen soluble nitrocellulose grades are modularizing into hybrid binder systems for UV-curable wood coatings. European furniture manufacturers are adopting these modules to bridge drying speed and emission compliance. The technology is modularizing application equipment requirements, allowing finishers to retrofit existing spray lines rather than replacing capital.
EPA hazardous air pollutant standards for surface coating operations are tightening residual solvent limits in wood furniture and automotive refinish segments. U.S. finishers face compliance deadlines that compress reformulation windows to 18-24 months. Nitrocellulose-dependent suppliers are responding with exempt solvent blends and higher-solids concentrates to preserve qualification.
Specification-driven procurement is consolidating buyer power among multinational coatings formulators. Tier-one automotive refinish and packaging ink producers are unbundling technical service from material supply, pressuring mid-tier nitrocellulose distributors. This pattern is most visible in Germany and the U.S. Great Lakes industrial corridor, where formulator concentration has advanced furthest.
Nitrocellulose Market Segmentation
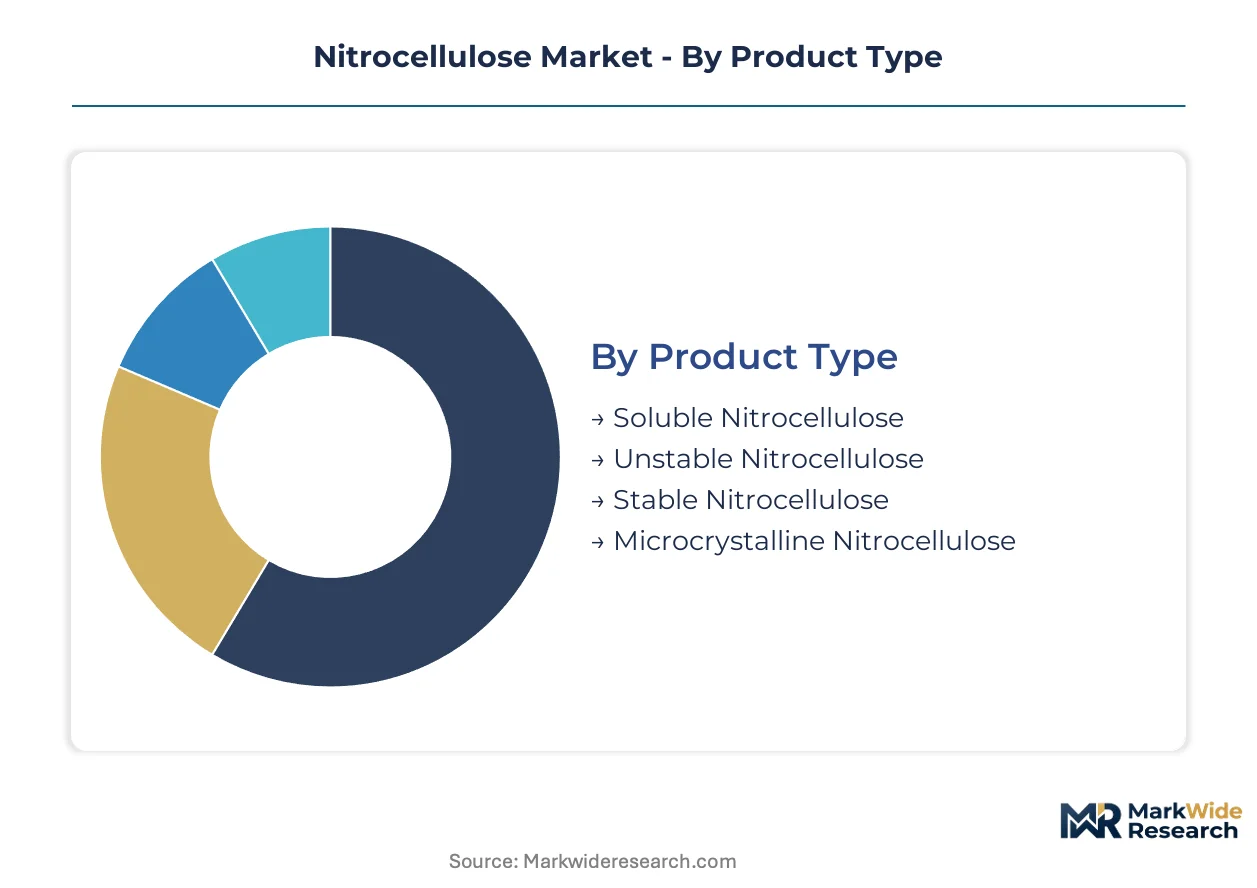
Nitrocellulose specifications vary sharply across nitrogen content, solubility profiles, and stability ratings, creating distinct supply chains and qualification requirements for each segment. Understanding these technical boundaries enables suppliers to align capacity investments with end-use demand trajectories and regulatory constraints.
Product Type:
Nitrogen content and esterification degree determine functional performance across film-forming, propellant, and controlled-release applications.
- Soluble Nitrocellulose:Contains 10.5-11.2% nitrogen content enabling dissolution in ester-alcohol solvent blends. Wood lacquer and flexographic ink formulators in Germany and the U.S. Midwest concentrate procurement here, though waterborne polyurethane substitution is compressing volume in decorative coatings.
- Stable Nitrocellulose:Higher nitrogen grades (12.0-12.5%) with stabilized acid residuals for propellant base applications. Military ammunition programs across NATO standardization agreements are tightening specifications and pulling capacity from civilian production lines.
- Unstable Nitrocellulose:Intermediate nitrogen content requiring immediate processing into finished propellant or explosive compositions; limited commercial storage life drives captive production at munitions facilities.
- Microcrystalline Nitrocellulose:Reduced chain-length variants for pharmaceutical tablet coatings and microencapsulation; oral dosage form manufacturers in Switzerland and Japan specify these grades for controlled-release matrices.
Mature deployment sits with soluble nitrocellulose in coatings and inks. Newer deployment is concentrated in stable nitrocellulose as military procurement tightens specifications.
Application:
End-use performance requirements span film durability, drying speed, adhesion strength, and regulatory compliance thresholds.
- Coatings:Automotive refinish and wood furniture segments absorb the deepest volume pools. EPA hazardous air pollutant standards and REACH solvent restrictions are forcing reformulation toward higher-solids concentrates and exempt solvent blends.
- Inks:Flexographic and gravure packaging applications dominate food-contact formulations. Southeast Asian barrier coating expansion is absorbing soluble nitrocellulose volumes as export-oriented packaging capacity scales.
- Adhesives:Solvent-based bonding systems for leather finishing and automotive interior assembly; domestic footwear production in India is driving specialty-grade absorption.
- Nitrocellulose Lacquers:Traditional high-gloss finishes for musical instruments and specialty wood products; niche volume concentrated in European artisanal manufacturing clusters.
Volume leadership belongs to coatings. Steepest expansion trajectory is emerging in adhesives as automotive interior assembly specifications tighten.
End User:
Procurement sophistication and qualification timelines diverge sharply between regulated industries and commodity manufacturing.
- Automotive:Refinish coatings and interior adhesive applications anchor commercial demand. Tier-one formulators in Germany and Michigan are unbundling technical service from material supply, consolidating buyer power.
- Pharmaceuticals:Tablet coating and controlled-release matrices command premium pricing. FDA and EMA validation requirements extend qualification timelines to 18-24 months.
- Aerospace:Propellant applications and specialty coatings for airframe finishing; dual-use export controls under multilateral munitions licensing complicate cross-border shipment documentation.
- Consumer Goods:Nail polish, printing inks, and decorative coatings; price sensitivity drives procurement toward Asian supply sources.
Regulatory intensity peaks in pharmaceuticals. Fastest commercial volume growth is materializing in automotive as refinish coating specifications tighten.
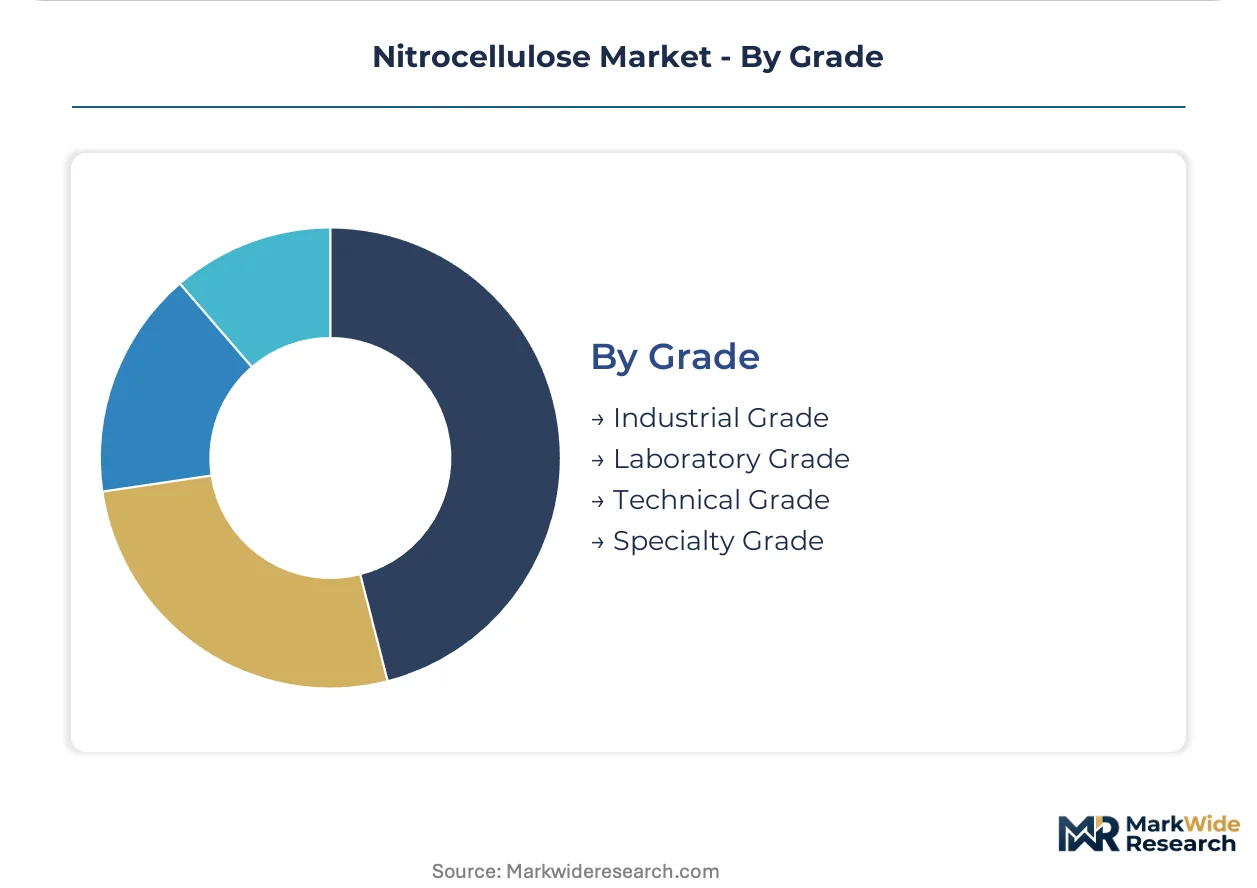
Grade:
Purity thresholds and certification requirements stratify pricing and supplier qualification barriers.
- Industrial Grade:Standardized nitrogen content for coatings and adhesives; volume production concentrates at integrated cellulose processors in China and India.
- Specialty Grade:Tight specification tolerances for pharmaceutical and military applications; Hagedorn AG anchors European supply for tablet coating markets.
- Laboratory Grade:Analytical and research-scale quantities; fragmented supply across regional chemical distributors.
- Technical Grade:Intermediate purity for prototyping and non-validated production processes; price-sensitive procurement from South Asian exporters.
Margin concentration aligns with specialty grade validation requirements. Volume scale is accumulating in industrial grade as Chinese domestic solvent-based ink production expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the deepest volume pools in nitrocellulose consumption, with domestic solvent-based ink production and military propellant programs anchoring demand. Military modernization across NATO-standard ammunition programs is pulling stable-grade capacity toward defense applications in multiple jurisdictions.
China
Domestic solvent-based ink manufacturers and military propellant programs drive volume consumption. MIIT enforces GB standards for chemical safety in production facilities, consolidating sub-scale producers. The Yangtze River Delta hosts integrated cellulose processors serving both coatings and ammunition sectors.
United States
Automotive refinish coatings and wood furniture segments absorb commercial-grade soluble nitrocellulose. EPA hazardous air pollutant standards and OSHA process safety management rules govern manufacturing protocols. The U.S. Great Lakes industrial corridor concentrates formulator activity where tier-one producers are unbundling technical service from material supply.
Germany
Flexographic ink formulators and wood lacquer manufacturers concentrate procurement in soluble grades. REACH authorization timelines and solvent restrictions are forcing reformulation investments. Industrial clusters in North Rhine-Westphalia anchor European coatings supply chains.
India
Domestic footwear production and automotive upholstery manufacturing drive specialty-grade absorption for leather finishes. BIS standards and chemical facility safety codes shape supplier qualification requirements. Gujarat and Maharashtra host integrated processors serving South Asian adhesive and coatings markets.
Switzerland
Oral dosage form manufacturers specify microcrystalline grades for controlled-release matrices. Swissmedic validation requirements extend pharmaceutical qualification timelines. Basel-Zurich corridor concentration supports high-margin specialty pharmaceutical applications.
Nitrocellulose Market Vendor Landscape
Capacity expansion dominates the current landscape as producers retrofit solvent recovery systems to meet tightening emission standards. The vendor base stratifies across three tiers: integrated cellulose processors with captive feedstock supply, specialty-grade producers serving pharmaceutical and military qualification requirements, and regional distributors handling commodity coatings volumes. Strategic archetypes include backward-integrated raw material controllers, specification-driven pharmaceutical specialists, and scale-focused industrial-grade manufacturers. Competitive intensity centers on regulatory compliance investments and geographic qualification in priority export markets.
Among European integrated producers, Synthesia a.s. occupies a position exemplifying cellulose supply chain control, while Hagedorn AG sits within the specialty-grade tier serving pharmaceutical validation markets. Nitrex Chemicals India Pvt. Ltd. represents the South Asian scale-focused archetype, anchoring regional supply for adhesives and leather finish applications. These three patterns—integrated feedstock control, pharmaceutical specification expertise, and regional volume scale—define the competitive structure.
| Leading Market Players |
|---|
| TNC Industrial Co., Ltd. |
| Nitrex Chemicals India Pvt. Ltd. |
| Nitro Química |
| Hagedorn AG |
| Hubei Xufei Chemical Co., Ltd. |
| Hengshui Orient Chemical Co., Ltd. |
| Synthesia a.s. |
| Atomax Chemicals Co., Ltd. |
| Nobel NC |
| Others |
Supply Flow & Price Mechanics
REACH authorization timelines for solvent-based ink producers are compressing procurement windows, forcing European formulators to pre-qualify compliant suppliers and accept premium-grade pricing to maintain formulation access. This demand-side pressure concentrates purchasing power among integrated cellulose processors with verified nitration capacity, widening spreads between qualified and unqualified supply tiers.
Pricing Analysis
Volume leadership sits with industrial-grade soluble nitrocellulose for coatings and inks, while margin concentration aligns with specialty-grade validation for pharmaceutical and military applications. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-validated microcrystalline grades from Chinese industrial production and South Asian technical-grade exports. Cost compression in standard-grade coatings is intensifying because waterborne polyurethane dispersions achieve comparable film properties at lower volatile organic compound burden. Consumer goods manufacturers in Southeast Asia exhibit the highest price sensitivity, while pharmaceutical tablet coaters in Switzerland and Japan accept extended qualification timelines for validated supply security.
Supply Chain Analysis
Single-source vulnerability sits with purified cotton linters supply concentrated in South Asian and Chinese processors, exposing nitration facilities to climate and trade policy shocks. Production gravity centers on China, India, and Germany, with the Yangtze River Delta and North Rhine-Westphalia hosting integrated cellulose-to-nitrocellulose operations. Feedstock supply draws from cotton byproduct streams and wood pulp derivatives, while nitration chemistry requires mixed acid handling infrastructure under specialized permitting. Tariff exposure on cellulose feedstock imports complicates cost planning for European and North American finishers. Distribution runs through regional chemical distributors for commodity volumes and direct technical service relationships for specialty-grade qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory tightening across REACH solvent restrictions and EPA hazardous air pollutant standards is forcing sub-scale producers into exit or acquisition, consolidating viable capacity among compliant integrated processors. This pressure architecture favors incumbents with capitalized abatement systems and validated military-grade specifications.
For Market Incumbents: Anchor market position through captive cellulose supply chain control and nitration capacity expansion in China or India to serve regional solvent-based ink demand. Waterborne substitution in European decorative coatings threatens volume; defend through specialty-grade pharmaceutical validation investments and military propellant specification capture under NATO standardization agreements. For New Entrants and Emerging Players: The price-point gap between Swiss-validated pharmaceutical grades and Chinese industrial production creates white-space opportunity for mid-tier specialty-grade producers serving Indian leather finishing and Southeast Asian flexographic packaging markets. Target domestic footwear and automotive upholstery manufacturers in Gujarat and Maharashtra with technical service bundled to formulation support, bypassing established distributor relationships. For Investors and Strategic Acquirers: The window for entry favors integrated cellulose processors with verified GB standard compliance and military qualification pathways. Long-term viability hinges on dual-use export control licensing infrastructure and nitration chemistry expertise pools that are aging in Western Europe. Watch for MIIT enforcement actions consolidating Chinese sub-scale producers as the inflection signal for share capture timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cellulose Feedstock | Cotton linter supply control insulates Synthesia a.s. from South Asian climate volatility and trade disruptions. |
| Solvent Recovery System Retrofit | EPA hazardous air pollutant compliance preserves U.S. Great Lakes corridor qualification for automotive refinish coatings. |
| Pharmaceutical Grade Validation Investment | FDA and EMA qualification timelines extend Hagedorn AG's tablet coating margin protection against commodity entrants. |
| Military Propellant Specification Capture | NATO standardization agreement alignment pulls stable nitrocellulose capacity from civilian production lines. |
| Regional Distribution Partnership | Nitrex Chemicals India Pvt. Ltd. leverages Maharashtra hub position to serve domestic footwear and automotive upholstery demand. |
Methodological Framework
Trade databases, chemical industry association publications, and regulatory filing repositories formed the secondary backbone, cross-referenced against primary interviews with nitration plant managers, coatings formulator procurement leads, pharmaceutical tablet coating specialists, and military propellant program officers. Bottom-up volume modeling triangulated against top-down demand segmentation across nitrogen content grades, end-use applications, and regional production hubs to establish supply-demand balances.
Bottom-up modeling built from individual facility capacity declarations and utilization assumptions, while top-down validation applied end-use consumption coefficients across automotive refinish, flexographic packaging, and pharmaceutical dosage form markets. Segmentation dimensions included nitrogen content tier, solubility profile, stability rating, and geographic regulatory cluster. CAGRs derived from gradient analysis of substitution elasticity and specification tightening trajectories, with inputs from waterborne dispersion penetration rates and military modernization procurement schedules.
Inputs from customs records and chemical facility permitting databases were available through the study window; gaps in sub-scale Chinese producer utilization rates introduce uncertainty bands around volume concentration estimates. Forecasts reflect documented assumptions on REACH authorization sunset dates and EPA residual solvent limit enforcement timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Halloysite Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
Rigid Polyurethane Foams Market
Specialty Materials
PCB Prepreg Material Market
Specialty Materials
Barium Borate Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Conductive Fluted Sheets Market
Specialty Materials
Organic Scintillators Market
Specialty Materials
Niobium Pentoxide Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Global Fluorosilicone Market
Specialty Materials
Semiconductor O-Rings Market
Specialty Materials
MLCC Silicone Release Film Market
Specialty Materials
Africa Collagen Market