
 EVA Interlayer for Photovoltaic Market | 2026-2036
EVA Interlayer for Photovoltaic Market Size, Share, and Industry Trends Forecast 2026-2036
EVA Interlayer for Photovoltaic Market Insights
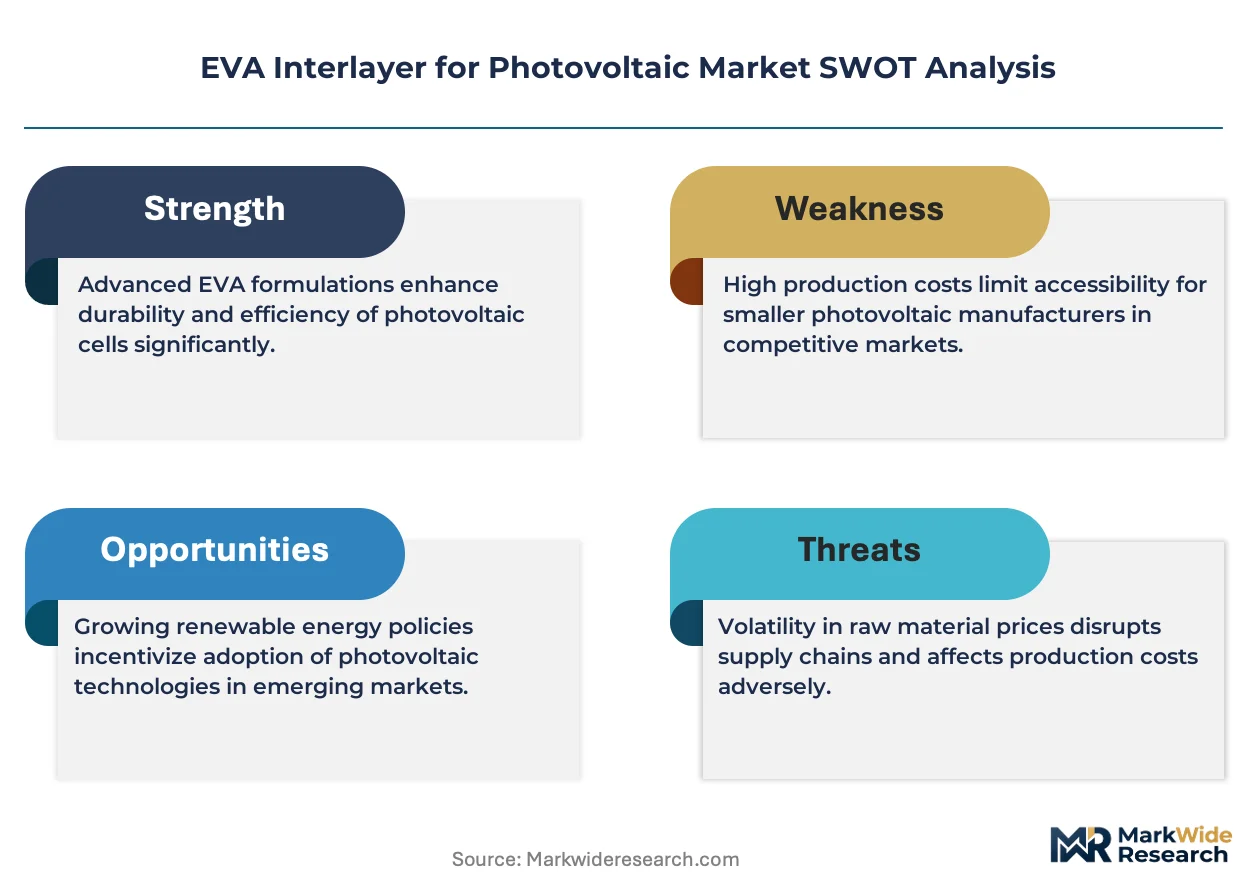
The price-performance gap between premium and commodity EVA interlayers is hardening as module manufacturers demand higher PID resistance and UV stability for bifacial and TOPCon cells. Hangzhou First Applied Material leverages integrated resin compounding to sustain cost advantages across standard and high-transparency grades. Shanghai HIUV New Materials anchors its position through specialized low-temperature curing formulations that reduce lamination energy in high-throughput lines. Jiangsu Sveck Photovoltaic New Material differentiates via reflective EVA products that boost bifacial module rear-side gain.
Ethylene-vinyl acetate interlayer for photovoltaic applications consists of a copolymer resin with vinyl acetate content typically ranging from 28% to 33%, crosslinked with peroxide initiators during vacuum lamination to achieve optical clarity above 91% and moisture barrier performance critical for cell encapsulation. The material functions primarily as an adhesive-encapsulant that electrically insulates solar cells while transmitting photons and dissipating thermal stress across decades of outdoor exposure. High transparency EVA commands expanding share as n-type and heterojunction cell architectures require superior UV-cut and anti-PID chemistry, while reflective EVA grows fastest in bifacial module configurations where rear-side albedo capture determines system economics. Standard EVA retains volume dominance in cost-sensitive markets though margin pools have shifted toward specialty grades.
The EPA regulates VOC emissions from EVA resin production and lamination processes in the United States, while REACH restricts certain crosslinking additives and plasticizers across European supply chains, and China's MEE enforces carbon intensity benchmarks on petrochemical feedstock operations that shape interlayer manufacturing economics. These frameworks collectively push suppliers toward cleaner peroxide systems, recycled content pathways, and localized compounding to maintain market access. Stakeholders must monitor how evolving encapsulant standards for fire safety and end-of-life recyclability will reshape product qualification requirements and regional sourcing decisions.
Market Dynamics
The transition from p-type to n-type cell architectures is compressing margins on standard EVA grades while redistributing value toward anti-PID and UV-cut formulations that module manufacturers now mandate for warranty compliance.
Growth Catalysts
- EU Green Deal carbon benchmarks:The EU Green Deal's embodied carbon rules for imported solar modules are forcing European assemblers to specify low-carbon EVA interlayers, pulling supply toward producers with renewable-powered compounding facilities.
- Bifacial module proliferation:Utility-scale solar farms in China and India are specifying reflective EVA for rear-side albedo gain, creating a dedicated demand stream that commands 15-20% price premiums over standard encapsulant grades.
- Perovskite tandem readiness:Emerging perovskite-silicon tandem cell architectures require EVA formulations with modified curing kinetics and ionic purity thresholds, opening qualification contracts for specialty resin compounders.
Market Restraints
- Ethylene feedstock volatility:EVA resin production remains tethered to naphtha and ethylene pricing cycles, with Asian petrochemical complexes passing through cost swings that compress interlayer margins during crude oil spikes.
- Chinese supply concentration:Over 70% of global EVA interlayer manufacturing capacity sits in Jiangsu, Zhejiang, and Shandong provinces, creating single-source risk for module assemblers outside China seeking supply diversification.
- POE substitution threat:Polyolefin elastomer encapsulants from Dow and Mitsui are capturing share in high-humidity applications where EVA's moisture permeability accelerates potential-induced degradation failures.
Strategic Opportunities
- India's PLI-driven module assembly:India's production-linked incentive scheme for solar manufacturing is attracting EVA interlayer localization investments as domestic cell and module capacity scales toward 100 GW annual targets.
- Recycled content pathways:Mechanical recycling of post-industrial EVA trim and edge scrap into lower-grade construction applications is creating circular revenue streams for compounders facing landfill restrictions under China's MEE enforcement.
- Low-temperature curing convergence:The intersection of heterojunction cell thermal sensitivity and energy cost reduction goals is creating demand for peroxide systems that cure below 140°C without sacrificing crosslink density.
Industry Challenges
- Crosslinking chemistry expertise gap:Formulation chemists capable of balancing peroxide initiator stability, gel content targets, and lamination throughput are concentrated among senior staff at incumbent suppliers, constraining new entrant scale-up.
- Multinational certification timelines:Qualifying EVA interlayers for IEC 61215 and UL 1703 across multiple module designs requires 12-18 month testing cycles that delay revenue recognition for modified formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EVA Interlayer for Photovoltaic Market |
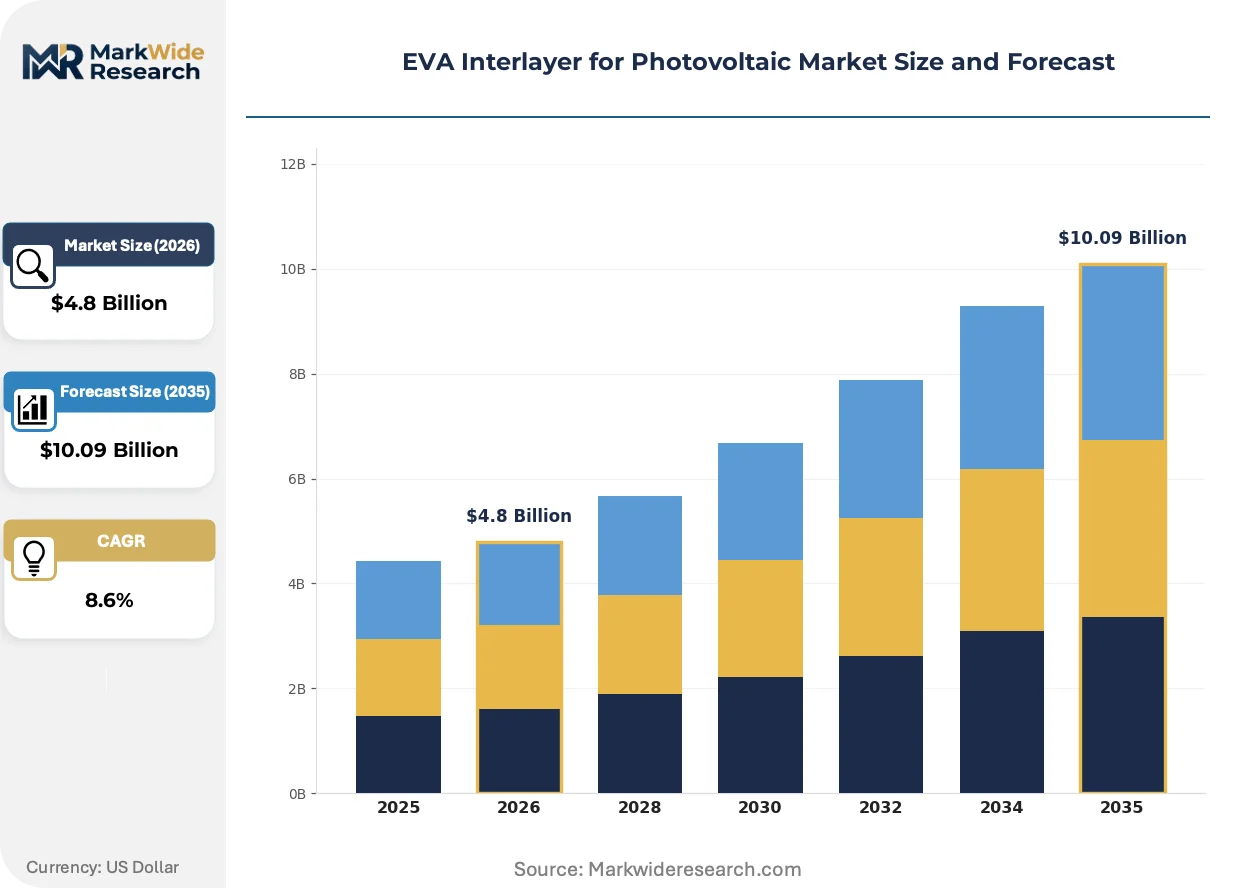
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard EVA, High Transparency EVA, Low Temperature EVA, Reflective EVA End User: Residential, Commercial, Utility Scale, Government Application: Solar Modules, Building Integrated Photovoltaics, Thin Film Solar, Concentrated Photovoltaics Installation Type: Ground Mounted, Rooftop, Off-Grid, Hybrid Systems |
| Companies Covered | Hangzhou First Applied Material, Shanghai HIUV New Materials, Jiangsu Sveck Photovoltaic New Material, Guangzhou Lushan New Materials, 3M, JA Solar Technology, Cybrid Technologies, Changzhou Sveck Photovoltaic New Material, Kenko Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EVA Interlayer for Photovoltaic Market Trends and Innovations
Formulation chemistry and lamination process control are converging to address the thermal and optical demands of next-generation cell architectures, with material suppliers racing to match the performance windows that n-type and tandem technologies require.
Anti-PID EVA with tailored vinyl acetate distribution and chelating additive packages is rewriting the encapsulant selection criteria for TOPCon and heterojunction modules. Tier-1 module manufacturers in China and Germany are mandating these grades for 25-year warranty coverage. The technology is compressing commodity EVA volumes into legacy p-type replacement markets while concentrating margin pools with compounders possessing in-house additive synthesis capabilities.
REACH restrictions on certain peroxide crosslinking byproducts are forcing European EVA suppliers to reformulate initiator packages and validate alternative chemistries with module assemblers. The regulation is extending qualification timelines by 6-9 months for products entering EU supply chains. German and Spanish module factories are responding by consolidating supplier lists to partners with established REACH-compliant resin streams.
Direct mill-to-lamination supply contracts are displacing spot-market resin purchases among the largest module manufacturers. Long-term offtake agreements with compounders like Hangzhou First and Shanghai HIUV are locking in volume and price corridors that insulate buyers from ethylene volatility. This pattern is most visible in China and India where vertically integrated solar manufacturers are capturing margin through captive interlayer sourcing.
EVA Interlayer for Photovoltaic Market Segmentation
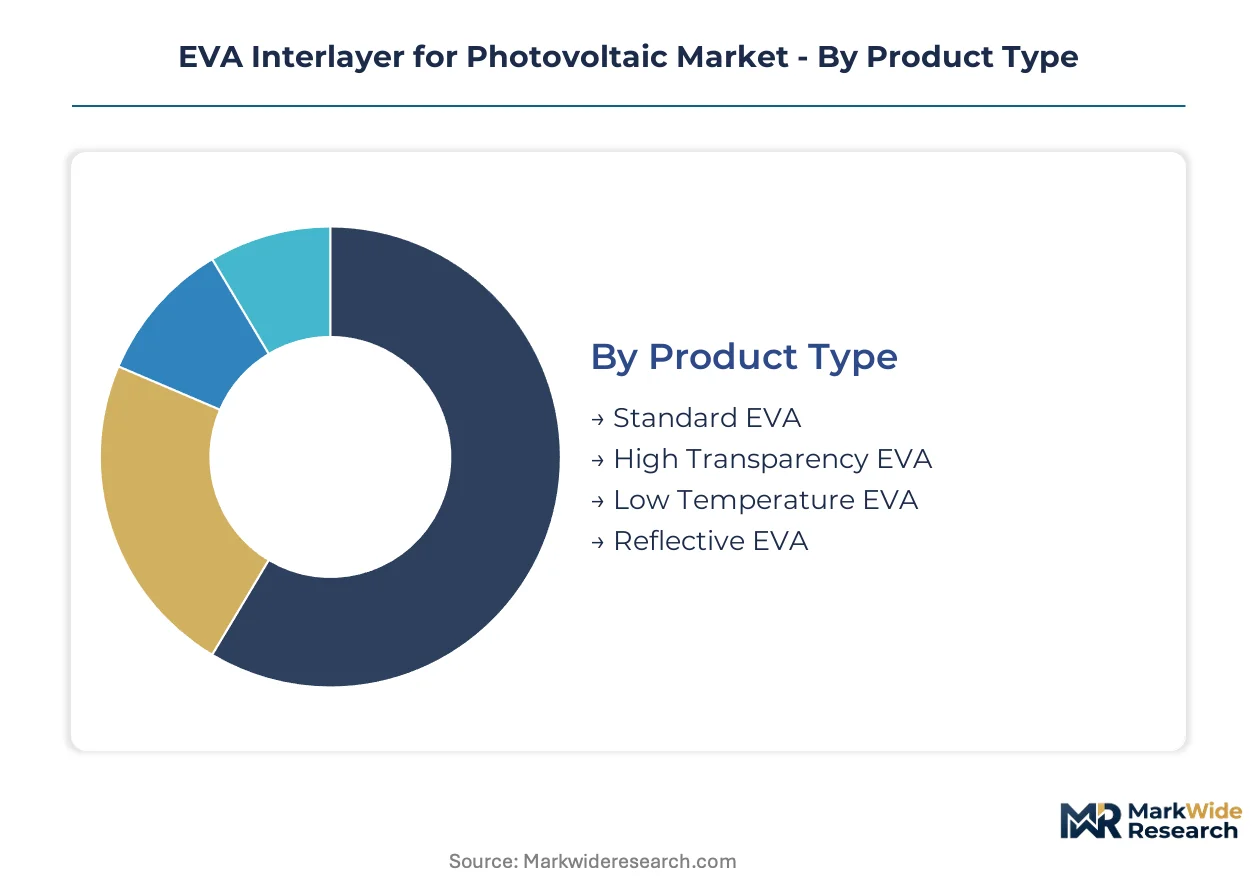
EVA interlayer procurement patterns diverge sharply across product grades and installation contexts, with module efficiency roadmaps and regional incentive structures reshaping how manufacturers allocate formulation investments across their portfolios.
Product Type:
Standard grades serve legacy p-type module replacement cycles as standalone purchases, while specialty formulations embed deeper into n-type and bifacial system architectures demanding warranty-compliant chemistry.
- Standard EVA:Vinyl acetate content near 28% delivers baseline optical clarity and adhesion for cost-sensitive monocrystalline modules. Procurement concentrates in India and Southeast Asia where p-type assembly lines still dominate domestic module targets, though margin compression from ethylene feedstock swings limits compounder enthusiasm for capacity expansion here.
- High Transparency EVA:Elevated optical clarity above 93% and tuned UV-cut profiles address the photon transmission demands of TOPCon and heterojunction cells. German and Chinese module manufacturers now mandate these grades for 25-year warranty coverage on n-type products, pulling formulation R&D toward chelating additive packages that suppress potential-induced degradation.
- Low Temperature EVA:Peroxide systems engineered for sub-140°C curing protect thermally sensitive heterojunction cells while cutting lamination energy costs.
- Reflective EVA:White-pigmented formulations redirect albedo to bifacial rear sides, commanding price premiums in utility-scale Chinese and Indian solar farms optimizing rear-side gain.
Volume placements concentrate in Standard EVA; the faster expansion belongs to High Transparency EVA.
End User:
Customer scale determines specification stringency, with large procurement teams driving qualification protocols that smaller residential distributors cannot replicate.
- Utility Scale:Developers of multi-hundred-megawatt solar farms in China and India specify reflective and anti-PID grades through multi-year offtake contracts, embedding EVA selection into levelized cost of electricity models where rear-side albedo gain and degradation rates compound across project lifespans.
- Commercial:Rooftop and C&I installers in Germany balance fire safety certifications with aesthetic requirements for building-integrated applications, sourcing REACH-compliant formulations with documented carbon footprints under EU Green Deal procurement rules.
- Residential:Distributed solar households in India and Brazil purchase modules incorporating standard EVA through installer networks with limited visibility into encapsulant sourcing.
- Government:Public tender programs in Saudi Arabia and the UAE specify performance warranties and domestic content ratios that indirectly shape EVA grade selection through module qualification requirements.
Procurement scale peaks with Utility Scale deployments; Commercial segments are climbing the fastest as building-integrated mandates spread.
Application:
Module architecture complexity dictates encapsulant performance thresholds, with conventional crystalline silicon demanding less chemical sophistication than tandem or concentrator designs.
- Solar Modules:Crystalline silicon panels—monocrystalline, polycrystalline, and bifacial variants—absorb the vast majority of EVA volume, with n-type diffusion driving rapid grade substitution toward high-transparency and anti-PID formulations in Chinese and German assembly lines.
- Building Integrated Photovoltaics:Facade and skylight installations in European commercial construction require EVA with enhanced fire resistance and color stability under prolonged UV exposure, often laminated between glass-glass stacks with stricter edge-seal requirements than fielded modules.
- Thin Film Solar:Cadmium telluride and CIGS manufacturers employ modified EVA with lower curing temperatures to protect temperature-sensitive semiconductor layers.
- Concentrated Photovoltaics:High-flux optical systems in Middle Eastern desert installations demand EVA with superior thermal stability and ionic purity to withstand concentrated irradiance and thermal cycling.
Deployment volume centers on Solar Modules; Building Integrated Photovoltaics posts the steepest expansion trajectory as European construction codes tighten renewable integration mandates.
Installation Type:
Mounting configuration shapes environmental stress profiles, with ground-mounted arrays facing distinct degradation mechanisms than rooftop or off-grid systems.
- Ground Mounted:Utility-scale fixed-tilt and tracking installations across China's western provinces and India's Rajasthan desert expose EVA to sand abrasion, thermal cycling, and humidity combinations that accelerate hydrolysis in standard grades, driving specification of enhanced moisture barrier formulations.
- Rooftop:Distributed commercial and residential systems in Germany and Japan face accelerated UV degradation from reflected irradiance and localized heating from poor ventilation, favoring EVA with stabilized UV-cut chemistry and higher vinyl acetate content for flexibility retention.
- Off-Grid:Remote installations in sub-Saharan Africa and Southeast Asian islands prioritize module durability under erratic maintenance schedules, with EVA selection secondary to cell efficiency and battery pairing.
- Hybrid Systems:Solar-plus-storage and solar-diesel configurations in mining and telecom applications stress EVA through irregular operating temperatures and vibration exposure during transport to remote sites.
Ground Mounted systems absorb the greatest EVA volume; Rooftop segments gain share fastest as distributed generation targets proliferate across European and Asian cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province anchors global EVA interlayer manufacturing, with Changzhou and Zhenjiang hosting over half of China's encapsulant compounding capacity. Module assembly clusters in these cities feed domestic gigawatt-scale solar farms while exporting to Southeast Asian and European markets.
China
Dual carbon goals and provincial renewable mandates in Jiangsu and Zhejiang are accelerating demand for high-transparency and anti-PID grades. MEE carbon intensity benchmarks on petrochemical feedstock operations are pushing compounders toward cleaner peroxide systems and renewable-powered facilities. Changzhou's Sveck Photovoltaic corridor concentrates reflective EVA production for bifacial module exports to India and the Middle East.
India
PLI scheme subsidies for solar manufacturing are attracting EVA interlayer localization investments as domestic module capacity scales toward national targets. CEA grid connectivity standards indirectly shape encapsulant selection through module qualification requirements. Gujarat's Mundra and Tamil Nadu's Sri City industrial zones are emerging as compounding hubs serving the western and southern solar corridors.
Germany
EU Green Deal embodied carbon rules for imported solar modules are forcing assemblers to specify low-carbon EVA interlayers from renewable-powered suppliers. REACH restrictions on crosslinking additives extend qualification timelines by 6-9 months, consolidating supplier lists. Saxony-Anhalt's Bitterfeld-Wolfen chemical park hosts specialized compounding for building-integrated photovoltaics requiring fire-resistant formulations.
United States
IRA domestic content bonuses for solar projects are creating pull-through demand for North American-sourced encapsulants, though compounding capacity remains limited. EPA VOC emission regulations from resin production and lamination processes shape facility siting decisions. Ohio's polymer corridor and Texas's petrochemical complexes represent potential expansion zones for localized supply.
Japan
METI feed-in tariff adjustments and building-integrated solar mandates are sustaining demand for premium-grade EVA with enhanced UV stability and color consistency. JIS standards for fire safety and long-term durability exceed baseline IEC requirements, filtering supplier qualification. Kyushu's Fukuoka industrial zone maintains specialized compounding for thin-film and heterojunction module architectures.
EVA Interlayer for Photovoltaic Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and certification depth, with anti-PID and low-temperature grades commanding sustained price premiums. The supplier base concentrates among Chinese compounders with integrated resin sourcing, while European and Japanese specialists occupy niche positions in high-specification building-integrated and fire-rated segments. Three archetypes dominate: integrated petrochemical-resin-compounders, independent specialty formulators, and captive module-maker supply divisions. Capacity expansion and backward integration into resin compounding represent the dominant competitive moves as ethylene volatility reshapes cost structures.
Within the integrated compounder tier, Hangzhou First Applied Material and Shanghai HIUV New Materials exemplify archetypes of scale-driven, process-optimized suppliers serving tier-1 module manufacturers through direct mill-to-lamination contracts. Jiangsu Sveck Photovoltaic New Material occupies a position reflecting specialization in reflective and bifacial-optimized formulations. These three Chinese entities anchor the competitive structure, with their geographic clustering in Jiangsu and Zhejiang provinces reinforcing supply-side concentration even as end-markets diversify across India, Europe, and utility-scale deployments in the Middle East.
| Leading Market Players |
|---|
| Hangzhou First Applied Material |
| Shanghai HIUV New Materials |
| Jiangsu Sveck Photovoltaic New Material |
| Guangzhou Lushan New Materials |
| 3M |
| JA Solar Technology |
| Cybrid Technologies |
| Changzhou Sveck Photovoltaic New Material |
| Kenko Industrial |
| Others |
Pricing and Supply Chain Analysis
Naphtha price volatility cascades through ethylene and EVA resin markets, compressing interlayer margins during crude spikes while concentrating pricing power among integrated compounders in Jiangsu and Zhejiang provinces. Module manufacturers respond with multi-year offtake contracts that lock in volume corridors and insulate against feedstock swings.
Pricing Analysis
Warranty-compliant throughput anchors value-based pricing for anti-PID and high-transparency EVA grades, with compounders capturing premiums tied to module yield guarantees rather than resin tonnage. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified specialty formulations from commodity p-type replacement grades. Pricing pressure stems from POE substitution in high-humidity applications, eroding EVA's historical cost advantage. Utility-scale developers exhibit lowest price sensitivity due to LCOE modeling, while residential distributors in India and Brazil prioritize lowest unit cost.
Supply Chain Analysis
Dual-sourcing requirements from European and Japanese module assemblers mandate qualification of at least two compounders per grade, extending procurement timelines but reducing single-source exposure. Manufacturing concentrates in China, India, and Germany, with Jiangsu province hosting over half of global compounding capacity. Feedstock draws from naphtha crackers in Zhejiang and Shandong, with peroxide initiators sourced from domestic chemical parks. Single-source vulnerability persists in specialty additive synthesis, where chelating agent production remains concentrated among incumbent suppliers. Distribution runs through direct mill-to-lamination contracts for tier-1 module makers, supplemented by distributor networks serving smaller assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethylene feedstock volatility and crosslinking chemistry expertise gaps constrain new capacity additions, propping pricing for qualified suppliers while compressing margins for undifferentiated compounders.
For Market Incumbents: Lock in multi-year offtake agreements with tier-1 module manufacturers before POE substitution accelerates in humid climates. Invest in backward integration into peroxide initiator synthesis to secure additive supply chains against REACH restriction disruptions. Prioritize low-temperature curing R&D to capture heterojunction cell demand as thermal sensitivity tightens specification windows. For New Entrants and Emerging Players: Enter via India's PLI-driven module assembly corridor, where domestic content requirements and scaling capacity create procurement gaps for localized EVA supply. Target reflective EVA for bifacial utility projects in Rajasthan and Gujarat, where rear-side albedo optimization commands price premiums. Pursue direct qualification with state-run solar developers to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated resin-compounders with renewable-powered facilities in Jiangsu province, where MEE carbon benchmarks are stranding conventional petrochemical assets. Long-term viability hinges on formulation chemistry capabilities transferable to perovskite tandem encapsulant requirements. Watch POE market share trajectories in Southeast Asian humid-climate installations as an inflection signal for EVA demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Peroxide Initiator Synthesis | Secures additive supply chains against REACH restriction disruptions affecting European module exports. |
| Low-Temperature Curing Formulation Development | Captures heterojunction cell demand as thermal sensitivity below 140°C becomes mandatory. |
| India Localization Investment | Positions compounders to meet PLI scheme domestic content requirements for module assembly. |
| Reflective EVA Capacity Expansion | Serves bifacial utility demand in Rajasthan and Chinese western provinces optimizing rear-side albedo gain. |
| REACH-Compliant Resin Stream Qualification | Maintains EU market access as ECHA restrictions extend crosslinking additive approval timelines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with EVA compounding plant managers, module manufacturer procurement leads, solar EPC contractors, and peroxide initiator technical directors. SEC 10-K disclosures from petrochemical feedstock suppliers, MEE carbon intensity benchmarks, and IEC certification databases provided volume and pricing validation. Bottom-up resin consumption estimates triangulated against top-down module production forecasts across the analysis window.
Data-stream reconciliation aligned ethylene price indices, naphtha crack spreads, and module assembly capacity buildouts into a unified forecasting framework. Segmentation dimensions modeled include product grade tier, end-use installation scale, cell architecture type, and regional regulatory cluster. CAGRs derived from compound growth logic applied to resin throughput per module wattage, with heterojunction penetration rates and bifacial market share as solar-specific demand drivers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ethylene feedstock volatility and POE substitution acceleration. Projections reflect assumptions on n-type cell diffusion timelines, REACH additive approval pathways, and Indian PLI scheme disbursement continuity. Deviation in perovskite tandem commercialization schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Compostable Cotton Swab Market
Specialty Materials
Specialty Polyamides Market
Specialty Materials
Europe Solar Control Window Films Market
Specialty Materials
Light Diffusion Materials Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Specialty Silica Market
Specialty Materials
Silicone Film Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Spermaceti Wax Market
Specialty Materials
Conductive Plastics Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
PVB Interlayers Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Jesmonite Market