
 Super Engineering Plastics Market | 2026-2036
Super Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Super Engineering Plastics Market Outlook
Specialty chemical distribution is fragmenting as regional distributors and B2B platforms capture share from traditional bulk channels in super engineering plastics. DSM leverages backward integration into bio-based polyamide feedstocks to secure supply continuity. BASF sustains technology leadership through advanced PBT compounding capabilities for electrical applications. DuPont anchors its position with high-heat polycarbonate grades serving aerospace OEM specifications.
Super engineering plastics are high-performance thermoplastic polymers with continuous-use temperatures exceeding 150°C, including polycarbonate, polyamide, PBT, and acetal, manufactured through polycondensation and ring-opening polymerization processes for load-bearing precision components. These materials deliver dimensional stability, chemical resistance, and flame retardancy for aerospace, automotive, electrical, and medical applications. Polyamide dominates volume due to its balance of mechanical properties and processability across automotive under-hood and electrical connector segments. PBT captures margin pools in miniaturized electrical housings where dimensional precision commands premium pricing. Medical applications represent the fastest-growing segment as surgical device manufacturers adopt sterilization-resistant acetal and polycarbonate grades for reusable instrumentation.
REACH in Europe mandates substance registration and restricts hazardous additives in polymer formulations, while RoHS limits heavy metal content in electrical-grade plastics, compelling reformulation of flame-retardant systems. FDA oversees biocompatibility requirements for medical device polymers in the United States, and ISO 10993 testing protocols govern material qualification for surgical instrument applications. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these chemicals historically enabled critical performance properties in high-end formulations and their phase-out demands accelerated development of alternative polymer architectures.
Market Dynamics
REACH substance restrictions and RoHS heavy metal limits are forcing wholesale reformulation of flame-retardant systems across European polymer supply chains. Aerospace OEMs simultaneously demand higher continuous-use temperatures above 150°C while medical device manufacturers pursue sterilization-resistant grades, creating divergent technical requirements that reshape supplier capabilities.
Growth Catalysts
- REACH compliance mandates:European ECHA registration requirements for polymer additives are accelerating substitution toward bio-based polyamide feedstocks. Reformulation investments now prioritize registered substance portfolios over legacy halogenated systems.
- Aerospace lightweighting specifications:OEM structural component requirements for continuous-use temperatures exceeding 150°C are pulling high-heat polycarbonate grades into wing and fuselage applications previously served by metal assemblies.
- German automotive clusters:Stuttgart and Munich industrial concentrations drive specialized consumption of polyamide for under-hood precision components. Regional tier-1 supplier density creates captive demand for localized compounding capabilities.
Market Restraints
- Caprolactam feedstock volatility:Polyamide raw material costs fluctuate with benzene derivative markets. European petrochemical supply concentration exposes compounders to input price swings without vertical hedge mechanisms.
- Per- and polyfluoroalkyl substance phase-outs:Multiple jurisdictions are restricting PFAS chemicals historically critical for high-end formulation performance. Alternative polymer architectures require extended development timelines.
- Medical device qualification duration:FDA biocompatibility reviews and ISO 10993 testing protocols extend surgical instrument material approval cycles. Sterilization-resistant acetal and polycarbonate grades face 18-24 month certification windows.
Strategic Opportunities
- India electrical connector demand:BIS standards harmonization with IEC specifications is opening import substitution opportunities for PBT compounds serving miniaturized housing applications. Domestic automotive wiring harness growth outpaces local polymer supply.
- China NMPA medical device pathway:Streamlined registration for sterilization-reusable surgical instruments creates entry vectors for polycarbonate grades meeting GB biocompatibility requirements. Dual carbon policy incentives favor localized production.
- Bio-based feedstock integration:Agricultural waste-derived polyamide precursors align with EU Green Deal procurement criteria. DSM's backward integration model demonstrates supply continuity advantages for sustainability-mandated buyers.
Industry Challenges
- Compounding technician scarcity:PBT precision formulation for electrical miniaturization requires specialized rheology expertise. European polymer engineering programs graduate insufficient talent for medical-grade and aerospace-specification production lines.
- Legacy flame-retardant system replacement:Reformulating halogen-free alternatives without sacrificing CTI performance demands iterative testing cycles. Electrical housing OEMs resist specification changes mid-product-lifecycle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Super Engineering Plastics Market |
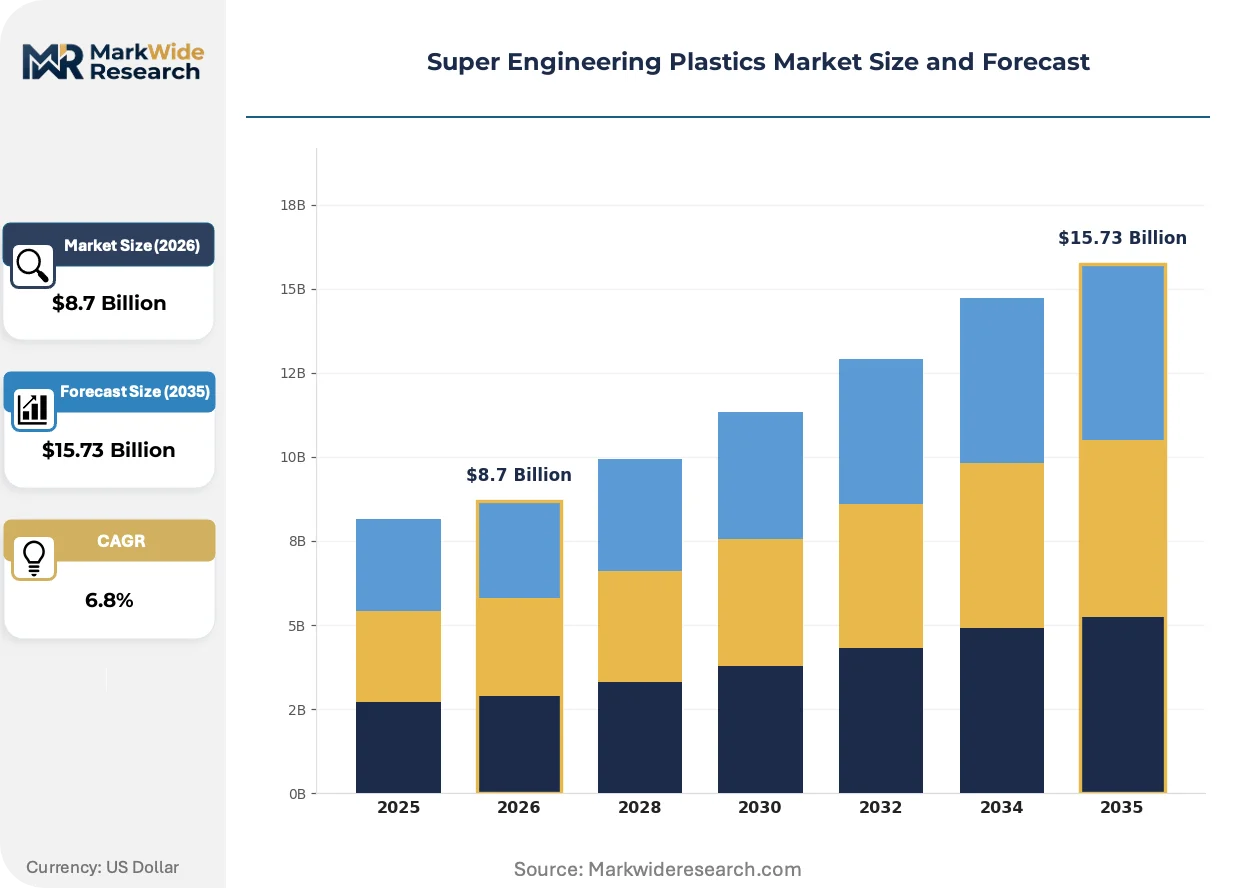
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Polyamide, PBT, Acetal Application: Aerospace, Automotive, Electrical, Medical End User: Aerospace OEMs, Consumer Electronics, Industrial Equipment, Surgical Devices Distribution Channel: Direct Sales, Distributors, Online Retail, B2B Platforms |
| Companies Covered | DSM, Ascend Performance Materials, BASF, DuPont, Sumitomo Chemical, Toray Industries Inc., Invista, DIC Corporation, Asahi Kasei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Super Engineering Plastics Market Strategic Shifts
Digital twin technologies are compressing polymer formulation development cycles while regulatory substance databases enable predictive compliance screening. These capabilities intersect with distributed manufacturing models that reshape where compounding occurs relative to end-use demand.
High-performance polymer simulation software is virtualizing traditional trial-and-error compounding workflows. BASF and DuPont technical centers deploy molecular modeling to predict PBT crystallization behavior and polycarbonate thermal degradation before physical batch production. Aerospace material qualification timelines compress as virtual testing generates preliminary data packages for FAA submission. This capability is virtualizing the historical bottleneck between R&D lab and production-scale validation.
ECHA SVHC candidate list expansions are triggering supply chain disclosure requirements for polymer additives. European compounders must now document substance concentrations above 0.1% w/w across imported and domestically sourced feedstocks. Electrical connector manufacturers face particular exposure as legacy brominated flame retardants appear on updated restriction proposals. German automotive OEMs are responding by mandating full material composition declarations from tier-2 polymer suppliers.
Regional distributors and specialized B2B platforms are capturing procurement volume from traditional bulk chemical channels. Medical device manufacturers in the United States now source sterilization-resistant acetal grades through vertically focused distributors offering lot traceability and certificate-of-analysis bundling. This channel shift concentrates in surgical instrument clusters around Warsaw, Indiana and Irvine, California where FDA-registered device assemblers prioritize supply chain documentation over volume pricing.
Super Engineering Plastics Market Segmentation
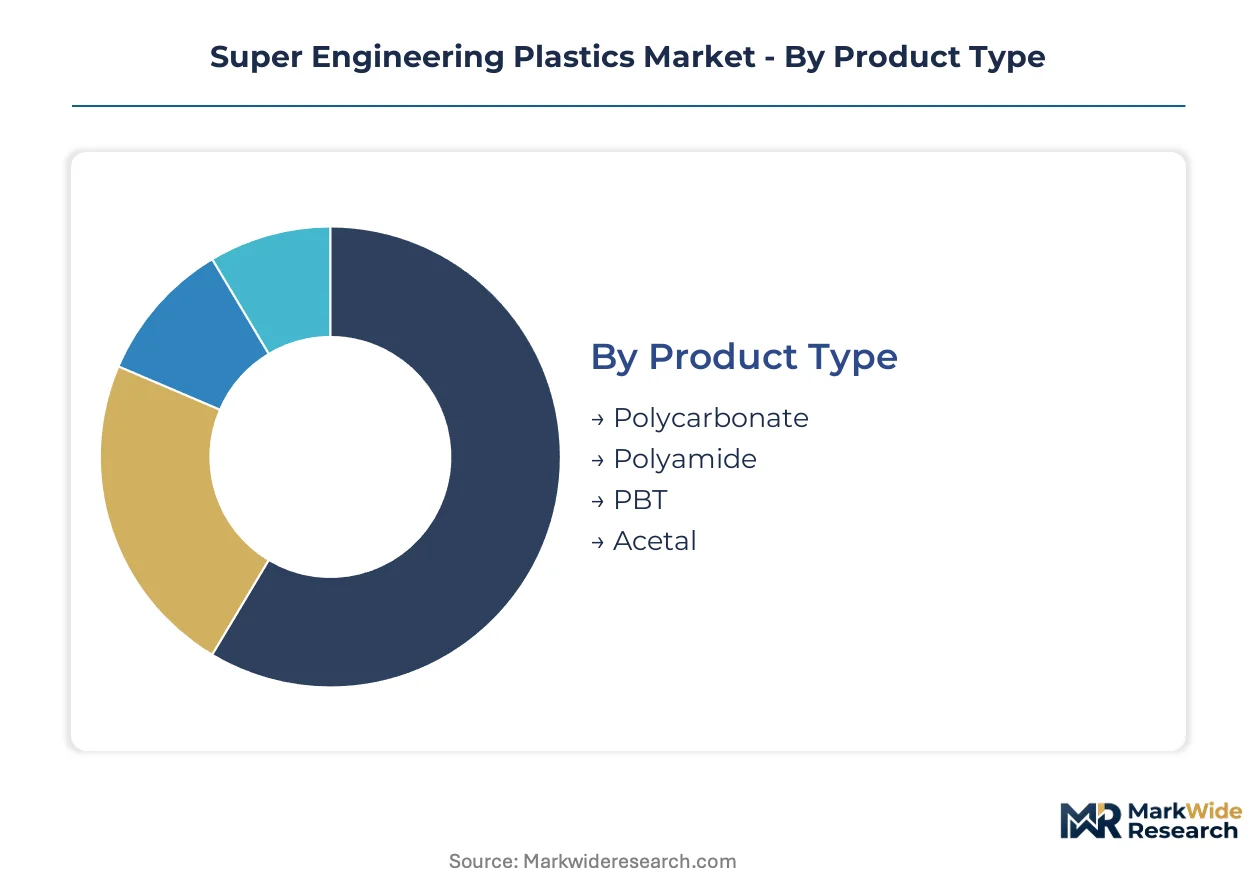
Super engineering plastics demand fragments across temperature thresholds, regulatory regimes, and precision requirements that reshape supplier-customer relationships. Segmentation reveals where formulation investments concentrate and which qualification burdens determine competitive access.
Product Type:
After-sales service intensity varies sharply across polymer families, with high-heat grades requiring technical support for processing optimization and regulatory documentation.
- Polyamide:This polymer family delivers continuous-use thermal stability above 150°C through aliphatic and semi-aromatic structures. German automotive clusters in Stuttgart and Munich consume specialized grades for under-hood precision components where dimensional stability under thermal cycling is mandatory. REACH-registered additive packages now dominate formulation specifications.
- Polycarbonate:High-heat bisphenol-A derived resins achieve glass-like transparency with impact resistance. Aerospace OEMs specify these grades for wing and fuselage structural applications previously metal-dominated, pulling demand toward FAA-qualification-ready supply chains.
- PBT:Crystalline polyester engineered for electrical miniaturization with precise dimensional control. Miniaturized connector housings in automotive wiring harnesses command premium pricing for flame-retardant compounded grades.
- Acetal:High-crystallinity homopolymer and copolymer grades deliver low friction and sterilization resistance. Surgical device manufacturers specify these for reusable instrumentation requiring autoclave cycle durability.
Polyamide holds the largest share; momentum sits with polycarbonate as aerospace lightweighting accelerates.
Application:
Cost tier stratification separates qualification-intensive medical and aerospace segments from volume-driven automotive and electrical applications.
- Automotive:Under-hood precision components including throttle bodies, fuel system modules, and electrical connectors consume heat-stabilized polyamide and PBT grades. German OEM specification authority drives formulation standardization across European supply chains.
- Medical:Sterilization-resistant grades for surgical instruments and drug delivery devices require ISO 10993 biocompatibility certification. FDA review cycles and European MDR compliance create extended material approval timelines that favor established compounders with regulatory dossier libraries.
- Aerospace:Structural and interior component specifications demand continuous-use temperature ratings exceeding 150°C with FST (flame, smoke, toxicity) compliance. OEM direct qualification relationships limit supplier switching.
- Electrical:Miniaturized housings and connectors for consumer and industrial electronics require CTI tracking resistance and halogen-free flame retardancy. RoHS compliance mandates heavy metal-free formulations.
Automotive holds the largest share; medical is climbing the fastest as device manufacturers convert metal instruments to polymer.
End User:
Customer type determines procurement modality, with OEM direct relationships contrasting distributor-dependent fragmented demand.
- Aerospace OEMs:Boeing, Airbus, and tier-1 aerostructures manufacturers specify qualified grades through approved supplier lists. Material qualification investments create multi-year lock-in with compounders holding FAA PMA documentation.
- Surgical Devices:Reusable instrument manufacturers in Warsaw, Indiana and Irvine, California prioritize lot traceability and certificate-of-analysis documentation. FDA-registered device assemblers drive demand for sterilization-validated acetal and polycarbonate grades.
- Consumer Electronics:Smartphone and laptop manufacturers specify thin-wall capable flame-retardant grades for internal structural components. Miniaturization trends push toward higher-flow PBT and polyamide variants.
- Industrial Equipment:Pump, valve, and bearing manufacturers consume wear-resistant acetal and polyamide grades for moving parts. Specification authority typically resides with equipment OEM engineering departments rather than end-user maintenance organizations.
Aerospace OEMs hold the largest share; surgical devices are gaining share fastest as instrument conversion accelerates.
Distribution Channel:
Supply concentration in compounding capacity shapes how material flows reach geographically dispersed precision manufacturers.
- Distributors:Regional specialty chemical distributors capture medical and small-batch industrial demand through certificate bundling and technical service. German automotive clusters rely on localized inventory positioning for just-in-time tier-1 supply.
- B2B Platforms:Vertically focused procurement platforms aggregate demand from mid-sized device manufacturers. Lot traceability and documentation workflow integration differentiate platform value against traditional channels.
- Direct Sales:Aerospace OEMs and large automotive tier-1s negotiate direct contracts with BASF, DSM, and DuPont for qualified grades. Volume commitments secure allocation priority during feedstock constraints.
- Online Retail:Small-lot prototyping and R&D sampling flow through e-commerce channels with limited technical support. Price transparency benefits buyers with internal formulation expertise.
Distributors hold the largest share; B2B platforms are expanding most quickly as procurement digitization penetrates mid-market device manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal procurement criteria and national industrial policies are redirecting polymer demand toward bio-based feedstocks and localized compounding capacity across major manufacturing economies.
Germany
Automotive OEM specification authority in Stuttgart and Munich clusters drives specialized polyamide consumption for under-hood precision components. REACH-registered additive packages now dominate formulation requirements from ECHA. Baden-Württemberg's tier-1 supplier density creates captive demand for localized compounding capabilities serving just-in-time production lines.
United States
FAA qualification requirements for high-heat polycarbonate grades pull aerospace OEM demand toward approved supplier networks. FDA biocompatibility reviews under 21 CFR govern surgical instrument material approvals. Warsaw, Indiana and Irvine, California surgical device clusters prioritize lot traceability and certificate-of-analysis documentation from polymer distributors.
China
NMPA streamlined registration pathways for sterilization-reusable surgical instruments create entry vectors for polycarbonate grades meeting GB biocompatibility requirements. Dual carbon policy incentives favor localized production of high-performance polymers. Yangtze River Delta electrical connector manufacturers drive PBT demand for miniaturized automotive wiring harness applications.
Japan
METI industrial standards and JIS specifications shape electrical-grade polymer requirements for consumer electronics miniaturization. Precision compounding expertise concentrates in Kansai and Chubu industrial corridors. Osaka-based connector manufacturers specify high-flow PBT variants for thin-wall housing applications in automotive and industrial equipment segments.
India
BIS standards harmonization with IEC specifications opens import substitution opportunities for PBT compounds serving miniaturized electrical housing applications. PLI scheme incentives for domestic automotive manufacturing accelerate wiring harness demand. Maharashtra and Tamil Nadu automotive clusters outpace local polymer supply, creating distributor expansion opportunities.
Super Engineering Plastics Market Competitive Environment
On the supply side, the industry is consolidating around integrated compounders with captive feedstock positions and qualification-ready regulatory dossiers. Three strategic archetypes dominate: European chemical majors with backward integration into bio-based polyamide precursors, Japanese diversified chemical groups with precision compounding expertise, and specialized performance material divisions of global conglomerates. Competitive moves center on M&A for regulatory dossier libraries and capacity expansion in medical-grade cleanroom compounding facilities.
Within the integrated European tier, DSM and BASF exemplify divergent feedstock strategies. DSM's backward integration into bio-based polyamide precursors aligns with EU Green Deal procurement criteria, while BASF sustains technology positioning through advanced compounding capabilities. DuPont anchors the high-heat polycarbonate segment serving aerospace OEM qualification requirements. These three entities represent the archetype of regulatory-compliant, specification-grade supply.
| Leading Market Players |
|---|
| DSM |
| Ascend Performance Materials |
| BASF |
| DuPont |
| Sumitomo Chemical |
| Toray Industries Inc. |
| Invista |
| DIC Corporation |
| Asahi Kasei |
| Others |
Value Chain & Pricing Dynamics
Baden-Württemberg's polyamide compounding cluster anchors European supply capacity, with Stuttgart's tier-1 supplier density translating into localized pricing power for heat-stabilized grades serving just-in-time automotive lines.
Pricing Analysis
Certification level creates the primary spread between medical-grade ISO 10993-validated acetal and standard industrial polyamide, with FDA-registered surgical instrument compounds commanding substantial premiums over automotive under-hood grades. Three-tier pricing structure separates aerospace-qualified polycarbonate with FAA PMA documentation from commercial electrical PBT and economy-grade recycled-content variants. Pricing pressure stems from caprolactam feedstock volatility as benzene derivative markets swing without vertical hedge mechanisms. Consumer electronics buyers exhibit highest price sensitivity, while aerospace OEMs prioritize qualification continuity over unit cost.
Supply Chain Analysis
Tariff exposure between China and Germany dominates supply chain risk planning as Yangtze River Delta polycarbonate capacity feeds European electrical connector demand. Manufacturing concentrates in Germany, China, and Japan, with each hub specializing in distinct grade families. Feedstock dependencies rest on caprolactam for polyamide, bisphenol-A for polycarbonate, and purified terephthalic acid for PBT crystallization. Single-source vulnerability characterizes aerospace-qualified supply chains where FAA PMA documentation locks compounders into multi-year relationships. Distribution runs through regional specialty distributors for medical small-batch demand and direct sales for automotive tier-1 volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as the primary defensive moat, with ISO 10993 dossier libraries and FAA PMA qualifications creating switching costs that extend customer retention across product lifecycles.
For Market Incumbents: Harden qualification barriers by expanding cleanroom compounding capacity in medical device clusters around Warsaw, Indiana and Irvine, California. Deepen backward integration into bio-based polyamide feedstocks to neutralize caprolactam price volatility. Anchor aerospace relationships through dedicated technical service teams embedded at Boeing and Airbus engineering centers.
For New Entrants and Emerging Players: Build out PBT compounding capabilities targeting India's Maharashtra and Tamil Nadu automotive wiring harness demand as BIS-IEC harmonization opens import substitution windows. Pursue distributor partnerships offering lot traceability and certificate bundling rather than competing for direct OEM contracts. Prioritize sterilization-reusable surgical instrument grades where NMPA streamlined registration in China lowers qualification barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized medical-grade cleanroom assets and dormant regulatory dossiers. Long-term viability hinges on compounding expertise migration as European polymer engineering programs contract. Monitor PFAS restriction acceleration across multiple jurisdictions as the signal indicating which compounders will face forced reformulation costs versus those holding alternative architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | DSM's agricultural waste-derived polyamide model secures EU Green Deal procurement preference. |
| Medical-Grade Cleanroom Capacity Expansion | ISO 10993-validated compounding lines capture surgical instrument conversion from metal. |
| Aerospace Qualification Dossier Acquisition | FAA PMA documentation libraries create multi-year lock-in with Boeing and Airbus. |
| Regional Distributor Partnership Deepening | Lot traceability bundling penetrates mid-market device manufacturers in Warsaw and Irvine. |
| PFAS-Free Formulation Development | Alternative polymer architectures address ECHA restriction proposals before enforcement deadlines. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with polymer compounding plant managers, automotive tier-1 procurement leads, medical device biomedical engineers, and specialty chemical distribution channel partners; and secondary validation drawing from ECHA substance registration databases, FDA 510(k) filings, customs trade data, and SEC 10-K disclosures from listed chemical majors. Bottom-up volume modeling across grade families triangulated against top-down market sizing from production capacity assessments.
Forecast inputs incorporated polymer grade tier, end-use industry application, regional regulatory cluster, and qualification intensity level across the projection horizon. CAGRs derived from segmented growth rate analysis weighted by automotive production forecasts, aerospace OEM build rates, and medical device approval timelines. Caprolactam feedstock pricing volatility and PFAS regulatory trajectory served as scenario variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed polymer producers or accelerated PFAS phase-outs would shift outcomes. Material shifts in REACH substance restriction scope or NMPA medical device registration timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Global Graphic Film Market
Specialty Materials
Europe Textile Films Market
Specialty Materials
Africa Collagen Market
Specialty Materials
Middle East and Africa Anti-Friction Coatings Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
Specialty Polyamides Market
Specialty Materials
PCB Prepreg Material Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Europe Microspheres Market
Specialty Materials
Methyl Silicone Market
Specialty Materials
Global PU Films Market
Specialty Materials
Light Diffusion Materials Market
Specialty Materials
Compostable Cotton Swab Market
Specialty Materials
Epoxy Encapsulation Material Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market
Specialty Materials
Non-Semiconductor Neon Market