
 Adhesion Laminated Surface Protection Films Market | 2026-2036
Adhesion Laminated Surface Protection Films Market Size, Share, and Industry Trends Forecast 2026-2036
Adhesion Laminated Surface Protection Films Market Intelligence
High-clarity, low-tack residue-free films are bifurcating the market away from standard-grade protective layers. Nitto Denko Corporation specializes in advanced optical films for electronics applications. 3M leverages its broad materials science portfolio to serve diverse industrial equipment needs. Saint-Gobain Performance Plastics competes with high-performance solutions for aerospace components, demonstrating the breadth of end-user requirements.
Adhesion laminated surface protection films are multi-layer composites designed to safeguard surfaces from scratches, abrasion, and environmental damage during manufacturing, transit, or use. These films typically consist of a base material like Polyethylene Terephthalate (PET) coated with a pressure-sensitive adhesive. Within applications, consumer electronics represents the fastest-growing segment due to short product cycles and high aesthetic standards. Water-based adhesive technologies are gaining share over solvent-based alternatives due to stricter environmental regulations.
Regulatory frameworks such as the EU’s REACH regulation and China's GB standards dictate the chemical composition of adhesives and polymer substrates. In the United States, EPA guidelines on volatile organic compounds (VOCs) influence the shift towards water-based and UV-curable technologies. Navigating these divergent material compliance requirements is a central challenge for manufacturers seeking to maintain a unified product portfolio across major markets.
Market Dynamics
The market's central dynamic is the tension between escalating performance demands for high-clarity, residue-free films in electronics and the simultaneous tightening of environmental regulations like REACH and RoHS, which constrict the available palette of high-performance polymers and adhesives.
Growth Catalysts
- Consumer Electronics Demand:Short product lifecycles and high aesthetic requirements for smartphones, tablets, and displays in manufacturing clusters like South Korea necessitate advanced, scratch-resistant protective films for screens and casings.
- Regulatory Mandates for Greener Materials:The EU's RoHS directive, restricting hazardous substances, and EPA guidelines on VOCs are steering film and adhesive development toward more compliant, water-based technologies, creating demand for new formulations.
- Automotive Sector Expansion:The use of protective films is expanding beyond transit wrap to in-vehicle applications, safeguarding high-gloss interior surfaces, infotainment screens, and sensor lenses from scratches and wear during assembly and ownership.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the cost of petrochemical-derived base materials, particularly Polyethylene Terephthalate (PET) and Polyethylene (PE), directly impact film manufacturer margins and create pricing instability for end-users.
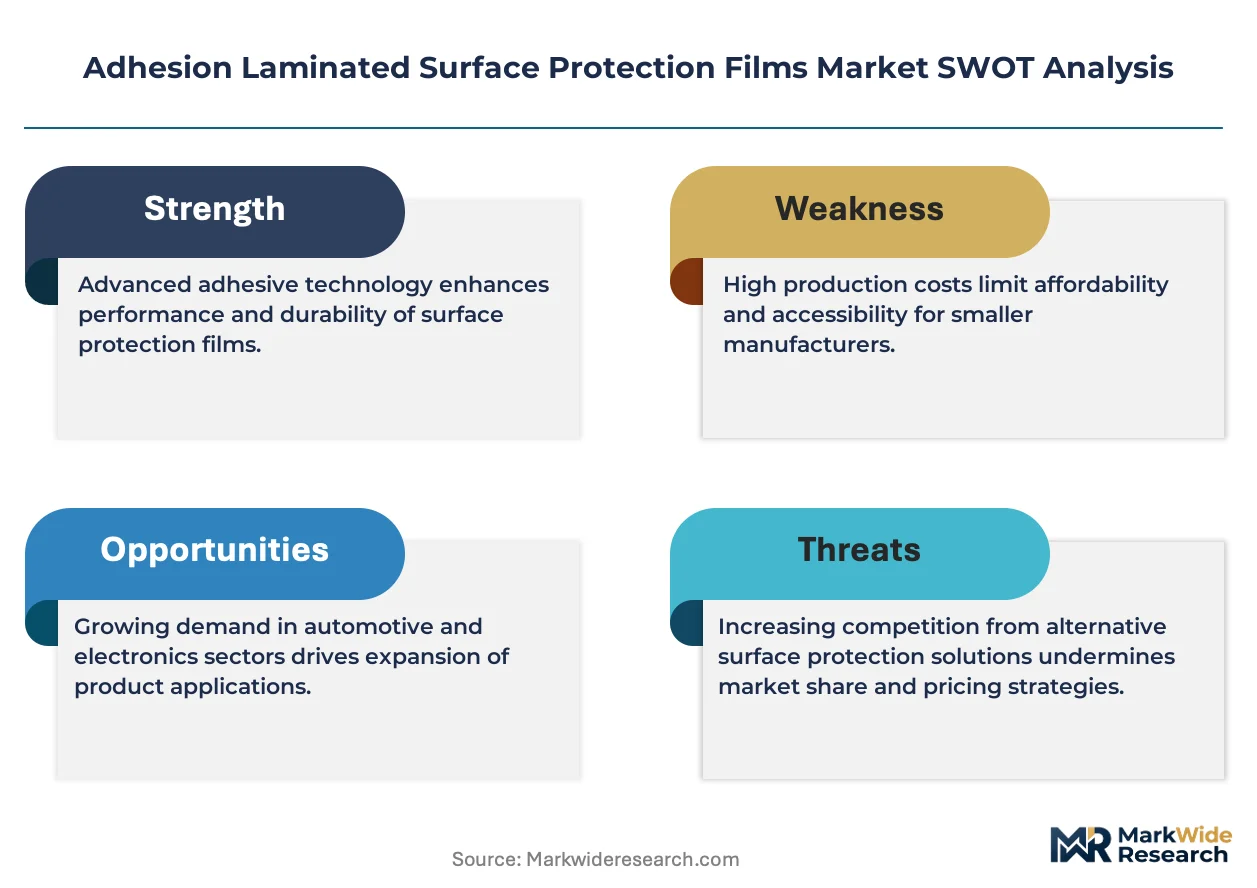
- Threat of Substitute Technologies:The development of integrated surface hardening treatments and liquid-applied, curable coatings for electronics and automotive components presents a long-term substitution risk to traditional laminated films.
- Complex Global Compliance:Navigating divergent chemical regulations, such as the EU’s REACH framework and China's GB standards, increases R&D costs and complicates the creation of a unified product portfolio for global markets.
Strategic Opportunities
- Films for Renewable Energy:Untapped applications exist in protecting surfaces of solar panels and wind turbine blades from abrasion, UV degradation, and environmental contaminants, extending operational life and maintaining efficiency.
- Functional Film Integration:There is a significant opportunity to incorporate value-added properties like anti-microbial, anti-fog, or self-healing functionalities into films for medical devices, public touchscreens, and transportation interiors.
- Expansion in Medical Device Packaging:The medical sector offers an avenue for high-margin specialty films designed to protect sterilized instruments and sensitive diagnostic equipment surfaces from contamination and damage through the supply chain.
Industry Challenges
- Specialized Certification Timelines:Obtaining necessary certifications for niche, high-consequence applications such as aerospace or medical devices is a lengthy and expensive process, creating high barriers to entry and delaying revenue generation.
- Capital-Intensive Production:The requirement for cleanroom environments and high-precision coating and lamination machinery to produce defect-free optical-grade films demands significant upfront capital investment, favoring established players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adhesion Laminated Surface Protection Films Market |
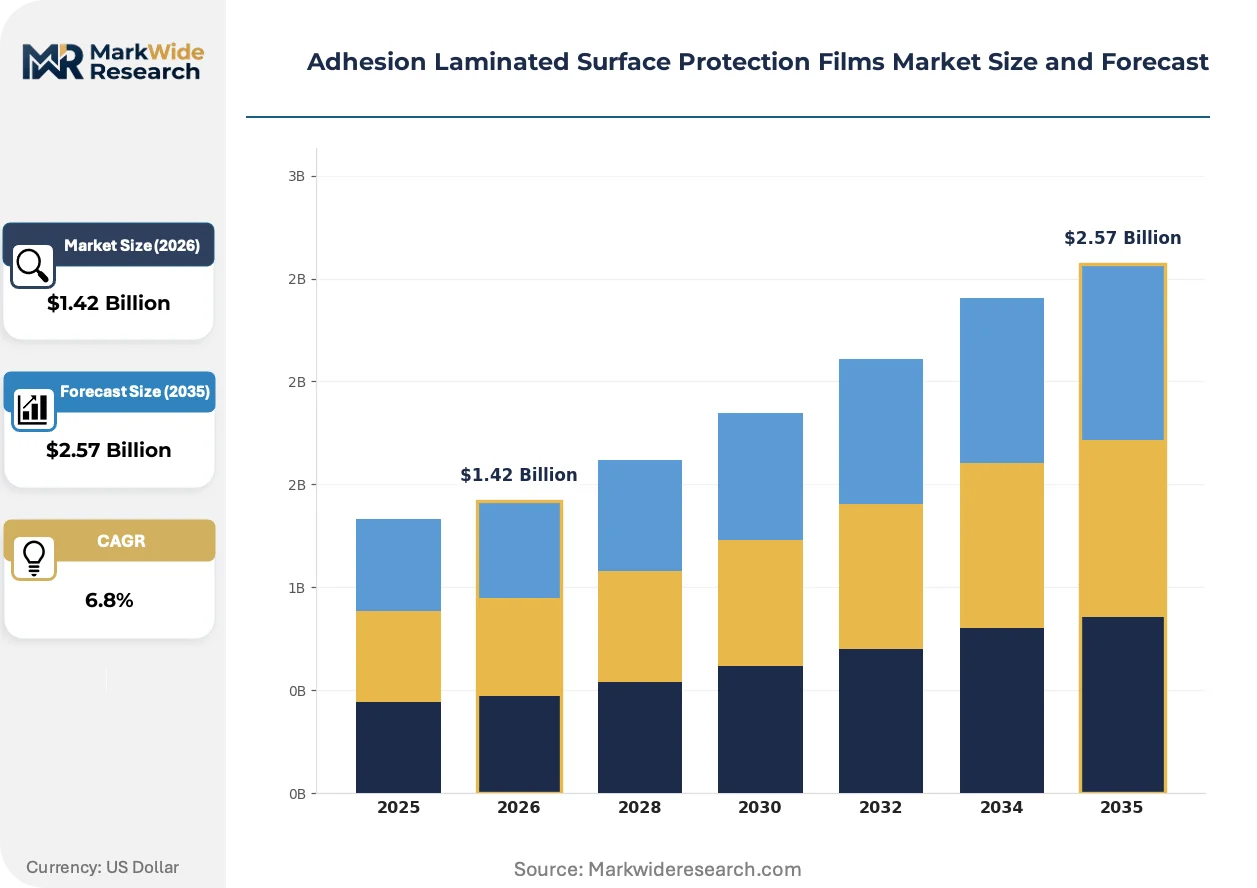
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate, Polyvinyl Chloride, Polycarbonate, Polypropylene, Polystyrene Technology: Solvent-Based, Water-Based, Radiation-Curable, Hot Melt, UV-Curable Application: Consumer Electronics, Aerospace Components, Furniture Surfaces, Industrial Equipment, Custom Fabrication End User: OEM Manufacturers, Aftermarket Suppliers, Fabricators, Contract Manufacturers, Design Studios |
| Companies Covered | Tesa SE, Saint-Gobain Performance Plastics, 3M, Henkel Corporation, Intertape Polymer Group, Nitto Denko Corporation, LINTEC Corporation, E. I. du Pont de Nemours and Company, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adhesion Laminated Surface Protection Films Market Strategic Shifts & Innovations
Innovation is focused on developing multi-functional composites that deliver enhanced surface protection while adhering to a stricter global environmental and chemical safety consensus. This evolution pushes product development beyond simple abrasion resistance toward integrated performance characteristics and sustainable material science.
Advanced multi-layer co-extrusion technology enables the creation of films with discrete, specialized layers for functions like UV blocking and anti-static control. The consumer electronics and semiconductor industries are adopting these complex films to safeguard increasingly delicate and sensitive components. This technology is miniaturizing the total film thickness while embedding more protective functions, which meets the stringent form-factor requirements of modern compact devices.
Environmental policy, particularly the US Environmental Protection Agency's (EPA) stringent limits on volatile organic compounds (VOCs), is a primary force in materials science. This regulatory pressure directly impacts adhesive formulation, driving a market-wide shift from solvent-based systems to water-based and UV-curable alternatives. Manufacturers supplying films for automotive and architectural applications are most affected, compelling them to invest heavily in R&D to reformulate product lines for compliance.
A notable behavioral shift is occurring as end-users in high-value manufacturing move from procuring bulk film rolls to demanding pre-cut, application-specific kits. This change disrupts traditional distributors who rely on slitting large rolls, creating an opening for suppliers offering precision die-cutting and just-in-time inventory services. This kitting model is most visible in the aerospace and medical device sectors, where it helps minimize material waste and streamline complex assembly workflows.
Adhesion Laminated Surface Protection Films Market Segmentation
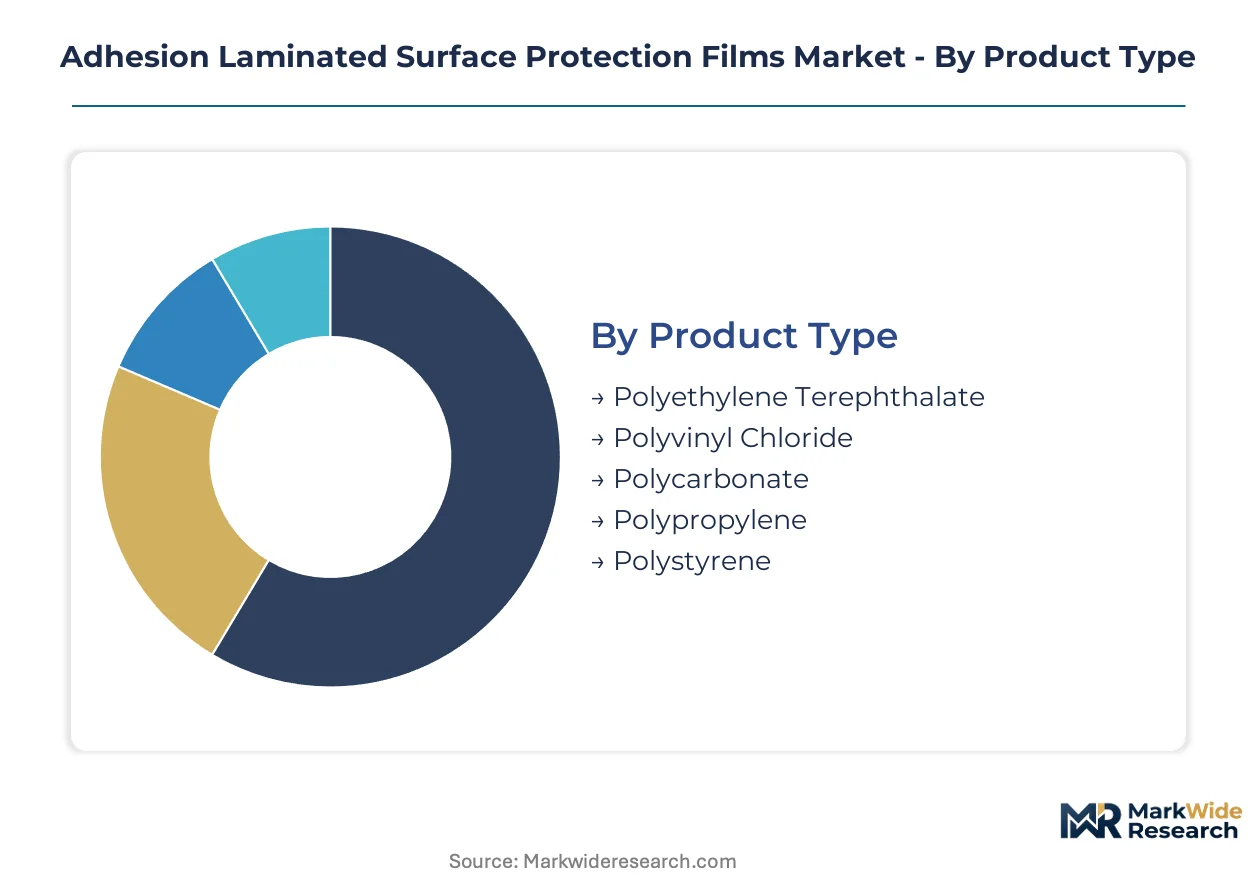
Understanding the segmentation of the adhesion laminated surface protection films market reveals the diverse material requirements and technological preferences driving product development. This analysis highlights specific areas of concentrated demand and the varying performance criteria across end-use sectors.
Product Type:
Margin pools within product types concentrate in advanced polymer films offering superior optical clarity and durability for high-value applications.
- Polyethylene Terephthalate:Polyethylene Terephthalate (PET) films offer high tensile strength and excellent dimensional stability, making them suitable for optical applications. Demand for PET films is strong in South Korea's consumer electronics sector, particularly for high-resolution display protection.
- Polycarbonate:Polycarbonate films provide exceptional impact resistance and optical transparency, often used where robust protection is critical. Automotive manufacturers in Germany increasingly specify polycarbonate films for protecting interior display panels and headlamp lenses.
- Polyvinyl Chloride:Polyvinyl Chloride (PVC) films offer flexibility and chemical resistance, finding use in general industrial masking applications.
- Polypropylene:Polypropylene (PP) films provide good moisture barrier properties and are cost-effective for packaging and temporary surface protection.
- Polystyrene:Polystyrene (PS) films are rigid and transparent, often employed in less demanding protective applications or as temporary carriers.
The dominant share belongs to Polyethylene Terephthalate, while Polycarbonate is closing the gap fastest.
Technology:
Cost tiers for adhesive technologies reflect raw material purity and the complexity of formulation processes.
- Water-Based:Water-based adhesive technologies utilize water as a primary solvent, significantly reducing volatile organic compound (VOC) emissions during application. Regulatory pressures from the US EPA drive adoption of water-based systems in architectural and automotive film production.
- UV-Curable:UV-curable adhesives polymerize rapidly upon exposure to ultraviolet light, enabling high-speed production lines and solvent-free processing. Manufacturers in Japan leverage UV-curable solutions for precision bonding in semiconductor and optical film assembly.
- Solvent-Based:Solvent-based adhesives offer strong initial tack and adhesion, traditionally used in demanding industrial applications.
- Radiation-Curable:Radiation-curable technologies, including electron beam, provide rapid curing and high cross-linking density for durable film properties.
- Hot Melt:Hot melt adhesives are thermoplastic polymers applied in a molten state, delivering quick setting times for various packaging and assembly tasks.
Water-based and UV-curable technologies are expanding most quickly, driven by environmental compliance and production efficiency gains.
Application:
Specific application requirements dictate the performance characteristics and material specifications for protective films.
- Consumer Electronics:Films for consumer electronics protect sensitive screens and casings from scratches and impact during manufacturing, transit, and consumer use. High aesthetic standards and short product lifecycles in China's smartphone manufacturing hubs necessitate high-clarity, residue-free films.
- Aerospace Components:Aerospace components require films that withstand extreme temperatures, UV radiation, and chemical exposure, protecting critical surfaces during assembly and flight. The FAA's stringent material requirements for aircraft parts ensure only certified films are deployed on sensitive exterior and interior surfaces.
- Furniture Surfaces:Protective films for furniture surfaces prevent damage from handling and transport, maintaining aesthetic quality for retail display.
- Industrial Equipment:Industrial equipment applications demand robust films that shield machinery panels and displays from abrasion, chemicals, and workshop debris.
- Custom Fabrication:Custom fabrication leverages specialized films tailored to unique geometries and material sensitivities for bespoke protective solutions.
Consumer electronics applications continue to drive significant volume, while aerospace components command premium pricing for specialized films.
End User:
End-user segments exhibit distinct procurement patterns and demand specific service levels from film suppliers.
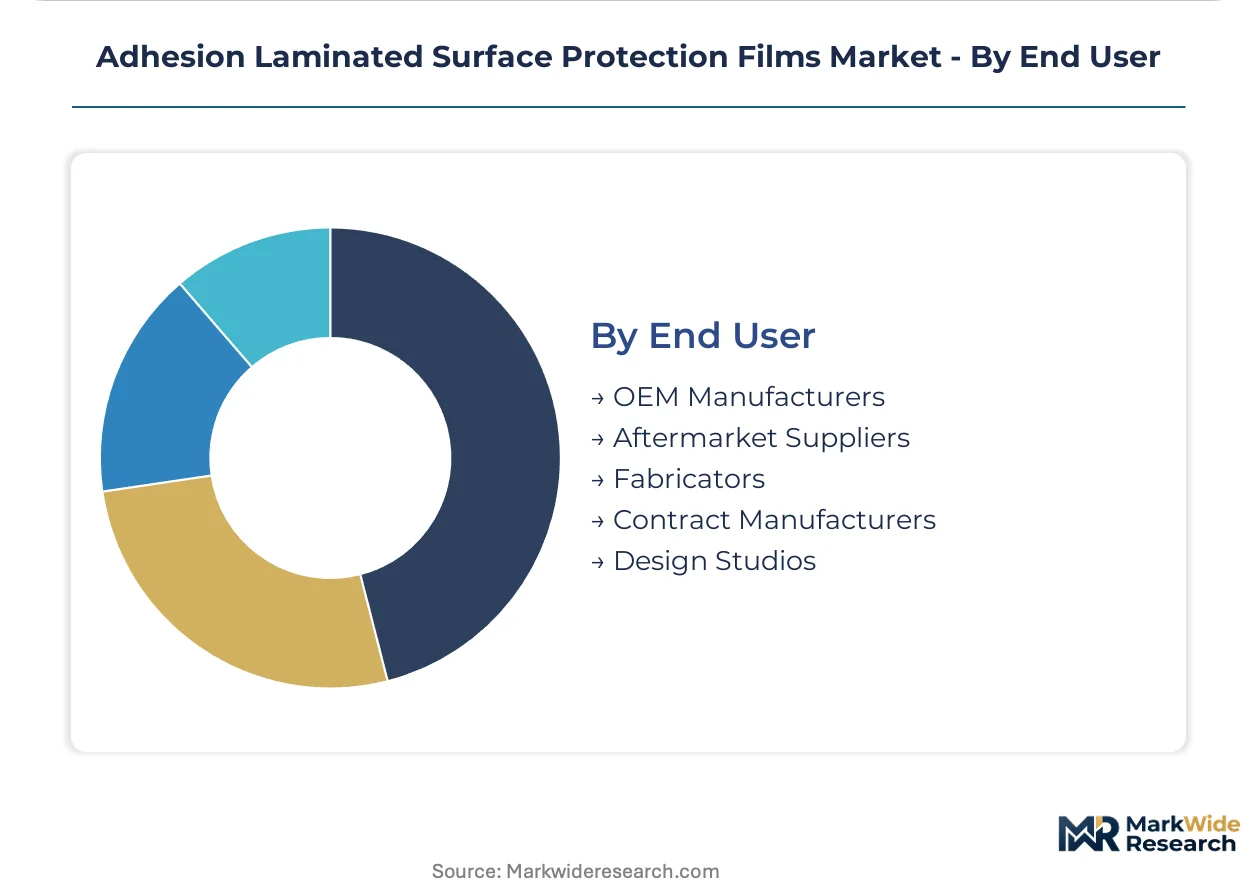
- OEM Manufacturers:Original Equipment Manufacturers (OEMs) integrate protection films directly into their production lines for new products, requiring consistent quality and just-in-time delivery. Automotive OEMs in Germany and Japan procure large volumes of films for protecting vehicle components during assembly and shipping.
- Aftermarket Suppliers:Aftermarket suppliers provide protective films for post-purchase installation or replacement, focusing on ease of application and broad compatibility. Demand from aftermarket channels in the United States includes DIY screen protectors and automotive paint protection films.
- Fabricators:Fabricators use protective films during cutting, drilling, and shaping of materials to prevent surface damage before final assembly.
- Contract Manufacturers:Contract manufacturers apply protection films to components and sub-assemblies, ensuring product integrity through complex supply chains.
- Design Studios:Design studios use protective films for prototyping and showcasing sensitive materials, preserving aesthetic intent during conceptualization.
OEM manufacturers represent the largest volume segment, with aftermarket suppliers demonstrating strong growth in consumer-facing solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market for adhesion laminated surface protection films exhibits a geographic concentration where specialized manufacturing capabilities converge. Key production hubs often align with major end-use manufacturing clusters, driving localized demand for high-performance films. This dynamic shapes regional market development and material compliance requirements.
South Korea
South Korea drives strong demand for PET films in high-resolution display protection and advanced electronics manufacturing. The country's stringent manufacturing standards ensure product quality for delicate components. Advanced manufacturing clusters in regions like Gyeonggi Province lead in developing and consuming these specialized films.
United States
The United States sees significant demand from aftermarket suppliers and the aerospace sector for protective films. EPA guidelines on volatile organic compounds influence adhesive formulation, favoring water-based and UV-curable technologies. Aerospace manufacturing hubs in states like Washington and California require highly certified films for critical components.
Germany
Germany's automotive industry drives substantial demand for protective films, particularly for interior display panels and headlamp lenses. EU regulations like REACH and RoHS dictate material choices, steering towards compliant polymer films. Automotive manufacturing centers in Bavaria and Baden-Württemberg integrate these films during vehicle assembly and transit.
China
China's vast consumer electronics manufacturing base creates immense demand for high-clarity, residue-free protective films. The country's GB standards and MEE regulations influence the chemical composition of adhesives and polymer substrates. Smartphone manufacturing hubs in the Pearl River Delta region require these films for screens and casings.
Japan
Japan's advanced semiconductor and optical film assembly industries generate specific demand for UV-curable and precision bonding films. METI initiatives support innovation in high-performance materials and advanced manufacturing processes. Technology clusters in regions like Kansai specialize in developing and applying these complex protective solutions.
Adhesion Laminated Surface Protection Films Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the adhesion laminated surface protection films market. The market structure exhibits a tiered consolidation, with a few large, diversified materials science companies alongside specialized niche players. Strategic archetypes include integrated materials giants, specialized film manufacturers, and regional converters. Portfolio diversification and strategic partnerships represent dominant competitive moves among these participants.
On the premium-tier vector, 3M leverages its broad materials science portfolio, exemplifying an integrated materials giant with diverse industrial applications across many geographies. Nitto Denko Corporation, a Japan-based entity, represents a specialized film manufacturer focused on advanced optical films for electronics, particularly in Asian markets. Saint-Gobain Performance Plastics, a global corporation, occupies a position among high-performance solution providers, catering to demanding sectors like aerospace components with certified solutions. These players collectively anchor different segments of the market.
| Leading Market Players |
|---|
| Tesa SE |
| Saint-Gobain Performance Plastics |
| 3M |
| Henkel Corporation |
| Intertape Polymer Group |
| Nitto Denko Corporation |
| LINTEC Corporation |
| E. I. du Pont de Nemours and Company |
| Avery Dennison Corporation |
| Others |
Cost & Logistics Intelligence
The shift from solvent-based to water-based adhesives reshapes supply geography towards compliant raw material sources, influencing film pricing economics. This transformation requires new manufacturing capabilities and impacts the cost structures for film producers.
Pricing Analysis
EU's RoHS directive dictates the pricing tier structure for adhesion laminated surface protection films, emphasizing compliant materials. Pricing stratifies across premium, standard, and economy tiers, driven by certification level for aerospace components and optical clarity for display applications. Pricing softness impacts standard-grade films due to raw material price volatility, particularly PET and PE. OEM manufacturers prioritize consistent quality and long-term contracts, while aftermarket suppliers exhibit higher price sensitivity for consumer-facing solutions.
Supply Chain Analysis
Managing inventory and lead times for high-clarity films proves challenging due to specialized production requirements. Supply concentrates in South Korea for electronics-grade films and Germany for automotive applications. The supply chain relies heavily on petrochemical-derived PET and PE base materials, along with advanced water-based and UV-curable adhesives. Raw material price volatility presents a significant structural risk. Distribution runs through direct channels to OEM manufacturers and specialized kitting services for aerospace and medical sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The adhesion laminated surface protection films market is entering a cyclical recovery phase, driven by renewed consumer electronics demand following product refresh cycles.
For Market Incumbents:Fortify core market positions by investing in advanced multi-layer co-extrusion technology, delivering thinner films with integrated functions. Deepen vertical integration into specialized adhesive production, particularly for water-based and UV-curable formulations, to mitigate raw material price volatility. This strategy counters the long-term threat of substitute surface hardening treatments. Prioritize certification investment for niche, high-consequence applications like aerospace components.
For New Entrants and Emerging Players:The demand for pre-cut, application-specific kits represents a service-layer gap where incumbents under-serve. Target this white space by offering precision die-cutting and just-in-time inventory services, especially for the medical device sector. Focus on functional film integration, such as anti-microbial or self-healing properties, for public touchscreens and medical equipment. The medical device packaging segment offers the most penetrable entry point through specialized service offerings.
For Investors and Strategic Acquirers:The market sits at a mid-growth phase that favors specialized film manufacturers with strong R&D capabilities in compliant materials. This sector exhibits strong long-term viability over the next 5-10 years, driven by escalating performance demands and regulatory shifts. Acquisition targets should include niche players possessing proprietary water-based adhesive formulations or advanced multi-layer co-extrusion expertise. The signal to watch is increasing M&A activity among regional converters specializing in application-specific kitting.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Water-Based Adhesive R&D | Accelerates compliance with EPA VOC guidelines for automotive and architectural applications. |
| Expand Multi-Layer Co-Extrusion Capacity | Enables production of thinner, multi-functional films for compact consumer electronics devices. |
| Pursue Aerospace Certification for New Films | Unlocks premium pricing and high-margin opportunities for critical aircraft component protection. |
| Develop Pre-Cut Kitting Services | Addresses end-user demand for waste reduction and streamlined assembly in medical device manufacturing. |
| Integrate Anti-Microbial Functionality | Creates new value propositions for public touchscreens and medical equipment surfaces. |
Research Approach
The analysis maps consumer electronics, automotive, and medical device sub-sectors, each validated through primary interviews with R&D directors, procurement leads, and regulatory compliance officers. This primary research was cross-referenced with extensive secondary data, including company annual reports, industry association publications, and regulatory body guidelines from EPA and REACH. Bottom-up data aggregation and top-down market sizing ensured comprehensive triangulation.
Outputs were consistently validated against external benchmarks and historical market trends across the analysis window. The analytical framework modeled segmentation dimensions including product type, adhesive technology, application, end-user, and regional manufacturing clusters. Compound Annual Growth Rates were derived from a blend of historical performance and projected demand drivers. Key forecast inputs included consumer electronics production volumes and automotive interior display growth rates.
Forecasts assume regulatory continuity in EU, US, and China regimes; material policy shifts would require re-modeling. These projections reflect current market assumptions, but unforeseen raw material supply disruptions or accelerated adoption of substitute technologies pose risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Silicone Solutions Market
Specialty Materials
Conductive Carbon Black Market
Specialty Materials
Sulphur Bentonite Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Absorbent Booms and Socks Market
Specialty Materials
Global Liquid Crystal Polymer (LCP) Films and Laminates Market
Specialty Materials
Plastic Dielectric Films Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Engineered Foam Market
Specialty Materials
Semiconductor O-Rings Market
Specialty Materials
Magnesium Fluoride Market
Specialty Materials
Epoxy Encapsulation Material Market
Specialty Materials
Barium Fluoride Market
Specialty Materials
Dysprosium Oxide Sputtering Target Market
Specialty Materials
Metallised Polyester Films Market