
 Carbon Mold Market | 2026-2036
Carbon Mold Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Mold Market Intelligence
China is fragmenting as new carbon fiber prepreg capacity comes online in Jiangsu and Jilin provinces. Toray Industries sustains technology leadership through proprietary PAN-based precursor systems. Hexcel Corporation anchors North American supply with integrated carbon fiber-to-composite capabilities. Mitsubishi Chemical Group competes via backward integration into pitch-based fiber production.
Carbon molds are precision tooling systems machined from high-stiffness carbon fiber reinforced polymer or isotropic graphite, engineered to withstand repeated thermal cycling above 180°C while maintaining dimensional tolerances within 0.05 mm for composite part fabrication. Aerospace applications dominate value capture due to qualification barriers and long-term OEM contracts, while automotive resin transfer molding represents the fastest-expanding demand pool as EV platforms prioritize mass reduction. Tier-1 suppliers constitute the most concentrated buyer segment, with OEM direct procurement growing in satellite and defense programs.
EPA industrial emissions rules and REACH substance restrictions constrain binder chemistries and disposal protocols for carbon mold manufacturing. FAA certification requirements for aerospace tooling impose traceability standards that filter market access. Japan's METI carbon fiber recycling directives and China's GB standards for composite workplace safety add compliance layers. Stakeholders must monitor evolving automotive OEM specifications for recycled carbon content thresholds and align mold lifecycle strategies accordingly.
Market Dynamics
Carbon mold demand pivots on aerospace OEM qualification cycles and automotive EV platform ramp-ups, with supply-side concentration in Japanese PAN precursor technology and German precision machining clusters creating asymmetric pricing power.
Growth Catalysts
- EPA emissions standards:US aerospace manufacturers accelerate composite adoption to meet fuel efficiency mandates, driving qualified tooling procurement.
- EV platform mass reduction targets:Automotive OEMs specify carbon fiber structural battery enclosures, expanding resin transfer molding capacity.
- Japan's METI recycling directives:Closed-loop carbon fiber recovery mandates stimulate mold refurbishment services and secondary material tooling.
Market Restraints
- Precursor supply concentration:Toray Industries and Mitsubishi Chemical control PAN and pitch-based fiber feedstocks, constraining independent mold fabricators.
- REACH substance restrictions:ECHA limitations on epoxy hardeners and release agents force formulation reformulation and qualification delays.
- Steel mold substitution:High-volume automotive applications below 150°C service temperature revert to hardened steel for cost-sensitive programs.
Strategic Opportunities
- India PLI scheme for composites:Domestic aerospace and defense manufacturing incentives create greenfield tooling demand outside established supply corridors.
- Digital twin integration:Convergence of in-situ thermal monitoring and predictive maintenance software enables mold-as-a-service business models.
- China GB workplace safety standards:Composite fabrication facility upgrades mandate precision tooling investments in Jiangsu and Shandong provinces.
Industry Challenges
- FAA certification timelines:Aerospace tooling traceability requirements extend qualification cycles to 18-24 months, freezing working capital.
- Specialized CNC machining workforce:Isotropic graphite and CFRP machining expertise concentrates in Stuttgart and Nagoya, creating recruitment bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Mold Market |
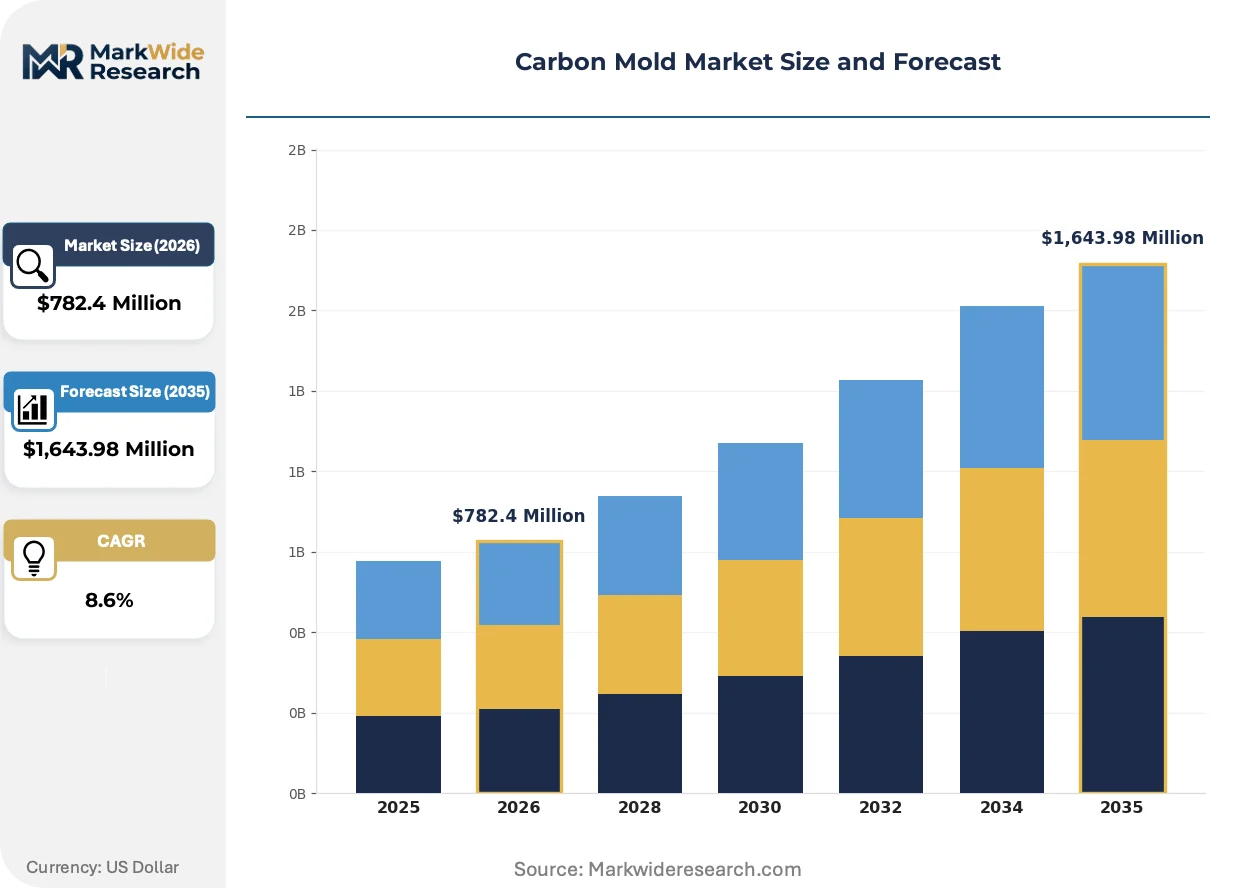
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,643.98 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Resin Transfer, Vacuum Infusion, Compression Molding Application: Aerospace, Automotive, Consumer Goods, Industrial End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Research Institutions Technology: 3D Printing, CNC Machining, Hand Layup, Automated Fiber Placement |
| Companies Covered | MDC Mould & Plastic Co, Ltd, DEXCRAFT, Mouldbox, Toray Industries Inc., Hexcel Corporation, Teijin Limited, Mitsubishi Chemical Group, SGL Carbon, Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Mold Market Strategic Shifts & Innovations
Additive manufacturing of mold inserts and heating elements is compressing lead times while reshaping traditional subtractive fabrication economics. Three developments dominate competitive positioning.
Continuous fiber 3D printing with in-situ consolidation enables conformal cooling channels and integrated heating elements in single-build mold components. Tier-1 automotive suppliers in Bavaria and aerospace contractors in Toulouse are qualifying these hybrid molds for sub-500 unit production runs. The technology is rendering obsolete conventional gun-drilled steel cooling plates in low-to-medium volume composite applications.
REACH authorization requirements for diisocyanates and specific epoxy curatives are forcing mold manufacturers toward bio-based binder systems and water-based release agents. ECHA sunset dates for legacy chemistries compress reformulation windows to 24 months. German automotive supplier corridors face the steepest compliance costs, with mold specifications now requiring full substance disclosure to OEM sustainability scorecards.
Direct long-term contracting between aerospace primes and mold fabricators is displacing tier-1 supplier intermediation for satellite and defense programs. Boeing and Lockheed Martin now specify tooling suppliers in source-controlled procurement agreements, bypassing traditional distributor networks. This pattern concentrates most visibly in Colorado and California defense manufacturing clusters, where security-cleared mold shops capture multi-year program commitments.
Carbon Mold Market Segmentation
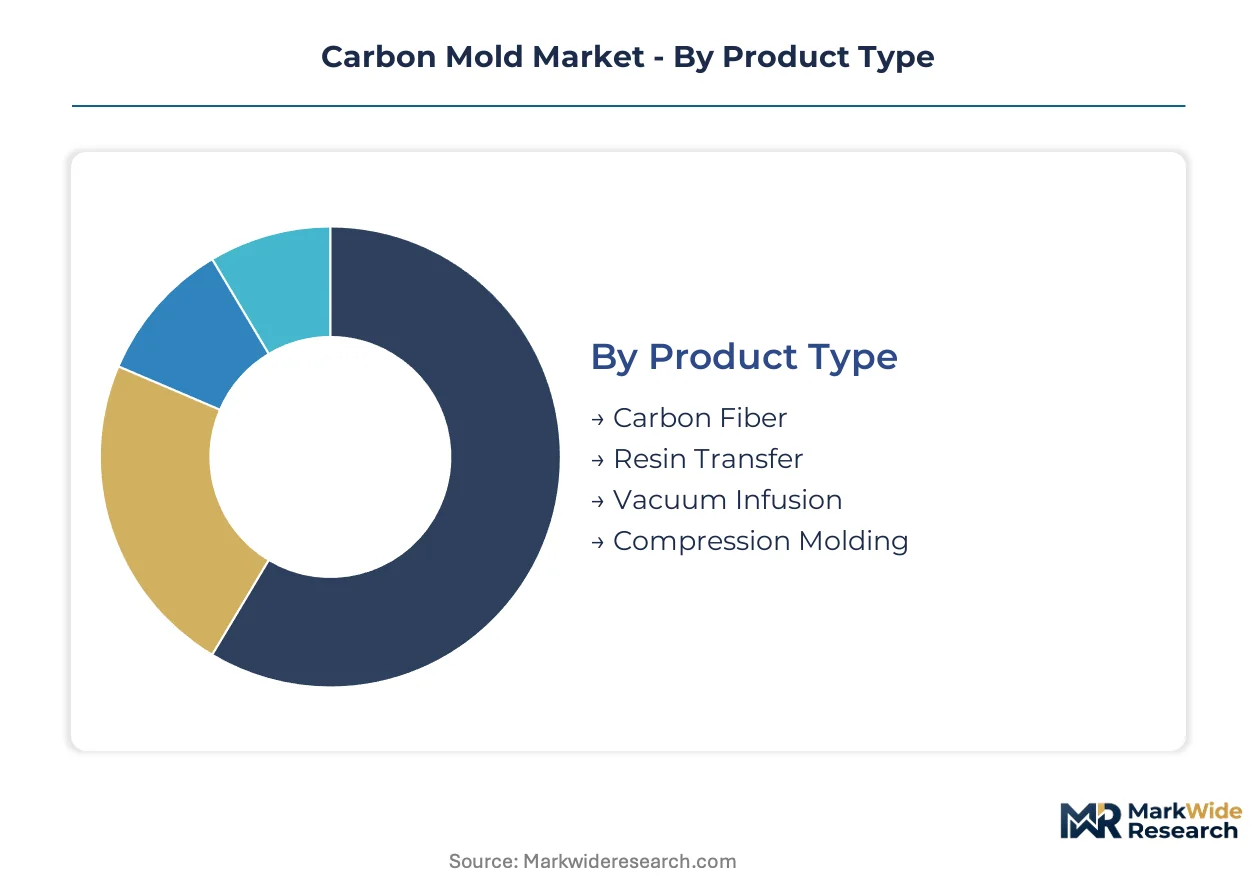
Carbon mold procurement patterns diverge sharply across manufacturing technologies and end-use qualification requirements. OEM specification hierarchies create distinct performance tiers that reshape supplier positioning and investment priorities.
Product Type:
Mature processes dominate installed capacity while emerging formats reshape capital allocation timelines for composite fabricators.
- Carbon Fiber:PAN-based and pitch-based fiber architectures deliver stiffness-to-weight ratios exceeding 150 GPa/(g/cm³). Aerospace prime contractors in the US and Germany specify these molds for wing spar and fuselage monocoque fabrication, with qualification cycles locking in multi-year supply agreements.
- Resin Transfer Molding:Closed-cavity injection systems achieve fiber volume fractions above 60% with cycle times under 15 minutes. Automotive EV battery enclosure programs in Germany's supplier corridor are scaling RTM capacity fastest, driven by platform mass reduction mandates.
- Vacuum Infusion:Single-sided tooling with vacuum-assisted resin distribution suits wind turbine blade and marine hull production. Lower capital barriers attract mid-volume fabricators in China's Jiangsu province.
- Compression Molding:Matched-die configurations process thermoplastic composites at sub-5 minute cycles. Consumer electronics chassis and industrial equipment housings in Japan's precision manufacturing clusters concentrate demand.
Carbon fiber handles the majority of throughput; resin transfer molding is expanding most quickly on share.
Application:
Cost tier stratification separates qualification-intensive aerospace programs from price-sensitive industrial tooling.
- Aerospace:FAA-certified tooling for primary structure fabrication demands traceability documentation across 50+ process parameters. Boeing and Airbus supply chains in Washington state and Toulouse lock in 18-24 month qualification horizons.
- Automotive:EV platform structural components—battery trays, floor pans, roof assemblies—specify carbon molds for volumes between 5,000-50,000 units annually. German OEMs lead specification development.
- Consumer Goods:Sporting equipment and luxury goods leverage aesthetic carbon weave visibility with relaxed dimensional tolerances. Italian and Japanese sporting goods manufacturers drive seasonal procurement cycles.
- Industrial:Robotics end-effectors and semiconductor handling equipment prioritize isotropic thermal stability. South Korean and Taiwanese electronics capital equipment suppliers concentrate demand.
Aerospace commands premium pricing; automotive is climbing the fastest on volume contribution.
End User:
Customer type determines contract structure, with direct OEM engagement displacing traditional distributor intermediation in defense and satellite programs.
- OEMs:Prime contractors in US defense and European satellite manufacturing now specify mold suppliers directly, bypassing tier-1 intermediaries. Source-controlled procurement agreements concentrate in Colorado and California clusters.
- Tier-1 Suppliers:Automotive and aerospace subcontractors aggregate demand across multiple OEM platforms, capturing scale economies in mold refurbishment and lifecycle management services.
- Aftermarket Providers:Repair and replacement tooling for legacy aircraft programs and industrial equipment sustains niche fabrication shops with lower qualification barriers.
- Research Institutions:National laboratories and university composites centers pilot novel mold materials and heating element integration, feeding technology transfer to commercial fabricators.
Tier-1 suppliers manage the broadest mold portfolios; OEMs are gaining share fastest through direct contracting.
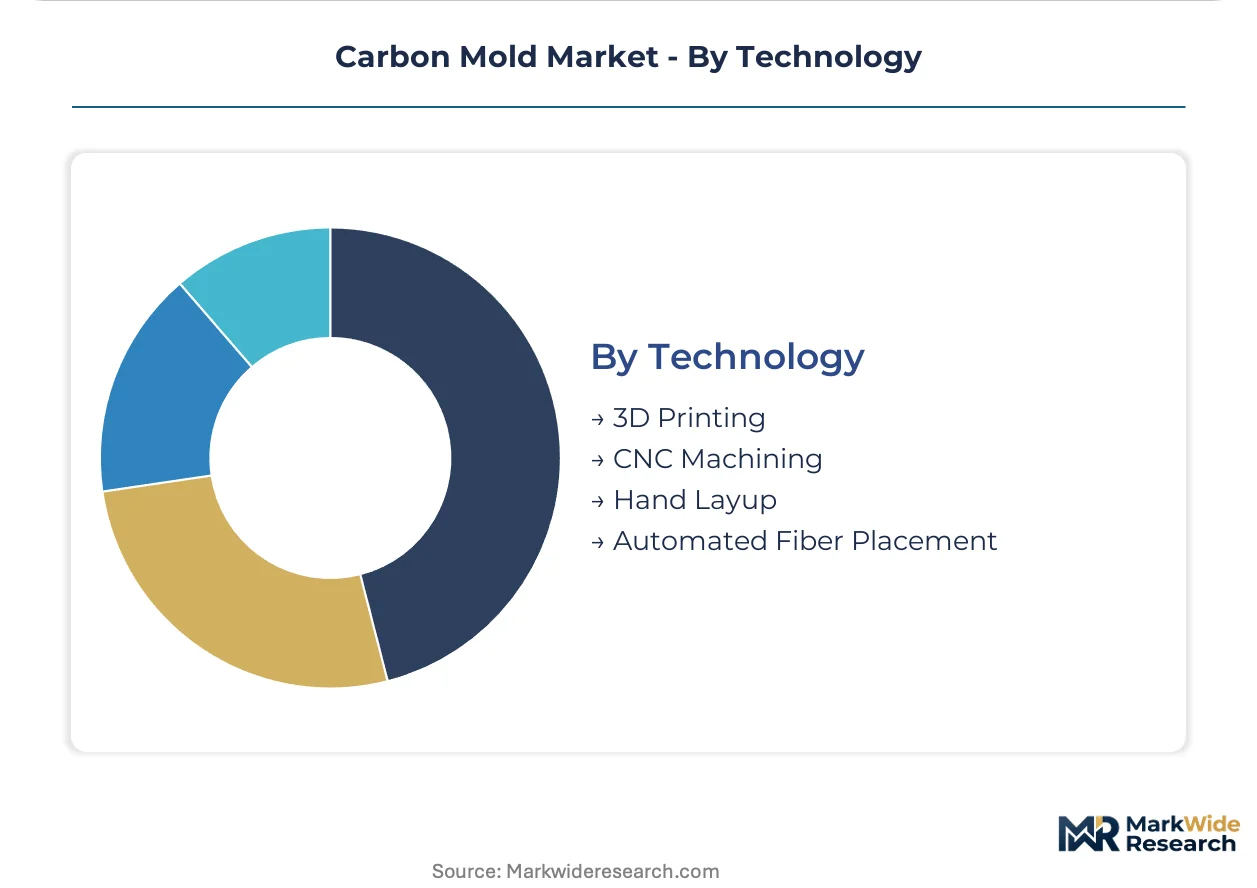
Technology:
Volume throughput separates automated production formats from craft-dependent fabrication.
- 3D Printing:Continuous fiber fused deposition with in-situ consolidation enables conformal cooling channels and integrated heating elements. Bavarian automotive suppliers qualify hybrid molds for sub-500 unit production runs.
- CNC Machining:Five-axis milling of isotropic graphite and CFRP blocks achieves surface finishes below 0.8 Ra. Stuttgart and Nagoya machining clusters face persistent workforce recruitment constraints.
- Hand Layup:Manual fiber placement with vacuum bag consolidation suits prototype and custom yacht tooling. Italian and Turkish marine fabricators sustain this format despite labor intensity.
- Automated Fiber Placement:Robotic tow deposition achieves deposition rates exceeding 50 kg/hour for aerospace fuselage sections. Boeing and Airbus tier-1 suppliers in Kansas and Hamburg anchor equipment utilization.
CNC machining handles the majority of precision tooling output; 3D printing is gaining share fastest in low-volume hybrid applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PAN precursor technology concentrates in Japanese chemical conglomerates, while precision machining capabilities cluster in German industrial corridors. Aerospace qualification cycles and automotive EV ramp-ups are redrawing procurement maps across four demand centers.
United States
FAA certification requirements for aerospace tooling extend qualification cycles to 18-24 months, freezing working capital for fabricators. EPA emissions standards accelerate composite adoption for fuel efficiency mandates. Colorado and California defense manufacturing clusters concentrate source-controlled procurement agreements between primes and mold suppliers.
Germany
REACH substance restrictions on epoxy hardeners force formulation reformulation across automotive supplier corridors. ECHA sunset dates compress compliance windows to 24 months. Bavaria hosts tier-1 suppliers scaling resin transfer molding capacity for EV battery enclosure programs.
Japan
METI carbon fiber recycling directives stimulate mold refurbishment services and secondary material tooling demand. JIS standards govern precision machining tolerances for isotropic graphite components. Nagoya machining clusters face persistent workforce recruitment constraints for five-axis CFRP milling expertise.
China
GB standards for composite workplace safety mandate facility upgrades in Jiangsu and Shandong provinces. MIIT industrial policy directs capacity expansion toward domestic aerospace and defense manufacturing. New carbon fiber prepreg capacity in Jiangsu and Jilin provinces is fragmenting supply-side concentration.
India
PLI scheme incentives for domestic aerospace and defense manufacturing create greenfield tooling demand outside established supply corridors. BIS certification requirements for industrial equipment impose quality benchmarks on mold imports. Maharashtra and Karnataka are emerging as fabrication hubs for precision composite components.
Carbon Mold Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in precursor and fiber production. The vendor base stratifies across three tiers: chemical conglomerates controlling PAN and pitch-based feedstocks, precision machining houses with aerospace qualification credentials, and regional fabricators serving automotive and industrial segments. Two strategic archetypes dominate: backward-integrated material suppliers and specialist tooling shops with security clearance access. Competitive moves concentrate on capacity expansion in high-growth corridors and technology licensing agreements to bypass qualification barriers.
Within the chemical conglomerate tier, Toray Industries and Mitsubishi Chemical Group anchor feedstock supply through proprietary precursor systems. Hexcel Corporation occupies a position bridging North American carbon fiber production with integrated composite capabilities. These three exemplify how upstream control over PAN-based and pitch-based architectures constrains independent mold fabricators while securing multi-year OEM contracts.
| Leading Market Players |
|---|
| MDC Mould & Plastic Co, Ltd |
| DEXCRAFT |
| Mouldbox |
| Toray Industries Inc. |
| Hexcel Corporation |
| Teijin Limited |
| Mitsubishi Chemical Group |
| SGL Carbon |
| Solvay S.A. |
| Others |
Cost & Logistics Intelligence
Shanghai-to-Hamburg container freight corridors transmit cost volatility from PAN precursor producers to precision machining clusters, amplifying price spreads between aerospace-qualified tooling and automotive production molds while compressing margins for independent fabricators lacking long-term OEM offtake agreements.
Pricing Analysis
REACH authorization timelines dictate the pricing tier structure across the European supplier base, separating FAA-certified aerospace tooling with full traceability documentation from standard industrial molds. Three-tier pricing structure across premium certification, qualified production, and general industrial levels reflects qualification investment recovery and raw material grade differentiation. Cost compression in automotive resin transfer molding intensifies as German OEMs consolidate supplier panels and demand volume-based rebates. Tier-1 automotive subcontractors exhibit highest price sensitivity due to fixed OEM contract terms, while defense primes accept premium positioning for security-cleared fabrication capabilities.
Supply Chain Analysis
Toray Industries and Mitsubishi Chemical anchor precursor supply through captive PAN and pitch-based fiber production, constraining independent mold fabricators without backward integration into feedstock supply. Raw material flows concentrate through Japan, Germany, and China's Jiangsu province, drawing from isotropic graphite blocks, epoxy resin systems, and release agent chemistries. Single-source vulnerability in aerospace-qualified carbon fiber grades creates procurement risk for tier-1 suppliers locked into long-term OEM qualification cycles. Distribution runs through direct contracting between primes and certified fabricators in defense and satellite programs, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon mold procurement is accelerating through a technology inflection as continuous fiber 3D printing compresses lead times for sub-500 unit production runs, disrupting traditional five-axis machining economics and enabling mold-as-a-service business models.
For Market Incumbents: Pre-empt additive manufacturing displacement by qualifying hybrid mold formats with integrated conformal cooling before tier-1 automotive suppliers complete their own validation programs. Secure long-term precursor supply agreements with Toray Industries or Mitsubishi Chemical to defend against feedstock allocation constraints during capacity expansion phases. Invest in security clearance infrastructure to capture direct sourcing relationships with Boeing and Lockheed Martin defense programs.
For New Entrants and Emerging Players: Pursue mold refurbishment and secondary material tooling services stimulated by Japan's METI recycling directives, where qualification barriers are lower and customer relationships are less entrenched. Target India's PLI scheme corridors in Maharashtra and Karnataka for greenfield fabrication capacity, leveraging domestic aerospace manufacturing incentives outside established German and Japanese supply clusters. Lead with digital twin integration and predictive maintenance software to differentiate from capital-intensive machining incumbents.
For Investors and Strategic Acquirers: Specialist tooling shops with FAA certification credentials and established aerospace prime relationships represent the most defensible acquisition targets within a five-to-ten year horizon. Monitor ECHA sunset date compliance progress as a signal for consolidation pressure on German automotive supplier corridor fabricators facing reformulation cost burdens. Watch India PLI scheme disbursement velocity as an indicator of greenfield demand creation outside legacy manufacturing clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Toray Industries' PAN-based systems demonstrate how feedstock control secures multi-year OEM contracts against allocation risk. |
| Continuous Fiber 3D Printing Qualification | Bavarian automotive suppliers validate hybrid molds with conformal cooling channels for sub-500 unit production runs. |
| Security Clearance Infrastructure Investment | Colorado and California defense clusters concentrate source-controlled procurement agreements bypassing tier-1 intermediaries. |
| Digital Twin Platform Development | In-situ thermal monitoring convergence enables predictive maintenance and mold-as-a-service recurring revenue models. |
| India PLI Scheme Corridor Entry | Maharashtra and Karnataka fabrication hubs capture domestic aerospace and defense manufacturing incentives. |
Research Approach
Initial hypotheses were tested against primary input from aerospace tooling procurement managers, automotive tier-1 supplier engineering directors, precision machining facility operators, and carbon fiber precursor technical sales leads, then refined through secondary validation against FAA certification databases, ECHA substance restriction filings, METI recycling directive documentation, and customs trade flow records. Bottom-up demand modeling from individual OEM platform specifications was triangulated with top-down capacity assessments across Japanese, German, and Chinese production clusters.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation across manufacturing technology, application qualification tier, end-user contract structure, and regional regulatory cluster. CAGRs were derived from weighted average growth contributions across aerospace EV platform ramp-ups, automotive resin transfer molding capacity expansion, and closed-loop recycling mandate compliance. Forecast inputs incorporated PAN precursor capacity expansion timelines, CNC machining workforce availability in Stuttgart and Nagoya clusters, and REACH authorization sunset date compliance progress.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed composite fabricators or accelerated FAA qualification timeline compression would shift outcomes beyond modeled ranges. Quarterly review of ECHA substance restriction enforcement, India PLI scheme disbursement rates, and aerospace prime direct contracting announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Special Graphite Market
Specialty Materials
Europe Solar Control Window Films Market
Specialty Materials
Barium Fluoride Market
Specialty Materials
Middle East and Africa Anti-Friction Coatings Market
Specialty Materials
Dysprosium Oxide Sputtering Target Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
Melamine Foam Market
Specialty Materials
EVA Interlayer for Photovoltaic Market
Specialty Materials
Silicone Film Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Specialty Silica Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Global Flexible Substrates Market
Specialty Materials
Europe Microspheres Market
Specialty Materials
Specialty Silicone Market