
 Lab Grown Diamonds Market | 2026-2036
Lab Grown Diamonds Market Size, Share, and Industry Trends Forecast 2026-2036
Lab Grown Diamonds Market Intelligence
GIA diamond grading protocols for laboratory-grown stones is reorganizing competitive access across the value chain. De Beers leverages its Lightbox brand to anchor a distinct price-positioned tier separate from natural diamond portfolios. Diamond Foundry (VRAI) controls vertically integrated solar-powered production in the United States, while Brilliant Earth differentiates through blockchain traceability and ethical sourcing narratives.
Lab grown diamonds are synthetic crystalline carbon structures produced through high-pressure high-temperature or chemical vapor deposition methods, achieving identical optical, physical, and chemical properties to mined diamonds at controlled purity grades. These stones serve both ornamental applications requiring specific color and clarity grades and industrial functions demanding thermal conductivity or hardness. Monocrystalline product types occupy the premium jewelry segment where optical consistency commands higher margins, while chemical vapor deposition technology leads capacity expansion due to superior scalability and lower energy intensity relative to HPHT batch processing.
The Federal Trade Commission monitors labeling accuracy under revised jewelry guides, while ISO 18323 standards govern terminology separating synthetic from natural stones in international commerce. India's Bureau of Indian Standards and the Gemological Institute of America jointly influence how certification flows shape consumer trust and cross-border trade eligibility. Stakeholders must track evolving disclosure mandates and energy-source verification requirements as sustainability claims become enforceable market-access criteria.
Market Dynamics
The lab grown diamonds market is undergoing structural recalibration as chemical vapor deposition capacity expansion outpaces high-pressure high-temperature batch economics, forcing incumbents to reposition around energy sourcing and certification differentiation rather than scarcity premiums alone.
Growth Catalysts
- FTC Jewelry Guide Revisions:The Federal Trade Commission's allowance of "cultured" and "laboratory-grown" terminology without mandatory qualifiers reduces consumer confusion and accelerates retail adoption across United States bridal channels.
- ISO 18323 Harmonization:International standardization of synthetic diamond disclosure protocols streamlines cross-border certification flows and reduces regulatory friction for Indian cutting and polishing clusters supplying North American retailers.
- Monocrystalline CVD Scaling:Chemical vapor deposition reactors achieving larger single-crystal boules improve optical consistency for premium jewelry grades while lowering unit energy consumption relative to legacy HPHT presses.
Market Restraints
- Electricity Cost Volatility:CVD production facilities face margin compression from grid price fluctuations, particularly impacting operations in regions without captive renewable generation or long-term power purchase agreements.
- Natural Diamond Inventory Overhang:De Beers' controlled release of mined rough from Botswana and Russian state stockpiles maintains price floor pressure that constrains synthetic stone pricing power in bridal segments.
- Capital Intensity Barriers:Reactor equipment and cleanroom infrastructure requirements exceed $15 million per production line, limiting new entrant participation to well-capitalized industrial conglomerates or private equity-backed platforms.
Strategic Opportunities
- Blockchain Traceability Integration:Distributed ledger verification of carbon-neutral production claims creates premium positioning for United States-based manufacturers serving sustainability-motivated millennial and Gen Z bridal purchasers.
- Industrial Thermal Management Applications:High-purity synthetic substrates for semiconductor heat spreaders and quantum computing components open non-jewelry revenue streams with longer contract durations and less fashion-cycle exposure.
- India Bureau of Indian Standards Alignment:Early certification to BIS quality marks for laboratory-grown stones secures preferential access to domestic Indian jewelry manufacturing clusters and duty-advantaged export channels.
Industry Challenges
- Gemological Grader Talent Scarcity:The Gemological Institute of America's limited annual certification throughput for synthetic stone specialists creates bottlenecks in quality assurance staffing for scaling production facilities.
- Patent Thicket Navigation:Expiring and overlapping intellectual property claims around CVD reactor designs and diamond seed preparation generate litigation exposure and licensing cost uncertainty for equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab Grown Diamonds Market |
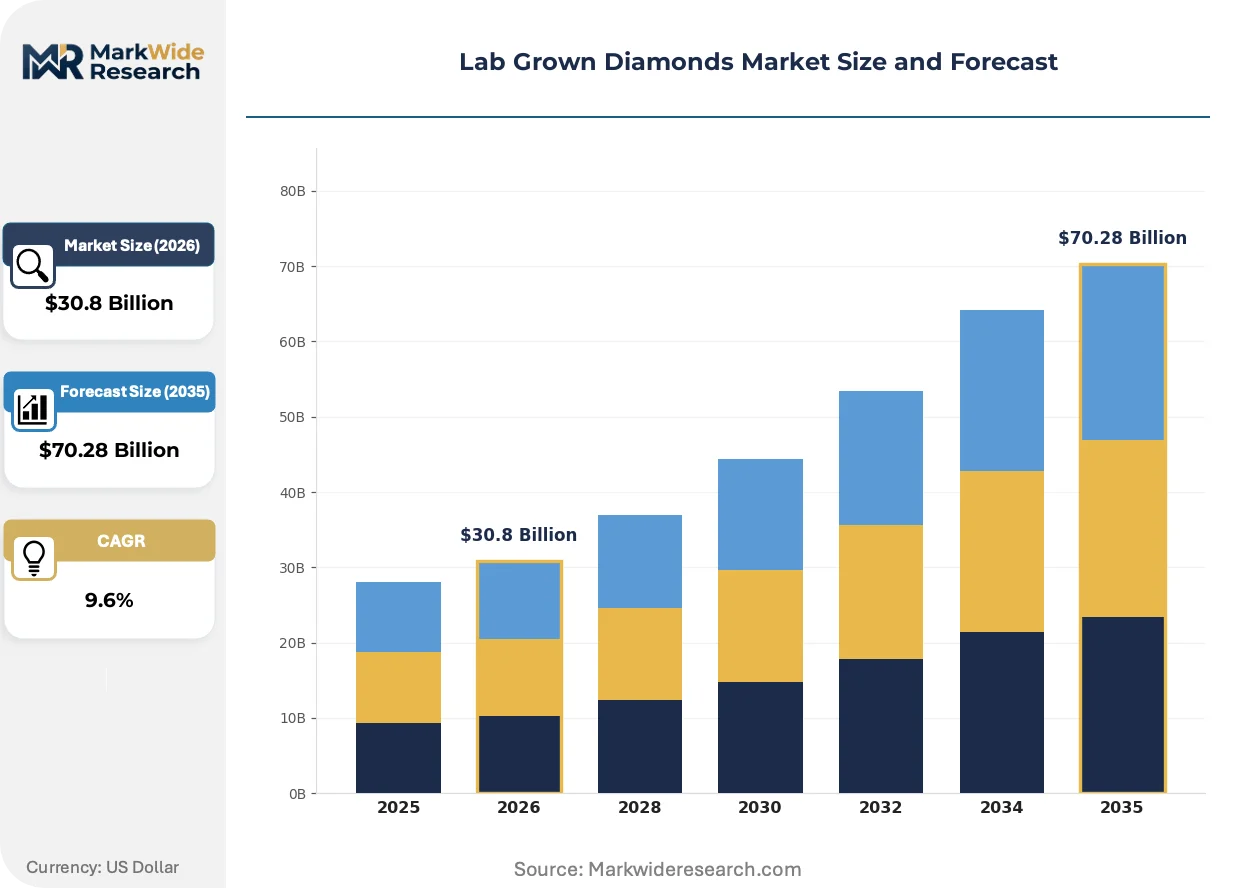
| Market Size in 2026 | $30.8 Billion |
| Market Size in 2035 | $70.28 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polychrystalline, Nanocrystalline, Polycrystalline Technology: High Pressure High Temperature, Chemical Vapor Deposition, Pulsed Laser Deposition, Microwave Plasma Application: Jewelry, Industrial Cutting, Electronics, Thermal Conductors, Optical Instruments End User: Manufacturers, Retailers, Electronics Producers, Research Institutes, Thermal Management Firms |
| Companies Covered | Adamas One, James Allen, De Beers, Trent (Pome), Diamond Foundry (VRAI), KIRA Diamonds, Blue Nile, Aurate, Brilliant Earth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab Grown Diamonds Market Strategic Shifts & Innovations
Production technology diversification is fragmenting competitive moats across the value chain, as reactor hardware improvements and renewable energy integration reshape cost structures faster than brand differentiation can solidify.
Plasma-enhanced chemical vapor deposition systems utilizing microwave frequency tuning are fragmenting the equipment supply landscape. Mid-scale jewelry manufacturers in the United States and India are adopting these reactors to bypass centralized foundry dependence. The technology is fragmenting regional production geography by enabling viable 500-carat-per-month operations outside traditional manufacturing clusters.
Europe's Corporate Sustainability Reporting Directive now mandates scope-three emissions disclosure for jewelry retailers above revenue thresholds, with downstream pressure flowing to diamond suppliers. This regulatory architecture forces synthetic producers to document energy sourcing or face exclusion from EU bridal supply chains. German and French luxury houses are responding by requiring supplier-specific carbon accounting verified to ISO 14064 standards.
Direct-to-consumer digital channels are compressing traditional wholesale-retail markups that historically sustained mined diamond distribution economics. United States-based bridal purchasers increasingly complete transactions through virtual try-on platforms with home sample programs, displacing brick-and-mortar consultation dependency. This behavioral shift concentrates marketing spend on social media influencer partnerships rather than legacy jewelry trade show presence.
Lab Grown Diamonds Market Segmentation
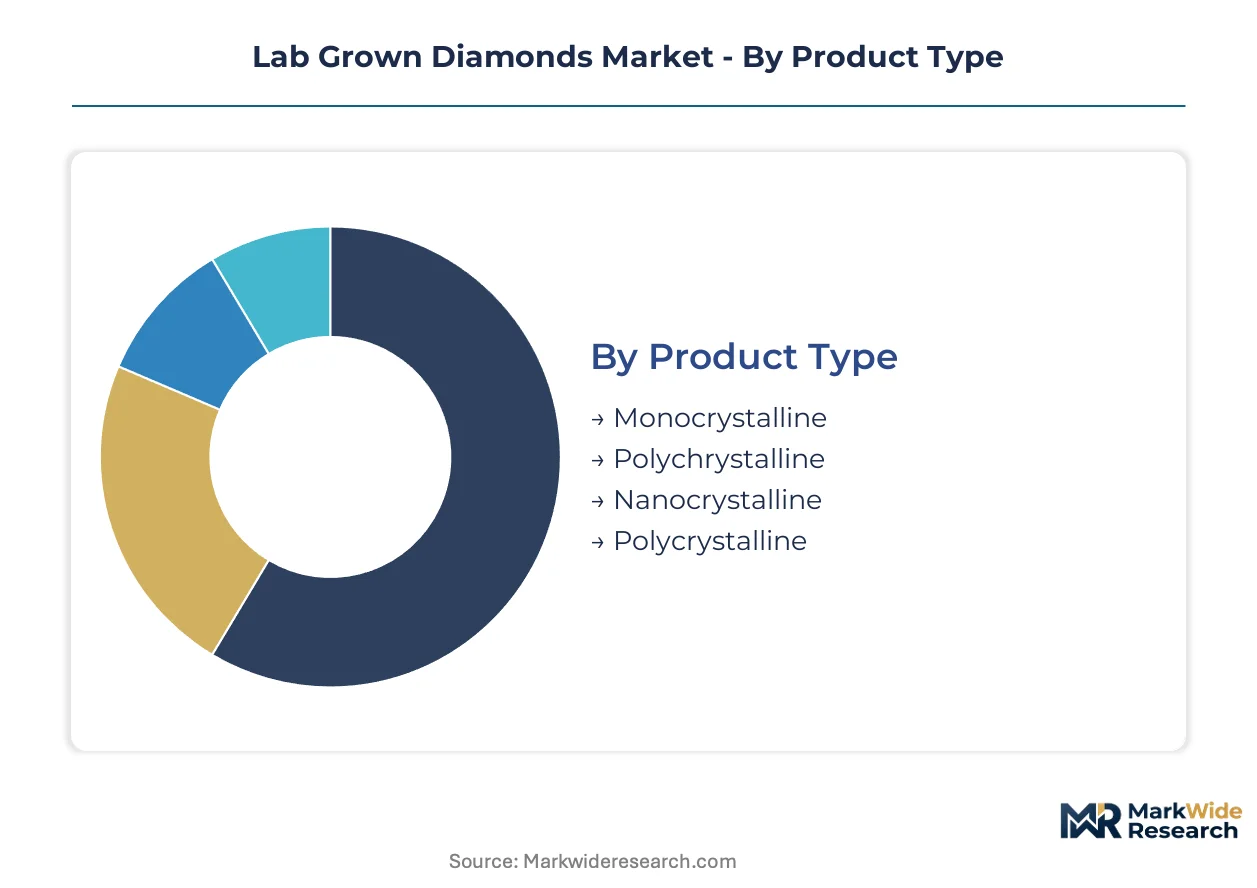
Segmentation in lab grown diamonds reveals where technological substitution pressure concentrates most intensely. Product purity grades and production methods determine which applications face imminent displacement from competing materials versus sustained premium positioning.
Product Type:
Substitution pressure from cubic zirconia and moissanite hits hardest at lower crystalline grades where optical differentiation collapses.
- Monocrystalline:Single-crystal structures with uniform lattice alignment deliver maximum optical clarity and thermal conductivity. Bridal jewelry demand in the United States concentrates here as GIA certification protocols validate premium positioning against natural stones.
- Polychrystalline:Aggregated crystal formations with grain boundaries suit industrial cutting tools and thermal spreaders where hardness trumps optical perfection. Electronics producers in Germany and Japan source these substrates for semiconductor heat management applications.
- Nanocrystalline:Ultra-fine grain structures under 100 nanometers enable specialized coatings and quantum sensing applications.
- Polycrystalline:Multi-crystal matrices balance cost and performance for abrasive and drilling tool manufacturers.
Monocrystalline anchors the volume base while nanocrystalline gains share at the steepest rate.
Technology:
Cost tier divergence separates batch-process legacy systems from continuous-flow reactor architectures.
- High Pressure High Temperature:Press-based crystallization using metal catalyst solvents achieves rapid diamond growth in discrete batches. Indian cutting clusters rely on HPHT output for melee-sized stones under 0.2 carats where throughput economics outweigh unit energy costs.
- Chemical Vapor Deposition:Gas-phase carbon deposition onto diamond seeds enables larger single-crystal boules with superior clarity control. United States producers leverage CVD scalability to serve direct-to-consumer bridal brands requiring consistent D-F color grades.
- Pulsed Laser Deposition:Ablation-based carbon transfer creates thin-film diamond coatings for optical and electronic substrates.
- Microwave Plasma:Enhanced CVD variants using resonant cavity excitation accelerate growth rates for specialized industrial grades.
Chemical vapor deposition dominates capital deployment while microwave plasma configurations climb the fastest.
Application:
Margin structure fragmentation splits ornamental from functional demand pools with diverging certification requirements.
- Jewelry:Ornamental stones graded by color, clarity, cut, and carat compete directly with mined diamonds in bridal and fashion segments. FTC labeling harmonization in the United States reduces consumer friction for laboratory-grown bridal purchases.
- Industrial Cutting:Abrasive grains and tool inserts exploit diamond hardness for machining composites and ceramics. German automotive suppliers specify synthetic diamond tooling for electric motor component fabrication.
- Electronics:High-purity substrates for RF devices and power semiconductors leverage thermal and electrical properties.
- Thermal Conductors:Heat spreader materials for LED and laser diode packaging.
- Optical Instruments:Transparent windows and lenses for high-power laser systems.
Jewelry anchors the volume base while electronics gains share at the steepest rate.
End User:
Customer type concentration determines pricing power through inventory risk allocation and specification stringency.
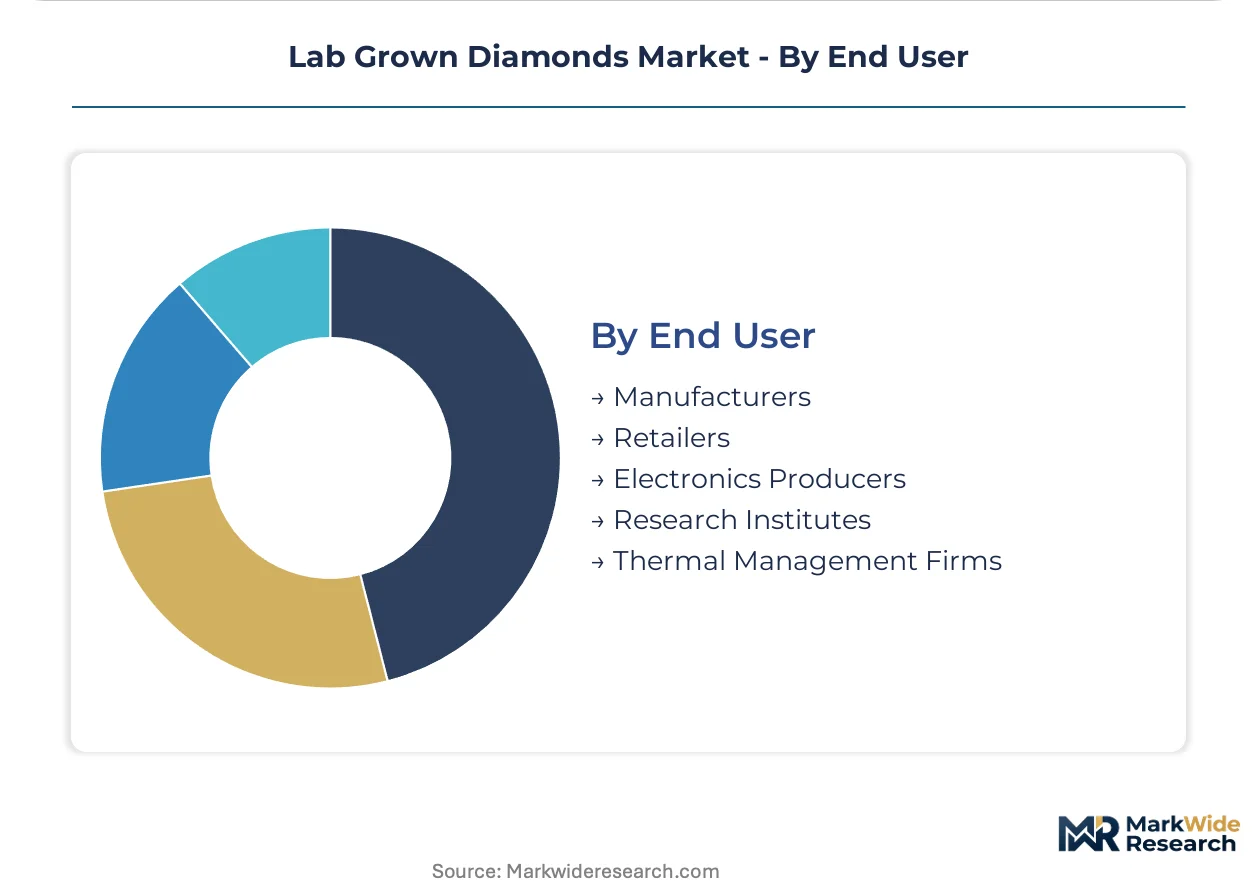
- Manufacturers:Cutting and polishing houses in Surat and Ahmedabad process rough into polished stones for downstream jewelry fabrication. India's Bureau of Indian Standards certification requirements shape procurement specifications for export-qualified output.
- Retailers:Bridal jewelry chains and independent stores stock certified stones with blockchain traceability documentation. United States direct-to-consumer platforms bypass wholesale tiers to capture margin compression benefits.
- Electronics Producers:Semiconductor and device manufacturers specify thermal and electrical performance metrics.
- Research Institutes:Academic and government laboratories procure specialized grades for quantum and materials science.
- Thermal Management Firms:Specialized suppliers integrating diamond substrates into heat dissipation systems.
Manufacturers anchor the volume base while electronics producers gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bridal jewelry purchasers in the United States drive volume concentration, while cutting and polishing clusters in India and production facilities in China supply the upstream pipeline. European luxury houses are mandating carbon-accounting documentation from synthetic diamond suppliers.
United States
Direct-to-consumer brands capture bridal demand through virtual try-on platforms and home sampling programs. The FTC's revised jewelry guides permit "cultured" and "laboratory-grown" labeling without mandatory qualifiers, reducing consumer friction at point of sale. Diamond Foundry operates solar-powered CVD production facilities serving domestic retail channels with blockchain-verified provenance claims.
India
Surat and Ahmedabad cutting houses process rough synthetic stones into polished melee under 0.2 carats for export-qualified jewelry manufacturing. The Bureau of Indian Standards collaborates with GIA to shape certification protocols that determine cross-border trade eligibility. HPHT batch economics dominate small-stone throughput for North American bridal supply chains.
China
Zhengzhou and Ningbo production clusters scale microwave plasma CVD reactors for industrial thermal management substrates and optical-grade jewelry stones. MIIT standards govern equipment manufacturing quality for reactor hardware exports. Domestic producers supply both semiconductor heat spreader markets and fashion jewelry channels with differentiated purity grades.
Germany
Automotive suppliers specify synthetic diamond tooling for electric motor component fabrication, creating industrial demand separate from ornamental applications. The Corporate Sustainability Reporting Directive mandates scope-three emissions disclosure from jewelry retailers above revenue thresholds, forcing supplier carbon accounting. Frankfurt and Munich-based luxury houses require ISO 14064-verified energy sourcing documentation from synthetic diamond vendors.
Belgium
Antwerp's historic diamond district now integrates laboratory-grown stone certification alongside natural diamond grading workflows. REACH regulations govern chemical handling in CVD reactor maintenance and seed preparation processes. The port city's logistics infrastructure enables re-export of Indian-polished synthetic stones to North American retail channels with consolidated documentation.
Lab Grown Diamonds Market Key Industry Players
Player mix skews toward vertically integrated producers with captive energy sourcing and direct-to-consumer retailers with blockchain traceability infrastructure. The vendor base separates into three tiers: mining conglomerates with synthetic sidelines, technology-driven pure-play manufacturers, and digital-native jewelry brands. Dominant competitive moves include renewable energy integration for production cost defense and strategic partnerships with gemological institutes for certification preferencing.
Within the mining-conglomerate tier, De Beers anchors a distinct price-positioned segment through its Lightbox brand, occupying a position separate from premium natural diamond portfolios. Among technology-driven pure-plays, Diamond Foundry and Brilliant Earth exemplify divergent archetypes—one controlling in-house solar-powered production, the other differentiating through ethical sourcing narratives and distributed ledger verification. These three companies represent the primary competitive anchors shaping how certification, energy provenance, and retail channel strategy define positioning.
| Leading Market Players |
|---|
| Adamas One |
| James Allen |
| De Beers |
| Trent (Pome) |
| Diamond Foundry (VRAI) |
| KIRA Diamonds |
| Blue Nile |
| Aurate |
| Brilliant Earth |
| Others |
Cost & Logistics Intelligence
CVD reactor scale economies in Zhengzhou and Surat concentrate manufacturing capacity among capital-intensive operators, compressing unit costs while anchoring price floors to electricity-indexed production contracts rather than scarcity premiums alone.
Pricing Analysis
Cost-plus contracts with electricity indexation dominate rough supply agreements between CVD producers and Indian cutting houses. Three-tier pricing structure across premium monocrystalline bridal grades, standard melee sizes, and industrial polychrystalline tiers reflects certification grade and energy provenance verification. Pricing pressure stems from De Beers' Lightbox positioning in the value tier, forcing synthetic specialists toward carbon-neutral differentiation. Retailers exhibit highest price sensitivity in sub-one-carat bridal segments, while electronics producers accept premium thermal-grade pricing for quantum substrate applications.
Supply Chain Analysis
Strategic stockpiling of diamond seeds and metal catalyst solvents prevails over just-in-time approaches given reactor batch continuity requirements. Supply concentrates in China, India, and the United States, with raw material dependencies on high-purity methane gas, specialized reactor components from German equipment manufacturers, and GIA-certified grading labor. Single-source vulnerability in microwave generator supply creates chokepoint exposure for CVD capacity expansion. Distribution runs through Antwerp certification hubs for re-export to North American retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as millennial and Gen Z bridal purchasers split demand across sustainability-verified, price-accessible, and heritage-brand segments, creating defendable niches for differentiated positioning.
For Market Incumbents: Consolidate reactor capacity in captive renewable energy zones to defend margins against grid-price volatility. Acquire GIA-certified grading capacity to reduce certification bottlenecks. Lock long-term power purchase agreements before electricity cost escalation accelerates. For New Entrants and Emerging Players: Lead with blockchain-verified carbon-neutral production claims targeting EU luxury supply chains under CSRD disclosure mandates. Target German automotive thermal management applications where specification stringency limits incumbent pivot speed. Partner with direct-to-consumer platforms bypassing wholesale markup compression. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors solar-integrated CVD operators with in-house seed preparation capabilities over HPHT-dependent legacy assets. Five-to-ten year viability hinges on industrial electronics diversification beyond bridal cyclicality. Watch for BIS-GIA certification harmonization as inflection signal for Indian export channel access.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Integration | Solar-powered CVD production secures margin defense against electricity volatility in grid-dependent regions. |
| Blockchain Traceability Deployment | Distributed ledger verification satisfies EU CSRD scope-three disclosure mandates for luxury retail channels. |
| GIA Certification Capacity Expansion | In-house grading labor reduces bottlenecks limiting throughput for premium monocrystalline bridal output. |
| Industrial Electronics Diversification | Thermal substrate supply contracts extend revenue duration beyond fashion-cycle jewelry exposure. |
| Direct-to-Consumer Channel Buildout | Virtual try-on platforms capture margin compression benefits from displaced wholesale-retail tiers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FTC jewelry guide filings, BIS certification protocols, and GIA grading standard documentation. Conversations with CVD reactor engineers, Surat cutting house operators, and United States bridal retail procurement heads informed production cost and channel margin structures. Trade data from Indian customs authorities, SEC filings of publicly traded jewelry retailers, and ISO 18323 implementation records provided validation anchors. Bottom-up capacity modeling triangulated against top-down consumer expenditure estimates.
Segmentation dimensions modeled include product crystalline structure, deposition technology type, application category across jewelry and industrial end-uses, and customer archetype from manufacturers through direct-to-consumer platforms. CAGRs derive from reactor installation forecasts, electricity cost trajectory assumptions, and bridal purchase propensity indices across generational cohorts. Analysis incorporates HPHT-to-CVD technology substitution curves and renewable energy penetration rates in production clusters.
Forecasts assume regulatory continuity in FTC jewelry labeling, EU CSRD disclosure timelines, and BIS certification reciprocity; material policy shifts would require re-modeling. Revision becomes warranted when CVD reactor equipment lead times or diamond seed supply constraints cross thresholds disrupting capacity expansion assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Compostable Cotton Swab Market
Specialty Materials
Global Montan Wax Market
Specialty Materials
Nanoencapsulation Market
Specialty Materials
Global Cellulose Acetate Market
Specialty Materials
EVA Interlayer for Photovoltaic Market
Specialty Materials
Activated Carbon Bags Market
Specialty Materials
Jesmonite Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Epoxy Encapsulation Material Market
Specialty Materials
Global Synthetic Zeolite Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
Nanocapsules Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Organic Scintillators Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Electroactive Polymers (EAP) Market