
 Carbon Blacks for Non-Rubber Applications Market | 2026-2036
Carbon Blacks for Non-Rubber Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Blacks for Non-Rubber Applications Market Insights
ISO 14001 environmental management certification is redrawing the competitive map for carbon black suppliers seeking non-rubber contracts. Birla Carbon leverages integrated furnace operations across multiple continents to sustain cost-advantaged feedstock access. Orion Engineered Carbons anchors its position through specialized acetylene-process capacity serving electronics-grade demand. Cabot Corporation differentiates via deep R&D investment in surface-modified pigment blacks for coatings applications.
Carbon blacks for non-rubber applications comprise engineered particulate carbon materials produced through controlled thermal decomposition or partial combustion of hydrocarbon feedstocks, typically featuring primary particle sizes from 10 to 500 nanometers and surface areas ranging 20 to 250 m²/g, serving primarily as colorants, conductive additives, and UV stabilizers across industrial formulations. Pigment Black commands the largest value pool due to entrenched demand from automotive and architectural coatings, while Specialty Black captures expanding margin opportunities in lithium-ion battery electrodes and semiconductor packaging where conductivity thresholds are stringent. The Furnace Process segment dominates volume output given its scalability and feedstock flexibility, though the Acetylene Process retains premium positioning for ultra-high purity electronics applications.
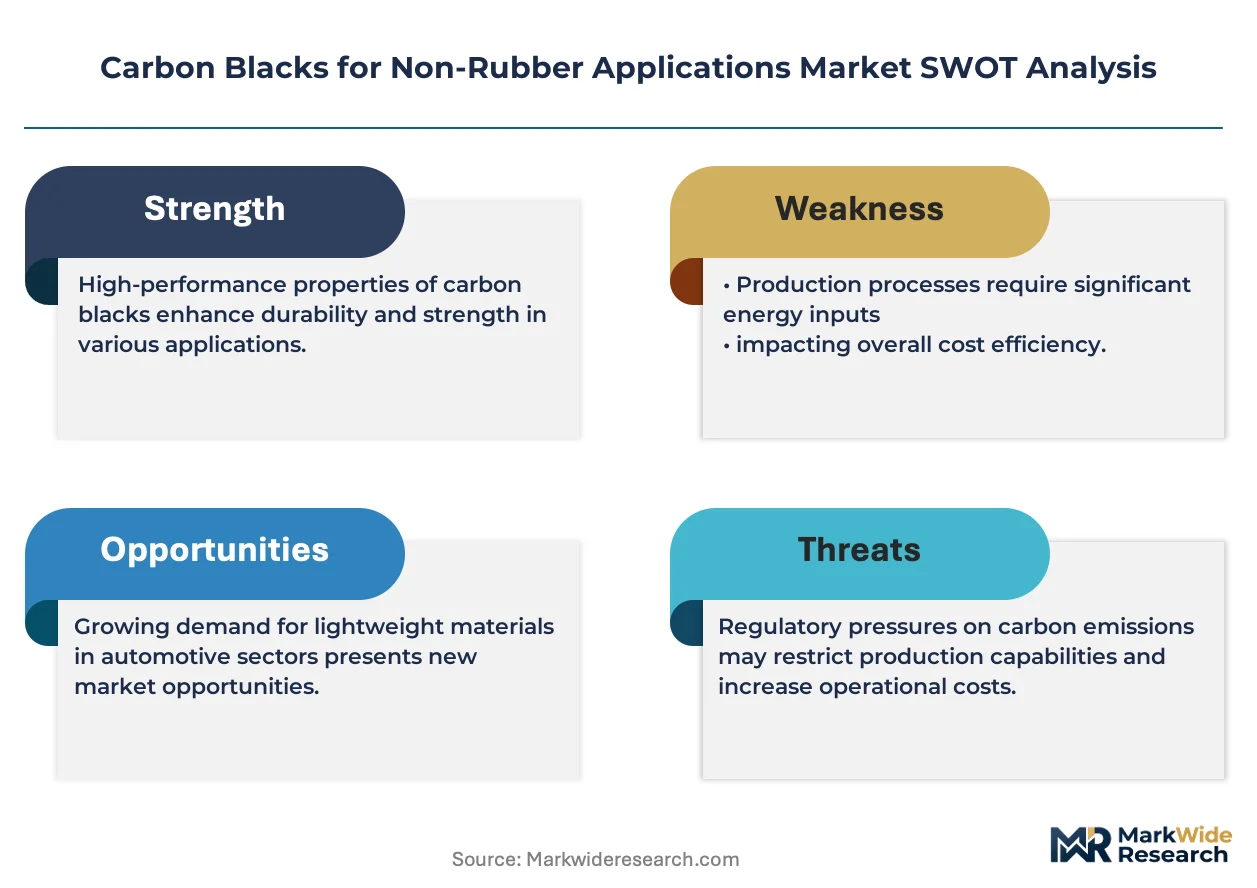
EPA emission standards under the Clean Air Act and REACH registration mandates administered by ECHA impose escalating compliance burdens on carbon black manufacturing, particularly regarding polycyclic aromatic hydrocarbon content and fugitive particulate emissions. China's MEE enforces parallel GB standards for air pollutants from carbon black production, creating a fragmented regulatory landscape that favors producers with multi-jurisdiction certification capabilities. Buyers must monitor evolving carbon intensity disclosure requirements under the EU Green Deal and emerging state-level climate mandates, as these frameworks will increasingly gate market access and contract eligibility.
Market Dynamics
EPA emission standards under the Clean Air Act and REACH registration mandates administered by ECHA are tightening purity thresholds for polycyclic aromatic hydrocarbon content, forcing carbon black suppliers to requalify furnace-process lines and redirect capital toward multi-jurisdiction certification capabilities.
Growth Catalysts
- REACH registration mandates:European coatings formulators now require ISO 14001-certified pigment blacks, creating contract eligibility barriers that favor qualified suppliers.
- Lithium-ion battery electrodes:Specialty-grade conductive blacks face stringent conductivity thresholds that furnace-process manufacturers are engineering surface modifications to meet.
- China's domestic furnace capacity:Localized supply expansion to plastics compounders and electronics manufacturers reduces import dependency and shortens lead times.
Market Restraints
- Feedstock cost volatility:Heavy aromatic oil and coal tar prices fluctuate with refinery output decisions, compressing margin predictability for furnace-process operators.
- Acetylene process supply concentration:Ultra-high purity electronics-grade production remains concentrated among specialized producers with captive acetylene supply.
- Silica substitution in tire applications:While outside non-rubber scope, silica R&D spillover threatens conductive black positioning in select industrial rubber-adjacent segments.
Strategic Opportunities
- India's BIS certification pathway:Domestic plastics and coatings sectors lack qualified local pigment black suppliers, creating first-mover eligibility for ISO-certified entrants.
- Semiconductor packaging demand:Advanced flip-chip and wafer-level packaging requires ultra-pure acetylene-process blacks with sub-50 ppm ash content.
- EU Green Deal carbon intensity disclosure:Buyers with Science-Based Targets initiative commitments are gating contracts on verified Scope 1-3 emissions data.
Industry Challenges
- Surface chemistry expertise gap:Formulating oxidized pigment blacks with controlled volatile content requires R&D talent scarce outside established coatings chemical hubs.
- MEE GB standard compliance timelines:China's air pollutant limits for carbon black production demand furnace retrofit investments with 18-24 month certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Blacks for Non-Rubber Applications Market |
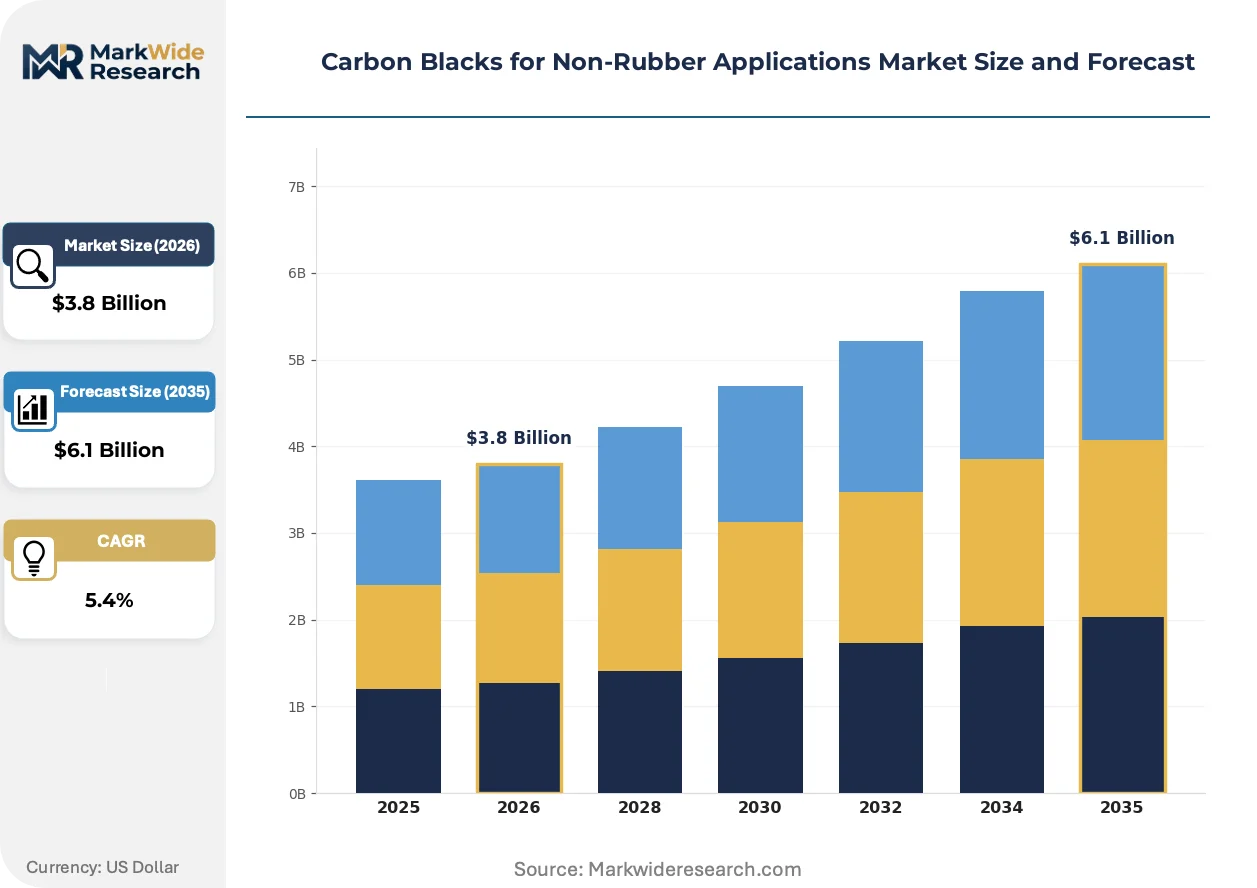
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conduction Black, Pigment Black, Specialty Black, Thermal Black End Use Industry: Plastics, Coatings, Inks, Electronics Form: Powder, Granules, Dispersions, Pellets Technology: Acetylene Process, Furnace Process, Gas Black Process, Thermal Process |
| Companies Covered | Cabot Corporation, Orion Engineered Carbons, Birla Carbon, Phillips Carbon Black, Tokai Carbon, Gansu Black Cat Carbon Black, Continental Carbon, Jiangxi Black Cat Carbon, Sid Richardson Carbon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Blacks for Non-Rubber Applications Market Trends and Innovations
Surface-modified pigment blacks with tailored volatile and ash specifications are reshaping supplier-buyer technical relationships, while regulatory disclosure mandates and procurement digitization are compressing traditional qualification timelines.
Plasma-process carbon black featuring sub-30 nanometer primary particle sizes and narrow aggregate distributions is supplanting conventional furnace grades in high-gloss automotive clearcoats. German and Japanese automotive OEMs have accelerated qualification cycles from 36 to 18 months for these materials. The shift is compressing commodity pigment pricing power while expanding margin capture for surface-engineered specialty grades.
REACH registration mandates administered by ECHA now require updated safety data sheets for all carbon black grades exceeding 0.1% polycyclic aromatic hydrocarbon content. Industrial coatings formulators in Germany and France are reformulating toward low-PAH pigment blacks to preempt downstream liability. The regulatory pressure is fragmenting supplier qualification pools and extending contract lock-in periods for compliant producers.
Buyer technical service requirements have intensified as coatings formulators seek co-development partnerships for color-stability optimization in waterborne systems. Direct supplier-R&D-lab relationships are displacing traditional distributor-mediated sampling and specification matching. This pattern concentrates most visibly in automotive OEM technical centers clustered around Stuttgart, Detroit, and Shanghai.
Carbon Blacks for Non-Rubber Applications Market Segmentation
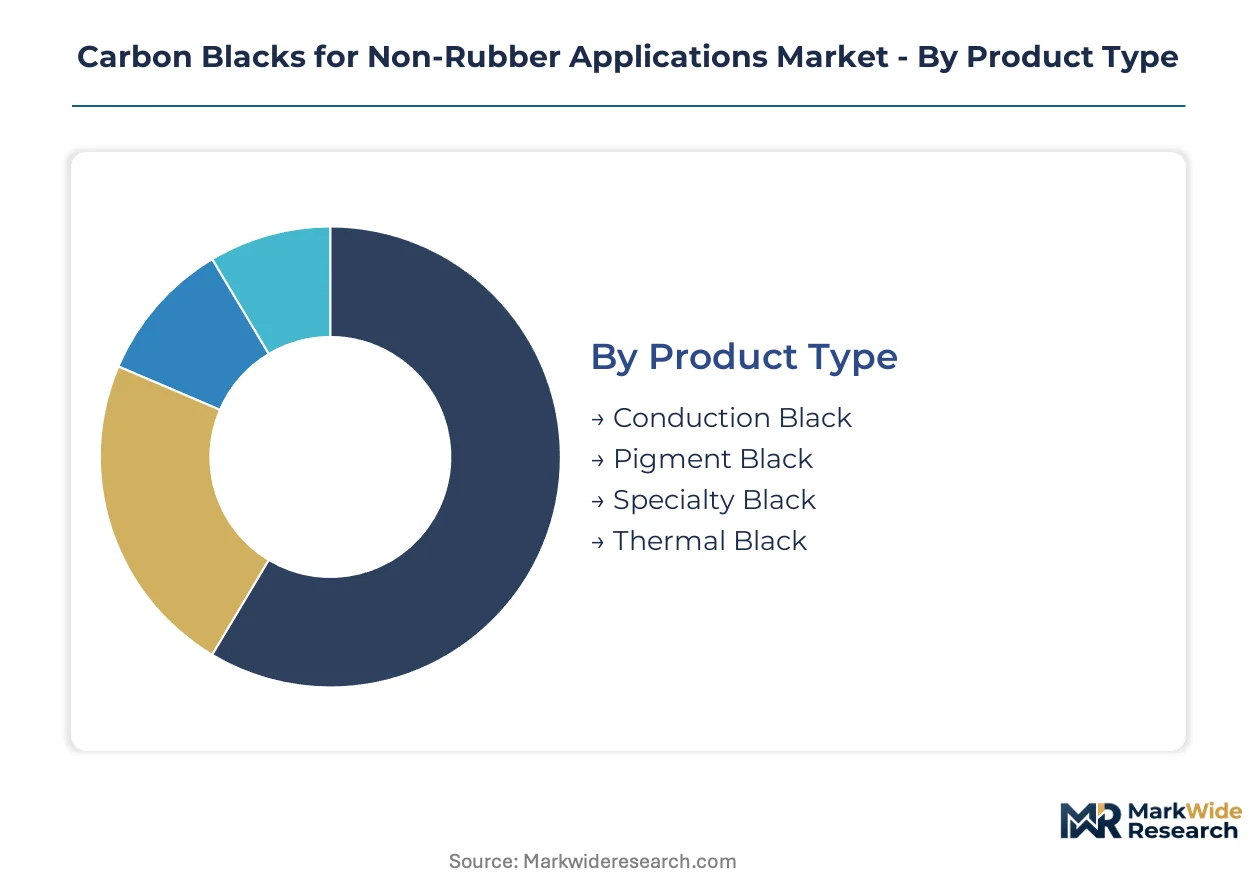
Carbon black suppliers configure product portfolios around distinct purity thresholds and conductivity specifications that align with end-use regulatory requirements. Segmentation discipline separates commodity furnace grades from premium acetylene-process materials commanding specialized qualification protocols.
Product Type:
REACH registration mandates administered by ECHA now require updated safety data sheets for grades exceeding polycyclic aromatic hydrocarbon thresholds, fragmenting supplier pools by compliance tier.
- Pigment Black:Engineered particulate carbon with primary particle sizes from 10 to 100 nanometers serves as the dominant colorant in automotive and architectural coatings. Demand concentrates among German and French industrial coatings formulators reformulating toward low-PAH specifications to preempt downstream liability under evolving ECHA guidance.
- Specialty Black:Surface-modified grades with controlled volatile content and sub-50 ppm ash specifications target lithium-ion battery electrodes and semiconductor packaging. China's domestic electronics manufacturers are accelerating qualification of these materials for localized supply to battery compounders.
- Conduction Black:High-structure furnace grades with enhanced electron transport properties serve plastics and antistatic applications.
- Thermal Black:Large particle-size material produced through natural gas thermal decomposition finds niche use in insulating compounds and metallurgical applications.
Pigment Black handles the majority of throughput; Specialty Black is the fastest mover on share.
End Use Industry:
Customer technical service requirements intensify as formulators seek co-development partnerships, concentrating supplier-buyer relationships around R&D clusters in Stuttgart, Detroit, and Shanghai.
- Coatings:Automotive OEM clearcoats and industrial finishes demand plasma-process grades with sub-30 nanometer primary particles for high-gloss applications. German and Japanese automotive technical centers have compressed qualification cycles from 36 to 18 months for these materials.
- Electronics:Flip-chip packaging and wafer-level interconnects require ultra-pure acetylene-process blacks with conductivity thresholds stringent enough to displace conventional furnace grades. Taiwan and South Korean semiconductor fabricators are gating supplier access on verified ash content below 50 ppm.
- Plastics:Masterbatch compounders integrate conductive blacks into engineering polymers for ESD protection and electromagnetic shielding.
- Inks:Publication gravure and UV-curable systems utilize oxidized pigment blacks with tailored volatile specifications for rheology control.
Coatings commands the largest absolute volume; Electronics is climbing the fastest on margin expansion.
Form:
Logistics economics and dust exposure regulations favor densified formats, though powder retains critical positioning in waterborne systems requiring rapid dispersion.
- Powder:Uncompressed carbon black with maximum surface area for rapid wetting in high-shear dispersion equipment serves waterborne coatings and ink systems where dust control equipment mitigates occupational exposure.
- Pellets:Densified spherical forms reduce transportation costs and improve handling characteristics for automated plastics compounding operations. Chinese domestic furnace producers are expanding pelletization capacity to serve localized plastics compounders.
- Granules:Intermediate density format balances dispersion speed with dust reduction for mid-volume coatings applications.
- Dispersions:Pre-dispersed pigment concentrates in aqueous or solvent carriers eliminate milling steps for small-batch coatings formulators.
Pellets handles the majority of throughput; Dispersions is gaining share fastest among specialty coatings formulators.
Technology:
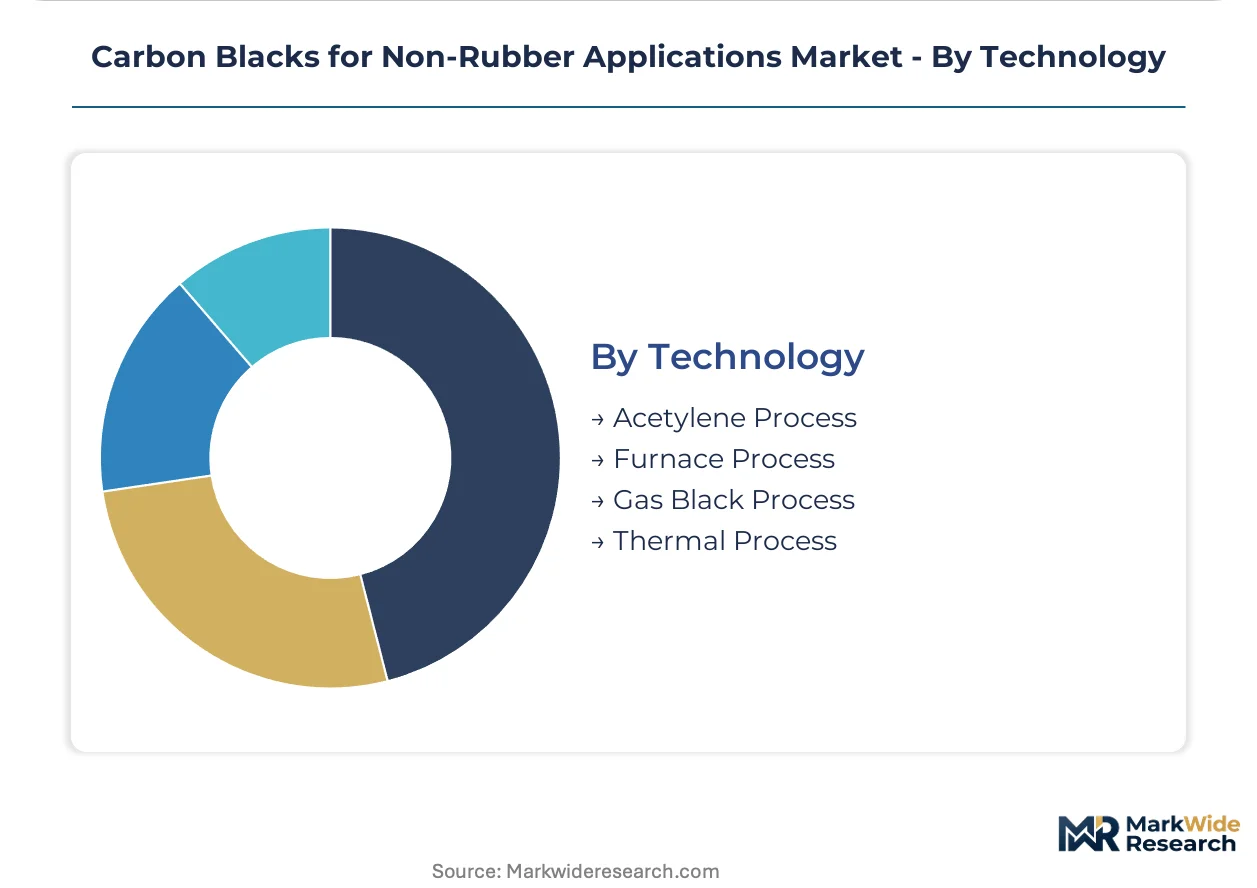
Capital intensity and feedstock flexibility separate scalable furnace operations from premium acetylene capacity concentrated among specialized producers with captive hydrocarbon supply.
- Furnace Process:Partial combustion of heavy aromatic oils or coal tar feedstocks yields scalable output with adjustable particle size through reactor temperature and residence time control. China's MEE-enforced GB standards for air pollutants are forcing 18-24 month retrofit investments across domestic furnace lines.
- Acetylene Process:Thermal decomposition of acetylene gas produces ultra-high purity carbon black with sub-50 ppm ash content for electronics and semiconductor applications. Supply remains concentrated among producers with captive acetylene supply, creating margin protection against furnace-grade commoditization.
- Thermal Process:Natural gas cracking in refractory-lined furnaces generates large particle-size material for insulating and rubber applications with limited non-rubber penetration.
- Gas Black Process:Channel or impingement methods using natural gas feedstock yield high-structure grades with distinctive morphology for specialized coatings applications.
Furnace Process handles the majority of throughput; Acetylene Process is expanding most quickly on electronics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration mandates and EPA emission standards are reshaping supplier qualification protocols across major manufacturing economies. Domestic furnace capacity expansion in China and localized supply strategies in India are redrawing traditional import-dependent trade flows.
United States
Automotive OEMs in Detroit and industrial coatings formulators drive specialty-grade pigment black consumption. EPA standards under the Clean Air Act enforce escalating purity thresholds for polycyclic aromatic hydrocarbon content. Technical centers clustered around Detroit compress qualification cycles for surface-modified grades serving waterborne coating systems.
Germany
Industrial coatings formulators in Stuttgart and automotive clearcoat producers anchor European pigment black demand. ECHA-administered REACH registration mandates require updated safety data sheets for grades exceeding PAH thresholds. German automotive OEM technical centers have accelerated plasma-process carbon black qualification from 36 to 18 months for high-gloss applications.
China
Domestic electronics manufacturers and plastics compounders concentrate demand for furnace-process output. MEE-enforced GB standards for air pollutants demand 18-24 month retrofit investments across domestic furnace lines. Yangtze River Delta electronics clusters are accelerating qualification of specialty blacks for localized lithium-ion battery electrode supply.
India
Domestic plastics and coatings sectors lack qualified local pigment black suppliers, creating contract eligibility gaps. BIS certification pathways remain underpenetrated for ISO 14001-certified entrants. Maharashtra and Gujarat industrial corridors present first-mover positioning for furnace-process suppliers meeting domestic compounder specifications.
South Korea
Semiconductor fabricators in Gyeonggi Province gate supplier access on verified ash content below 50 ppm for flip-chip packaging applications. MFDS-aligned material safety protocols intersect with customer-imposed purity thresholds. Busan-Ulsan electronics clusters concentrate demand for ultra-high purity acetylene-process grades in advanced wafer-level interconnects.
Carbon Blacks for Non-Rubber Applications Market Competitive Landscape
Listed leaders compete with private specialists across certification and feedstock access dimensions. The supplier base consolidates around integrated furnace operators with multi-continent presence and specialized acetylene-process producers serving electronics-grade niches. Three archetypes dominate: integrated petrochemical-carbon black majors, acetylene-captive purity specialists, and regional furnace operators with localized feedstock advantages. Capacity expansion and multi-jurisdiction certification capability are the dominant competitive moves reshaping contract eligibility.
Within the integrated major tier, Cabot Corporation and Birla Carbon occupy positions defined by scale and geographic reach. Orion Engineered Carbons exemplifies the specialty-grade archetype through acetylene-process positioning. Among Asian furnace operators, Gansu Black Cat Carbon Black and Jiangxi Black Cat Carbon represent regional champions leveraging domestic capacity expansion to serve localized plastics and electronics demand.
| Leading Market Players |
|---|
| Cabot Corporation |
| Orion Engineered Carbons |
| Birla Carbon |
| Phillips Carbon Black |
| Tokai Carbon |
| Gansu Black Cat Carbon Black |
| Continental Carbon |
| Jiangxi Black Cat Carbon |
| Sid Richardson Carbon |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between furnace-process producers and automotive OEMs lock in multi-year feedstock access while fixing price visibility against heavy aromatic oil volatility. These structures concentrate pricing power among integrated operators with captive refinery relationships, while spot-exposed compounders absorb margin compression from coal tar price swings.
Pricing Analysis
Certification level creates the primary spread between ISO 14001-qualified pigment blacks and uncertified furnace grades. Contract-based long-term offtake dominates automotive coatings procurement, while spot transactional pricing prevails among plastics masterbatch compounders. Price differentiation hinges on REACH compliance tier and volume scale, with low-PAH specialty blacks commanding premiums. Cost compression in standard furnace grades is intensifying because China's domestic capacity expansion shortens lead times and erodes import pricing. Plastics compounders exhibit highest price sensitivity due to commoditized substitution options, whereas semiconductor fabricators show lowest sensitivity given ash-content thresholds that gate supplier pools.
Supply Chain Analysis
Strategic stockpiling of heavy aromatic oil feedstock buffers furnace operators against refinery output volatility, while just-in-time pellet delivery dominates plastics compounding relationships. Supply concentrates in China, the United States, and Germany, with furnace-process output anchored in Yangtze River Delta clusters and acetylene-process purity concentrated in South Korean and Japanese electronics corridors. Raw material dependencies draw from coal tar distillates, natural gas thermal crackers, and captive acetylene generation. Single-source vulnerability runs through specialized acetylene-captive producers serving sub-50 ppm ash semiconductor specifications. Distribution runs through direct technical service relationships with automotive OEM R&D centers, displacing traditional distributor mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon black incumbents face substitution defense against plasma-process nanomaterials and surface-engineered conductive polymers that threaten pigment black positioning in high-gloss coatings. Silica R&D spillover from tire applications presents adjacent-segment encroachment risk that demands technical differentiation investment.
For Market Incumbents: Consolidate furnace-process capacity around multi-jurisdiction certification capabilities to preempt ECHA and EPA qualification barriers. Backward integration into heavy aromatic oil refining secures feedstock cost visibility against volatile coal tar markets. Defensive R&D investment in surface-modified pigment blacks for waterborne coatings systems counters plasma-process substitution in automotive clearcoats.
For New Entrants and Emerging Players: Lead with BIS certification pathways in India's underpenetrated Maharashtra and Gujarat industrial corridors, where domestic plastics compounders lack qualified local pigment black suppliers. White-space concentration in ISO 14001-certified furnace grades for coatings formulators offers first-mover contract eligibility. Go-to-market positioning through direct technical service relationships with automotive OEM R&D labs in Stuttgart and Shanghai accelerates qualification cycles.
For Investors and Strategic Acquirers: Capital is best deployed toward acetylene-captive purity specialists serving semiconductor packaging demand, where sub-50 ppm ash thresholds create margin protection against furnace-grade commoditization. Long-term viability across the projection horizon rests on multi-jurisdiction certification capabilities that gate contract eligibility under REACH and evolving EPA standards. The signal to watch is qualification cycle compression for plasma-process grades in German and Japanese automotive technical centers, indicating substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | China's MEE-enforced GB standards demand 18-24 month furnace retrofit investments. |
| Backward Integration | Captive heavy aromatic oil supply secures margin visibility against refinery volatility. |
| Green Manufacturing Transition | EU Green Deal carbon intensity disclosure gates contract eligibility for Science-Based Targets buyers. |
| Long-term Supply Agreement | Automotive OEM offtake contracts lock in multi-year feedstock access and price stability. |
| Joint Venture | Localized furnace capacity in India addresses BIS certification gaps for plastics compounders. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with coatings formulators, plastics masterbatch compounders, semiconductor packaging engineers, and carbon black plant managers. Secondary validation drew from ECHA REACH registration databases, EPA Clean Air Act enforcement records, SEC 10-K filings of listed producers, and China MEE GB standard documentation. Bottom-up volume modeling triangulated against top-down value estimates from trade flow analysis.
Across the analysis window, projections incorporated furnace-process capacity expansion trajectories, acetylene-process purity yield curves, and qualification cycle compression patterns in automotive technical centers. Segmentation dimensions spanned product type tier, end-use industry concentration, form factor logistics economics, and process technology capital intensity. CAGRs were derived from elasticity-adjusted demand curves and feedstock cost pass-through assumptions. Industry-specific inputs included polycyclic aromatic hydrocarbon threshold evolution under ECHA guidance and lithium-ion battery electrode conductivity specifications.
Underlying assumptions cover sustained REACH registration enforcement and EPA emission standard tightening, with deviation risk concentrated in China's domestic furnace capacity utilization rates and semiconductor demand cyclicality. Revision becomes warranted when plasma-process nanomaterial qualification velocity crosses thresholds that displace conventional pigment blacks in high-gloss automotive applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
PVB Interlayers Market
Specialty Materials
Activated Carbon Bags Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
India Collagen Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Carrageenan Film Market
Specialty Materials
South America Polyether Ether Ketone (Peek) Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
EVA Interlayer for Photovoltaic Market
Specialty Materials
Alginate Films Market
Specialty Materials
Nanoencapsulation Market
Specialty Materials
United States Neoprene Market
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Asia-Pacific Reflective Tape Market
Specialty Materials
Magnesium Fluoride Market
Specialty Materials
Global Graphic Film Market