
 Sheath Materials Market | 2026-2036
Sheath Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Sheath Materials Market Outlook
Asset-light leasing models for extrusion equipment is reconfiguring competitive entry barriers, allowing mid-scale processors to access production capacity without capital-intensive infrastructure commitments. Dow Inc. leverages its integrated polymer supply chain to dominate thermoplastic resin feedstock availability for sheath producers. SAB Bröckskes GmbH & Co. KG specializes in temperature-resistant jacketing systems that anchor its position across industrial cable applications. Gravita India Ltd. competes on recycled metal sourcing for conductive core sheathing, particularly in cost-sensitive electrical distribution markets.
Sheath materials are protective outer layers applied over conductive cores, optical fibers, or structural elements, typically extruded from thermoplastic or thermoset polymers with wall thicknesses ranging from 0.1 mm to 5.0 mm depending on voltage rating and mechanical protection requirements. These layers serve to insulate, shield against environmental degradation, and provide abrasion resistance in operational environments spanning automotive engine bays to surgical suites. Polyurethane formulations command premium positioning in medical and aerospace applications where flexibility and biocompatibility justify higher material costs. Thermoplastic compounds sustain volume leadership across automotive wire harnessing due to processing speed and recyclability advantages. Polyethylene grades dominate electrical utility cabling where moisture resistance and dielectric stability remain paramount specifications.
FDA biocompatibility standards under ISO 10993 govern medical sheath acceptance in the United States, while REACH substance restrictions and CE marking requirements under the EU MDR shape European material selection and supplier qualification protocols. EPA emission regulations for vinyl chloride monomer processing additionally constrain domestic manufacturing configurations for PVC-based sheathing alternatives. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as fluoropolymer sheath formulations face prospective substitution pressures that will reshape material R&D priorities and supplier qualification timelines.
Market Dynamics
Biocompatibility certification timelines and fluoropolymer substitution pressures are restructuring supplier qualification protocols, compressing R&D cycles while fragmenting material sourcing strategies across medical and industrial segments.
Growth Catalysts
- EU MDR compliance mandates:European medical device manufacturers accelerate polyurethane sheath adoption for catheter systems to meet biocompatibility and traceability requirements under tightened CE marking protocols.
- Automotive electrification:German OEM clusters in the industrial corridor drive thermoplastic demand for high-voltage wire harnessing as EV production scales.
- REACH substance restrictions:ECHA regulatory pressure on per- and polyfluoroalkyl substances forces material innovation, opening market share for alternative polymer formulations.
Market Restraints
- Vinyl chloride monomer processing costs:EPA emission regulations constrain domestic PVC-based sheathing manufacturing configurations, elevating compliance expenditures for US-based extrusion facilities.
- Fluoropolymer feedstock concentration:Limited qualified suppliers for temperature-resistant jacketing systems create supply vulnerability for aerospace and industrial cable applications.
- Dielectric stability thresholds:Polyethylene grades face technical ceiling effects in ultra-high-voltage transmission applications above 400 kV, restricting material substitution potential.
Strategic Opportunities
- Recycled metal core sheathing:Cost-sensitive electrical distribution markets in India present expansion potential for processors with validated circular material supply chains.
- Asset-light extrusion leasing:Equipment-as-a-service models enable mid-scale processors to access production capacity without capital-intensive infrastructure commitments.
- ISO 10993 pre-certification services:Third-party testing laboratories can capture value from medical device manufacturers seeking accelerated FDA biocompatibility approval pathways.
Industry Challenges
- Multi-jurisdictional substance tracking:Sheath producers must maintain parallel compliance documentation for REACH, EPA, and evolving state-level PFAS restrictions simultaneously.
- Wall thickness precision engineering:Medical catheter applications demand tolerance control within 0.05 mm across production batches, requiring specialized extrusion die maintenance protocols.
- Legacy PVC formulation phase-outs:Industrial cable producers face requalification timelines of 18-24 months when substituting established jacketing materials with compliant alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheath Materials Market |
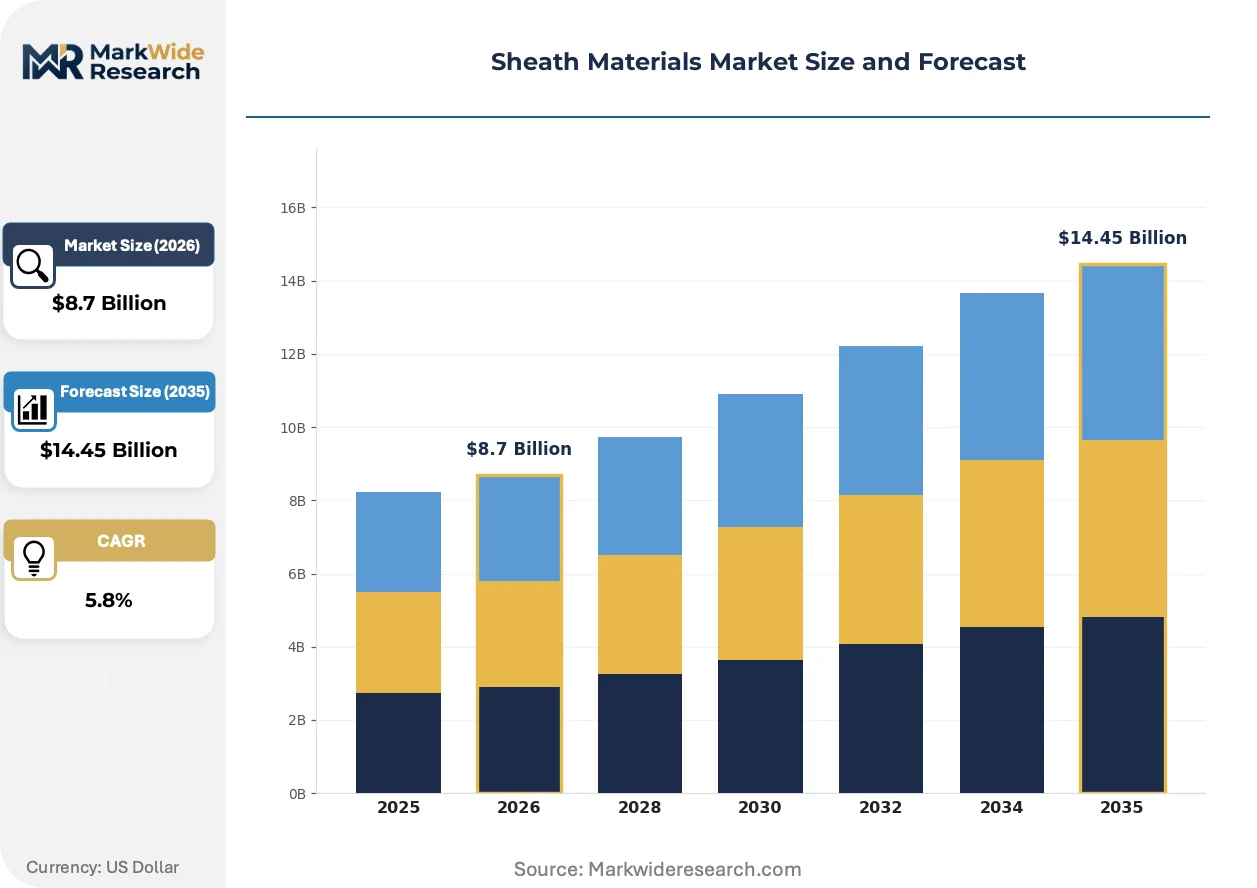
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic, Thermoset, Polyethylene, Polyurethane Application: Automotive, Electrical, Medical, Aerospace Material: Copper, Aluminum, Glass Fiber, Composite End User: Manufacturers, Distributors, Retailers, Contractors |
| Companies Covered | Gravita India Ltd., Steel Will, Ducab, Caledonian, SAB Bröckskes GmbH & Co. KG, Durex Industries, Marttiini, Teltech, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheath Materials Market Strategic Shifts
Digital twin simulation of extrusion processes is compressing development cycles while regulatory substance databases are automating compliance verification, together accelerating material iteration velocity.
Multi-layer co-extrusion simulation software is virtualizing traditional prototyping workflows for thermoplastic sheath development. Medical device manufacturers in Germany and the United States deploy these platforms to reduce physical iteration cycles by half. The technology is virtualizing capital allocation patterns, redirecting R&D expenditure from tooling toward computational material science.
REACH substance restriction amendments under ECHA review are expanding candidate list coverage for persistent organic pollutants in polymer additives. Industrial cable producers face reformulation mandates affecting flame-retardant jacketing systems across European supply contracts. German automotive OEMs are responding by pre-qualifying alternative halogen-free compounds ahead of enforcement deadlines.
Consolidated procurement platforms for certified polymer feedstock are displacing spot-market purchasing among mid-scale extrusion processors. Medical sheath specialists in North America now source biocompatible polyurethane through validated supplier portals with embedded chain-of-custody documentation. This channel shift is most visible in catheter manufacturing clusters where FDA audit readiness requirements dominate supplier selection criteria.
Sheath Materials Market Segmentation
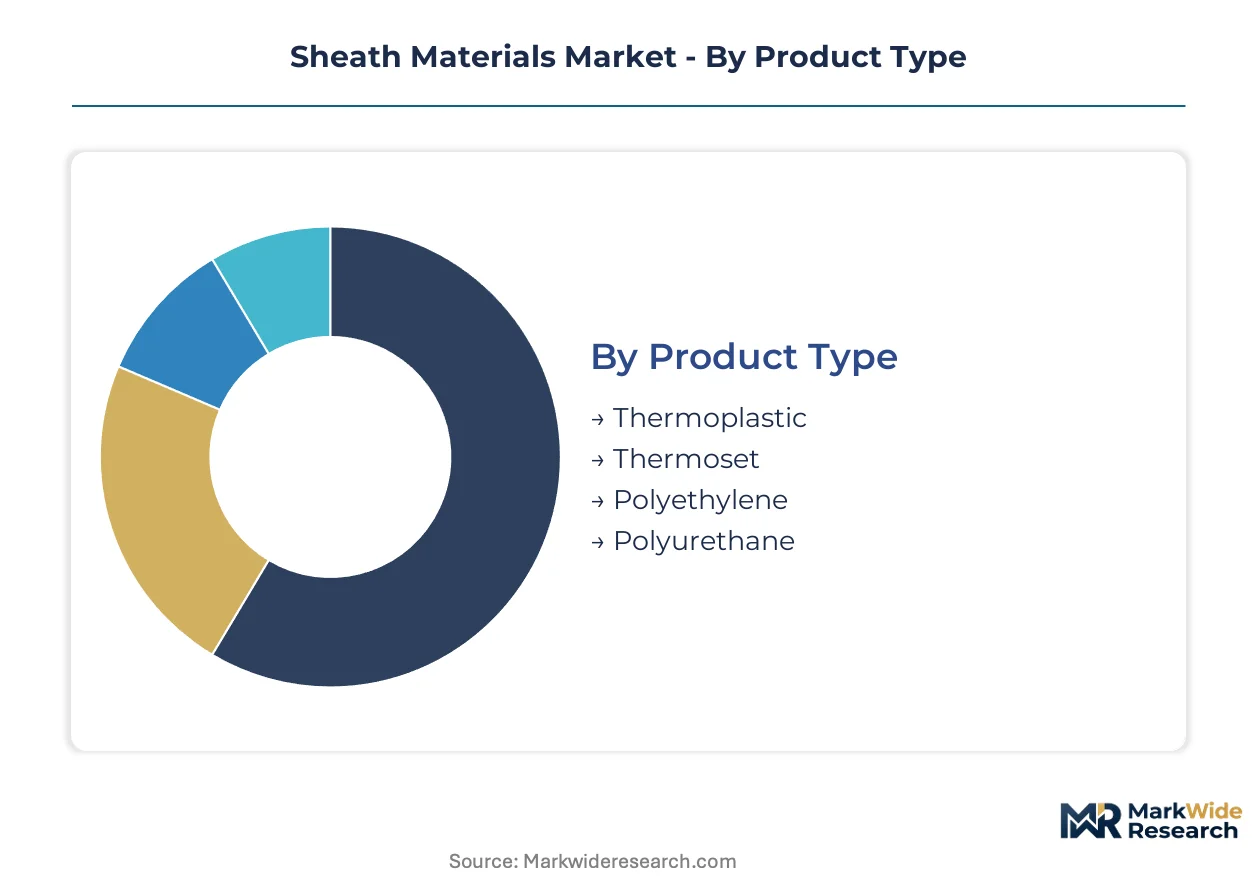
Material selection across sheath categories determines compliance pathways, processing economics, and end-use qualification timelines. Product chemistry, application environment, and conductive core composition each impose distinct specification hierarchies that reshape procurement priorities and supplier positioning.
Product Type:
Cost tier differentiation separates commodity thermoplastics from engineered thermosets and specialty polymers, with formulation chemistry driving margin structure and capital intensity.
- Thermoplastic:Extruded polymers including PVC, PE, and PP formulations dominate automotive wire harnessing and electrical utility cabling due to reprocessability and high-speed manufacturing. German OEM clusters in Stuttgart and Wolfsburg specify halogen-free grades for EV high-voltage systems under REACH substance restrictions.
- Thermoset:Cross-linked elastomers and cured rubber compounds deliver temperature resistance above 150°C for industrial cable and aerospace applications. Limited reprocessability elevates scrap costs but justifies premium positioning in mission-critical installations.
- Polyethylene:LDPE and XLPE grades anchor electrical transmission sheathing where moisture resistance and dielectric stability govern specification. Utility-scale projects in the United States and India specify these materials for underground and submarine cable deployments.
- Polyurethane:Segmented aromatic and aliphatic formulations command medical catheter and aerospace flexible harness applications. FDA biocompatibility certification under ISO 10993 and EU MDR traceability requirements compress supplier qualification timelines for catheter manufacturers.
Thermoplastic commands the established base. The steepest expansion runs through polyurethane as medical device certification requirements tighten across North American and European markets.
Application:
End-use environment dictates mechanical, thermal, and chemical resistance specifications, with regulatory density varying sharply across verticals.
- Automotive:Wire harness sheathing for internal combustion and electric powertrains faces diverging material demands. EV battery routing systems specify flame-retardant thermoplastics with thermal runaway containment properties, while traditional engine bay applications prioritize oil and abrasion resistance.
- Electrical:Utility-scale transmission, distribution, and building wire applications specify polyethylene and PVC-based jacketing. Dielectric stability requirements above 400 kV create technical ceilings that restrict material substitution in ultra-high-voltage corridors.
- Medical:Catheter, guidewire, and implantable lead sheathing demands biocompatible polyurethane with sub-0.1 mm wall thickness control. ISO 10993 testing protocols and FDA 510(k) submission requirements extend development cycles to 18-36 months.
- Aerospace:Temperature-resistant jacketing for avionics and engine systems operates across -65°C to 260°C ranges. Fluoropolymer concentration among qualified suppliers creates procurement vulnerability as ECHA reviews PFAS restrictions under REACH amendments.
Electrical applications anchor volume demand. Medical and aerospace segments climb the fastest as certification barriers concentrate margin capture among qualified processors.
Material:
Conductive core composition determines electromagnetic shielding requirements, thermal management needs, and mechanical protection specifications for the overlying sheath.
- Copper:High-conductivity cores in electrical transmission and automotive power distribution require dielectric sheathing with precise thickness control. BIS certification in India and UL listing in the United States govern sheath-core system approvals.
- Aluminum:Lightweight conductive cores in aerospace and automotive applications reduce mass but demand compatible sheath materials that accommodate differential thermal expansion. Cost-sensitive utility markets in India specify aluminum conductor steel-reinforced cables with polyethylene jacketing.
- Glass Fiber:Optical fiber sheathing prioritizes crush resistance and moisture blocking over electrical insulation. Telecommunications infrastructure deployments specify loose tube and tight buffer designs with gel-filled or dry water-blocking compounds.
- Composite:Carbon fiber and hybrid conductive elements in aerospace and specialized industrial applications impose unique thermal and mechanical loading on protective jackets. Niche positioning limits volume but sustains premium pricing.
Copper-core sheathing commands the established base. Composite configurations gain share fastest in aerospace weight-reduction programs.
End User:
Customer type determines procurement scale, specification authority, and compliance documentation requirements across the value chain.
- Manufacturers:OEMs and tier suppliers in automotive, medical device, and cable production hold direct specification authority. REACH and EU MDR compliance documentation requirements dominate European supplier selection, while FDA audit readiness governs North American medical sheath procurement.
- Distributors:Electrical and industrial supply wholesalers intermediate between extrusion processors and installation contractors. Consolidated procurement platforms with embedded chain-of-custody documentation displace spot-market purchasing for certified polymer feedstock.
- Retailers:Consumer-facing channels for building wire and DIY electrical applications emphasize standardized product lines with established safety certifications. Price sensitivity limits specialty material penetration.
- Contractors:Installation and construction firms specify sheathing for project-specific applications with variable compliance documentation needs. Regional electrical codes and inspector approval requirements shape local material preferences.
Manufacturers command the established base. Distributor channel consolidation runs through the steepest expansion trajectory as validated supplier portals capture procurement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive electrification subsidies and US EPA emission regulations are redirecting sheath material procurement toward compliant thermoplastic and polyurethane formulations across major manufacturing economies.
United States
EV battery plant construction in Michigan and Tennessee is accelerating demand for flame-retardant thermoplastic sheathing in high-voltage wire harness systems. EPA vinyl chloride monomer emission regulations constrain domestic PVC extrusion capacity, elevating compliance costs for processors. Medical device manufacturers in Minneapolis and Boston clusters pursue ISO 10993 pre-certification pathways to compress FDA approval timelines for catheter sheath introductions.
Germany
Automotive OEMs in Stuttgart and Wolfsburg specify halogen-free thermoplastic grades for electric powertrain routing under REACH substance restriction protocols. EU MDR traceability mandates compress supplier qualification timelines for polyurethane medical sheath producers. The industrial corridor spanning Bavaria and Baden-Württemberg concentrates cable producers and automotive tier suppliers driving regional thermoplastic consumption.
China
Grid-scale renewable energy deployment is expanding polyethylene sheathing demand for ultra-high-voltage transmission infrastructure. MIIT industrial standards for cable materials are tightening dielectric stability specifications above 400 kV. Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces host extrusion processors serving domestic electrical utility and automotive export markets.
India
Cost-sensitive electrical distribution markets specify aluminum conductor cables with polyethylene jacketing for rural grid extension programs. BIS certification requirements govern sheath-core system approvals for copper and aluminum configurations. Gujarat and Maharashtra industrial corridors concentrate cable producers sourcing recycled metal feedstock for conductive core sheathing applications.
Japan
Aerospace wire harness manufacturers specify temperature-resistant jacketing materials for avionics systems operating across extreme thermal ranges. METI industrial policy supports domestic fluoropolymer substitution R&D as ECHA reviews PFAS restrictions affecting qualified supplier bases. Nagoya and Tokyo manufacturing clusters maintain precision extrusion capabilities for medical and aerospace sheath applications requiring sub-0.1 mm wall thickness control.
Sheath Materials Market Competitive Environment
On the supply side, the industry is tiered between integrated polymer producers, specialized extrusion processors, and recycled material suppliers competing across distinct certification and cost vectors. Dow Inc. leverages captive thermoplastic resin production to dominate feedstock availability for high-volume automotive and electrical applications. Specialist jacketing fabricators concentrate in German and North American industrial corridors where OEM proximity and regulatory compliance documentation create qualification barriers. Consolidated procurement platforms and asset-light equipment leasing models are lowering entry thresholds for mid-scale processors while compressing spot-market purchasing margins.
Within the integrated polymer tier, Dow Inc. anchors North American thermoplastic supply chains through backward control of resin production. Among specialized European fabricators, SAB Bröckskes GmbH & Co. KG exemplifies the temperature-resistant jacketing archetype serving industrial cable applications. Gravita India Ltd. occupies a position in the recycled metal sourcing segment for cost-sensitive electrical distribution markets in South Asia.
| Leading Market Players |
|---|
| Gravita India Ltd. |
| Steel Will |
| Ducab |
| Caledonian |
| SAB Bröckskes GmbH & Co. KG |
| Durex Industries |
| Marttiini |
| Teltech |
| Dow Inc. |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Alpine freight corridor shapes cost dynamics for polyurethane resin deliveries from German chemical clusters to medical device manufacturers in Switzerland and northern Italy, compressing margins for non-integrated processors while amplifying price differentiation between REACH-certified and uncertified feedstock tiers.
Pricing Analysis
Certification level (ISO 10993/FDA-grade vs. industrial-grade) creates the primary spread across polyurethane and thermoplastic categories, with medical catheter sheathing commanding substantial premiums over automotive wire harness materials. Contract-based long-term offtake agreements dominate volume procurement among German OEMs and North American cable producers, insulating qualified suppliers from spot-market volatility. Cost compression in standard-grade thermoplastics is intensifying because asset-light leasing models are flooding mid-scale capacity into automotive and electrical segments. Building wire retailers exhibit the highest price sensitivity, while aerospace and medical device manufacturers prioritize qualification documentation over unit economics.
Supply Chain Analysis
Upstream thermoplastic resin production concentrates in the United States, Germany, and China, with Dow Inc. and regional petrochemical complexes anchoring feedstock availability for extrusion processors. Polyurethane precursor supply draws from specialty chemical manufacturers in Belgium and the Netherlands, while fluoropolymer feedstock hinges on limited qualified suppliers in Japan and the United States. Single-source vulnerability for temperature-resistant jacketing materials creates procurement risk as ECHA reviews PFAS restrictions under REACH amendments. Distribution runs through consolidated procurement platforms with embedded chain-of-custody documentation, displacing spot-market purchasing among mid-scale medical sheath specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidated procurement platforms are transforming sheath materials into a platform-economics market, with interoperability between supplier qualification databases and OEM ERP systems determining access to specification authority at German automotive and North American medical device clusters.
For Market Incumbents: Pre-empt fluoropolymer substitution disruption by accelerating halogen-free compound pre-qualification ahead of ECHA enforcement deadlines. Secure backward integration into biocompatible polyurethane precursor supply through captive production or exclusive offtake agreements with Belgian and Dutch specialty chemical producers. Channel control through validated supplier portals with embedded FDA audit readiness documentation will defend margin position against asset-light entrants.
For New Entrants and Emerging Players: India's Gujarat and Maharashtra industrial corridors offer the most penetrable white-space for recycled metal core sheathing in cost-sensitive rural grid extension programs. Target ISO 10993 pre-certification services as a service-based entry vector, capturing value from medical device manufacturers seeking accelerated FDA approval pathways without capital-intensive extrusion infrastructure. Equipment-as-a-service leasing models enable mid-scale processors to access production capacity while building qualification track records.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core cable jacketing divisions lacking REACH compliance documentation infrastructure. Long-term viability favors processors with validated circular material supply chains and embedded regulatory affairs capabilities across multiple jurisdictions. Monitor ECHA substance restriction amendment timelines as the critical inflection signal for fluoropolymer substitution R&D prioritization and distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Precursors | Captive supply of biocompatible resin secures margin capture from REACH-certified medical sheath demand. |
| ISO 10993 Pre-Certification Service Launch | Third-party testing laboratories capture value from catheter manufacturers compressing FDA approval timelines. |
| Halogen-Free Compound Pre-Qualification | German automotive OEMs secure specification authority ahead of ECHA flame-retardant additive restrictions. |
| Asset-Light Extrusion Equipment Leasing | Mid-scale processors access production capacity without capital-intensive infrastructure commitments in India. |
| Consolidated Procurement Platform Expansion | Validated supplier portals with chain-of-custody documentation displace spot-market purchasing among medical specialists. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs and trade databases, and ECHA regulatory submissions to establish baseline market sizing. Primary interviews engaged extrusion plant managers, procurement leads at automotive OEMs and cable producers, biomedical engineers at catheter manufacturers, and distribution channel partners across North America, Europe, and Asia-Pacific. Secondary validation drew from FDA 510(k) submission databases, EU MDR notified body reports, and MIIT industrial standards documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators to ensure consistency across the analysis window.
Forecast inputs include modeled segmentation across material chemistry, application environment, conductive core composition, and end-user procurement scale. Growth trajectories incorporate automotive electrification content per vehicle, medical device certification timeline compression, and grid infrastructure deployment patterns across the projection horizon. CAGRs derive from regression analysis of historical capacity utilization, feedstock cost trajectories, and regulatory enforcement schedule probabilities. Industry-specific inputs encompass REACH substance restriction amendment review timelines and EPA vinyl chloride monomer emission compliance cost curves.
Practitioners should monitor ECHA PFAS restriction finalization, FDA biocompatibility guidance updates, and MIIT dielectric stability specification tightening for early signals requiring forecast revision. Cross-checking against IEA grid infrastructure investment databases and automotive OEM electrification platform announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Light Diffusion Materials Market
Specialty Materials
Solar Backsheet Films Market
Specialty Materials
UK Lab-Grown Diamonds Market
Specialty Materials
Silicone Gel Market
Specialty Materials
Global Beeswax Market
Specialty Materials
Global Cellulose Esters Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Surface Technology Market
Specialty Materials
Electrode Paste Market
Specialty Materials
Specialty Silica Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Global Consumer Foam Market
Specialty Materials
Open Cell Foam Market
Specialty Materials
Global Graphic Film Market
Specialty Materials
Organic Scintillators Market
Specialty Materials
Global PE Films Market