
 Polymer Reinforcing Filler Market | 2026-2036
Polymer Reinforcing Filler Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Reinforcing Filler Market Analytics
The divergence between premium and commodity tiers is hardening as specialty precipitated calcium carbonate and surface-treated kaolin command widening price premiums over uncoated ground calcium carbonate for basic polypropylene compounding. Imerys Group leverages its vertically integrated mineral extraction and surface modification capabilities to sustain margin leadership in automotive under-the-hood applications. Evonik Industries AG differentiates through its silica and silane chemistry portfolio, while Omya International AG anchors global supply for construction-grade PVC profiles through its distributed grinding network.
Polymer reinforcing fillers are particulate or fibrous materials, typically 0.1 to 50 microns in median particle size, dispersed within thermoplastic or thermoset matrices to enhance tensile strength, dimensional stability, and heat deflection temperature. Carbon Black dominates tire and rubber hose formulations where electrical conductivity and abrasion resistance prove critical, though Glass Fibers represent the fastest-expanding category as long-fiber-reinforced thermoplastics penetrate automotive front-end modules. Calcium Carbonate remains the volume anchor in construction films and extruded profiles, while Kaolin concentrates margin pools in wire and cable insulation where dielectric performance commands specification premiums.
EPA emission standards for industrial minerals processing and REACH substance restrictions on crystalline silica content shape product development trajectories and site licensing requirements for compounders operating in North America and Europe. FDA food-contact regulations and ISO 10993 biocompatibility protocols additionally govern fillers entering packaging and medical device channels. Stakeholders must monitor evolving battery enclosure fire-safety standards and recyclate-content mandates, as these will determine which surface chemistries and particle morphologies secure qualification in next-generation polymer formulations.
Market Dynamics
Automotive lightweighting mandates and battery enclosure fire-safety standards are compressing qualification timelines for mineral fillers, forcing compounders to validate surface-treated grades faster than traditional development cycles permit.
Growth Catalysts
- EPA Tier 3 emission standards:Under-the-hood components in US passenger vehicles now require heat-resistant fillers that maintain dimensional stability above 150°C, accelerating specification of precipitated calcium carbonate and surface-modified kaolin.
- Electric vehicle battery housings:Chinese domestic compounding capacity for structural plastics in EV battery enclosures continues scaling, consuming flame-retardant mineral fillers at volumes that reshape regional supply allocations.
- REACH substance restrictions:European crystalline silica thresholds are tightening, pushing compounders toward engineered precipitated grades and synthetic alternatives that bypass natural mineral purity constraints.
Market Restraints
- Energy cost volatility:Precipitated calcium carbonate production depends on natural gas-fired carbonation kilns; European energy price spikes since 2022 have compressed margins for synthetic filler producers.
- Supply concentration in Guangxi Province:Premium-grade kaolin reserves and wet-processing capacity cluster in southern China, exposing automotive compounders to logistics disruptions and concentrated supplier negotiation leverage.
- Technical ceiling in dielectric applications:Kaolin's inherent moisture sensitivity limits its deployment in high-voltage EV cable insulation above 800V, ceding share to engineered silicas and surface-treated aluminas.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic compounding capacity for lightweight structural plastics is underpenetrated; local filler production partnerships can capture import substitution premiums before scale economies mature.
- Bio-based surface modifiers:Fatty acid and silane chemistries derived from agricultural waste streams are converging with mineral processing, enabling carbon footprint claims that differentiate premium grades in European sustainability procurement.
- Direct-to-compounder digital platforms:Specialty filler distributors are bypassing traditional merchant networks, offering lot-traceable, certificate-backed material flows that reduce qualification friction for medical device and food-contact applications.
Industry Challenges
- Surface chemistry talent scarcity:Formulation chemists who understand both silane coupling mechanisms and polymer rheology command compensation premiums that strain mid-tier compounder R&D budgets.
- ISO 10993 biocompatibility timelines:Medical device filler qualifications require 18-24 month cytotoxicity and sensitization protocols, compressing product launch windows against faster-moving automotive and packaging segments.
- Legacy compounding equipment retrofit costs:Long-fiber-reinforced thermoplastic production demands twin-screw extruders with specialized screw geometries; sunk capital in single-screw assets delays Glass Fiber penetration at smaller compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Reinforcing Filler Market |
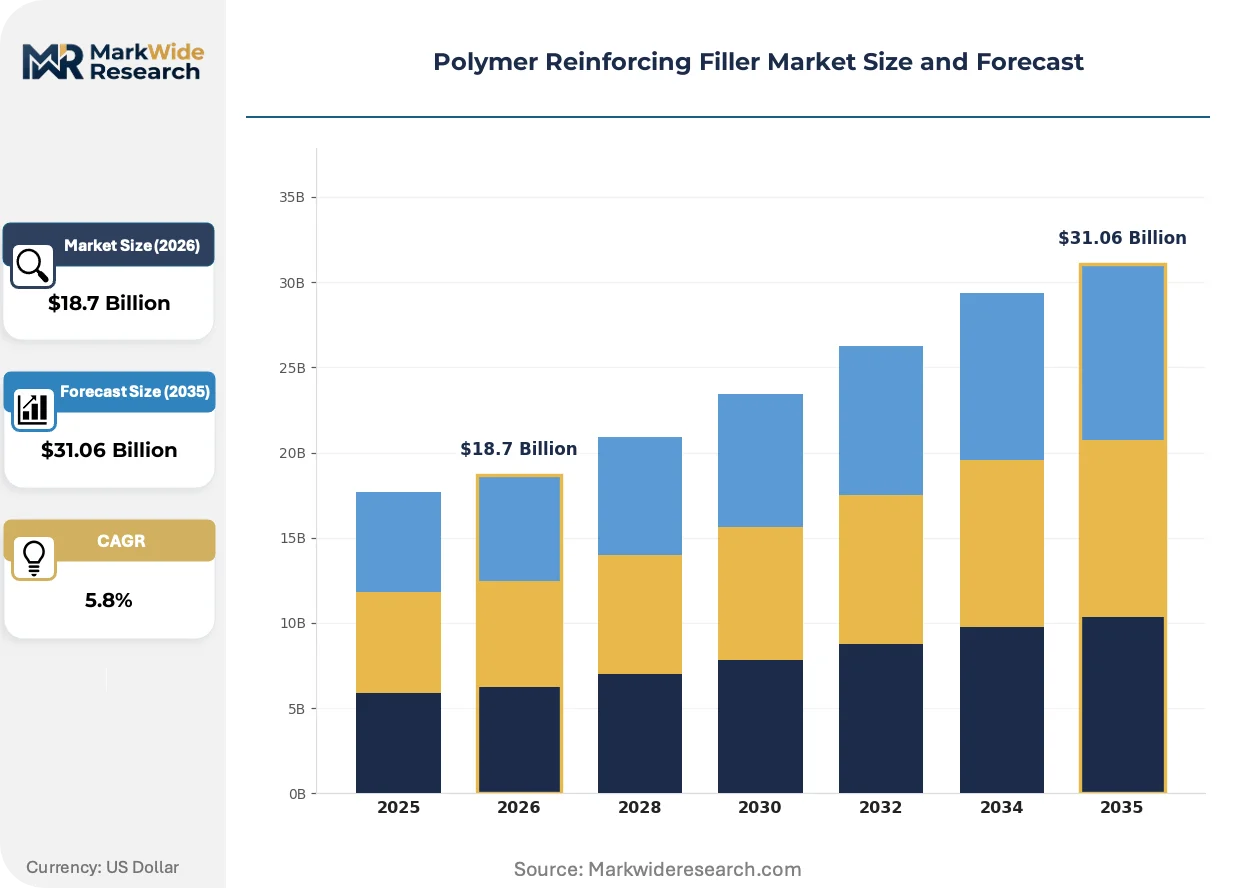
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Black, Calcium Carbonate, Glass Fibers, Kaolin End Use Industry: Automotive, Construction, Consumer Goods, Electronics Form: Powder, Granules, Pellets, Beads Application: Adhesives, Coatings, Compounds, Sealants |
| Companies Covered | Amco Polymers, Omya International AG, Imerys Group, Evonik Industries AG, BASF SE, Minerals Technologies Inc., RTP Company, J.M. Huber Corporation, Hoffmann Mineral, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Reinforcing Filler Market Evolving Landscape
Surface modification chemistry and particle engineering are compressing the performance gap between commodity mineral fillers and premium synthetics, while regulatory pressure on carbon intensity reshapes process technology choices.
Long-fiber-reinforced thermoplastic (LFRT) compounding is modularizing automotive structural component design. Tier-1 suppliers in Germany and the US Midwest are adopting direct-LFT lines that integrate glass roving impregnation with inline mineral filler dosing, cutting intermediate pellet costs. This process architecture is modularizing how compounders configure production assets, enabling rapid grade switches between bumper beams and battery tray substrates without dedicated extrusion campaigns.
REACH authorization requirements for crystalline silica are tightening occupational exposure thresholds across EU member states. Industrial minerals processors must now implement closed-loop dust suppression and real-time airborne monitoring to maintain site licenses. Surface-treated kaolin and precipitated calcium carbonate producers are capturing specification share in French and German wire and cable compounds where legacy ground calcium carbonate faces substitution pressure from occupational health audits.
Automotive OEMs are consolidating approved supplier lists for under-the-hood compounds, compressing qualification cycles from 36 months to 18 months. Tier-2 compounders in Michigan and Stuttgart are responding with pre-validated filler masterbatch platforms that bundle mineral content, stabilizer packages, and processing aids into single-SKU offerings. This specification bundling is most visible in North American powertrain applications where Ford and GM procurement teams now prioritize supplier reduction over unit cost minimization.
Polymer Reinforcing Filler Market Segmentation
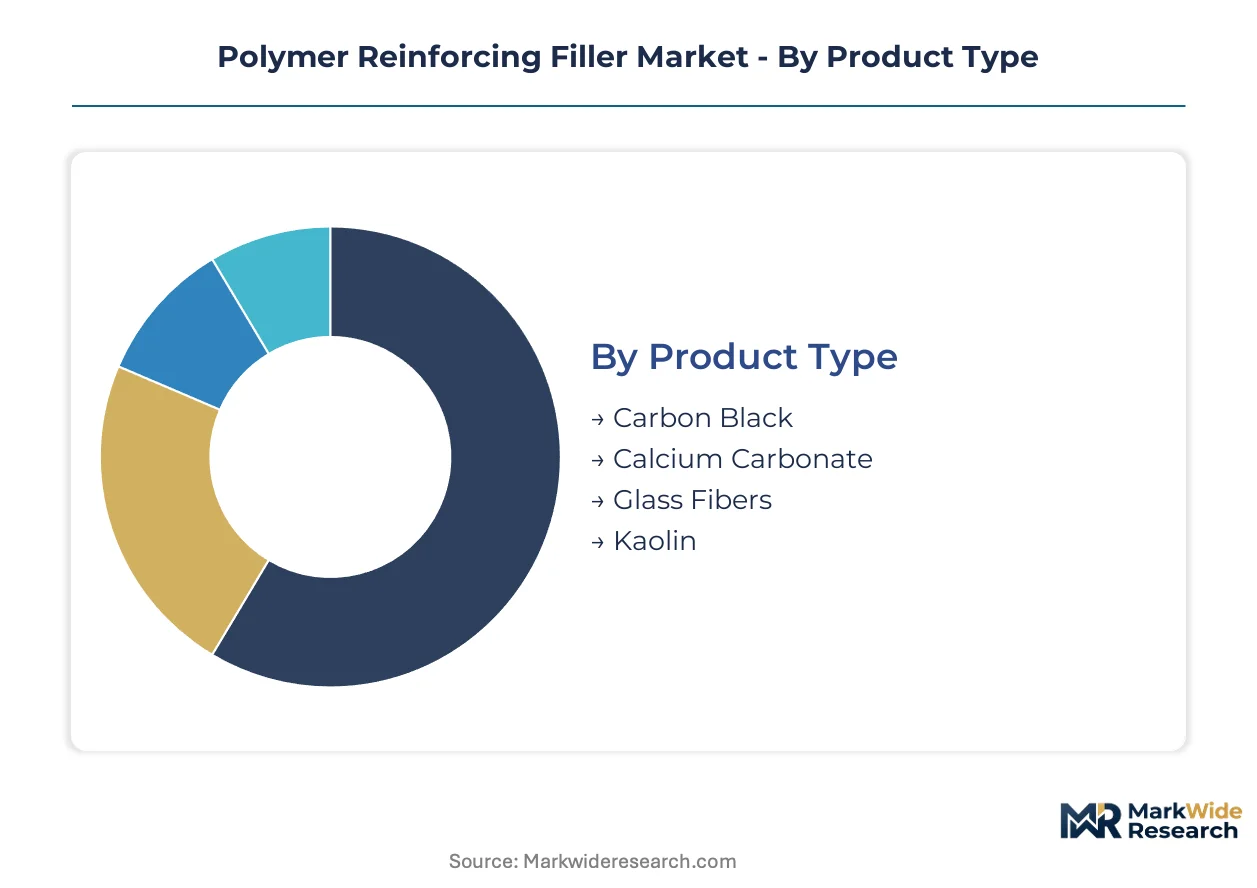
Polymer reinforcing fillers serve radically different performance requirements across tire compounds, battery housings, and medical devices. Specification divergence between commodity ground minerals and engineered precipitated grades creates distinct margin pools that reshape competitive positioning within each segment category.
Product Type:
Customization intensity spans from bulk commodity minerals to precision-engineered synthetics with proprietary surface chemistries.
- Carbon Black:Furnace and thermal blacks with primary particle sizes of 15-100 nanometers deliver electrical conductivity and abrasion resistance in tire treads and industrial rubber. Demand concentrates in US Gulf Coast tire plants where EPA Tier 3 standards now require low-PAH grades for under-the-hood hoses.
- Glass Fibers:E-glass and S-glass rovings with aspect ratios exceeding 100:1 enable long-fiber-reinforced thermoplastics in automotive front-end modules. German Tier-1 suppliers are adopting direct-LFT lines that integrate inline mineral dosing, cutting intermediate pellet costs for bumper beams and battery tray substrates.
- Calcium Carbonate:Ground and precipitated grades from 0.5-10 micron median size anchor volume in construction films and PVC profiles.
- Kaolin:Hydrous and calcined clays with controlled particle aspect ratios serve wire insulation where dielectric performance commands specification premiums.
Leading the category by volume: Calcium Carbonate. Expanding most quickly: Glass Fibers.
End Use Industry:
Margin capture varies sharply between regulated automotive specifications and price-sensitive construction applications.
- Automotive:Under-the-hood components and battery enclosures drive specification of heat-resistant fillers above 150°C. Chinese domestic compounding capacity for EV structural plastics continues scaling, consuming flame-retardant mineral grades that reshape regional supply allocations.
- Construction:Extruded PVC profiles and construction films represent the volume anchor for ground calcium carbonate. European REACH compliance on crystalline silica content is pushing compounders toward engineered precipitated grades that bypass natural mineral purity constraints.
- Consumer Goods:Packaging films and household articles utilize standard mineral loadings for cost reduction and dimensional stability.
- Electronics:High-voltage cable insulation above 800V demands engineered silicas and surface-treated aluminas where kaolin's moisture sensitivity creates technical ceilings.
Dominant revenue concentration: Automotive. Steepest expansion trajectory: Electronics.
Form:
Physical configuration determines handling economics, dust exposure compliance, and compounding line compatibility.
- Powder:Sub-50 micron loose bulk density materials dominate high-volume construction applications. European industrial minerals processors must implement closed-loop dust suppression and real-time airborne monitoring to maintain site licenses under tightening occupational exposure thresholds.
- Pellets:Dust-free concentrate formats with 40-80% mineral loading enable direct feeding into twin-screw extruders. North American powertrain compounders are consolidating approved supplier lists, compressing qualification cycles from 36 months to 18 months for pre-validated masterbatch platforms.
- Granules:Intermediate agglomerated forms balance flowability with dispersibility in batch compounding operations.
- Beads:Spherical engineered formats minimize dust generation in automated handling systems for medical device and food-contact channels governed by FDA regulations and ISO 10993 protocols.
Highest shipment volumes: Powder. Fastest format transition: Pellets.
Application:
Functional requirements in each application dictate surface chemistry specifications and qualification protocols.
- Compounds:Thermoplastic and thermoset matrices with 10-40% mineral loading require tailored silane coupling agents for tensile strength and heat deflection temperature. Automotive OEMs in Michigan and Stuttgart now prioritize supplier reduction over unit cost minimization, bundling mineral content with stabilizer packages into single-SKU offerings.
- Coatings:Architectural and industrial finishes demand controlled particle size distribution for gloss control and barrier properties. Bio-based surface modifiers derived from agricultural waste streams are converging with mineral processing to enable carbon footprint claims in European sustainability procurement.
- Adhesives:Gap-filling and rheology control applications utilize thixotropic mineral grades with specific surface area targets.
- Sealants:Construction and automotive joint sealers require moisture-resistant surface treatments for durability in exposed conditions.
Primary volume driver: Compounds. Gaining share fastest: Coatings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangzhou anchors the world's densest concentration of polymer filler compounding capacity, with the Pearl River Delta corridor consuming engineered mineral grades for electric vehicle battery enclosures at volumes that reshape global supply allocations.
China
Domestic compounding capacity for EV structural plastics scales rapidly in Guangxi Province, where premium kaolin wet-processing clusters serve automotive under-the-hood specifications. MEE enforcement of dual carbon goals tightens emission thresholds for precipitated calcium carbonate kilns. Zhejiang Province chemical parks are integrating surface modification lines with carbon capture retrofits to maintain operating licenses.
Germany
REACH crystalline silica thresholds push wire and cable compounders toward engineered precipitated grades in Baden-Württemberg automotive supplier corridors. KBA vehicle certification protocols now incorporate filler thermal stability documentation for powertrain components. Stuttgart Tier-1 suppliers compress qualification cycles to 18 months through pre-validated masterbatch platforms.
United States
EPA Tier 3 standards mandate heat-resistant fillers above 150°C for under-the-hood hoses, concentrating demand in Michigan powertrain corridors. NHTSA safety protocols for battery enclosures accelerate flame-retardant mineral validation timelines. Gulf Coast carbon black producers invest in low-PAH furnace lines to secure automotive qualification.
India
Automotive PLI scheme incentives attract compounding investments for lightweight structural plastics in Maharashtra and Gujarat industrial corridors. BIS certification timelines for construction-grade PVC profiles extend 12-18 months, favoring established precipitated carbonate importers. Tamil Nadu chemical parks develop surface treatment capacity to capture import substitution premiums.
Polymer Reinforcing Filler Market Competitive Landscape
Premium-margin players sit above commodity-margin players across surface chemistry sophistication and qualification speed, with the market consolidating around three tiers: integrated mineral processors with captive extraction, specialty chemical houses with silane coupling expertise, and regional grinding operations serving construction volume. Archetypes include vertically integrated mineral majors, precision surface modification specialists, and distributed grinding networks. Competitive moves center on M&A for mineral reserve access and partnerships with compounders for pre-validated masterbatch platforms.
Within the integrated mineral processing tier, Imerys Group and Omya International AG exemplify scale-driven archetypes with European headquarters structures. Evonik Industries AG occupies a position among specialty chemical houses where silane and silica chemistry portfolios anchor premium-tier positioning. These three entities represent distinct strategic vectors: mineral extraction integration, surface chemistry specialization, and global distribution density.
| Leading Market Players |
|---|
| Amco Polymers |
| Omya International AG |
| Imerys Group |
| Evonik Industries AG |
| BASF SE |
| Minerals Technologies Inc. |
| RTP Company |
| J.M. Huber Corporation |
| Hoffmann Mineral |
| Others |
Value Network & Pricing Analysis
Captive mineral extraction in Guangxi Province and Zhejiang chemical parks anchors both supply security and pricing power for precipitated calcium carbonate and surface-treated kaolin producers serving automotive under-the-hood specifications. European compounders absorb widening premiums for engineered grades as REACH crystalline silica restrictions eliminate lower-cost natural mineral alternatives from qualified supplier lists.
Pricing Analysis
Value-based pricing anchored to thermal stability performance above 150°C separates premium precipitated calcium carbonate from commodity ground grades in automotive powertrain applications. Three-tier pricing structure across automotive-certified, construction-grade, and packaging-economy levels reflects certification burden and surface chemistry sophistication. Cost compression in European synthetic filler production intensifies because natural gas-fired carbonation kilns face energy price volatility. Construction compounders in extruded PVC profiles exhibit highest price sensitivity, while medical device channels governed by ISO 10993 protocols accept substantial premiums for lot-traceable, certificate-backed material flows.
Supply Chain Analysis
High-purity kaolin feedstock rests on wet-processing clusters concentrated in Guangxi Province, China, with secondary dependence on Brazilian sedimentary deposits and US Georgia sedimentary reserves. Synthetic precipitated calcium carbonate production draws from limestone quarries, carbon dioxide industrial sources, and specialty silane coupling agents. Single-source vulnerability in Guangxi premium-grade reserves exposes automotive compounders to logistics disruptions and concentrated supplier negotiation leverage. Distribution runs through merchant mineral networks and emerging direct-to-compounder digital platforms serving medical device and food-contact channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is accelerating as REACH compliance costs and qualification timeline compression force sub-scale grinding operations toward exit or acquisition. Surface chemistry talent scarcity and capital requirements for closed-loop dust suppression systems discriminate against mid-tier compounders lacking integrated mineral extraction or specialty chemical partnerships.
For Market Incumbents: Deepen backward integration into Guangxi kaolin reserves or Zhejiang chemical park surface modification capacity to defend margin pools against synthetic silica substitution in high-voltage cable insulation. Acquire regional grinding operations in India's Maharashtra and Gujarat corridors before PLI scheme incentives mature local competition. Prioritize pre-validated masterbatch platform investments that compress automotive OEM qualification cycles from 36 months to 18 months.
For New Entrants and Emerging Players: Begin with bio-based surface modifier production partnerships in European agricultural waste stream convergence, targeting sustainability procurement premiums in French and German wire and cable compounds. Enter India's Tamil Nadu chemical parks with surface treatment capacity to capture import substitution premiums in construction-grade PVC profiles before BIS certification timelines favor established importers. Lead with carbon footprint claims and certificate-backed material flows that reduce qualification friction for medical device channels.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty chemical houses with silane coupling expertise and captive mineral reserves, as automotive OEM supplier list consolidation rewards scale and qualification speed. Long-term viability favors entities with integrated extraction-to-surface-modification capabilities serving battery enclosure fire-safety standards and recyclate-content mandates. Watch for inflection in battery enclosure compound qualification volumes as NHTSA safety protocols and Chinese domestic EV production scaling reshape regional supply allocations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Reserves | Captive kaolin extraction in Guangxi Province secures supply continuity for automotive under-the-hood specifications. |
| Pre-Validated Masterbatch Platform Launch | Single-SKU offerings bundling mineral content and stabilizers compress Ford and GM procurement qualification cycles. |
| Bio-Based Surface Modifier Development | Fatty acid chemistries from agricultural waste streams enable REACH-compliant carbon footprint claims in European sustainability procurement. |
| Direct-to-Compounder Digital Platform | Lot-traceable material flows reduce ISO 10993 qualification friction for medical device filler applications. |
| Closed-Loop Dust Suppression Retrofit | Real-time airborne monitoring maintains EU site licenses under tightening REACH crystalline silica occupational exposure thresholds. |
Research Methodology
Independent corroboration across plant managers at precipitated calcium carbonate facilities, procurement leads at German Tier-1 automotive suppliers, and distribution channel partners in Pearl River Delta chemical parks underwrites the qualitative findings. Technical R&D directors at wire and cable compounders in Baden-Württemberg provided formulation specification detail. Secondary validation drew from customs and trade data tracking mineral filler flows, SEC 10-K filings of integrated mineral processors, and Cefic reports on European industrial minerals capacity. Bottom-up volume builds across product type, end-use industry, and regional production hub segments triangulate against top-down macroeconomic anchors.
Comparable-period anchoring to historical automotive production cycles, construction spending patterns, and EV battery enclosure deployment rates structured the projection horizon. Segmentation dimensions modeled include filler grade tier, end-use industry, physical form, and regional compounding capacity cluster. CAGRs derive from regression analysis against named demand drivers including EPA Tier 3 emission standards, REACH substance restrictions, and Chinese dual carbon goal enforcement. Industry-specific forecast inputs incorporate MEE emission threshold trajectories for carbonation kilns and KBA thermal stability documentation requirements for powertrain components.
Underlying measurement precision varies by segment; automotive and electronics applications carry tighter precision than construction-grade volume estimates due to specification documentation density. Forecasts reflect documented assumptions on regulatory enforcement timing, energy cost trajectories, and battery enclosure fire-safety standard adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyglycerates Market
Polymers & Resins
Middle East Polymer Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Cast Polymers Market
Polymers & Resins
Polysorbate Market
Polymers & Resins
Europe Geopolymer Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Polycide Market
Polymers & Resins
China Geopolymer Market
Polymers & Resins
Ethylene Acrylic Acid (EAA) Copolymers Market
Polymers & Resins
Canada Bioresorbable Polymers Market
Polymers & Resins
1-Hexene Based Polyethylene Market
Polymers & Resins
Ionomer Resins Market
Polymers & Resins
Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
Biobased Thermosetting Polymers Market
Polymers & Resins
Global Polyphthalamide Market