
 Activated Carbon Market | 2026-2036
Activated Carbon Market Size, Share, and Industry Trends Forecast 2026-2036
Activated Carbon Market Intelligence
Modular bulk-delivery systems is consolidating buyer preference in municipal water treatment, shifting procurement from bagged shipments toward silo-stored granular activated carbon with automated dosing. Calgon Carbon Corporation leverages its North American reactivation infrastructure to anchor long-term municipal contracts. Kuraray Co., Ltd dominates specialty coal-based grades for industrial gas refining through integrated Japanese manufacturing. Jacobi Carbons extends its coconut-shell supply chain across Sri Lankan and Indonesian processing facilities to compete on renewable feedstock credentials.
Activated carbon comprises a microporous carbonaceous material produced through physical or chemical activation of biomass, coal, or coconut-shell precursors, typically exhibiting surface areas exceeding 500 square meters per gram and pore volumes optimized for contaminant adsorption. Its primary commercial purpose centers on removing organic compounds, chlorine, and volatile substances from water, air, and process streams across industrial and municipal systems. Granular activated carbon commands the largest volume share in water treatment infrastructure, while powdered activated carbon generates faster growth in seasonal or emergency remediation scenarios where rapid deployment outweighs long-term bed-life economics. Extruded activated carbon occupies premium positioning in fixed-bed industrial gas applications where low pressure-drop geometry justifies higher unit pricing.
The United States Environmental Protection Agency regulates activated carbon under the Safe Drinking Water Act and Stage 2 Disinfectants and Disinfection Byproducts Rule, mandating enhanced surface water treatment that directly expands GAC contactor installations. The European Chemicals Agency classifies certain spent activated carbon streams under REACH waste protocols, shaping reactivation service economics and cross-border logistics for DESOTEC Activated Carbon and Donau Carbon operations. India's Central Pollution Control Board enforces effluent standards for textile and chemical clusters that drive powdered activated carbon consumption in Gujarat and Tamil Nadu industrial zones. Stakeholders must monitor feedstock cost divergence between coconut-shell and coal-based precursors while evaluating reactivation network proximity against virgin carbon supply security.
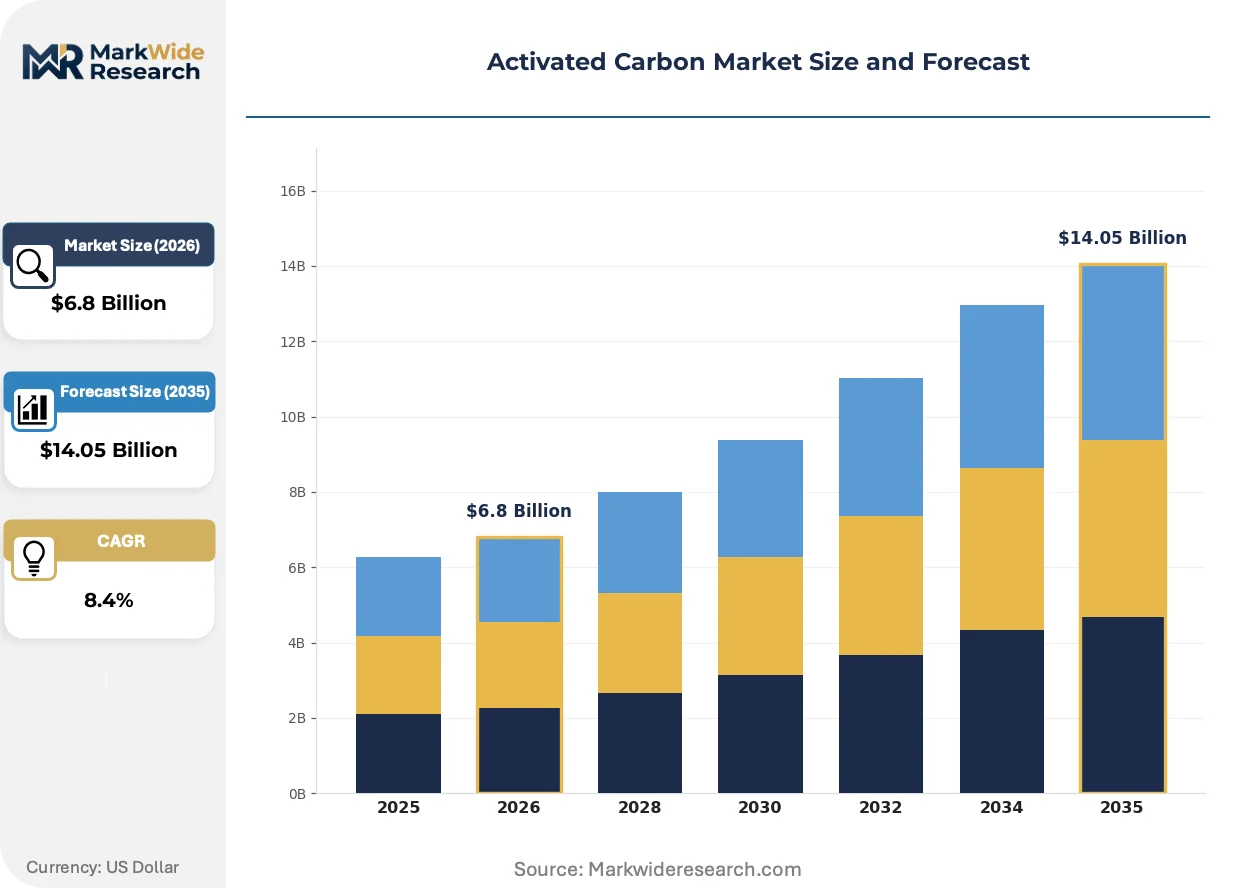
Market Dynamics
Municipal water utilities are consolidating procurement around automated bulk-delivery systems, compressing spot-market bagged carbon volumes while locking in decade-long granular activated carbon contracts with integrated reactivation providers.
Growth Catalysts
- EPA Stage 2 Disinfectants Rule:US surface water treatment mandates are expanding GAC contactor installations across Midwestern and Southeastern utilities, creating durable infrastructure demand.
- Lithium-ion battery manufacturing:Semiconductor and cell fabrication facilities in East Asian industrial clusters are consuming specialized powdered grades for ultra-pure process water.
- Coconut-shell feedstock optimization:Steam-activation improvements across Sri Lankan and Indonesian processing facilities are lowering unit production costs for renewable-origin carbon.
Market Restraints
- Feedstock cost divergence:Coconut-shell prices fluctuate with South Asian agricultural yields while coal-based precursor costs track energy markets, creating margin compression for blended-product manufacturers.
- Spent carbon logistics:European REACH waste protocols classify certain reactivation streams as hazardous, adding cross-border transport complexity and thermal reprocessing facility siting constraints.
- Pressure-drop limitations:Granular activated carbon bed geometry imposes flow-rate ceilings that extruded carbon alternatives circumvent in high-volume gas treatment applications.
Strategic Opportunities
- Modular reactivation infrastructure:Containerized thermal regeneration units can service remote US municipal systems without long-haul spent carbon transport, reducing total cost of ownership.
- Per- and polyfluoroalkyl substances remediation:Emerging EPA drinking water standards for PFAS compounds are opening specialized carbon formulation development for forensic treatment scenarios.
- Industrial cluster service contracts:Gujarat and Tamil Nadu textile zones under India's Central Pollution Control Board effluent mandates present concentrated demand for powdered carbon tolling services.
Industry Challenges
- Reactivation technician scarcity:Thermal regeneration facility operations require specialized combustion engineering expertise that outpaces vocational training program output in North America and Europe.
- Legacy contactor retrofit complexity:Municipal utilities with decades-old concrete basin infrastructure face structural modification costs when upgrading to automated carbon handling and density-controlled bed management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Activated Carbon Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular Activated Carbon, Powdered Activated Carbon, Extruded Activated Carbon, Activated Carbon Cloth Application: Water Treatment, Air Purification, Food & Beverage Processing, Industrial Gas Refining End User: Municipalities, Chemical Manufacturers, Pharmaceuticals, Automotive Form: Pellets, Powder, Beads, Fibers |
| Companies Covered | Kuraray Co., Ltd, DESOTEC Activated Carbon, Calgon Carbon Corporation, CPL Activated Carbon, Haycarb PLC, Jacobi Carbons, Donau Carbon, Oxbow Activated Carbon, Norit Activated Carbon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Activated Carbon Market Strategic Shifts & Innovations
Steam-activation process intensification and feedstock pretreatment chemistry are compressing production energy requirements while expanding micropore tunability for contaminant-specific applications.
Electrochemical regeneration of spent activated carbon is converging with distributed water treatment architectures, enabling on-site reactivation without thermal infrastructure. Semiconductor fabrication facilities in Taiwan and South Korea are piloting these systems for closed-loop ultrapure water circuits. The technology is converging with modular system design to displace centralized reactivation logistics for high-value industrial streams.
The European Chemicals Agency's evolving REACH waste classification protocols are redefining spent carbon handling economics across German and Belgian industrial corridors. Cross-border reactivation service networks face new documentation and tracking requirements that favor integrated producer-service provider structures over merchant reactivation merchants. Specialty chemical manufacturers are responding by consolidating multi-site contracts with single-source carbon lifecycle managers.
Water utility procurement departments are unbundling carbon supply from reactivation services, creating separate competitive bidding events that expose incumbent integrated providers to disintermediation. This pattern concentrates in US municipal systems with professionalized supply chain functions and transparent e-procurement platforms. The shift compresses contract durations from ten-year frameworks toward three-year supply agreements with annual reactivation option exercises.
Activated Carbon Market Segmentation
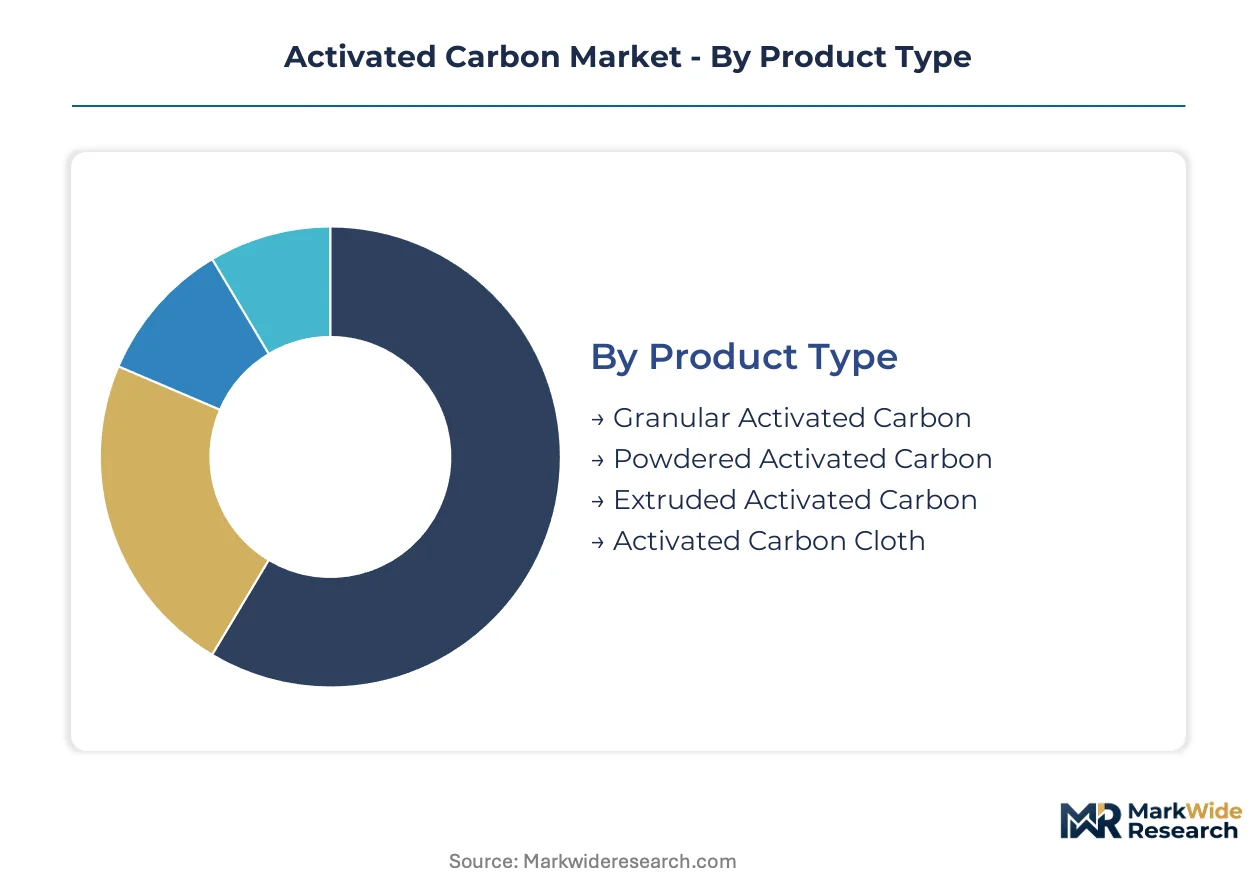
Product differentiation in activated carbon tracks directly to regeneration economics and contaminant specificity. Buyers select grades based on pore structure, mechanical durability, and compatibility with existing contactor infrastructure rather than commodity pricing alone.
Product Type:
Upgrade cycles for municipal contactor systems favor granular formats with extended bed life, while semiconductor fabs and battery plants drive rapid format experimentation for process water purity.
- Granular Activated Carbon:Irregular particle geometry (0.2-5mm) optimized for fixed-bed adsorption with high mechanical strength for repeated backwashing cycles. Municipal water utilities across the United States Midwest specify this format for EPA-mandated disinfection byproduct removal, locking in decade-long supply contracts with integrated reactivation providers.
- Powdered Activated Carbon:Fine particulate structure (typically 80% passing 325 mesh) enabling rapid dispersion for seasonal taste-and-odor events or emergency contaminant spikes. East Asian lithium-ion battery manufacturing clusters in South Korea and Taiwan consume specialized ultra-pure grades for electrode material washing, where metallic contamination tolerances approach parts-per-billion thresholds.
- Extruded Activated Carbon:Cylindrical pellet geometry engineered for low pressure-drop performance in high-flow gas treatment systems.
- Activated Carbon Cloth:Woven fiber matrix delivering conformable adsorption surfaces for protective apparel and point-of-use filtration devices.
Granular activated carbon sits at the top of the volume ranking, with powdered activated carbon climbing the fastest.
Application:
Cost tier differentiation separates infrastructure-heavy municipal installations from discretionary industrial purification spending that fluctuates with manufacturing output.
- Water Treatment:Surface water filtration, groundwater remediation, and process water polishing across municipal and industrial systems. US utilities facing EPA Stage 2 Disinfectants Rule mandates are expanding GAC contactor capacity in Ohio, Illinois, and Georgia, driving durable equipment procurement rather than spot carbon purchases.
- Air Purification:Volatile organic compound capture, odor control, and indoor air quality management in commercial and residential buildings.
- Food & Beverage Processing:Decolorization of edible oils, sugar refining, and alcoholic beverage filtration requiring food-grade certification and low extractable protocols.
- Industrial Gas Refining:Hydrogen purification, carbon dioxide recovery, and natural gas sweetening in petrochemical and energy infrastructure.
Water treatment commands the largest installed base, with air purification gaining share fastest in commercial building retrofits.
End User:
Customer type determines contract structure, with public procurement transparency contrasting proprietary industrial specifications.
- Municipalities:Public water utilities operating under regulatory compliance timelines with bonded capital financing for infrastructure.
- Chemical Manufacturers:Process-intensive operations requiring carbon for solvent recovery, catalyst support, and effluent polishing in Texas and Louisiana petrochemical corridors.
- Pharmaceuticals:cGMP-validated carbon grades for active pharmaceutical ingredient purification and water-for-injection systems.
- Automotive:Evaporative emission control canisters and cabin air filtration modules in vehicle manufacturing supply chains.
Municipalities anchor procurement volume, with pharmaceutical applications expanding most quickly on regulatory purity requirements.
Form:
Supply concentration for coconut-shell versus coal precursors shapes form availability and pricing volatility across manufacturing regions.
- Pellets:Extruded cylindrical geometry (1-5mm diameter) for packed-bed gas phase applications with controlled pressure-drop characteristics.
- Powder:Pulverized carbon for slurry-fed systems and rapid-response dosing in seasonal water quality events.
- Beads:Spherical activated carbon with optimized fluidization properties for moving-bed and countercurrent regeneration systems.
- Fibers:Activated carbon fiber formats for specialized adsorption and electrochemical regeneration applications.
Pellets dominate gas treatment specifications, with beads gaining traction in continuous regeneration process designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The activated carbon industry traces its modern industrial scale to Pittsburgh, Pennsylvania, where Calgon Carbon pioneered granular activated carbon production for municipal water treatment in the 1940s. This North American foundation established the technical standards and reactivation service models that subsequently diffused to European and Asian manufacturing centers.
United States
Midwestern and Southeastern utilities drive granular activated carbon procurement under EPA Stage 2 Disinfectants Rule mandates. The Safe Drinking Water Act enforcement creates durable infrastructure demand across Ohio, Illinois, and Georgia. Modular bulk-delivery systems are consolidating procurement patterns in municipal water districts surrounding Chicago and Atlanta.
Germany
Industrial gas refining and chemical manufacturing clusters consume specialty coal-based activated carbon grades. The European Chemicals Agency's REACH waste protocols shape cross-border reactivation logistics for spent carbon streams. The Rhine-Ruhr industrial corridor hosts integrated producer-service provider structures that manage multi-site carbon lifecycle contracts.
Japan
Semiconductor fabrication facilities in the Kanto and Kansai regions demand ultra-pure powdered activated carbon for process water systems. METI industrial policy supports closed-loop ultrapure water circuit development. Taiwan and South Korean battery manufacturers source specialized grades through Japanese trading house networks.
India
Textile and chemical clusters in Gujarat and Tamil Nadu drive powdered activated carbon consumption under Central Pollution Control Board effluent standards. Steam-activation process improvements across processing facilities are lowering unit production costs. Ahmedabad and Chennai industrial zones present concentrated demand for carbon tolling services.
Sri Lanka
Coconut-shell feedstock optimization anchors renewable-origin carbon production for export markets. Jacobi Carbons extends processing infrastructure across Sri Lankan and Indonesian facilities to compete on feedstock credentials. Colombo-based operations supply granular grades to European and North American municipal contractors.
Activated Carbon Market Key Industry Players
Premium-margin players sit above commodity-margin players across reactivation service integration and feedstock certification dimensions. The vendor base stratifies into three tiers: integrated multinational corporations with thermal regeneration networks, regional specialists controlling coconut-shell supply chains, and merchant carbon traders without reactivation assets. Two dominant competitive moves define current positioning: backward integration into coconut-shell processing in South Asia and strategic partnerships between municipal utilities and reactivation service providers.
Within the integrated multinational tier, Kuraray Co., Ltd and Calgon Carbon Corporation exemplify divergent geographic anchoring strategies. Kuraray represents Japanese coal-based specialty grade dominance through integrated domestic manufacturing. Calgon Carbon occupies North American reactivation infrastructure leadership with Pittsburgh historical roots. Jacobi Carbons sits within the renewable feedstock specialist archetype, leveraging Sri Lankan and Indonesian coconut-shell supply chain control.
| Leading Market Players |
|---|
| Kuraray Co., Ltd |
| DESOTEC Activated Carbon |
| Calgon Carbon Corporation |
| CPL Activated Carbon |
| Haycarb PLC |
| Jacobi Carbons |
| Donau Carbon |
| Oxbow Activated Carbon |
| Norit Activated Carbon |
| Others |
Cost & Logistics Intelligence
EPA Stage 2 Disinfectants Rule compliance gates both qualified supply and premium-tier pricing access for municipal water treatment utilities, forcing carbon producers to certify reactivation infrastructure before bidding on decade-long GAC contactor contracts. Buyers without bonded capital financing for automated bulk-delivery systems face exclusion from procurement pools regardless of unit price competitiveness.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates reactivation-integrated municipal contracts from spot-market bagged shipments and merchant-traded commodity grades. Price differentiation tracks feedstock certification, with coconut-shell renewable-origin carbon commanding premiums over coal-based precursors. Pricing pressure stems from steam-activation energy cost compression in Sri Lankan processing facilities eroding margin buffers for North American reactivation providers. Municipal utilities exhibit lowest price sensitivity due to regulatory compliance timelines, while textile processors in Gujarat industrial zones prioritize cost-per-kg above bed-life economics.
Supply Chain Analysis
Single-source vulnerability sits with coconut-shell feedstock dependence on Sri Lankan and Indonesian agricultural yields, where monsoon variability disrupts precursor availability without geographic diversification. Raw material dependencies include coconut-shell char, bituminous coal, and phosphoric acid for chemical activation grades. Supply chain risk centers on European REACH waste protocol restrictions that reclassify spent carbon streams as hazardous, blocking cross-border thermal reprocessing logistics. Distribution runs through integrated producer-service provider structures managing cradle-to-grave carbon lifecycle contracts rather than merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, justified by municipal procurement departments unbundling carbon supply from reactivation services and demanding certified infrastructure performance over commodity pricing.
For Market Incumbents: Anchor reactivation network proximity against virgin carbon supply security by expanding containerized thermal regeneration units near Midwestern US municipal clusters. Defend against merchant reactivation disintermediation by locking multi-site lifecycle management contracts with European chemical manufacturers facing REACH documentation burdens. Prioritize coconut-shell feedstock certification investments to capture renewable-origin premiums in North American public procurement. For New Entrants and Emerging Players: E-procurement platform specialization offers white-space entry into US municipal systems with professionalized supply chain functions and transparent bidding requirements. Target Gujarat and Tamil Nadu textile zones under Central Pollution Control Board effluent mandates for powdered carbon tolling services, where incumbent reactivation infrastructure remains underdeveloped. Pursue modular bulk-delivery system partnerships as the primary go-to-market angle rather than commodity grade competition. For Investors and Strategic Acquirers: Valuations sit cheapest among merchant carbon traders without reactivation assets, exposed to procurement unbundling trends that compress contract durations from ten-year frameworks toward three-year supply agreements. Long-term viability favors integrated producer-service providers with thermal regeneration networks and coconut-shell supply chain control. Watch EPA PFAS drinking water standard finalization as the inflection signal for specialized carbon formulation development demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coconut-Shell Processing | Sri Lankan and Indonesian feedstock control secures renewable-origin certification premiums in European procurement. |
| Modular Reactivation Infrastructure Deployment | Containerized thermal regeneration units reduce total cost of ownership for remote US municipal water systems. |
| PFAS Specialization Formulation Development | Forensic treatment carbon grades capture emerging EPA drinking water compliance demand from utilities. |
| Multi-Site Lifecycle Management Contracts | Integrated carbon supply and reactivation services defend against procurement unbundling disintermediation. |
| Steam-Activation Process Intensification | Energy requirement compression expands micropore tunability for contaminant-specific industrial applications. |
Research Approach
Direct dialogue with municipal water utility procurement directors, thermal regeneration facility operations managers, coconut-shell processing plant supervisors, and textile zone effluent compliance officers grounded qualitative findings in operational reality. Secondary validation drew from EPA Safe Drinking Water Act enforcement records, Central Pollution Control Board effluent standard filings, European Chemicals Agency REACH waste protocol updates, and customs trade data tracking coconut-shell char movements. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the activated carbon value chain.
Segment-level projections across product type, application, end user, and form dimensions fed into consolidated market estimates over the projection horizon. CAGRs were derived from regression analysis against regulatory enforcement timelines and industrial cluster expansion patterns. Forecast inputs incorporated EPA Stage 2 Disinfectants Rule implementation pace, lithium-ion battery manufacturing capacity buildouts in East Asia, and steam-activation energy efficiency improvement curves.
Feedstock cost divergence, regulatory reclassification events, and reactivation technician scarcity are the dominant revision risks that could shift trajectory materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Residential Filters Market
Filters
ePTFE Filter Film Market
Filters
Single-Use Filtration Assemblies Market
Filters
Global Gas Phase Filtration Market
Filters
Global Lamella Clarifier Market
Filters
Furnace Filters Market
Filters
Filter Media Market
Filters
Round Plate Filter Press Market
Filters
Europe Activated Carbon Market
Filters
Polishing Filter Market
Filters
Drum Filters Market
Filters
Air Filtration Media Market
Filters
United States Activated Carbon Market
Filters
Global Baghouse Filters Market
Filters
Zeolite Adsorbents Market
Filters
Filter Bag Market