
 Commercial Oven for Bakery Market | 2026-2036
Commercial Oven for Bakery Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Oven for Bakery Market Outlook
Italy is reconfiguring European supply dynamics through its concentration of specialty oven fabrication in Emilia-Romagna and Lombardy. Middleby Corporation leverages its multi-brand portfolio to control distribution across North American foodservice channels. Rational specializes in combi-oven technology leadership, extending its engineering footprint into bakery-specific thermal management systems. Unox anchors Mediterranean markets with energy-efficient convection platforms designed for high-volume artisan production.
A commercial oven for bakery denotes heavy-duty thermal processing equipment engineered for dough proofing, baking, and finishing at temperatures typically spanning 150°C to 300°C, constructed from stainless steel chambers with reinforced insulation and precision airflow or radiant heat distribution. These units serve industrial and retail baking operations requiring consistent crust formation, crumb structure, and throughput volume across extended production cycles. Convection ovens lead installed base metrics due to versatile airflow adaptability across bread, pastry, and confectionery applications, while rack ovens capture the fastest expansion trajectory in central commissary and wholesale bakery settings. Electric heating technology dominates new installations in urban European and North American facilities where emissions ordinances restrict gas combustion, though gas-fired systems sustain margin pools in cost-sensitive emerging markets with established natural gas infrastructure.
The U.S. Department of Energy and the EPA shape North American product standards through commercial kitchen equipment efficiency mandates and emissions thresholds that filter market access for imported combustion-based systems. In Europe, the Ecodesign Directive and F-Gas Regulation compel manufacturers to reformulate insulation materials and refrigerant-dependent steam injection systems, while CE marking requirements standardize electrical safety protocols across member states. Stakeholders must monitor evolving carbon border adjustment mechanisms and building code electrification timelines to calibrate technology roadmaps and geographic prioritization decisions.
Market Dynamics
Energy efficiency mandates from the U.S. Department of Energy are compressing product lifecycles across the installed base, forcing accelerated replacement schedules for thermal insulation and burner assemblies in commercial bakery operations.
Growth Catalysts
- Electrification Mandates:Urban emissions ordinances in New York City and San Francisco are prohibiting new gas hookups, redirecting capital toward electric convection and rack oven installations in commissary bakeries.
- Artisan Bakery Expansion:Regional chains across the U.S. and Germany are scaling production footprints to capture consumer preference for freshly baked goods, sustaining equipment procurement velocity.
- Steam Injection Advancement:Precision humidity control systems are enabling consistent crust formation in high-volume operations, expanding addressable demand from industrial wholesale into retail craft segments.
Market Restraints
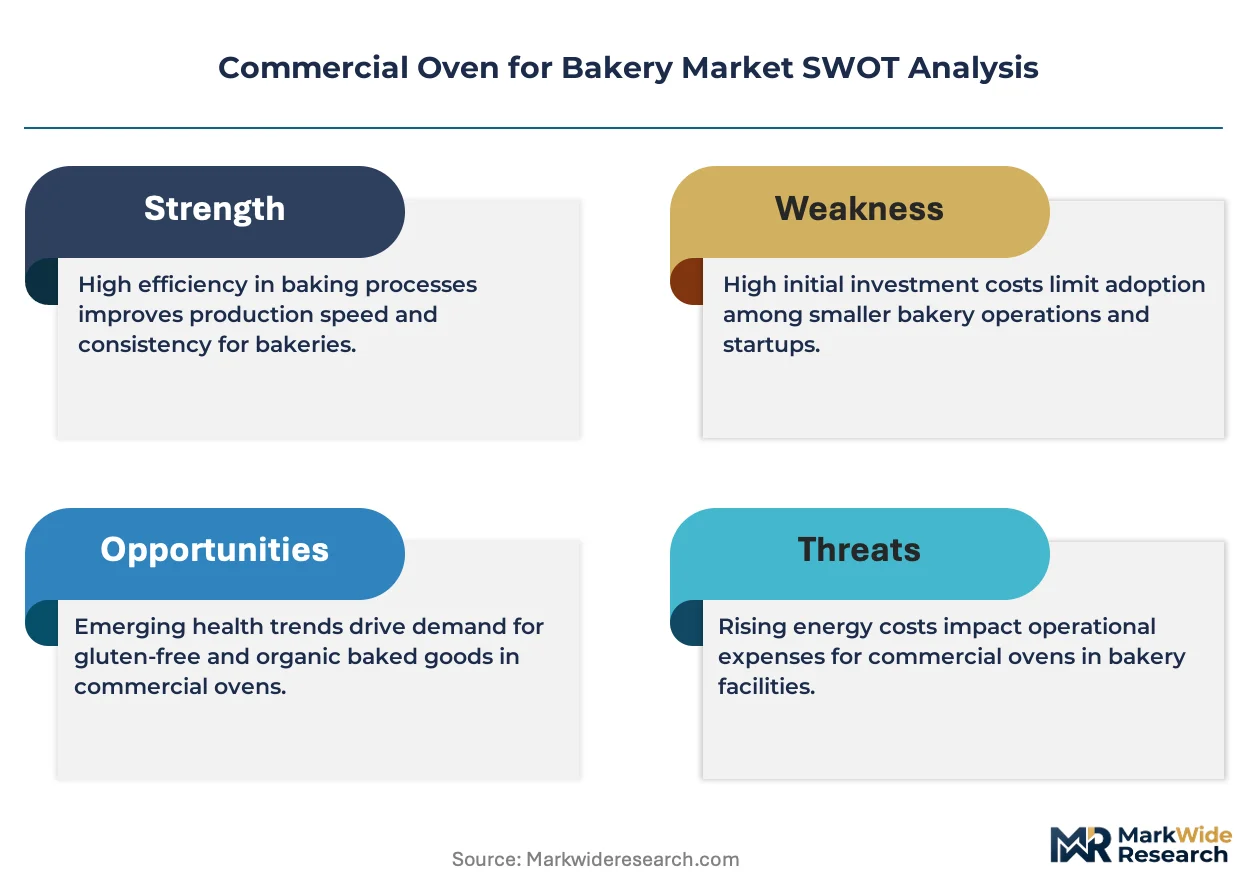
- Stainless Steel Input Volatility:Chamber fabrication depends on nickel and chromium supply chains concentrated in Indonesian and South African mining operations, exposing manufacturers to commodity price swings.
- Combustion System Certification Friction:EPA emissions thresholds for gas-fired ovens create extended validation timelines, delaying market access for imported European equipment into North American facilities.
- Refrigerant-Dependent Steam Systems:F-Gas Regulation phase-down schedules in Europe are forcing reformulation of steam injection technologies, raising engineering costs for cross-border product platforms.
Strategic Opportunities
- India Central Commissary Buildout:Organized retail and quick-service bakery chains are consolidating production into centralized facilities, creating demand for high-throughput rack and tunnel oven configurations.
- Carbon Border Adjustment Positioning:EU Green Deal implementation is creating first-mover advantage for manufacturers with verified low-carbon insulation supply chains and electrified product portfolios.
- IoT-Enabled Predictive Maintenance:Thermal sensor arrays and cloud-connected control systems are converging with traditional oven architecture, enabling subscription-based service revenue streams from installed base monitoring.
Industry Challenges
- Thermal Engineering Talent Scarcity:Precision airflow design and combustion optimization require specialized expertise that outpaces vocational training pipeline output in both European and North American labor markets.
- Legacy Control System Integration:Bakery operators with decade-old programmable logic controllers face compatibility barriers when retrofitting energy-efficient burner management systems, extending sales cycles and implementation risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Oven for Bakery Market |
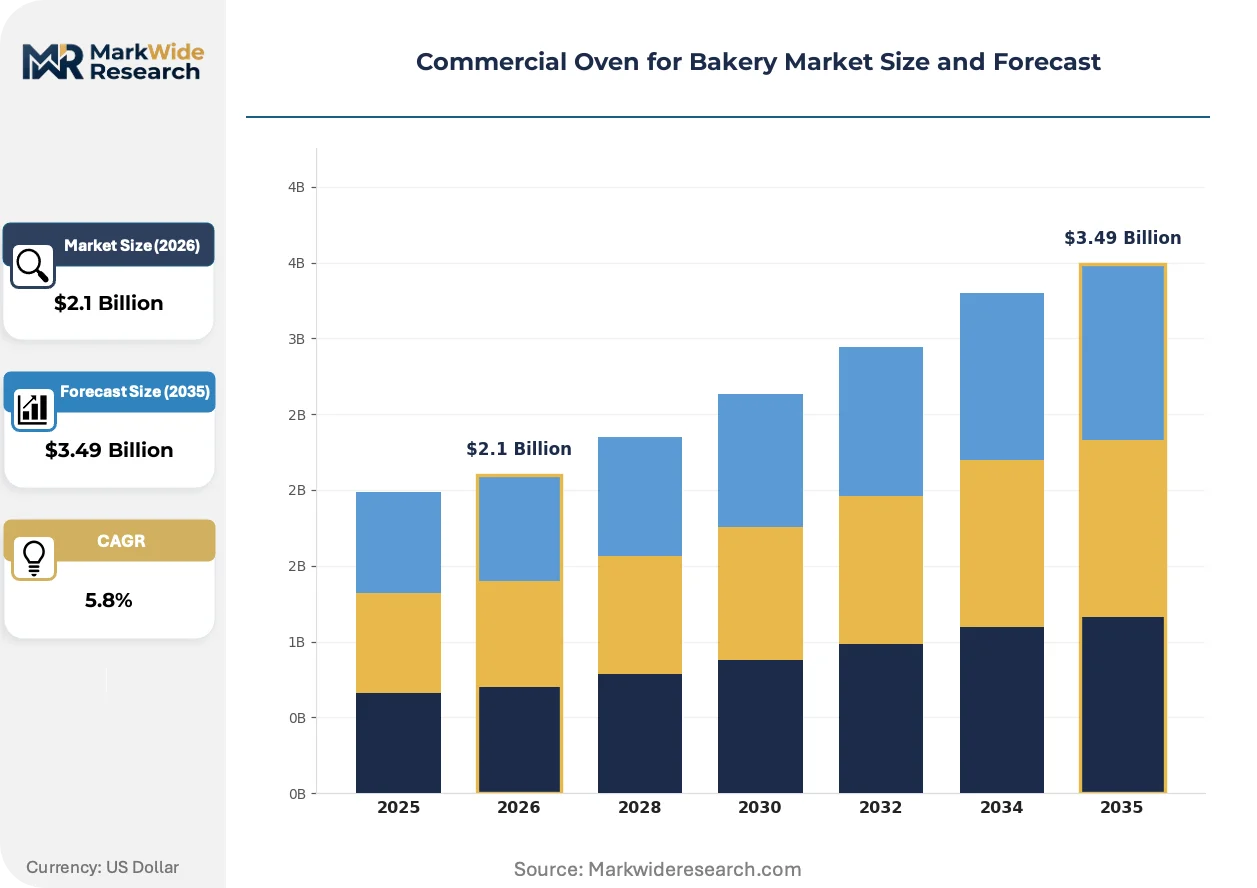
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convection Oven, Deck Oven, Rack Oven, Rotary Oven End User: Bakery Shops, Hotels, Restaurants, Catering Services Heating Technology: Electric, Gas, Wood-Fired, Infrared Size: Small, Medium, Large, Extra Large |
| Companies Covered | Blodgett, Baker's Pride, Moffat, Doyon, Hobart, Rational, TurboChef, Unox, Middleby Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Oven for Bakery Market Strategic Shifts
Electrification of thermal systems is compressing the competitive window for gas-fired equipment, while digital integration and regulatory pressure on refrigerants are simultaneously reshaping product architecture and aftermarket service models.
Advanced ceramic fiber insulation with aerogel composite layers is achieving 40% thermal loss reduction versus traditional mineral wool configurations. Large wholesale bakeries in Germany and the Netherlands are specifying these materials for new rack oven installations to preempt carbon border compliance costs. This thermal performance leap is rendering obsolete conventional insulation upgrade pathways that relied on incremental thickness increases.
EPA commercial kitchen appliance efficiency standards are tightening test procedure requirements for idle energy consumption and preheat recovery times. Manufacturers must redesign burner modulation systems and chamber geometry to maintain certification eligibility for gas-fired product lines. North American foodservice distributors are prioritizing electric SKUs in urban territories where local ordinances restrict combustion equipment procurement.
Central commissary operators are unbundling after-sales service contracts from equipment purchase agreements, instead procuring predictive maintenance subscriptions tied to throughput guarantees. This shift transfers operational risk to OEM service networks and compresses capital expenditure recognition for bakery chains. The model is most advanced in U.S. and U.K. wholesale bakery segments where equipment utilization rates exceed 18 hours daily.
Commercial Oven for Bakery Market Segmentation
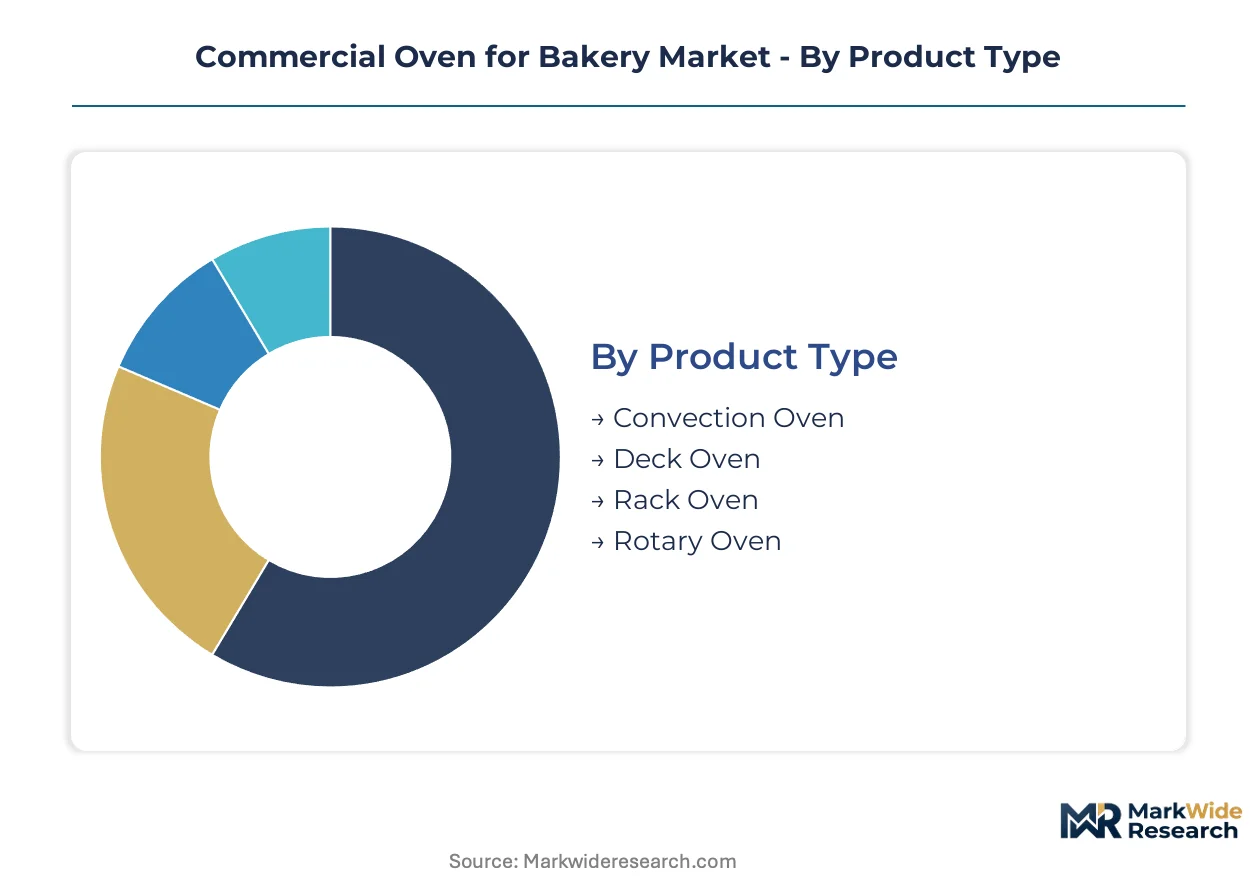
Commercial bakery oven procurement varies sharply by operational scale and thermal requirements. Equipment specification cascades from production volume targets through energy infrastructure constraints to finished product quality standards.
Product Type:
The use-case spectrum spans from versatile countertop units to continuous-feed industrial tunnel systems.
- Convection Oven:Forced-air circulation chambers achieve temperature uniformity through fan-driven heat distribution, enabling simultaneous baking of mixed product loads. Bakery shops across Germany and the Netherlands specify these units for croissant and Danish production where consistent browning drives repeat purchase rates.
- Rack Oven:Vertical loading systems accommodate wheeled racks holding multiple baking trays, maximizing throughput per floor square meter. Central commissaries in the United States are standardizing on these configurations as artisan chains consolidate production into fewer, larger facilities.
- Deck Oven:Stone or steel sole plates deliver conductive heat transfer prized for artisan bread crust development.
- Rotary Oven:Rotating rack mechanisms ensure even exposure in large-batch operations serving hotel and catering channels.
The dominant share belongs to Convection Oven, while Rack Oven is closing the gap fastest.
End User:
Customer archetypes diverge on capital intensity, operating hours, and technical sophistication requirements.
- Bakery Shops:Independent and chain retail bakeries prioritize compact footprints, rapid product changeover, and visual merchandising integration. Urban locations in Italy and France face emissions ordinances that restrict gas-fired equipment procurement, redirecting capital toward electric convection platforms.
- Hotels:Full-service properties require versatile thermal systems supporting breakfast pastry, banquet bread service, and in-house restaurant operations. Procurement decisions in the United States increasingly bundle oven specifications with broader kitchen equipment packages managed by foodservice distributors.
- Restaurants:Fine-dining and casual-dining operators seek specialty finishing equipment for house-made bread programs.
- Catering Services:Mobile and off-premise foodservice providers demand transportable or rapid-deployment baking capabilities.
Bakery Shops command the largest installed base, though Hotels are expanding equipment orders most aggressively.
Heating Technology:
Energy source selection hinges on local infrastructure, operating cost structures, and regulatory compliance timelines.
- Electric:Resistance-element or induction-based systems eliminate combustion emissions at point of use, satisfying urban air quality mandates. New York City and San Francisco prohibitions on new gas hookups are accelerating electric oven installations in commissary bakeries.
- Gas:Natural gas or propane combustion delivers faster preheat recovery and lower per-unit energy costs where pipeline infrastructure exists. Cost-sensitive emerging markets with established natural gas distribution sustain procurement of these systems despite efficiency standard pressures.
- Wood-Fired:Traditional fuel sources persist in specialty craft bakeries emphasizing flavor differentiation and heritage positioning.
- Infrared:Radiant heat technologies enable precise surface browning control for delicate confectionery applications.
Electric systems are gaining share fastest in regulated urban markets, while Gas retains margin strength in cost-driven segments.
Size:
Chamber capacity scaling aligns with batch economics and real estate constraints across facility types.
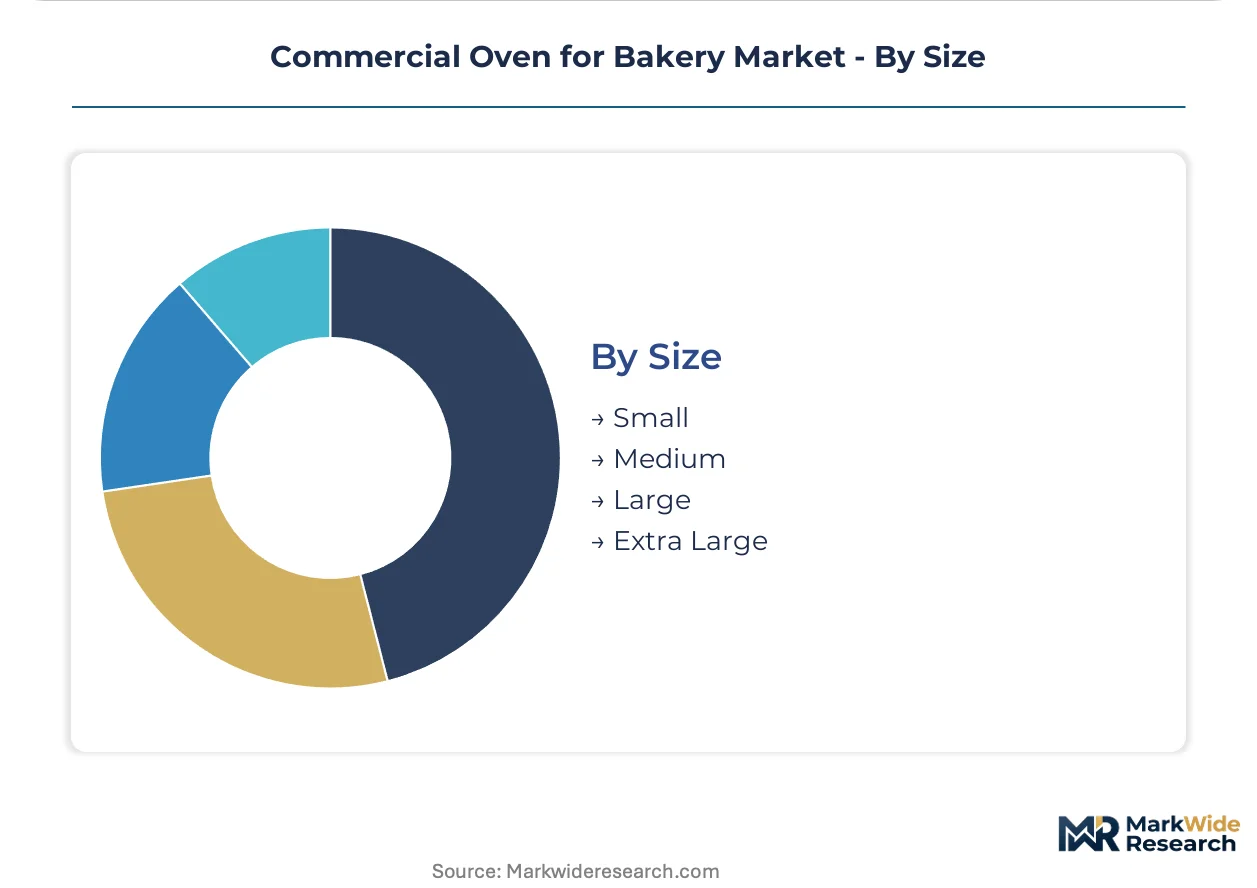
- Small:Countertop or under-counter units serve boutique retail locations and hotel satellite kitchens with limited production volumes. Premium positioning in Japanese and Swiss markets supports specification of compact, high-precision equipment for specialty product lines.
- Medium:Floor-standing single-rack or double-rack configurations balance throughput with flexibility for multi-product operations. Regional bakery chains in the United States are consolidating around medium-scale rack ovens as they expand from single-unit to multi-location footprints.
- Large:Multi-rack or tunnel configurations serve wholesale bakeries with dedicated product lines and extended operating schedules.
- Extra Large:Continuous industrial systems support mass-production facilities supplying retail grocery and foodservice distribution channels.
Medium units dominate current procurement volume, while Large configurations are expanding most quickly in central commissary buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty oven fabrication clusters in Emilia-Romagna and Lombardy supply equipment across European artisan bakery networks. Urban emissions ordinances in multiple jurisdictions are redirecting procurement toward electric thermal systems.
United States
Artisan bakery chains are consolidating production into central commissaries, driving rack oven procurement velocity. The EPA's commercial kitchen appliance efficiency standards compress product lifecycles for thermal insulation and burner assemblies. New York City and San Francisco prohibitions on new gas hookups accelerate electric convection installations in urban commissary facilities.
Germany
Traditional craft bakeries sustain premium deck and rotary oven procurement despite efficiency pressures. The Ecodesign Directive compels manufacturers to reformulate insulation materials and steam injection systems. Advanced ceramic fiber insulation with aerogel composite layers is achieving thermal loss reduction in new rack oven installations across wholesale bakeries in the Netherlands-adjacent Rhineland cluster.
Italy
Heritage positioning in specialty bread segments maintains demand for stone-hearth and wood-adjacent thermal systems. CE marking requirements standardize electrical safety protocols across equipment exports to member states. Emilia-Romagna and Lombardy fabrication districts reconfigure European supply dynamics through concentrated specialty oven production capacity.
India
Organized retail and quick-service bakery chains are consolidating production into centralized facilities. The Bureau of Indian Standards maintains equipment safety certifications for imported thermal systems. Maharashtra and Karnataka urban corridors are seeing commissary buildouts that create demand for high-throughput rack and tunnel oven configurations.
Japan
Premium positioning in compact, high-precision equipment supports specialty product line specifications. METI efficiency guidelines shape domestic appliance procurement criteria for commercial foodservice operators. Kanto and Kansai industrial corridors concentrate distribution infrastructure for imported European and domestic thermal processing equipment.
Commercial Oven for Bakery Market Competitive Environment
Multi-brand portfolio operators and specialized thermal engineering houses split the market across distinct value capture models. Consolidation pressure concentrates around distribution control in North American foodservice channels and energy-efficient technology leadership in European regulatory environments. Two archetypes dominate: diversified equipment conglomerates leveraging cross-category purchasing relationships, and focused combustion or convection specialists defending margin through thermal performance differentiation. Competitive moves center on geographic expansion through distributor acquisition and technology licensing for emissions-compliant burner systems.
Within the diversified conglomerate tier, Middleby Corporation and Rational exemplify contrasting approaches to portfolio architecture. Middleby anchors North American channel control through multi-brand distribution leverage, while Rational occupies a position defined by combi-oven technology extension into bakery-specific thermal management. Among European specialists, Unox sits within the energy-efficient convection segment, representing Mediterranean market anchoring through platform designs targeting high-volume artisan production. These three entities collectively illustrate the strategic bifurcation between scale-driven coverage and precision-focused specialization.
| Leading Market Players |
|---|
| Blodgett |
| Baker's Pride |
| Moffat |
| Doyon |
| Hobart |
| Rational |
| TurboChef |
| Unox |
| Middleby Corporation |
| Others |
Value Chain & Pricing Dynamics
Indonesian and South African mining operations for nickel and chromium feed directly into stainless steel chamber fabrication costs, concentrating margin pressure on manufacturers when commodity volatility spikes and forcing downstream pricing adjustments across equipment tiers.
Pricing Analysis
EPA commercial kitchen appliance efficiency standards dictate the pricing tier structure across the commercial bakery oven landscape. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and thermal performance specifications, with premium tiers capturing margin from Ecodesign Directive compliance and advanced insulation packages. Cost compression in mid-tier electric convection platforms is intensifying because urban emissions ordinances accelerate demand for compliant configurations. Small independent bakery shops exhibit highest price sensitivity, while central commissary operators prioritize throughput guarantees over unit cost.
Supply Chain Analysis
Export-control friction around combustion system technologies limits cross-border flows of gas-fired oven components into North American facilities. Chamber fabrication draws from nickel and chromium supply chains anchored in Indonesia and South Africa, with burner assemblies and precision airflow systems sourced from German and Italian engineering clusters. Single-source vulnerability concentrates around specialty ceramic fiber insulation with aerogel composite layers produced by limited qualified suppliers. Distribution runs through foodservice equipment distributors and OEM direct sales forces serving commissary and retail bakery segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision thermal engineering expertise sits in critically short supply relative to equipment procurement velocity, creating structural advantage for manufacturers with captive combustion optimization and airflow design capabilities.
For Market Incumbents: Insulate margin pools by securing backward integration into advanced insulation supply chains ahead of EU carbon border adjustment implementation, and deepen certification investment for EPA-compliant burner modulation systems to forestall import competition from European specialists. Electrification mandates in urban North American markets threaten gas-fired product line viability without rapid platform redesign. For New Entrants and Emerging Players: Establish a beachhead in India's central commissary buildout by offering high-throughput rack oven configurations with localized service networks, bypassing entrenched European and North American channel control. Aftermarket predictive maintenance subscriptions represent the most penetrable revenue model, with thermal sensor integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap thermal engineering specialists with proven aerogel insulation integration and established relationships with artisan bakery chains. Long-term viability hinges on electrification-ready product portfolios and service revenue attachment rates. Watch for inflection signals in municipal gas hookup prohibition timelines across additional North American jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Platform Development | EPA efficiency standards and urban gas prohibitions render combustion-dependent portfolios obsolete without electric thermal system investment. |
| Aerogel Insulation Backward Integration | EU carbon border adjustments reward manufacturers with verified low-carbon supply chains and captive advanced materials production. |
| Predictive Maintenance Service Launch | Cloud-connected thermal sensor arrays enable subscription revenue from central commissaries with equipment utilization exceeding 18 hours daily. |
| India Distribution Channel Acquisition | Maharashtra and Karnataka commissary buildouts create first-mover advantage for localized rack and tunnel oven service networks. |
| CE Marking Plus EPA Dual Certification | Cross-border product platform economics improve when single SKUs satisfy both Ecodesign Directive and commercial kitchen appliance efficiency requirements. |
Study Parameters
A standing panel of thermal engineering directors, central commissary operations managers, foodservice equipment procurement leads, and aftermarket service heads provided ongoing calibration across primary interview rounds. Secondary validation drew from EPA efficiency standard filings, Ecodesign Directive implementation guidance, U.S. Department of Energy test procedure documentation, and Bureau of Indian Standards equipment safety certifications. Bottom-up installation base modeling and top-down market sizing triangulated volume and value estimates across product type, heating technology, and end-user segments.
Scenario bracketing anchored the analytical framework across the projection horizon, with demand elasticity tested against electrification mandate acceleration and commodity price volatility assumptions. Segmentation dimensions modeled include product type, heating technology, end-user archetype, chamber size tier, and regional regulatory cluster. CAGRs derived from equipment replacement cycle compression rates and central commissary buildout trajectories, with steam injection technology adoption curves and insulation material cost curves as industry-specific forecast inputs.
Sensitivities concentrate around nickel and chromium commodity price swings, municipal gas hookup prohibition expansion timelines, and F-Gas Regulation phase-down acceleration affecting refrigerant-dependent steam systems. Forecasts reflect documented assumptions on replacement schedule acceleration and electrification infrastructure buildout pace. Material shifts in carbon border adjustment implementation scope or EPA test procedure stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Brewery Heat Exchanger Market
Food Processing Equipment
Cookie Dropper Machine Market
Food Processing Equipment
Pasteuriser Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Crossflow Wine Filters Market
Food Processing Equipment
Griddle Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Kebab Machine Market
Food Processing Equipment
Sheet Metal Processing Equipment Market
Food Processing Equipment
Nut Processing Machine Market
Food Processing Equipment
Global Electrodialysis Equipment Market
Food Processing Equipment
North America Commercial Sous Vide Machine Market
Food Processing Equipment
Food-Grade Mixing Tank Market
Food Processing Equipment
Bread Slicer Market
Food Processing Equipment
Commercial Beverage Blender Market
Food Processing Equipment
Potato Processing Market