
 Global Rice Cakes Market | 2026-2036
Global Rice Cakes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rice Cakes Market Outlook
China is tilting toward large-scale rice cake manufacturing to serve both domestic snack demand and export channels. Quaker Oats Company leverages its North American distribution network to sustain shelf presence across mass retail formats. Lundberg Family Farms anchors the organic segment through certified sourcing and transparent supply chain practices. Kameda Seika Co Ltd dominates the puffed rice cracker category with decades of technical refinement in Japanese production methods.
Rice cakes are puffed or compressed grain discs manufactured from whole rice, typically through high-pressure extrusion or hot-air expansion, yielding a low-calorie, shelf-stable snack substrate designed for direct consumption or topping applications. The product type dimension shows gluten-free and organic variants capturing expanding margin pools as certification premiums persist, while plain rice cakes retain volume leadership in price-sensitive channels. Distribution channel dynamics reveal online retailers and health food stores as the fastest-growing access points, whereas supermarkets still occupy the dominant share of total throughput.
The FDA governs labeling and allergen declarations for rice cakes sold in the United States, while the EU Green Deal and REACH frameworks impose stricter sustainability and chemical disclosure obligations on European imports. Japan's Ministry of Agriculture, Forestry and Fisheries maintains quality grading standards that influence export eligibility and brand positioning across Asian markets. Stakeholders must monitor evolving organic certification harmonization between USDA and EU organic regimes to preserve cross-border market access without redundant compliance costs.
Market Dynamics
The EU Green Deal and REACH frameworks are forcing ingredient disclosure and carbon accounting across European supply chains, compelling manufacturers to reconfigure sourcing networks and certification protocols to preserve market access.
Growth Catalysts
- Organic certification harmonization:Alignment between USDA and EU organic regimes reduces redundant compliance costs for cross-border exporters. This streamlines market entry for certified producers targeting both American and European health-conscious consumers.
- Japan:Traditional puffed rice cracker consumption anchors stable demand while technical refinement in production methods enables premium export positioning. Domestic quality grading standards from the Ministry of Agriculture, Forestry and Fisheries reinforce brand credibility across Asian markets.
- Hot-air expansion technology:Advanced puffing methods reduce oil content and extend shelf stability without artificial preservatives. Foodservice operators and retail buyers are adopting these substrates for clean-label menu applications.
Market Restraints
- Input cost volatility:Specialty rice varieties and organic grain premiums fluctuate with climate-induced harvest variability. Contracting structures have not kept pace with spot market swings.
- Supply concentration risk:Puffed rice cracker production expertise clusters in Japanese manufacturing clusters. Technical know-how transfer to alternative production bases remains limited.
- Substitution threat:Protein-fortified chips and seaweed-based crisps capture overlapping snacking occasions. Functional positioning of rice cakes has not fully differentiated against these alternatives.
Strategic Opportunities
- South Korea:Snacking culture convergence between traditional rice-based products and Western health trends creates whitespace for hybrid positioning. Local retail chains are expanding dedicated natural foods sections.
- Direct-to-consumer subscription channels:Curated flavor rotations and limited-batch releases build recurring revenue outside mass retail margin compression. Digital-native brands are capturing lifetime value through membership models.
- EU Green Deal procurement incentives:Public sector and institutional buyers face mandated sustainable sourcing thresholds. Early certification alignment opens B2B volume contracts with favorable terms.
Industry Challenges
- Cross-regional certification timeline:Dual USDA-EU organic validation requires parallel audit cycles and documentation systems. Smaller producers lack dedicated compliance staff to manage simultaneous submissions.
- Legacy equipment retrofit costs:Hot-air expansion systems demand capital outlays that strain mid-tier manufacturing balance sheets. Financing access varies sharply across regional banking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rice Cakes Market |
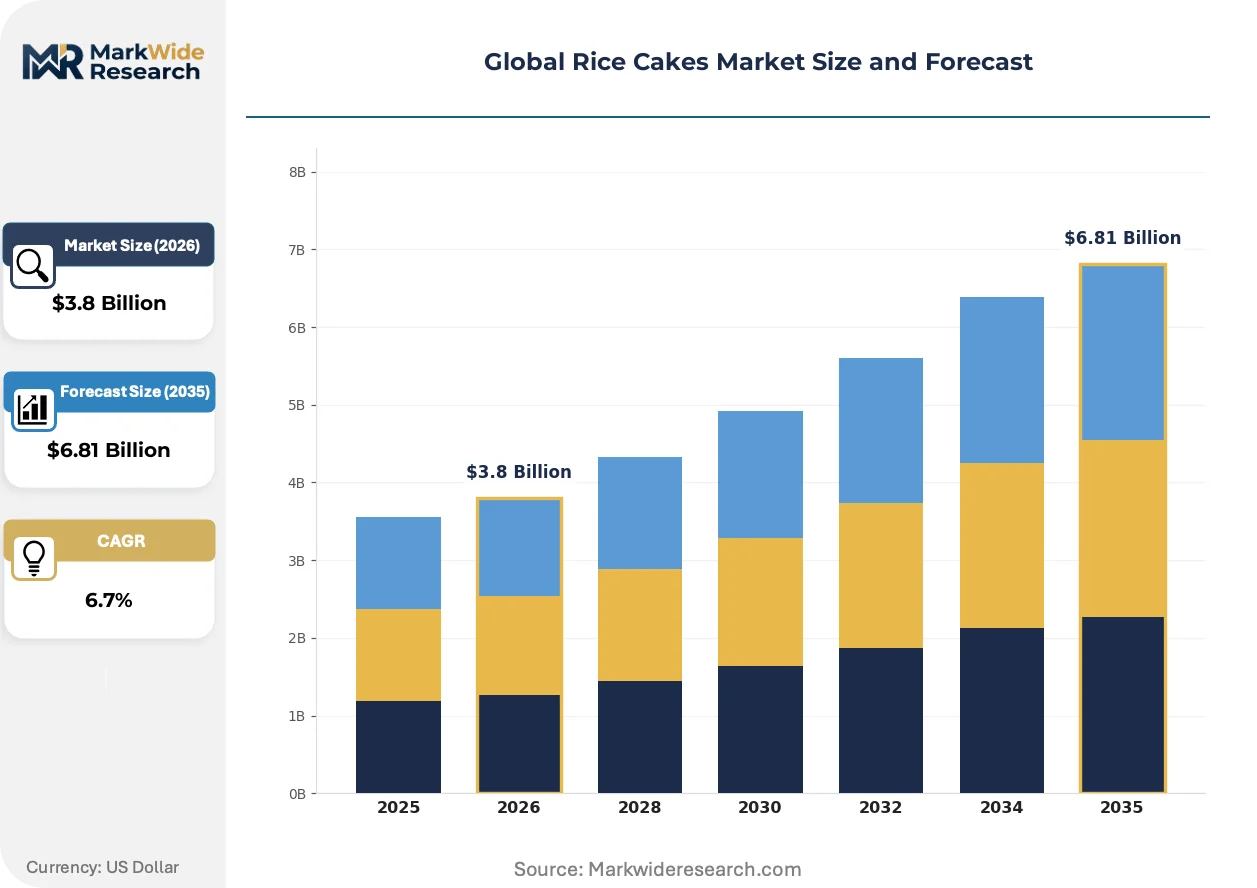
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain, Flavored, Organic, Gluten-Free Distribution Channel: Online Retailers, Supermarkets, Convenience Stores, Health Food Stores End User: Children, Adults, Athletes, Health Conscious Individuals Packaging Type: Bags, Boxes, Bulk Packaging, Individual Packs |
| Companies Covered | Quaker Oats Company, Lundberg Family Farms, Kameda Seika Co Ltd, Wasa, Lotus Foods, Nature's Path, Kallo Foods, Saki Foods, Edward & Sons Trading Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rice Cakes Market Strategic Shifts
Digital traceability infrastructure and precision fermentation are converging to reshape how rice cake supply chains demonstrate provenance and nutritional integrity to skeptical premium buyers.
Blockchain-enabled lot tracking is virtualizing the documentation layer between farm gate and retail shelf. European importers are mandating this capability for organic line items. The technology compresses audit cycles and reduces insurance premiums for certified supply chains.
REACH chemical disclosure obligations now extend to processing aids and packaging migrants in rice cake imports. Manufacturers are reformulating surface coatings and switching to barrier films that satisfy substance restriction lists. German retail consortia are rejecting shipments lacking full material transparency.
Health food store buyers are consolidating supplier relationships around vertically integrated producers with captive organic rice operations. This procurement compression favors manufacturers with direct farm partnerships over commodity-dependent competitors. The pattern is most visible in California and Pacific Northwest distribution corridors.
Global Rice Cakes Market Segmentation
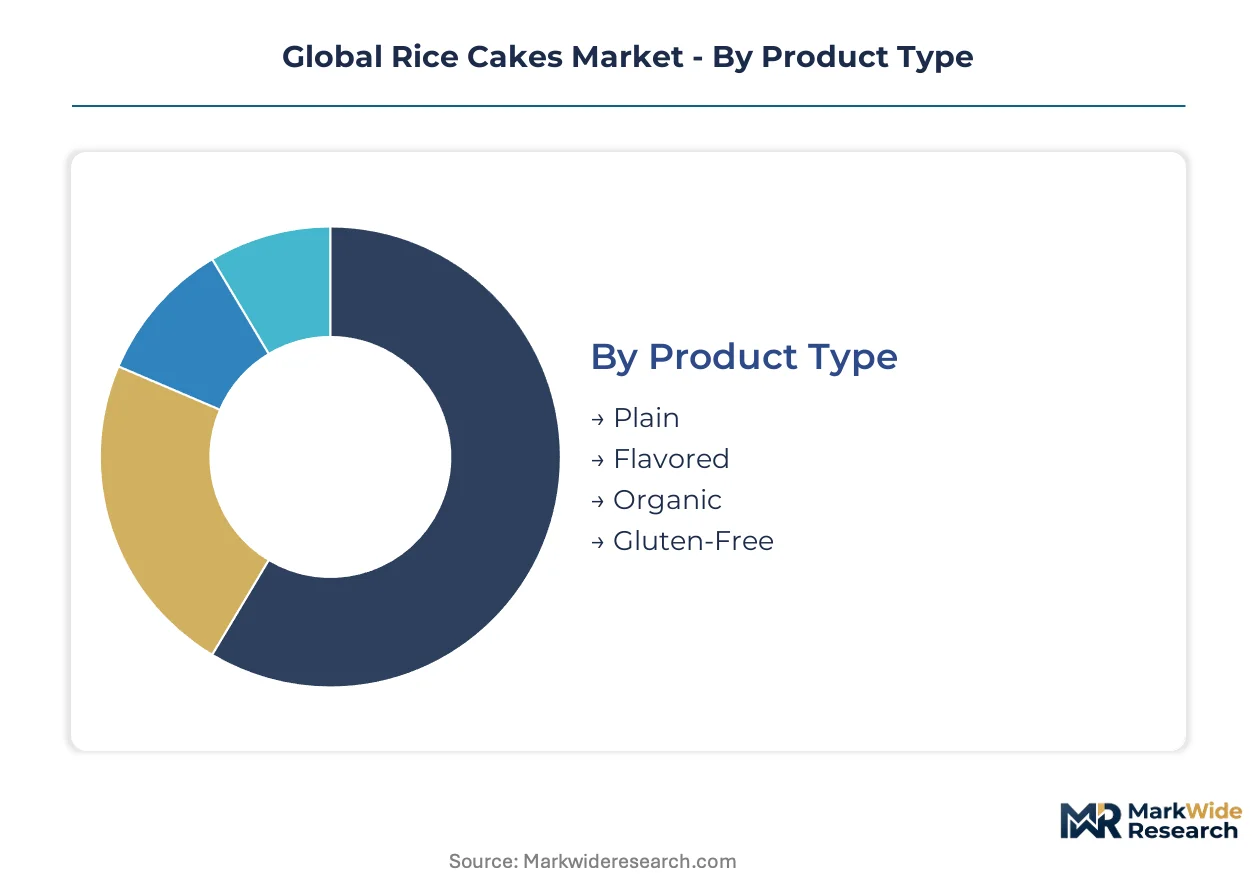
Segmentation in rice cakes reveals how certification premiums, channel access, and consumption occasions fragment demand across distinct margin tiers. Manufacturers configure production lines and sourcing networks differently for each slice, with organic and gluten-free variants commanding dedicated supply chain investments.
Product Type:
After-sales intensity varies sharply across product types, with organic and gluten-free segments demanding traceability documentation and certification renewal support that plain varieties rarely require.
- Plain:Unseasoned compressed rice discs serve as the volume foundation for price-sensitive retail channels. Demand concentrates in US mass-market supermarkets where private-label buyers prioritize shelf-stable substrates for topping applications.
- Organic:Certified whole-grain variants require dual USDA-EU validation for cross-border access, with Lundberg Family Farms anchoring supply through captive California rice operations. Japanese importers favor organic lines for premium convenience store placement.
- Flavored:Soy sauce, seaweed, and sweet coating applications target snacking occasions in South Korea and Japan where taste innovation drives repeat purchase.
- Gluten-Free:Dedicated production lines prevent cross-contamination for celiac-sensitive consumers, with demand clustering in US health food stores and European specialist retail.
By volume, plain leads. By growth pace, organic is ahead.
Distribution Channel:
Cost tier stratification separates premium health food placement from economy convenience store positioning, with channel-specific packaging and margin structures determining manufacturer prioritization.
- Supermarkets:Mass retail formats dominate throughput in the United States and Japan, with Quaker Oats leveraging existing cereal aisle relationships for shelf placement. Reset cycles favor established brands with promotional budgets.
- Online Retailers:Direct-to-consumer platforms enable curated flavor rotations and subscription models that bypass wholesale margin compression. Digital-native brands capture recurring revenue through membership structures.
- Health Food Stores:Specialist retail consolidates supplier relationships around vertically integrated producers with transparent farm partnerships. California and Pacific Northwest distribution corridors show the strongest procurement compression.
- Convenience Stores:Grab-and-go individual packs serve impulse occasions in Japanese and South Korean urban centers where puffed rice cracker traditions anchor snacking behavior.
Supermarkets still move the most units. Online retailers are climbing the fastest.
End User:
Application specificity distinguishes fuel-focused athletic consumption from child-oriented lunchbox placement, with formulation and portion sizing adapted to each occasion.
- Health Conscious Individuals:Clean-label seekers drive organic and low-sodium variant development, with EU Green Deal procurement incentives opening institutional volume contracts for certified suppliers.
- Athletes:Rapid glycogen replenishment applications favor plain varieties with minimal fiber interference, with sports nutrition distributors in the United States and Germany building dedicated snack assortments.
- Adults:Workplace snacking and meal accompaniment occasions sustain mid-tier flavored and savory lines across Japanese office retail channels.
- Children:Portion-controlled individual packs with mild flavor profiles target school lunch compliance and parental purchase approval in US and European markets.
Health conscious individuals represent the steepest expansion trajectory. Adults still account for the largest absolute base.
Packaging Type:
Volume scale and margin protection trade off across formats, with bulk institutional contracts requiring entirely different equipment and logistics than single-serve retail.
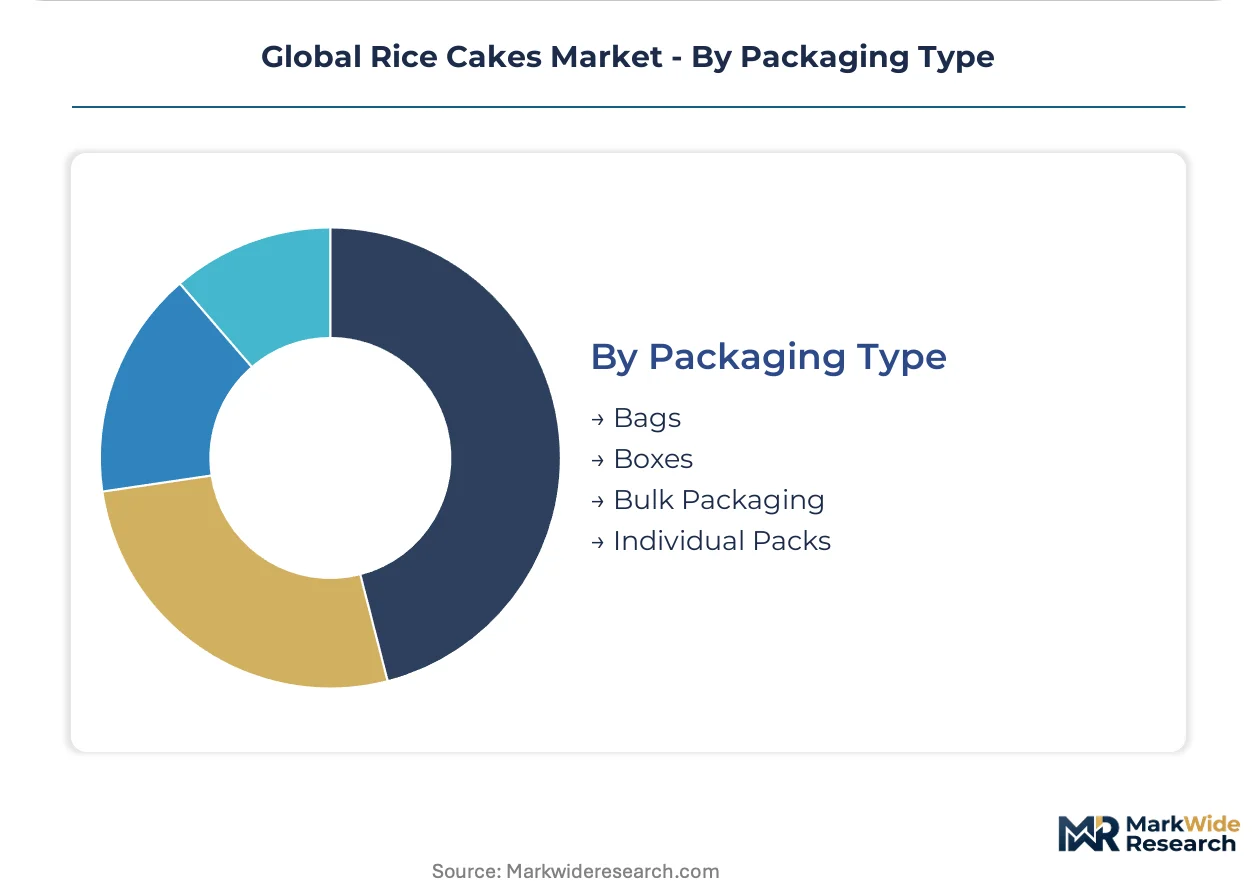
- Individual Packs:Portion-controlled units serve convenience store and foodservice channels where grab-and-go occasion dominance justifies higher per-unit packaging cost.
- Bags:Flexible pillow packs dominate supermarket shelf placement for family-size assortments, with barrier film specifications tightening under REACH substance restrictions.
- Boxes:Rigid cartons protect fragile puffed structures during transit to distant export markets, with Japanese manufacturers favoring this format for premium gift assortments.
- Bulk Packaging:Foodservice totes and institutional sacks serve European and US contract catering operations where ingredient cost minimization outweighs brand presentation.
Bags lead by volume. Individual packs are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese consumers treat puffed rice crackers as everyday staples, while American buyers view rice cakes primarily as health-oriented diet substrates, creating fundamentally different demand profiles across major markets.
United States
FDA labeling requirements for allergen declarations shape formulation decisions for domestic manufacturers. Health-conscious urban populations in coastal cities drive organic and gluten-free variant uptake. California's Sacramento Valley hosts vertically integrated rice milling operations that supply certified organic grain to premium snack producers.
Japan
Traditional puffed rice cracker consumption sustains stable baseline demand across all age demographics. Ministry of Agriculture, Forestry and Fisheries quality grading standards determine export eligibility for regional brands. Niigata Prefecture's established manufacturing clusters refine hot-air expansion techniques for premium gift assortments destined for Asian markets.
South Korea
Convenience store chains expand dedicated natural foods sections as Western health trends intersect with indigenous rice-based snacking culture. MFDS food safety standards govern additive limits and processing aid approvals. Seoul's retail innovation labs test hybrid flavor profiles combining traditional seaweed coatings with contemporary seasoning approaches.
Germany
REACH chemical disclosure obligations and EU Green Deal procurement mandates reshape ingredient sourcing for imported rice cake lines. Berlin-based retail consortia now reject shipments lacking full material transparency documentation. Bavarian distribution hubs consolidate inbound organic certified volumes for redistribution across Central European markets.
China
Large-scale manufacturing investments serve both domestic snack diversification and export channel development. SAMR food safety standards tighten processing facility registration requirements. Yangtze River Delta production zones integrate automated extrusion lines with blockchain-enabled traceability systems for European-bound organic shipments.
Global Rice Cakes Market Competitive Environment
Capability concentration sits with Japanese specialists holding decades of technical refinement in puffed rice production; scale advantage sits with North American cereal conglomerates leveraging existing retail relationships. The market structures around three tiers: multinational packaged food divisions with aisle dominance, family-owned organic specialists with captive sourcing, and regional Asian manufacturers with technical process expertise. Competitive moves center on portfolio diversification into certified organic lines and strategic partnerships with direct-to-consumer subscription platforms.
Within the organic specialist tier, Lundberg Family Farms and Lotus Foods exemplify producers with transparent supply chain positioning. Among Japanese technical leaders, Kameda Seika Co Ltd occupies a position representing traditional puffed rice cracker mastery. At the mass-market scale end, Quaker Oats Company anchors the North American retail presence archetype.
| Leading Market Players |
|---|
| Quaker Oats Company |
| Lundberg Family Farms |
| Kameda Seika Co Ltd |
| Wasa |
| Lotus Foods |
| Nature's Path |
| Kallo Foods |
| Saki Foods |
| Edward & Sons Trading Co. |
| Others |
Value Chain & Pricing Dynamics
Freight corridors connecting California's Sacramento Valley to European distribution hubs transmit organic rice premiums and REACH compliance costs simultaneously, concentrating pricing power among vertically integrated producers while fragmenting margin structures for commodity-dependent competitors across certification tiers.
Pricing Analysis
Price spreads between Japanese premium gift assortments and US mass-market private-label discs span threefold multiples, with certification grade and captive organic sourcing as the primary differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels is hardening as EU Green Deal procurement mandates filter through institutional buying. Cost compression in the plain rice cake tier is intensifying because input volatility in specialty rice varieties has outpaced contracting structures. Health-conscious consumers in coastal US cities and German metropolitan markets show lowest price sensitivity, while convenience store impulse buyers in South Korea and Japan remain most responsive to per-unit cost.
Supply Chain Analysis
Organic japonica rice cultivation in California's Central Valley, Niigata Prefecture's established milling clusters, and Yangtze River Delta processing zones anchor upstream feedstock availability for certified production lines. Supply chains draw from paddy rice, barrier film substrates, and hot-air expansion equipment as critical inputs. Single-source vulnerability concentrates in Japanese technical expertise for premium puffed cracker production, where decades of refinement have not transferred to alternative manufacturing bases. Distribution runs through supermarket reset cycles in the United States and Japan, health food store consolidation in California and Pacific Northwest corridors, and direct-to-consumer subscription platforms for digital-native brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through dual USDA-EU organic certification creates switching costs that lock institutional buyers into validated supplier relationships.
For Market Incumbents: Harden certification moats by accelerating dual organic validation timelines before smaller competitors resolve parallel audit capacity constraints. Deepen backward integration into captive California rice operations to insulate margin structures from climate-induced harvest variability. Protein-fortified chip substitutes and seaweed-based crisp alternatives represent the most pressing substitution threat requiring formulation response.
For New Entrants and Emerging Players: Pursue whitespace in South Korean convenience store natural foods sections where Western health trends intersect with indigenous rice snacking culture. Direct-to-consumer subscription channels with curated flavor rotations offer the most penetrable entry vector against mass retail margin compression. Lead with transparent blockchain-enabled traceability documentation to satisfy European importer mandates without legacy system retrofit burdens.
For Investors and Strategic Acquirers: EU Green Deal procurement mandate implementation reshapes the acquisition landscape toward certified suppliers with existing institutional volume contracts. Long-term viability across a decade horizon favors vertically integrated producers with direct farm partnerships over commodity-dependent processors. Monitor German retail consortium rejection patterns for shipments lacking full material transparency as the critical inflection signal for certification premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Organic Certification Investment | USDA-EU alignment unlocks cross-border institutional procurement contracts under Green Deal thresholds. |
| Blockchain Traceability Deployment | German retail consortia now mandate lot-level transparency for organic line item acceptance. |
| Hot-Air Expansion Capacity Addition | Clean-label positioning without artificial preservatives captures foodservice operator menu specifications. |
| Direct-to-Consumer Subscription Launch | Membership models bypass wholesale margin compression and build recurring revenue outside reset cycles. |
| Captive Rice Operation Integration | California Sacramento Valley vertical supply control insulates against climate-induced input volatility. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand managers at organic specialists, category buyers at US health food retailers, procurement leads at German distribution consortia, and technical directors at Japanese puffed cracker manufacturers. Secondary validation drew from FDA labeling guidance documents, EU REACH substance restriction lists, Ministry of Agriculture quality grading standards, and Nielsen retail audit data. Bottom-up volume modeling across product type and channel segments was triangulated against top-down macroeconomic consumption trend analysis.
Calibration against historical certification adoption curves and channel shift patterns informed projection logic across the analysis window. Segmentation dimensions modeled include product type tier, distribution channel format, end-user application, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year consumption estimates, with organic premium persistence and hot-air expansion technology diffusion serving as key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive certification investment moves by well-capitalized new entrants would shift outcomes beyond modeled ranges. Cross-checking against Japanese export volume trajectories and EU organic import customs data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Ezekiel Bread Market
Bakery Products
Gluten-Free Bakery Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Doughnuts Market
Bakery Products
Pizza Dough Balls Market
Bakery Products
Gulf Cooperation Council Frozen Bakery Products Market
Bakery Products
Low Fat Oatmeal Cookies Market
Bakery Products
Europe Bakery Products Market
Bakery Products
Low Fat Chocolate Cake Market
Bakery Products
Flatbread Market
Bakery Products
Canada Frozen Bakery Market
Bakery Products
Low Fat Muffin Market
Bakery Products
Europe Sourdough Market
Bakery Products
Pancake Mixes Market
Bakery Products
Bake Stable Pastry Fillings Market
Bakery Products
Diabetic Bakery Products Market