
 Organic Goji Berry Market | 2026-2036
Organic Goji Berry Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Goji Berry Market Analytics
Premium organic goji berry supply is shifting away from commodity-grade bulk exports as certified-origin product commands measurable price premiums. Navitas Organics leverages direct farmer partnerships in Ningxia to secure traceable supply chains. Dragon Herbs anchors its positioning through traditional Chinese medicine heritage branding and extraction expertise. Tradin Organic Agriculture competes across European health stores with EU Organic-certified sourcing.
Organic goji berries are dried or processed fruits of Lycium barbarum cultivated without synthetic pesticides or fertilizers, typically containing 18 amino acids and polysaccharides exceeding 5% by dry weight, used primarily in functional foods and dietary supplements. Dried berries dominate volume sales through supermarkets and health stores, while extract commands the strongest margin pools from nutraceutical company procurement. Powder segments extend into food manufacturer applications where clean-label ingredient demand runs highest.
USDA Organic certification governs US market access, while China's MEE enforces soil and water standards for domestic organic cultivation, and the EU Green Deal's Farm to Fork strategy tightens residue limits on imported superfruit. Stakeholders must monitor evolving organic equivalency agreements between major importing jurisdictions to preserve tariff advantages and shelf placement.
Market Dynamics
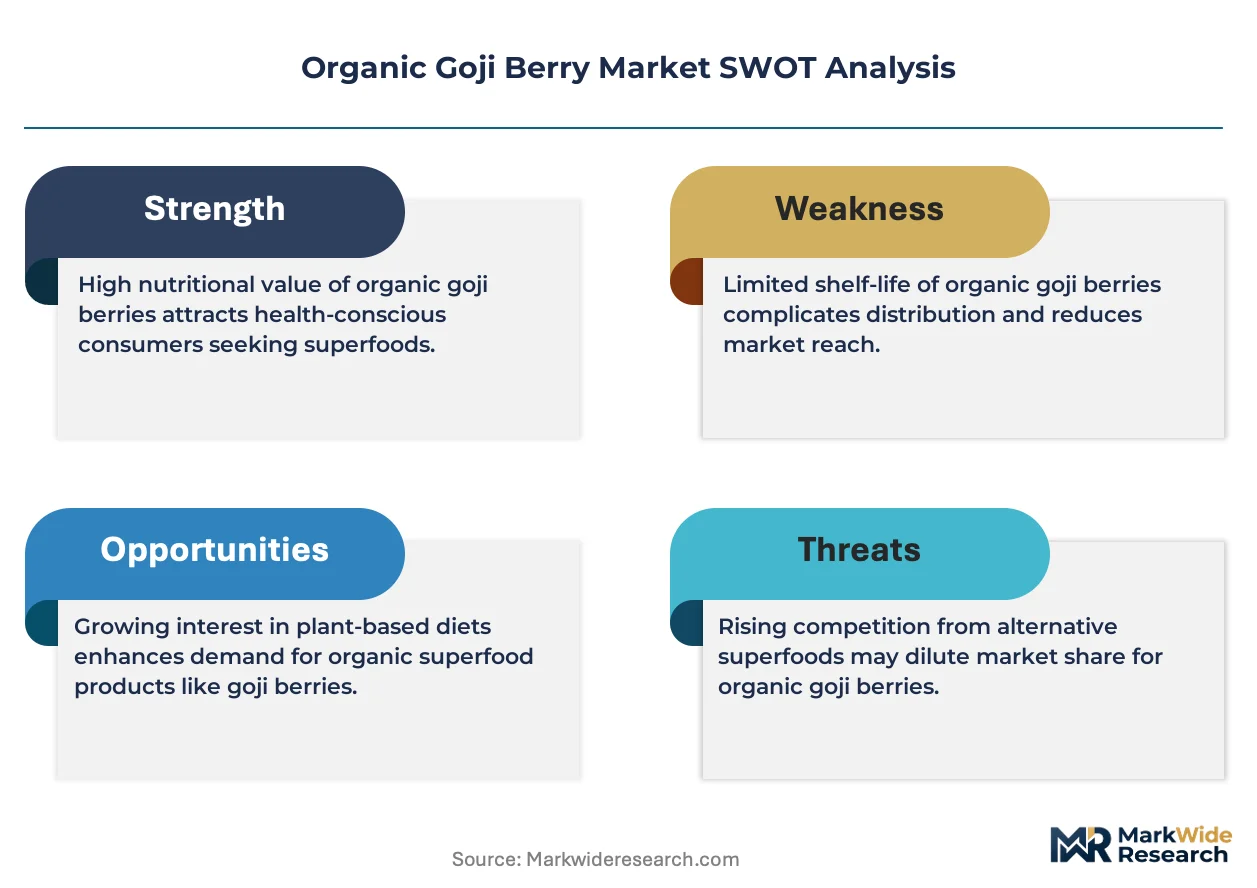
Certification-driven supply bifurcation is forcing organic goji berry producers to choose between premium traceable channels and commodity bulk exports, with EU and US organic equivalency requirements acting as the decisive filter.
Growth Catalysts
- EU Green Deal residue limits:The Farm to Fork strategy tightens maximum residue levels on imported superfruit, redirecting procurement toward certified-origin Ningxia suppliers who pre-emptively meet these standards.
- Nutraceutical formulation demand:Functional food manufacturers now specify organic-certified goji extract with verified polysaccharide content above 5% for immunity-positioned products.
- Controlled-origin cultivation clusters:Ningxia Autonomous Region's geographic indication protections create defensible premium positioning against generic Chinese supply.
Market Restraints
- Organic certification lag:China's MEE soil and water compliance timelines extend 24-36 months, freezing smallholder participation and concentrating supply among pre-certified estates.
- Input cost volatility:Organic fertilizer prices fluctuate with natural gas benchmarks, compressing margins for growers locked into multi-year organic transition contracts.
- Substitution pressure:Organic sea buckthorn and aronia berries compete for identical shelf space in European health stores, with comparable polyphenol profiles at lower price points.
Strategic Opportunities
- USDA Organic pipeline expansion:US retailers are adding dedicated superfruit sections, creating first-mover advantage for suppliers with existing National Organic Program certification.
- Direct-to-consumer subscription channels:Monthly wellness box services bypass traditional distributor markups and capture full margin on traceable-origin positioning.
- Traditional Chinese Medicine heritage branding:Extraction expertise combined with organic certification opens premium positioning in Asian pharmacy channels beyond commodity dried fruit.
Industry Challenges
- Auditor capacity constraints:Accredited organic certifiers face backlogs exceeding 18 months in Ningxia, delaying market access for new entrants.
- Traceability system integration:Blockchain and RFID tagging requirements from major EU retailers demand capital investment beyond typical dried fruit processor capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Goji Berry Market |
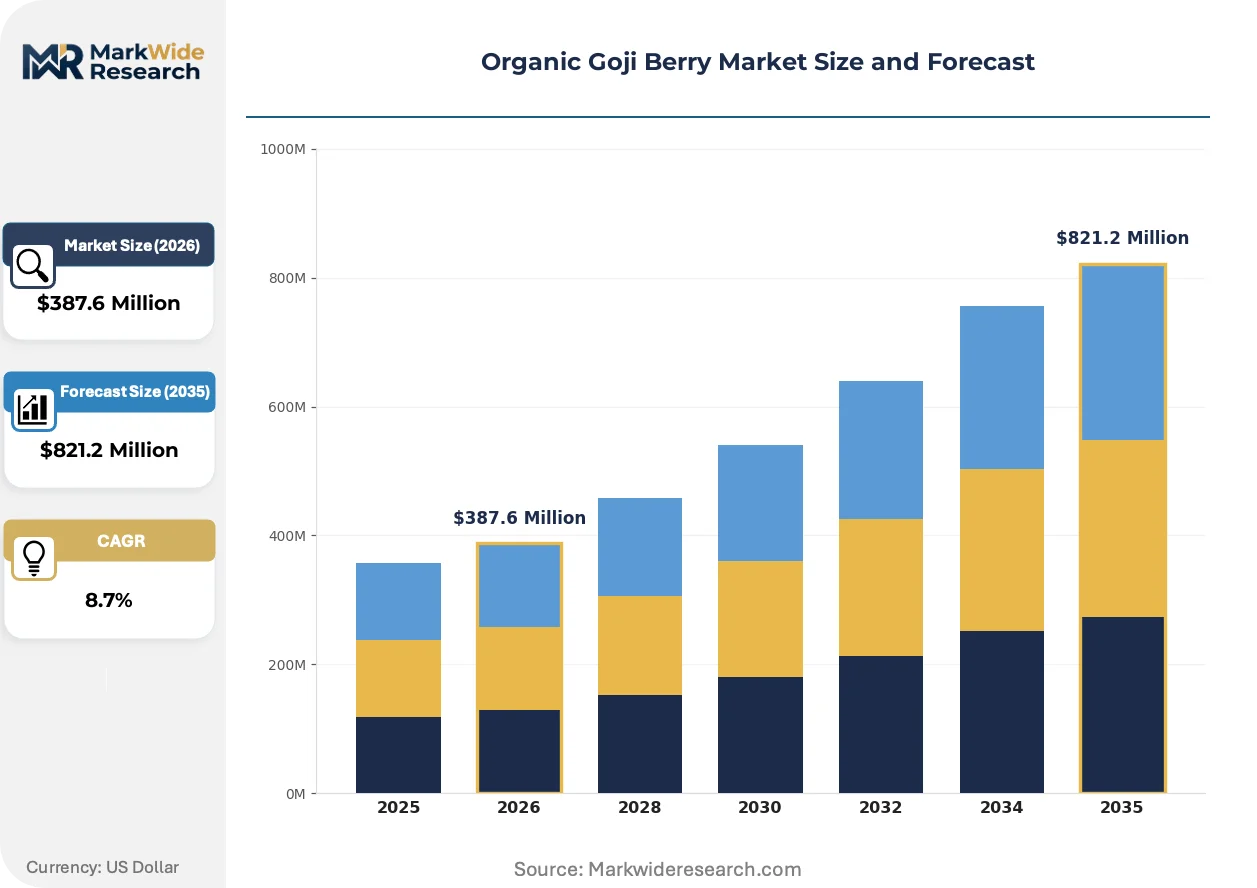
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Berries, Powder, Juice, Extract Distribution Channel: Online Retail, Supermarkets, Health Stores, Farms End User: Health Enthusiasts, Food Manufacturers, Retail Consumers, Nutraceutical Companies Packaging Type: Bulk Packaging, Individual Packs, Pouches, Bottles |
| Companies Covered | Gojix LTD, Purely Organic Foods, CXD Goji LLC, Dragon Herbs, Tibetan Goji Berry Company, Navitas Organics, Sunfood Superfoods, Tradin Organic Agriculture, Goji Farm USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Goji Berry Market Evolving Landscape
Low-temperature vacuum drying technology is overtaking conventional sun-drying methods, preserving heat-sensitive polysaccharides while reducing contamination risk. This shift is compressing the premium tier and forcing commodity processors to upgrade or accept permanent price discounting.
Spray-dried goji extract with standardized Lycium barbarum polysaccharide content is overtaking whole dried berries in nutraceutical procurement. Functional food formulators at mid-sized North American manufacturers are adopting this input for clean-label immunity products. The technology is overtaking traditional extraction methods by delivering consistent potency without solvent residues.
REACH compliance documentation requirements for novel food ingredients are tightening entry barriers for non-EU suppliers. The European Food Safety Authority now demands full toxicological profiles on polysaccharide isolates, favoring incumbent suppliers with existing dossiers. Organic goji extract shipments to Germany and the Netherlands face enhanced border inspection protocols.
Clean-label ingredient specifications are compressing acceptable additive lists for processed goji products. Food manufacturers in California and New York now reject sulfur dioxide treatments previously standard for color retention. This behavioral shift favors suppliers with controlled-atmosphere drying infrastructure and disadvantages traditional sun-drying operations dependent on chemical preservatives.
Organic Goji Berry Market Segmentation
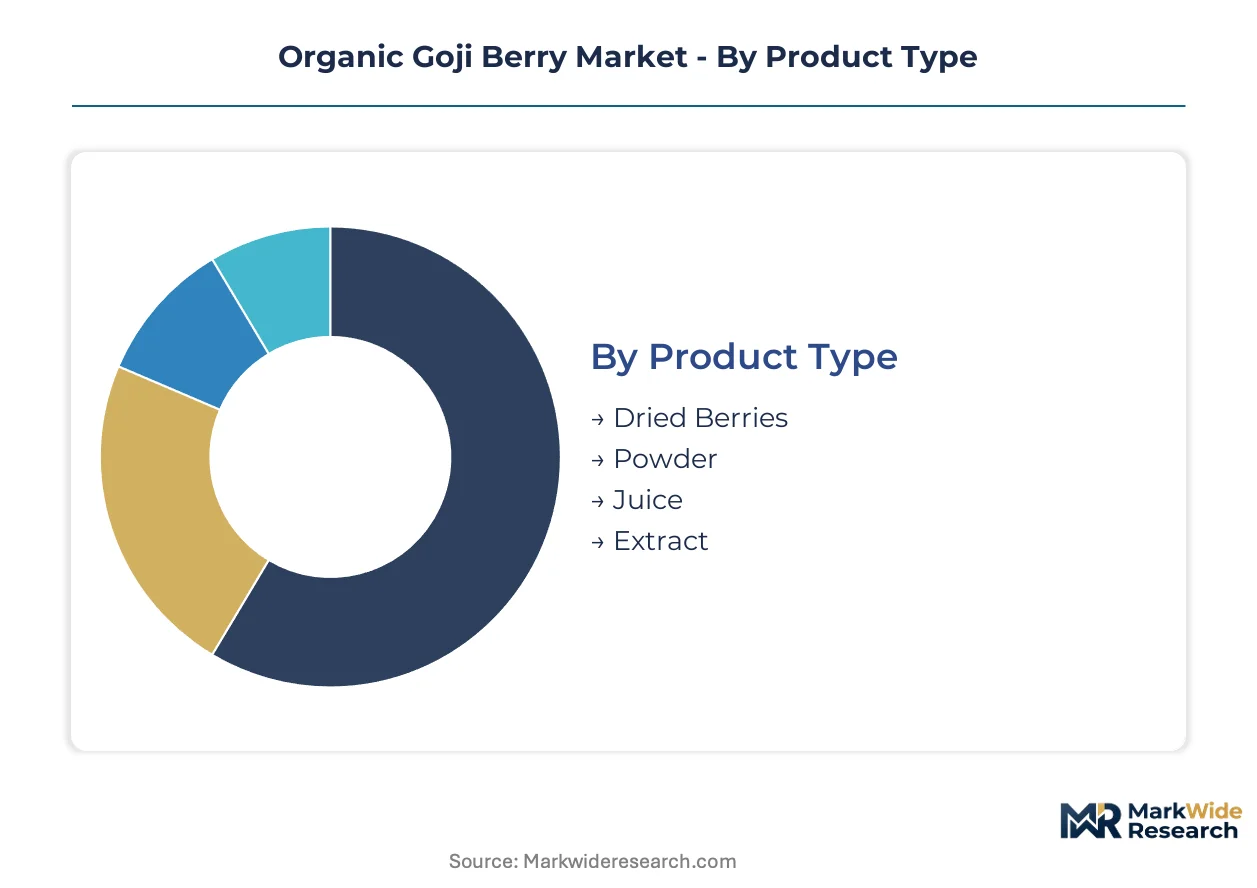
Organic goji berry segmentation reveals how certification grade and processing depth determine margin capture. Dried commodity berries serve mass retail while standardized extracts command nutraceutical premiums. Distribution channel selection increasingly separates traceable-origin suppliers from bulk exporters facing residue scrutiny.
Product Type:
Standalone consumption formats dominate shelf placement, while embedded ingredient systems penetrate food manufacturing and supplement formulations.
- Dried Berries:Whole dehydrated Lycium barbarum fruits retain 18 amino acids and polysaccharide content above 5% by dry weight. Supermarkets and health stores in Germany and the Netherlands drive procurement of sulfur-free vacuum-dried grades for clean-label positioning.
- Extract:Standardized polysaccharide concentrates serve immunity-positioned functional foods and Traditional Chinese Medicine formulations. Nutraceutical companies specify organic-certified lots with verified Lycium barbarum polysaccharide content, creating the strongest margin pool across all product types.
- Powder:Milled whole berry or juice-dried forms integrate into smoothie formulations and baked goods where clean-label ingredient demand runs highest.
- Juice:Single-strength or concentrate formats target direct consumption channels with shorter shelf life and cold-chain requirements.
Volume placements concentrate in Dried Berries; the faster expansion belongs to Extract.
Distribution Channel:
Channel selection now functions as a certification filter, with traceability requirements escalating from farm gate through retail shelf.
- Online Retail:Direct-to-consumer subscription services bypass distributor markups and capture full margin on controlled-origin positioning. Monthly wellness box services in California and New York specify blockchain-traceable Ningxia supply.
- Supermarkets:Dedicated superfruit sections at US retailers create first-mover advantage for USDA Organic-certified suppliers with existing National Organic Program documentation.
- Health Stores:EU Organic-certified sourcing dominates European health store placement, with residue limits under the EU Green Deal Farm to Fork strategy redirecting procurement toward pre-certified Ningxia estates.
- Farms:Direct farm gate sales concentrate in Ningxia Autonomous Region where geographic indication protections secure premium positioning against generic Chinese supply.
Health Stores capture the premium price tier; Online Retail is climbing the fastest.
End User:
User sophistication determines specification intensity, from commodity bulk buyers to formulation-driven nutraceutical engineers.
- Nutraceutical Companies:Functional food manufacturers specify organic-certified goji extract with verified polysaccharide content for immunity-positioned products, driving the most demanding procurement standards.
- Food Manufacturers:Clean-label ingredient specifications compress acceptable additive lists, with California and New York operations rejecting sulfur dioxide treatments previously standard for color retention.
- Health Enthusiasts:Direct purchasers prioritize organic certification and traceable origin, typically sourcing through subscription channels or specialty retailers.
- Retail Consumers:Mass-market buyers respond to shelf placement and price positioning, with limited differentiation between organic and conventional grades at point of purchase.
Food Manufacturers anchor volume demand; Nutraceutical Companies show the steepest expansion trajectory.
Packaging Type:
Packaging scale inversely correlates with traceability investment, from commodity bulk to individual unit authentication.
- Bulk Packaging:Industrial-scale totes and drums serve food manufacturers and extract processors where downstream processing occurs before retail exposure.
- Individual Packs:Single-serve sachets target on-the-go consumption and portion-controlled wellness routines.
- Pouches:Flexible stand-up bags with resealable closures dominate health store and online retail channels for dried berry and powder formats.
- Bottles:Rigid containers protect juice and extract products through cold-chain distribution, with amber glass preferred for light-sensitive polysaccharide preservation.
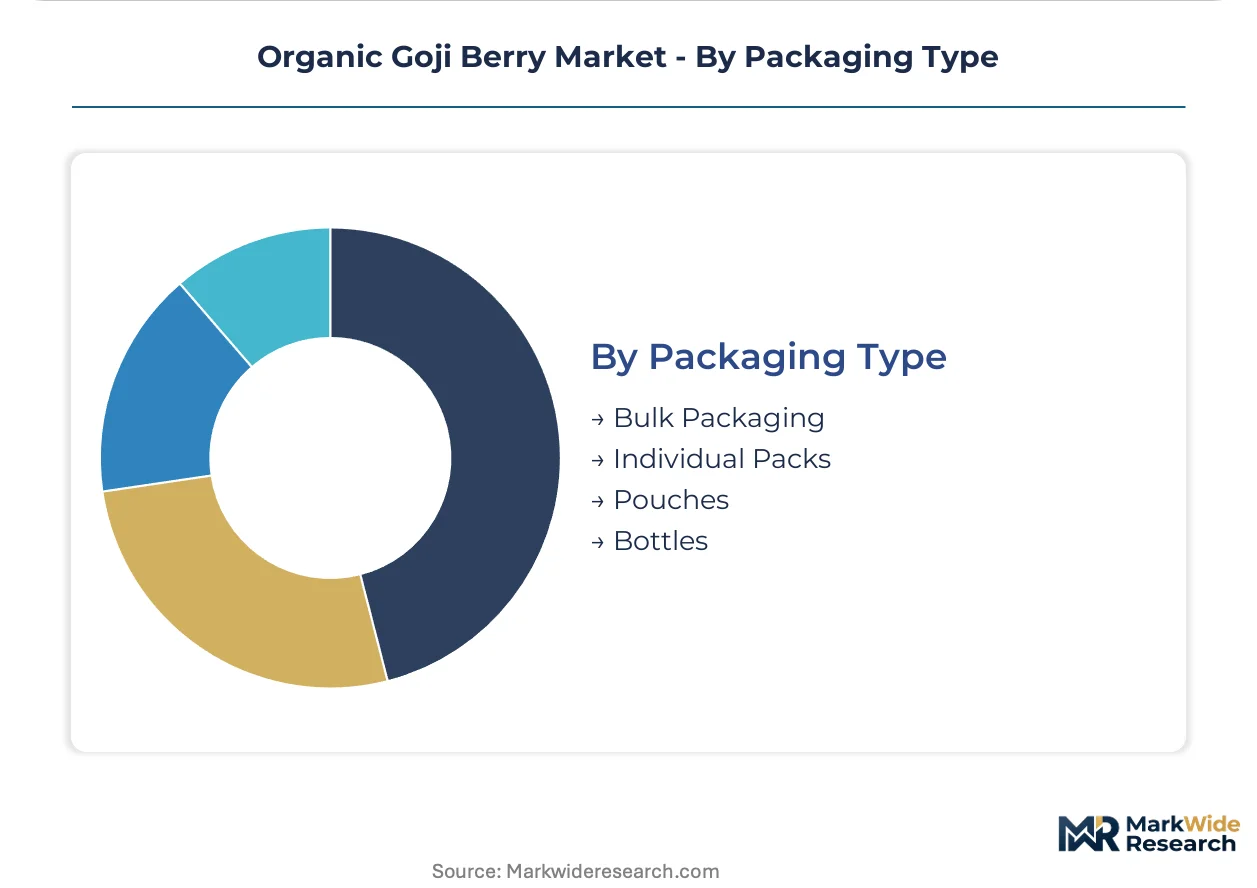
Bulk Packaging handles the largest tonnage; Pouches gain share fastest in premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ningxia Autonomous Region anchors organic goji berry cultivation, with Zhongning County's geographic indication protections securing premium positioning against generic Chinese supply.
China
Nutraceutical companies and TCM formulators drive procurement of certified-origin berries from Ningxia. China's MEE enforces soil and water standards for domestic organic cultivation, extending certification timelines to 24-36 months. Zhongning County's processing clusters concentrate vacuum-drying infrastructure for sulfur-free export grades.
United States
Superfruit retailers and wellness subscription services specify USDA Organic-certified supply for dedicated shelf sections. The USDA National Organic Program governs import equivalency, with California and New York operations rejecting sulfur dioxide treatments. Los Angeles-based direct-to-consumer channels capture margin through blockchain-traceable Ningxia sourcing.
Germany
Health store chains and functional food manufacturers demand EU Organic-certified extracts with REACH-compliant documentation. The EU Green Deal's Farm to Fork strategy tightens residue limits, redirecting procurement toward pre-certified estates. Hamburg's import terminals face enhanced border inspection protocols for polysaccharide isolates.
Netherlands
Traders and re-exporters serve as the primary European entry point for Ningxia-sourced organic berries. EFSA requirements for novel food ingredient toxicological profiles favor incumbent suppliers with existing dossiers. Rotterdam's cold-chain logistics hubs distribute spray-dried extracts to mid-sized North American manufacturers.
Canada
Health product retailers and clean-label food manufacturers specify organic-certified goji for immunity-positioned formulations. Health Canada and PMRA regulate natural health product claims, requiring substantiated polysaccharide content verification. Vancouver's Asian pharmacy channels import TCM-branded extracts alongside commodity dried fruit.
Organic Goji Berry Market Competitive Landscape
Capital-heavy producers with captive Ningxia cultivation compete with asset-light brand builders who source through contract farming arrangements. The vendor base separates into three strategic archetypes: vertically integrated estate operators, certified-origin traders, and direct-to-consumer wellness brands. Consolidation pressure favors pre-certified estates with existing USDA and EU Organic documentation. Competitive moves center on backward integration into controlled-origin cultivation and direct farmer partnerships that bypass commodity auction channels.
Among estate-integrated operators, Gojix LTD and CXD Goji LLC occupy positions anchored to Ningxia geographic indication protections. Dragon Herbs exemplifies the TCM heritage archetype, leveraging extraction expertise for Asian pharmacy channel positioning. Navitas Organics and Tradin Organic Agriculture represent the certified-origin trading tier, with the former emphasizing direct farmer partnerships and the latter competing across European health stores with EU Organic-certified sourcing. Sunfood Superfoods and Tibetan Goji Berry Company sit within the direct-to-consumer wellness segment, where subscription channels capture full margin on traceable-origin positioning.
| Leading Market Players |
|---|
| Gojix LTD |
| Purely Organic Foods |
| CXD Goji LLC |
| Dragon Herbs |
| Tibetan Goji Berry Company |
| Navitas Organics |
| Sunfood Superfoods |
| Tradin Organic Agriculture |
| Goji Farm USA |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's Farm to Fork residue limits gate qualified supply and premium-tier pricing access, concentrating margin capture among Ningxia estates with pre-certified organic documentation while excluding smallholders caught in China's MEE compliance timelines.
Pricing Analysis
Polysaccharide-standardized potency anchors value-based pricing tiers, with nutraceutical procurement commanding premiums against commodity dried berry grades. Price differentiation separates EU Organic-certified extracts from sulfur-treated sun-dried bulk, with California and New York food manufacturers rejecting chemically preserved inputs. Pricing pressure stems from organic fertilizer cost volatility tied to natural gas benchmarks, squeezing growers locked into multi-year transition contracts. Retail consumers show highest price sensitivity at mass-market shelf placement, while nutraceutical formulators absorb premiums for verified origin documentation.
Supply Chain Analysis
China's MEE soil and water mandates reshape sourcing toward controlled-origin Ningxia clusters with completed certification cycles. Geographic supply concentrates in China, the Netherlands, and Germany, with raw material dependencies on organic fertilizer inputs, vacuum-drying equipment, and polysaccharide testing infrastructure. Supply chain risk centers on auditor capacity backlogs exceeding 18 months in Zhongning County, freezing new entrant market access. Distribution runs through Rotterdam re-export terminals and Hamburg health store chains, with blockchain-traceable direct-to-consumer channels capturing margin from traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race, with backward control over Ningxia cultivation clusters determining who captures premium-tier pricing and who slides into commodity bulk exports.
For Market Incumbents: Cement supply security through direct farmer partnerships in Zhongning County that bypass auction channels and lock in polysaccharide-standardized output. Expand vacuum-drying infrastructure ahead of clean-label sulfur bans in California and New York food manufacturing. Organic sea buckthorn substitution in European health stores threatens shelf positioning; defend through TCM heritage branding and extraction expertise.
For New Entrants and Emerging Players: Mid-sized North American nutraceutical manufacturers represent the most penetrable buyer archetype, with specification demand for spray-dried extract outpacing established supplier capacity. Target USDA Organic-certified supply gaps in Los Angeles direct-to-consumer subscription channels where blockchain traceability commands full margin capture. Go-to-market leverage: pre-built EFSA dossiers for REACH-compliant polysaccharide isolates.
For Investors and Strategic Acquirers: Auditor backlog clearance in Ningxia is the leading indicator that supply-constrained pricing premiums will compress, favoring early positioning in pre-certified estate assets. Long-term viability hinges on 5-10 year organic equivalency agreement durability between US, EU, and Chinese regulators. Acquisition target archetype: Ningxia-integrated operators with existing USDA and EU Organic documentation. Signal to watch: EU Green Deal residue limit enforcement intensity at Hamburg import terminals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ningxia Cultivation | Captures geographic indication premiums and secures polysaccharide-standardized supply for nutraceutical procurement. |
| Vacuum-Drying Infrastructure Expansion | Meets clean-label sulfur-free requirements from California and New York food manufacturers. |
| USDA Organic Pipeline Certification | Unlocks dedicated superfruit shelf placement at US retailers adding organic sections. |
| Blockchain Traceability Implementation | Satisfies EU retailer RFID tagging requirements and supports direct-to-consumer premium positioning. |
| EFSA Dossier Development for Polysaccharide Isolates | Preserves market access under REACH compliance tightening for novel food ingredients. |
Research Methodology
Document review covered customs and trade data from China and the Netherlands, EU Green Deal regulatory filings, and USDA National Organic Program equivalency agreements, complemented by interviews with Ningxia cultivation estate managers, nutraceutical procurement leads at North American functional food manufacturers, EU health store category buyers, and organic certification auditors. Secondary validation drew from EFSA novel food ingredient databases, China's MEE soil compliance records, and trade flow documentation through Rotterdam terminals. Bottom-up supply chain modeling triangulated against top-down demand segmentation across product types and distribution channels.
Segmentation outputs across product type, distribution channel, end user, and packaging format informed volume and value projections across the analysis window. CAGRs derived from organic certification pipeline velocity, nutraceutical formulation adoption curves, and clean-label ingredient substitution rates in food manufacturing. Industry-specific forecast inputs included polysaccharide content standardization trends and EU Green Deal residue limit implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to organic equivalency agreement renegotiations between major jurisdictions and auditor capacity expansion in Ningxia. Forecasts reflect documented assumptions on certification timeline completion rates and substitution elasticity from competing superfruits. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Juice Market
Organic Food and Beverages
Europe Organic Food Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
Organic Ice Cream Market
Organic Food and Beverages
Global Organic Dried Fruit Market
Organic Food and Beverages
Organic Coconut Syrup Market
Organic Food and Beverages
Natural Food and Drinks Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
Organic Stevia Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
Organic Acai Juice Market
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
UAE Organic Food Market