
 North America Gluten Free Bakery Mixes Market | 2026-2036
North America Gluten Free Bakery Mixes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gluten Free Bakery Mixes Market Analysis
Canadian oat milling capacity is repositioning toward certified gluten-free supply chains to serve North American bakery mix manufacturers. General Mills leverages its sourcing infrastructure to secure dedicated gluten-free oat streams for its mix portfolio. Bob's Red Mill Natural Foods sustains its market presence through vertical integration from grain procurement to packaged goods. King Arthur Baking Company differentiates via rigorous third-party certification protocols that command premium shelf placement.
Gluten free bakery mixes comprise formulated dry blends utilizing rice flour, tapioca starch, xanthan gum, and alternative binders to replicate wheat-dependent baking performance without gluten protein networks. These mixes typically require precise hydration ratios and shorter mixing cycles to prevent gumminess in finished products, serving both home bakers and commercial operations seeking consistent, safe outputs. Bread mixes and all-purpose mixes occupy the largest volume positions, though cake mixes capture disproportionate margin pools through occasion-based gifting and celebration baking. The food service end user segment shows the steepest trajectory as restaurants and cafés build dedicated gluten-free prep lines to reduce cross-contamination liability.
The FDA enforces its gluten-free labeling rule requiring sub-20 ppm gluten content, while Health Canada maintains parallel standards that govern cross-border product movement. Both frameworks elevate compliance costs for smaller regional blenders while creating market access barriers for uncertified imports. State-level cottage food laws in Texas and Florida introduce additional variance for small-batch producers selling direct to consumers. Stakeholders must monitor evolving allergen threshold science and potential harmonization pressures between US and Canadian enforcement postures.
Market Dynamics
The FDA's sub-20 ppm gluten-free labeling rule and Health Canada's parallel standard are compressing formulation margins while simultaneously creating compliance moats that favor scaled blenders over regional competitors. This regulatory scaffolding now dictates capital allocation across the North American supply base.
Growth Catalysts
- Celiac disease diagnostic rates:Rising physician screening protocols in the United States and Canada expand the addressable patient population requiring certified gluten-free products.
- Health Canada's gluten-free standard:Cross-border regulatory alignment reduces formulation complexity for manufacturers serving both Canadian and US markets.
- Dedicated gluten-free oat streams:Canadian milling infrastructure investment secures certified raw material supply for bread and all-purpose mix production.
Market Restraints
- Input cost volatility:Tapioca starch and rice flour prices fluctuate with Southeast Asian harvest cycles, squeezing gross margins for unhedged blenders.
- Supply concentration risk:Xanthan gum production concentrates among a handful of fermentation facilities, creating single-source vulnerability for binding agents.
- Technical limitation:Gluten-free doughs lack the extensibility of wheat-based systems, limiting industrial automation compatibility in high-speed bakery lines.
Strategic Opportunities
- Underpenetrated food service channel:Independent restaurants in Texas and Florida lack dedicated gluten-free prep infrastructure, creating first-mover advantage for certified mix suppliers.
- Regulatory tailwind:State-level cottage food law expansion in the southern United States enables small-batch direct-to-consumer sales without commercial kitchen overhead.
- Emerging application:Frozen gluten-free pizza crust mixes for retail represent whitespace as pizzeria chains build dedicated production lines.
Industry Challenges
- Certification timeline compression:Third-party gluten-free certification from accredited bodies requires 6-12 month validation cycles that delay new product launches.
- Cross-contamination control:Commercial bakeries must segregate equipment and ventilation systems, driving capital intensity for multi-format operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gluten Free Bakery Mixes Market |
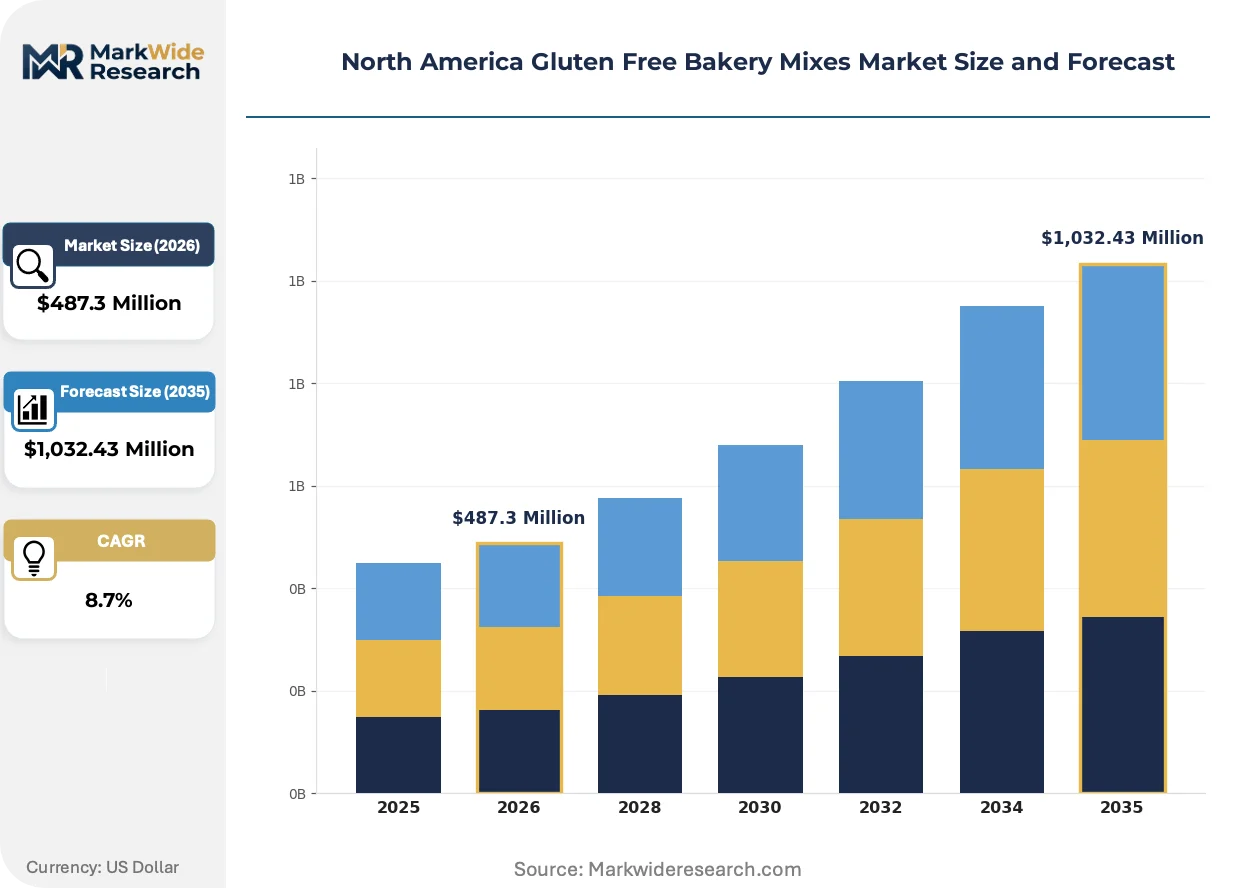
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Purpose Mixes, Bread Mixes, Cake Mixes, Muffin Mixes End User: Household, Food Service, Retailers, Bakeries Distribution Channel: Online, Supermarkets, Health Food Stores, Specialty Shops Form: Dry Mix, Ready-to-Bake, Frozen, Organic |
| Companies Covered | General Mills, Bob's Red Mill Natural Foods, King Arthur Baking Company, Pamela's Products, Canyon Bakehouse, Udi's Gluten Free Foods, Simple Mills, Krusteaz, Dr. Schär, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gluten Free Bakery Mixes Market Emerging Trajectories
Formulation science is advancing beyond simple wheat substitution toward functional ingredient systems that replicate gluten's viscoelastic properties. These developments are compressing the performance gap between conventional and gluten-free bakery outputs.
Enzymatic processing of rice and sorghum proteins is absorbing the structural role previously filled by chemical binders in premium mix formulations. Food service distributors in California and the Pacific Northwest are accelerating procurement of these enzyme-modified blends. The technology is absorbing market share from xanthan gum-dependent formulations by delivering cleaner label declarations.
The FDA maintains strict enforcement of its gluten-free labeling rule while Health Canada coordinates inspection protocols for cross-border shipments. This regulatory posture elevates compliance costs for uncertified imports and redirects sourcing toward domestic blenders. Small regional manufacturers in both countries are responding by consolidating under shared third-party certification umbrellas.
Home bakers are migrating toward subscription-based replenishment models for specialty mixes rather than supermarket aisle purchasing. Direct-to-consumer channels are displacing conventional grocery distribution for premium price-tier products. This behavioral shift concentrates most visibly in urban clusters across California and the Pacific Northwest where health-conscious consumption patterns predominate.
North America Gluten Free Bakery Mixes Market Segmentation
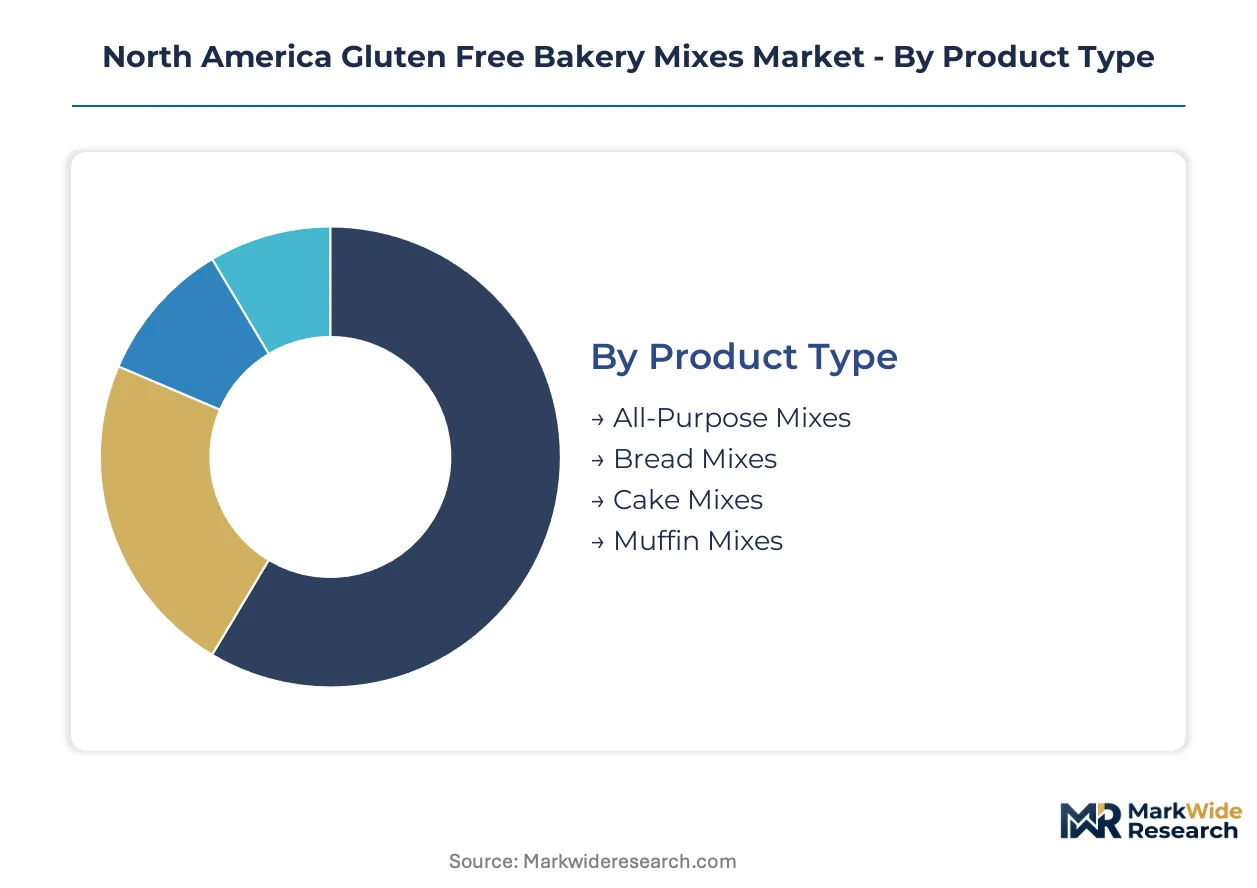
Segmentation in the North American gluten-free bakery mixes market reveals distinct capital requirements, formulation complexity, and channel economics. Manufacturers allocate R&D budgets differently across product types while distribution strategies diverge sharply between household and food service end users.
Product Type:
Capital intensity peaks in bread mix production, where dedicated gluten-free oat milling infrastructure and extended fermentation testing cycles drive fixed cost structures.
- All-Purpose Mixes:Versatile formulations combining rice flour, tapioca starch, and xanthan gum serve multiple baking applications from pancakes to cookies. Demand concentrates in California and the Pacific Northwest, where home bakers prioritize pantry consolidation and premium ingredient sourcing over single-purpose alternatives.
- Bread Mixes:Complex systems requiring precise hydration control and extended proofing protocols to replicate wheat gluten networks. Food service operators in Texas and Florida are expanding procurement as restaurants build dedicated gluten-free prep lines to serve celiac-diagnosed patrons.
- Cake Mixes:Occasion-driven purchases with higher margin profiles tied to celebration baking and gifting cycles.
- Muffin Mixes:Single-serve convenience formats gaining traction in grab-and-go retail channels.
Most installed capacity flows through All-Purpose Mixes. Expansion is steepest in Bread Mixes.
End User:
Customer type dictates formulation batch sizes, certification requirements, and technical support intensity, with food service demanding the most specialized account management.
- Food Service:Restaurants, cafés, and institutional kitchens requiring certified gluten-free supply chains with documented cross-contamination prevention protocols. Operators in Canada and the United States face liability exposure that drives preference for third-party validated mixes over commodity alternatives.
- Household:Home bakers purchasing through subscription replenishment models and direct-to-consumer channels, particularly in urban health-conscious clusters across California and the Pacific Northwest.
- Retailers:Grocery chains and mass merchandisers negotiating private-label arrangements with certified blenders.
- Bakeries:Small commercial producers seeking consistent outputs without in-house formulation expertise.
Volume concentration sits with Household purchasers. Food Service is gaining share fastest as celiac diagnoses climb and operators expand gluten-free menu offerings.
Distribution Channel:
Channel selection determines margin retention, with direct sales capturing value that intermediaries absorb in conventional retail.
- Online:Direct-to-consumer platforms and subscription services displacing supermarket aisles for premium-tier products. This channel concentrates in California and the Pacific Northwest where digital-native purchasing patterns intersect with health-conscious consumption.
- Supermarkets:Mass-market penetration requiring slotting fees and promotional support that compresses net margins for regional blenders.
- Health Food Stores:Curated assortments favoring third-party certified products with clean-label positioning.
- Specialty Shops:Independent retailers serving niche dietary communities with personalized technical guidance.
Supermarkets still move the largest unit volumes. Online is expanding most quickly as subscription models capture repeat purchasing.
Form:
Physical format shapes supply chain requirements, with frozen and ready-to-bake variants demanding cold-chain infrastructure that dry mixes avoid.
- Dry Mix:Shelf-stable powdered blends requiring precise hydration ratios and shorter mixing cycles to prevent gumminess. This format dominates household and food service procurement due to lower logistics costs and extended dating.
- Ready-to-Bake:Pre-hydrated doughs and batters reducing labor input for time-constrained operators.
- Frozen:Pizza crust mixes and par-baked bases requiring temperature-controlled distribution.
- Organic:Certified ingredient sourcing commanding premium positioning in health food channels.
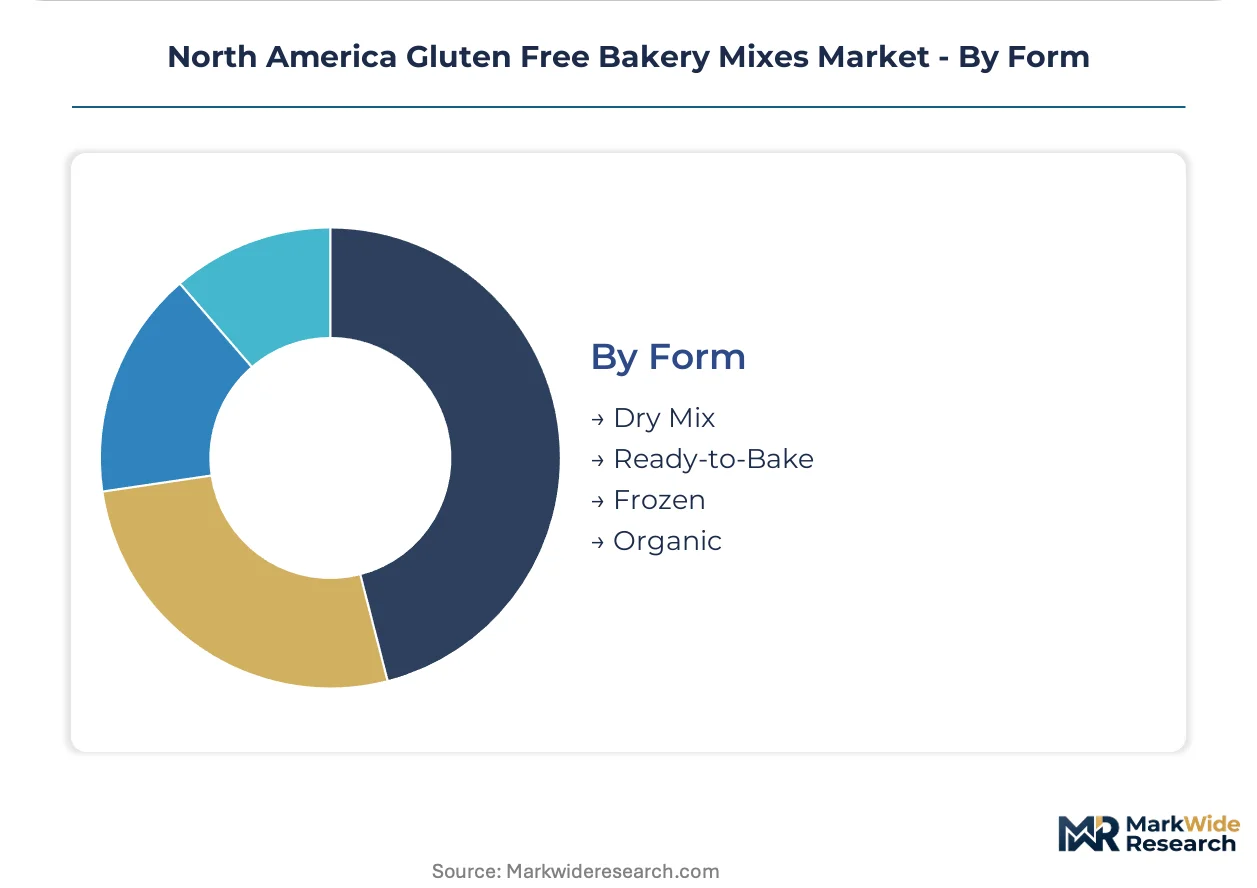
Dry Mix carries the heaviest installed capacity. Ready-to-Bake shows the steepest expansion trajectory as food service operators prioritize labor efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate blending capacity toward jurisdictions with streamlined certification pathways. The FDA's sub-20 ppm enforcement and Health Canada's parallel standards create compliance cost differentials that favor scaled operators with cross-border quality systems.
United States
Celiac disease screening expansion and food service liability exposure drive mix procurement across Texas and Florida restaurant chains. The FDA enforces gluten-free labeling with documented inspection protocols that elevate entry barriers for uncertified imports. California's health-conscious consumer clusters anchor premium subscription channel growth for direct-to-consumer blenders.
Canada
Certified gluten-free oat milling infrastructure investment supports bread mix supply security for North American manufacturers. Health Canada's gluten-free standard aligns with FDA thresholds, reducing dual-formulation burdens for cross-border producers. Prairie Provinces oat processors are capturing dedicated supply chain contracts from major blenders seeking backward integration.
Mexico
Specialty ingredient import dependency creates formulation cost pressures for domestic bakery operators serving tourist corridors. The country's national food safety regulator maintains evolving allergen threshold guidelines that lag US-Canada harmonization. Mexico City Metro food service distributors are expanding gluten-free menu procurement as international hotel chains standardize celiac-safe offerings.
North America Gluten Free Bakery Mixes Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-label enzyme-modified formulations and direct-to-consumer subscription models. The vendor base stratifies across three tiers: multinational food conglomerates with captive ingredient sourcing, regional specialty millers with third-party certification umbrellas, and venture-backed niche entrants leveraging digital-native distribution. Consolidation pressure concentrates among mid-scale blenders lacking dedicated gluten-free facility segregation. Dominant competitive moves include backward integration into certified oat supply chains and strategic partnerships with food service distributors building dedicated prep line protocols.
Within the multinational tier, General Mills and Bob's Red Mill Natural Foods exemplify divergent sourcing strategies—one leveraging commodity-scale infrastructure, the other vertical control from grain procurement through packaged goods. King Arthur Baking Company occupies a position defined by third-party certification rigor that commands premium retail placement. These three anchors illustrate how compliance investment and supply chain configuration separate sustainable market presence from marginal competitors.
| Leading Market Players |
|---|
| General Mills |
| Bob's Red Mill Natural Foods |
| King Arthur Baking Company |
| Pamela's Products |
| Canyon Bakehouse |
| Udi's Gluten Free Foods |
| Simple Mills |
| Krusteaz |
| Dr. Schär |
| Others |
Supply Flow & Price Mechanics
Family-owned milling specialists with multi-generational grain procurement relationships anchor supply discipline across the North American gluten-free bakery mix landscape, translating certified oat stream scarcity into sustained premium pricing power against commodity-blender competition.
Pricing Analysis
Distributor margin compression in conventional retail channels is accelerating channel migration toward direct-to-consumer subscription models that capture full markup. Three-tier pricing structure across premium enzyme-modified, standard certified, and economy private-label levels separates King Arthur Baking Company's third-party validated positioning from mass-market alternatives. Pricing pressure stems from Southeast Asian tapioca starch harvest volatility that squeezes unhedged regional blenders. Food service operators show least price sensitivity due to liability-driven preference for certified supply chains, while household bargain segments drive private-label growth.
Supply Chain Analysis
Dual-sourcing requirements mandated by major food service distributors are reshaping procurement patterns across Canadian Prairie Provinces and US Upper Midwest oat processing hubs. Raw material flows draw from certified gluten-free oat milling in Saskatchewan and Manitoba, xanthan gum fermentation facilities concentrated in China and Austria, and rice flour processing anchored in Arkansas and California. Single-source vulnerability concentrates in xanthan gum binding agents where fermentation capacity clusters among three global suppliers. Distribution runs through food service broadline distributors in Texas and Florida, direct-to-consumer platforms in California, and health food store networks across the Pacific Northwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA sub-20 ppm enforcement and Health Canada parallel standards permanently expand the certified-product addressable base beyond transient health trends.
For Market Incumbents: Deploy dedicated gluten-free facility segregation as the defensive anchor against mid-scale blender consolidation pressure. Acquire Prairie Provinces oat milling capacity to secure backward integration into certified grain streams before supply contracts lock. Channel control through food service distributor partnerships with documented cross-contamination protocols protects margin position against private-label encroachment.
For New Entrants and Emerging Players: Enzymatic rice protein modification technology offers a clean-label wedge against xanthan gum-dependent incumbents. White-space concentration sits in frozen pizza crust mixes for pizzeria chains building dedicated production lines, with Texas and Florida restaurant chains showing lowest current penetration. Direct-to-consumer subscription launch targeting California and Pacific Northwest urban clusters bypasses slotting fee barriers that crush supermarket margins.
For Investors and Strategic Acquirers: Food conglomerates with existing gluten-free brand portfolios are the most active acquirer in this space, seeking certified facility assets to fill portfolio gaps. Mid-scale blenders lacking dedicated gluten-free segregation represent the target archetype as consolidation pressure intensifies. Watch Health Canada-FDA enforcement harmonization discussions as the signal for accelerated cross-border M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Gluten-Free Facility Investment | FDA and Health Canada compliance moats protect margin position against uncertified imports. |
| Backward Integration into Oat Supply | Saskatchewan and Manitoba milling contracts secure raw material scarcity leverage. |
| Enzymatic Binder Technology Transition | Clean-label enzyme-modified formulations displace xanthan gum in premium tier positioning. |
| Food Service Distributor Partnership | Documented cross-contamination protocols reduce operator liability exposure in Texas and Florida. |
| Direct-to-Consumer Subscription Launch | California and Pacific Northwest digital-native channels bypass supermarket slotting fees. |
Methodological Framework
Bottom-up household and food service procurement modeling reconciled against top-down certified ingredient supply tracking forms the analytical core of this study. Primary interviews with bakery R&D directors, food service procurement managers, health food store category buyers, and third-party certification body auditors combined with secondary validation from FDA enforcement actions, Health Canada regulatory filings, USDA grain production statistics, and customs import records. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of certified gluten-free oat milling capacity expansion and enzyme-modified formulation adoption rates informs projection trajectories across the analysis window. Segmentation modeling spans product type, end user, distribution channel, and physical form dimensions with CAGRs derived from regression against celiac diagnosis screening expansion and food service liability incident patterns. Forecast inputs include Prairie Provinces harvest yield variability and xanthan gum fermentation facility utilization rates.
The model holds under sustained FDA and Health Canada enforcement postures; deviation in regulatory threshold relaxation or oat supply contamination events would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Frozen Bakery Market
Bakery Products
Global Rice Cakes Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Layer Cake Mixes Market
Bakery Products
Pizza Crust Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Low-Calorie Breakfast Muffins Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Flour Mixes Market
Bakery Products
Global Cakes Market
Bakery Products
Low Calorie Cake Market
Bakery Products
Low Fat Chocolate Cake Market
Bakery Products
Tunnel Bakery Oven Market
Bakery Products
Baking Molds and Trays Market
Bakery Products
United States Bread Market
Bakery Products
Instant Cake Emulsifier Market