
 Italy Food Enzymes Market | 2026-2036
Italy Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Food Enzymes Market Foresight
Italian enzyme production capacity is realigning as domestic biotech fermentation facilities expand to serve Mediterranean food processors. Novozymes leverages its microbial strain library to dominate northern Italy's industrial baking corridor. Kerry Group anchors supply relationships with major pasta and sauce manufacturers across the Emilia-Romagna region. Biochem Srl specializes in tailored enzyme blends for traditional Italian cheese aging protocols, differentiating against standardized imports.
Food enzymes comprise protein-based biocatalysts, typically operating at temperatures between 30°C and 60°C and pH ranges of 4.0 to 8.0, that accelerate specific biochemical reactions in food matrices without becoming consumed in the process. These catalysts serve industrial food production by enabling precise control over texture development, shelf-life extension, and flavor biogenesis while permitting cleaner ingredient declarations than chemical alternatives. Amylase and protease formulations lead product demand due to their entrenched roles in durum wheat processing and aged cheese maturation, whereas lactase is expanding fastest as Italian dairy processors reformulate for lactose-free positioning. Microbial-sourced enzymes command the dominant share of supply volumes given their reproducible fermentation economics and favorable kosher and halal certification pathways.
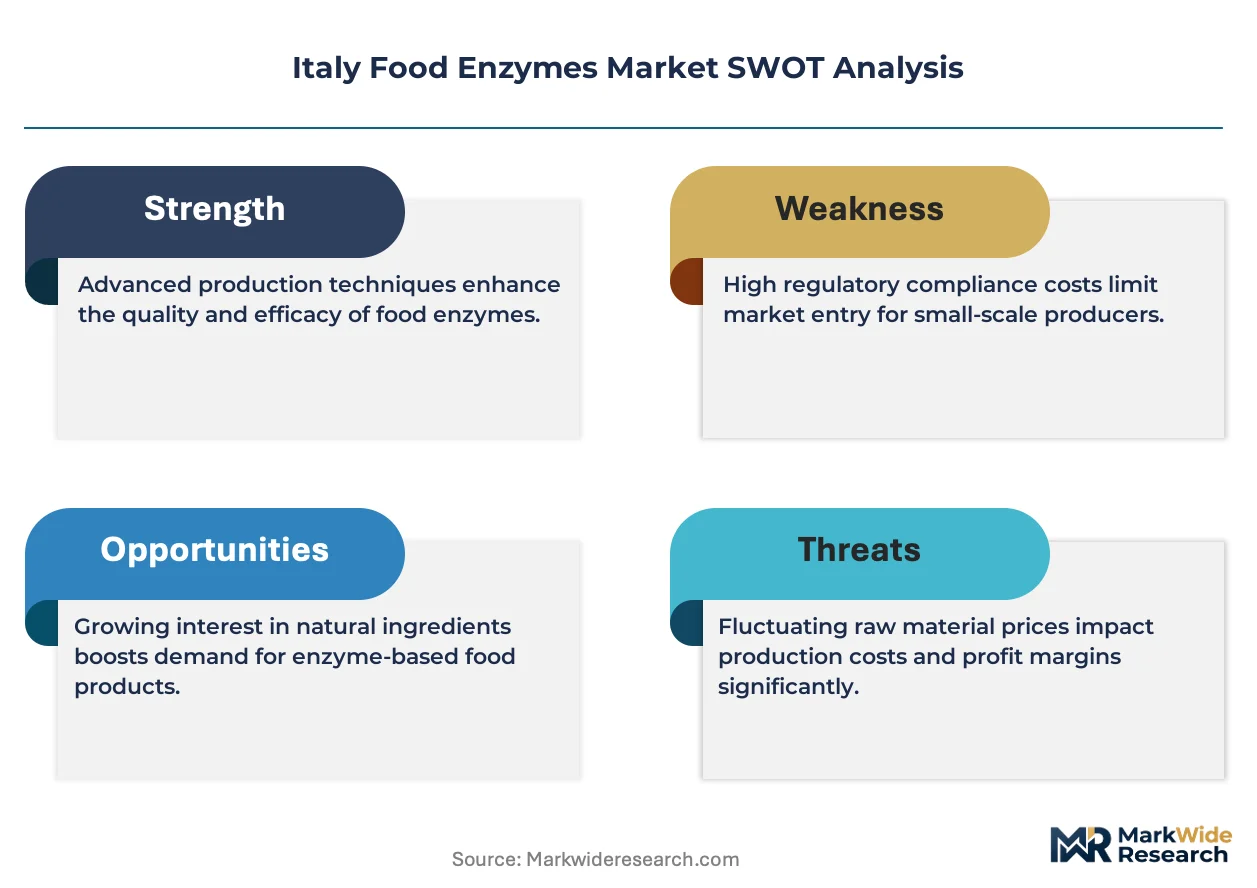
EFSA guidelines on novel food enzyme safety assessments, combined with Italy's Ministry of Health enforcement of EU food additive regulations, create compliance thresholds that favor established suppliers with dossier-ready toxicology packages. The EU Green Deal's pesticide and additive reduction targets are redirecting Italian processors toward enzyme-based process aids that avoid E-number labeling requirements. Stakeholders must monitor evolving EFSA opinion timelines and regional clean-label procurement mandates to anticipate qualification windows ahead of competitor filings.
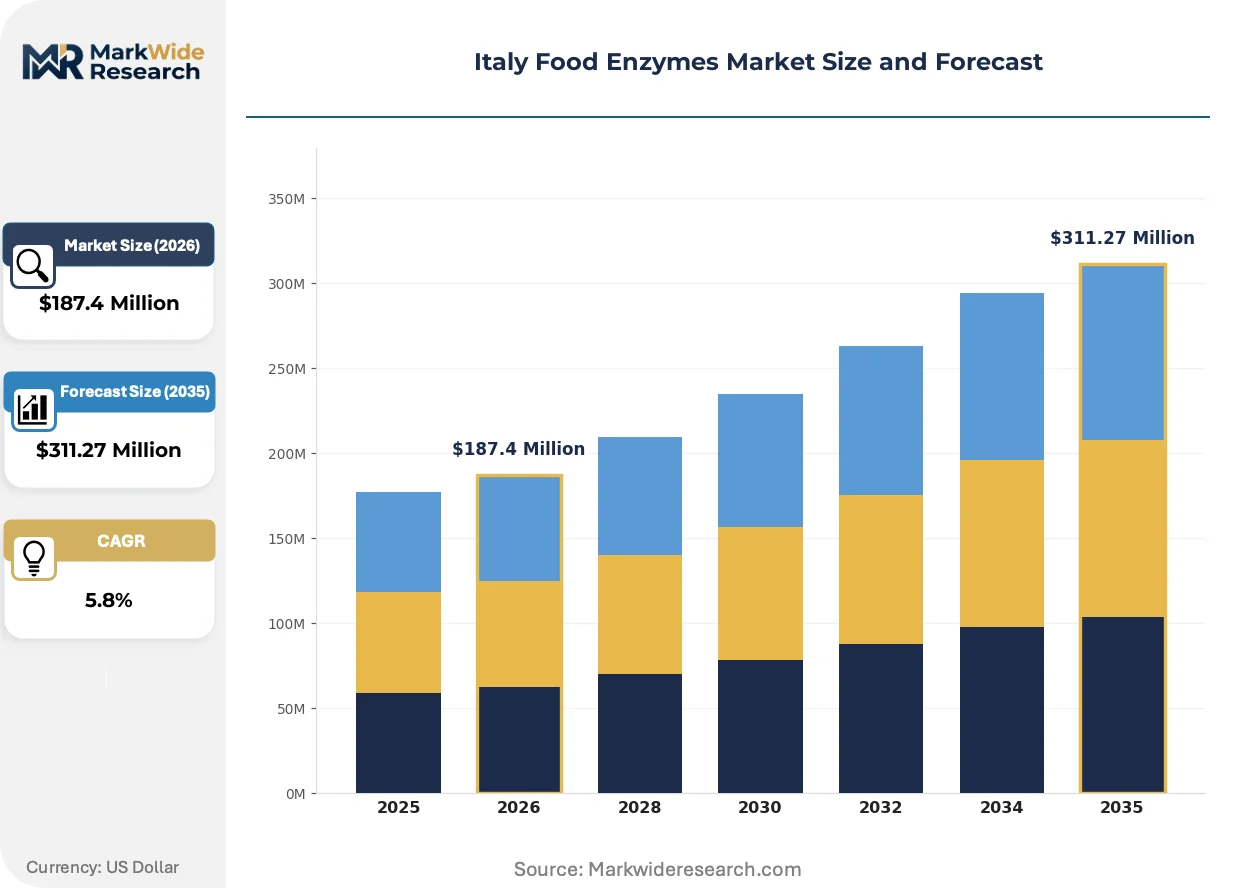
Market Dynamics
The EU Green Deal's additive reduction mandates are compressing chemical improver volumes across Italian baking and dairy corridors, redirecting procurement toward fermentation-derived process aids that bypass E-number labeling requirements.
Growth Catalysts
- EFSA Novel Food Enzyme Pathway:Streamlined safety assessment protocols for microbial-derived biocatalysts accelerate qualification timelines for domestic fermentation facilities serving Emilia-Romagna pasta processors.
- Lactose-Free Dairy Reformulation:Italian cheesemakers deploy lactase systems to capture expanding intolerance-sensitive consumer segments without altering traditional aging protocols.
- Clean-Label Baking:Industrial bakers from Milan to Bologna replace potassium bromate and azodicarbonamide with amylase-protease blends to satisfy retailer procurement mandates.
Market Restraints
- Fermentation Input Volatility:Molasses and corn steep liquor price swings squeeze margins for domestic enzyme manufacturers dependent on agricultural feedstock supply chains.
- Import Concentration Risk:Standardized enzyme formulations from Northern European suppliers dominate commodity segments, limiting pricing autonomy for Italian blenders.
- Thermostability Ceiling:Microbial protease variants face performance degradation above 55°C in high-temperature pasta extrusion applications.
Strategic Opportunities
- Southern Italy Underpenetration:Campania and Sicily processing clusters remain reliant on chemical additives, creating first-mover openings for enzyme-based clean-label alternatives.
- Plant-Based Dairy Convergence:Lipase and phospholipase systems enable texture replication in oat and almond milk formulations targeting flexitarian demographics.
- Farm to Fork Procurement Incentives:EU Green Deal implementation funds subsidize enzyme adoption for small-scale PDO cheese producers in Tuscany and Piedmont.
Industry Challenges
- Fermentation Scale-Up Expertise Gap:Italian biotech facilities lack sufficient downstream processing engineers to match Northern European yield efficiencies.
- EFSA Dossier Compilation Burden:Toxicology package preparation timelines extend 18-24 months, delaying market entry for novel strain-derived formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Food Enzymes Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Protease, Lactase, Cellulase Application: Baking, Dairy, Confectionery, Beverages Source: Microbial, Plant, Animal, Fungal End User: Food Processing, Food Service, Retail, Beverage Production |
| Companies Covered | Kerry Group, Novozymes, Koninklijke DSM N.V., Chr. Hansen Holding, BASF SE, Advanced Enzymes, DuPont de Nemours, Associated British Foods, Biochem Srl, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Food Enzymes Market Shifts & Advancements
Biocatalysis platforms are converging with precision fermentation to deliver enzyme systems tailored to specific Italian wheat varieties and milk proteomes, compressing development cycles from years to months.
Cell-free enzyme engineering is absorbing capital allocation from traditional whole-cell fermentation. Italian biotech startups deploy in vitro protein synthesis to generate thermostable amylase variants optimized for durum wheat semolina processing. Pasta manufacturers in Parma and Modena pilot these systems to reduce gelatinization temperature requirements. The technology is absorbing market share from conventional submerged fermentation by eliminating strain stability risks.
EU Green Deal pesticide and additive reduction targets are rewriting procurement specifications across Italian retail channels. Large-scale distributors now mandate enzyme-based process aids for private-label bread and fresh pasta lines to avoid E-number declarations. The Farm to Fork Strategy enforcement through Italy's Ministry of Health inspections is accelerating compliance investments among mid-tier processors.
Ingredient specification unbundling is fragmenting traditional enzyme supply relationships. Industrial bakeries in the Milan corridor now source amylase, xylanase, and lipase components separately rather than purchasing pre-blended improvers. This pattern compresses supplier margins while elevating technical service requirements. Northern Italian milling clusters exhibit the most pronounced shift toward component-level procurement.
Italy Food Enzymes Market Segmentation
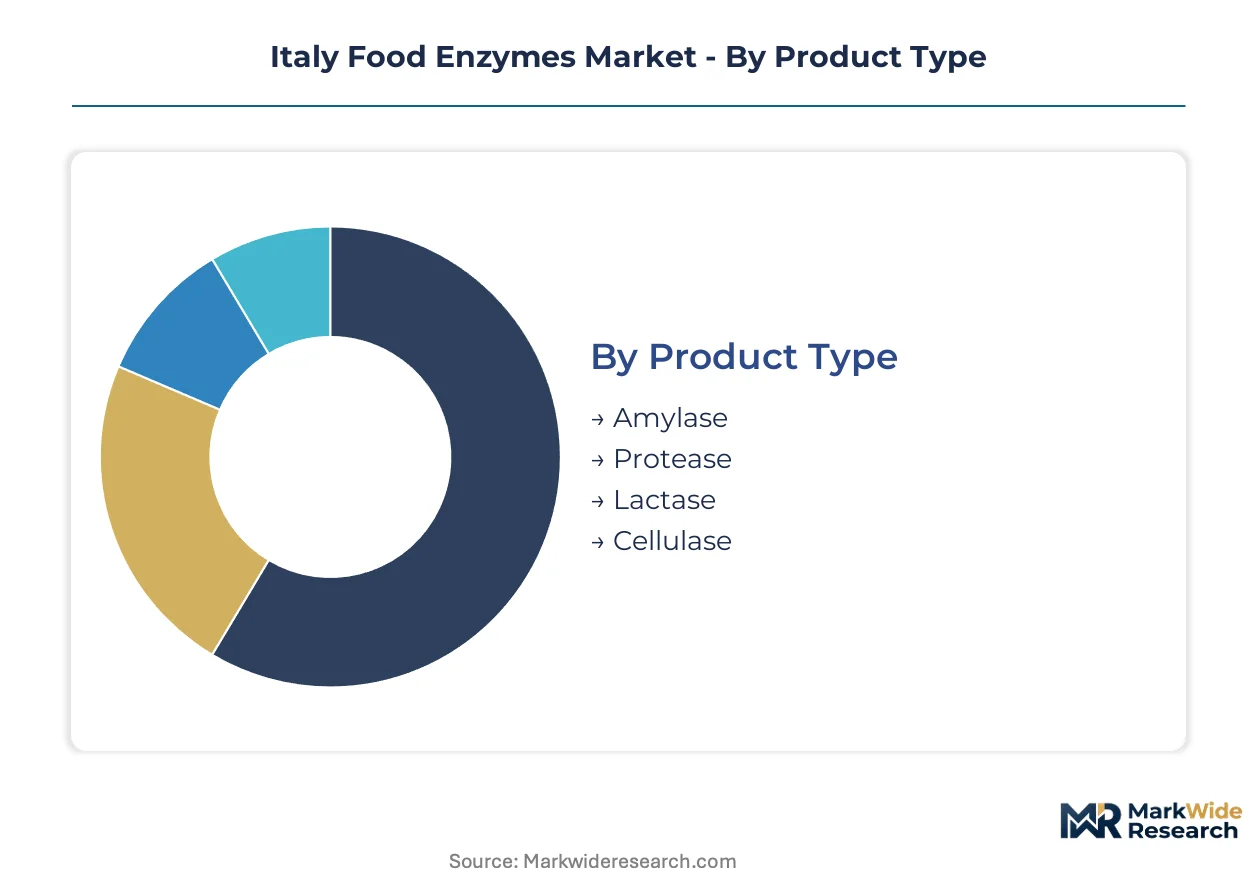
Enzyme procurement patterns across Italy's food processing corridors diverge sharply between commodity formulations and precision-tailored biocatalyst systems. Understanding these segment boundaries clarifies where domestic fermentation investments align with processor specifications versus import dependency zones.
Product Type:
Standalone enzyme actives dominate northern Italy's industrial baking and dairy clusters, whereas pre-blended formulations penetrate smaller processors lacking in-house formulation expertise.
- Amylase:These starch-hydrolyzing biocatalysts operate optimally at 50-60°C with pH stability between 5.5-7.0, enabling controlled sugar release in durum wheat processing. Demand concentrates across Parma and Modena pasta extrusion facilities where gelatinization control determines finished texture quality, though thermostability ceilings above 55°C constrain high-temperature applications.
- Protease:Protein-cleaving enzymes function across broader pH ranges (4.0-8.5) to accelerate gluten development in bread doughs and peptide maturation in aged cheeses. Northern Italian milling corridors from Milan to Bologna deploy these systems to replace chemical dough conditioners under retailer clean-label mandates.
- Lactase:Beta-galactosidase enzymes hydrolyze lactose into glucose-galactose for intolerance-sensitive dairy positioning.
- Cellulase:Cell wall-degrading biocatalysts improve extraction yields in fruit processing and modify fiber texture in functional foods.
Volume placements concentrate in amylase and protease for traditional wheat and dairy applications; the faster expansion belongs to lactase as dairy processors reformulate for intolerance-sensitive segments.
Application:
Cost tier stratification separates artisan-scale producers purchasing enzyme systems through distributor networks from industrial processors negotiating direct fermentation supply contracts.
- Baking:Industrial bakers across the Milan-Bologna corridor deploy amylase-xylanase blends to replace potassium bromate and azodicarbonamide, satisfying E-number avoidance requirements under EU Green Deal procurement specifications.
- Dairy:Lactase systems enable lactose-free milk and cheese positioning without altering traditional aging protocols, capturing expanding intolerance-sensitive consumer bases in Lombardy and Emilia-Romagna.
- Confectionery:Invertase and glucose oxidase formulations control crystallization and moisture retention in sugar-based products.
- Beverages:Pectinase and cellulase systems clarify fruit juices and improve extraction economics.
Procurement scale clusters in baking and dairy; confectionery and beverage applications are climbing fastest as processors diversify beyond traditional categories.
Source:
Supply concentration favors microbial fermentation platforms given reproducible economics and streamlined kosher and halal certification pathways versus plant or animal alternatives.
- Microbial:Bacterial and yeast-derived enzymes dominate commercial volumes through submerged fermentation economics, with Italian biotech facilities expanding strain libraries to serve Mediterranean food processors.
- Plant:Bromelain from pineapple and papain from papaya serve niche applications in meat tenderization and specialty baking.
- Animal:Rennet and lipase extracts from calf stomach and pancreatic tissues persist in traditional PDO cheese protocols.
- Fungal:Aspergillus-derived amylase and protease variants offer broader pH tolerance for acidic food matrices.
Microbial sources anchor procurement volumes; fungal platforms are gaining share fastest for pH-flexible processing applications.
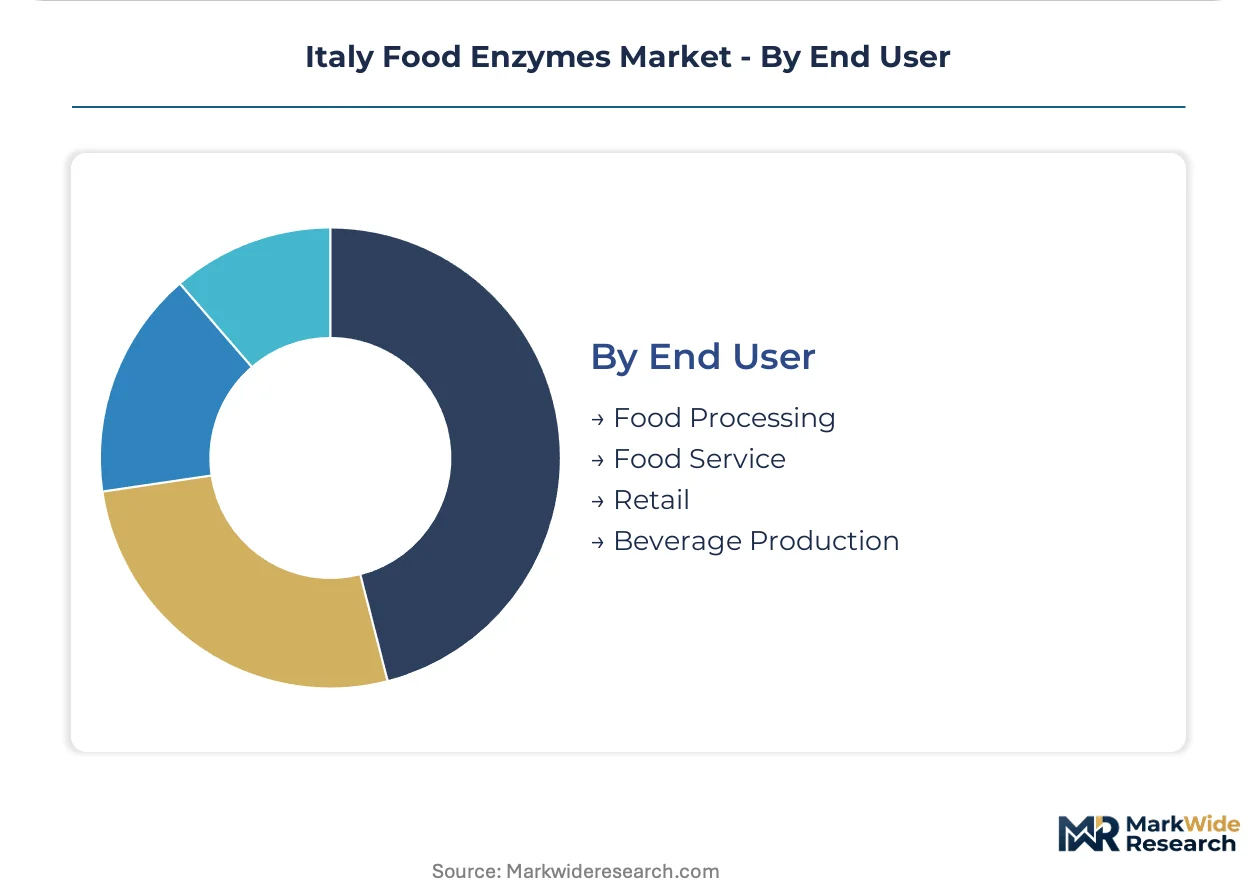
End User:
Customer type determines formulation complexity, with industrial processors demanding technical service integration and retail channels prioritizing clean-label declarations.
- Food Processing:Large-scale pasta manufacturers in Emilia-Romagna and dairy cooperatives in Lombardy negotiate direct supply relationships with fermentation facilities, embedding enzyme specifications into production protocols.
- Food Service:Bakery chains and restaurant groups purchase pre-blended improvers through distributor networks lacking technical optimization support.
- Retail:Private-label bread and fresh pasta specifications increasingly mandate enzyme-based process aids to avoid E-number labeling.
- Beverage Production:Juice processors and wine makers deploy pectinase and glucanase systems for clarification and filtration efficiency.
Food processing commands placement scale; beverage production is expanding most quickly as enzyme clarification displaces traditional fining agents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Molasses and corn steep liquor supply chains from Emilia-Romagna's agricultural belt anchor Italy's food enzyme fermentation capacity. Northern industrial corridors concentrate procurement scale, while southern regions present expansion frontiers for clean-label alternatives.
Lombardy
Industrial bakeries in Milan deploy amylase-xylanase blends to replace chemical dough conditioners under retailer E-number avoidance mandates. The EU Green Deal's Farm to Fork Strategy enforcement through regional health inspections accelerates compliance investments. Dairy cooperatives across the Po Valley negotiate direct lactase supply contracts for intolerance-sensitive cheese positioning.
Emilia-Romagna
Parma and Modena pasta extrusion facilities drive thermostable amylase demand for durum wheat gelatinization control. EFSA novel food enzyme safety assessment protocols streamline qualification for domestic fermentation facilities serving regional processors. Bologna's milling clusters exhibit pronounced shifts toward component-level enzyme procurement rather than pre-blended improvers.
Piedmont
PDO cheese producers in Tuscany-adjacent zones access EU Green Deal implementation funds subsidizing enzyme adoption for traditional aging protocols. The Ministry of Health's enforcement of additive reduction targets redirects small-scale processors toward fermentation-derived process aids. Turin-based dairy reformulation labs pilot lactase systems for lactose-free positioning without protocol alteration.
Veneto
Confectionery manufacturers in Verona deploy invertase and glucose oxidase for crystallization control in sugar-based products. Regional biotech facilities expand microbial strain libraries to serve Mediterranean food processors seeking kosher and halal certification pathways. Padua's ingredient distributors fragment traditional supply relationships through specification unbundling.
Campania
Processing clusters around Naples remain reliant on chemical additives, creating first-mover openings for enzyme-based clean-label alternatives. Southern Italy's underpenetration contrasts with northern procurement sophistication. Local pasta and sauce manufacturers lack technical service integration for precision fermentation systems.
Italy Food Enzymes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision-tailored biocatalyst systems for specific wheat varieties and milk proteomes. The market structures around three tiers: multinational fermentation specialists with dossier-ready toxicology packages, regional blenders serving Mediterranean processors, and domestic biotech startups deploying cell-free enzyme engineering. Consolidation pressures favor suppliers with streamlined EFSA qualification pathways. Competitive moves center on capacity expansion in northern Italian fermentation corridors and strategic partnerships with Emilia-Romagna pasta processors.
Among Irish-anchored nutrition specialists, Kerry Group represents the integrated formulation tier, embedding enzyme specifications into production protocols across pasta and sauce manufacturers. Danish biotechnology specialists exemplify the strain-library dominance model, leveraging microbial platforms to serve industrial baking corridors. Domestic Italian biotechnology limited companies occupy the precision-tailored tier, specializing in enzyme blends for traditional cheese aging protocols and differentiating against standardized imports through regional formulation expertise.
| Leading Market Players |
|---|
| Kerry Group |
| Novozymes |
| Koninklijke DSM N.V. |
| Chr. Hansen Holding |
| BASF SE |
| Advanced Enzymes |
| DuPont de Nemours |
| Associated British Foods |
| Biochem Srl |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between EFSA-dossier-ready formulations and unregistered commodity imports shapes both procurement premiums and supplier selection across Italy's food enzyme corridors. Domestic biotech facilities command pricing power through streamlined regulatory pathways, while standardized Northern European imports compete on volume terms.
Pricing Analysis
Technical service bundling separates premium domestic suppliers from unbundled commodity traders. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA qualification status, strain proprietary depth, and formulation customization scope. Pricing pressure stems from molasses and corn steep liquor feedstock volatility squeezing fermentation margins. Small-scale PDO cheese producers in Tuscany exhibit highest price sensitivity, whereas industrial pasta manufacturers in Emilia-Romagna prioritize performance consistency over unit cost.
Supply Chain Analysis
Freight cost differentials between Northern European bulk shipments and domestic Italian fermentation runs influence procurement decisions across the Milan-Bologna industrial corridor. Supply concentrates in Denmark, the Netherlands, and domestic Italian biotech facilities expanding strain libraries. Raw material dependencies center on molasses substrates, corn steep liquor nitrogen sources, and specialized microbial culture media. Single-source vulnerability persists for thermostable protease variants optimized for high-temperature pasta extrusion. Distribution runs through direct fermentation supply contracts with large-scale processors and distributor networks serving artisan-scale producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's food enzyme sector sits at a technology-transition inflection as cell-free enzyme engineering displaces traditional submerged fermentation platforms. Precision biocatalysis systems are replacing legacy whole-cell production methods across durum wheat processing applications.
For Market Incumbents: Hedge against cell-free enzyme engineering disruption by acquiring in vitro protein synthesis capabilities or partnering with Italian biotech startups piloting thermostable amylase variants. Expand downstream processing engineering capacity to close yield efficiency gaps with Northern European competitors. EFSA dossier compilation timelines represent a critical defensive moat against rapid commoditization.
For New Entrants and Emerging Players: The premium-economy price-point gap in Southern Italy's underpenetrated Campania and Sicily clusters offers immediate white-space access. Target Naples-area pasta and sauce manufacturers still reliant on chemical additives with clean-label enzyme alternatives and embedded technical service support. Pursue EU Green Deal implementation fund qualification to subsidize initial adoption costs among small-scale processors.
For Investors and Strategic Acquirers: Re-rating potential sits with precision-tailored enzyme specialists given convergence between biocatalysis platforms and precision fermentation compressing development cycles. Long-term viability hinges on strain library depth and EFSA regulatory navigation capabilities across a multi-year horizon. Monitor EFSA opinion timelines for novel food enzyme safety assessments as the critical inflection signal for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Dossier Investment | Streamlined toxicology packages accelerate qualification timelines for domestic fermentation facilities serving Emilia-Romagna processors. |
| Cell-Free Enzyme Engineering Adoption | In vitro protein synthesis eliminates strain stability risks while generating thermostable variants optimized for durum wheat semolina. |
| Southern Italy Geographic Expansion | Campania and Sicily processing clusters remain reliant on chemical additives, creating first-mover openings for enzyme-based alternatives. |
| Backward Integration into Feedstock Supply | Captive molasses and corn steep liquor sourcing insulates margins from agricultural commodity price swings. |
| Technical Service Embedding | Direct fermentation supply relationships with large-scale pasta manufacturers lock in component-level procurement shifts away from pre-blended improvers. |
Research Methodology
Independent corroboration across primary interviews with fermentation facility directors, EFSA regulatory consultants, and Emilia-Romagna pasta procurement leads underwrites the qualitative findings. Secondary validation draws from EFSA novel food enzyme safety opinions, EU Green Deal implementation documentation, and Italian Ministry of Health enforcement records. Bottom-up enzyme volume estimates from regional processing clusters triangulate against top-down market sizing from fermentation capacity expansion announcements.
Rate-of-change decomposition across enzyme source transitions, application mix shifts, and end-user procurement pattern evolution anchors the analytical framework. Segmentation dimensions span product type, application category, microbial versus fungal source platforms, and food processing versus food service end-user tiers. CAGRs derive from fitted growth curves calibrated to EFSA regulatory timeline acceleration and EU Green Deal additive reduction mandate enforcement intensity.
Inputs from EFSA opinion databases and regional health inspection records were available through the study window; gaps in proprietary strain performance data introduce uncertainty bands around thermostability ceiling estimates. Forecasts reflect assumptions regarding EFSA streamlining continuity and EU Green Deal fund disbursement pacing. Stakeholders should weight assumptions against their own operating context and regulatory navigation capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Octadecanedioic Acid (ODDA) Market
Food Additives and Ingredients
Pyranose Oxidase Market
Food Additives and Ingredients
Europe Food Micronized Salt Market
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
North America Dehydrated Onion Market
Food Additives and Ingredients
Brazil Food Additives Market
Food Additives and Ingredients
Europe Feed Anti-Caking Agents Market
Food Additives and Ingredients
Cream of Tartar Market
Food Additives and Ingredients
North America Food Stabilizers Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
Natural Food Color Ingredients Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Natural Food Color Additives Market
Food Additives and Ingredients
Argentina Food Acidulants Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
Nisin for Food Market