
 United States Bread Market | 2026-2036
United States Bread Market Size, Share, and Industry Trends Forecast 2026-2036
United States Bread Market Insights
Bakery technician staffing is collapsing across industrial bread plants, forcing automation upgrades and line consolidation that alter competitive economics. Flowers Foods leverages its direct-store-delivery network to sustain shelf-space dominance in the Southeast and Mid-Atlantic. Bimbo Bakeries USA anchors national scale through centralized milling and baking operations spanning dozens of plants. General Mills differentiates in the premium segment through specialty grain formulations and clean-label positioning.
Bread comprises a baked staple produced from fermented dough containing wheat flour, water, salt, and leavening agents, typically achieving moisture content between 35 and 40 percent and undergoing thermal processing at 200 to 230 degrees Celsius to develop crumb structure and crust coloration. Its primary commercial purpose is delivering a low-cost, shelf-stable carbohydrate source for retail and food service channels. Whole wheat and multigrain varieties are capturing margin pools as health-conscious consumers trade up from value-tier white bread. Gluten-free bread remains the fastest-growing product type, though production complexity and ingredient costs constrain widespread profitability. Supermarkets and hypermarkets dominate distribution channel volume, while online retail is expanding fastest among direct-to-consumer subscription models.
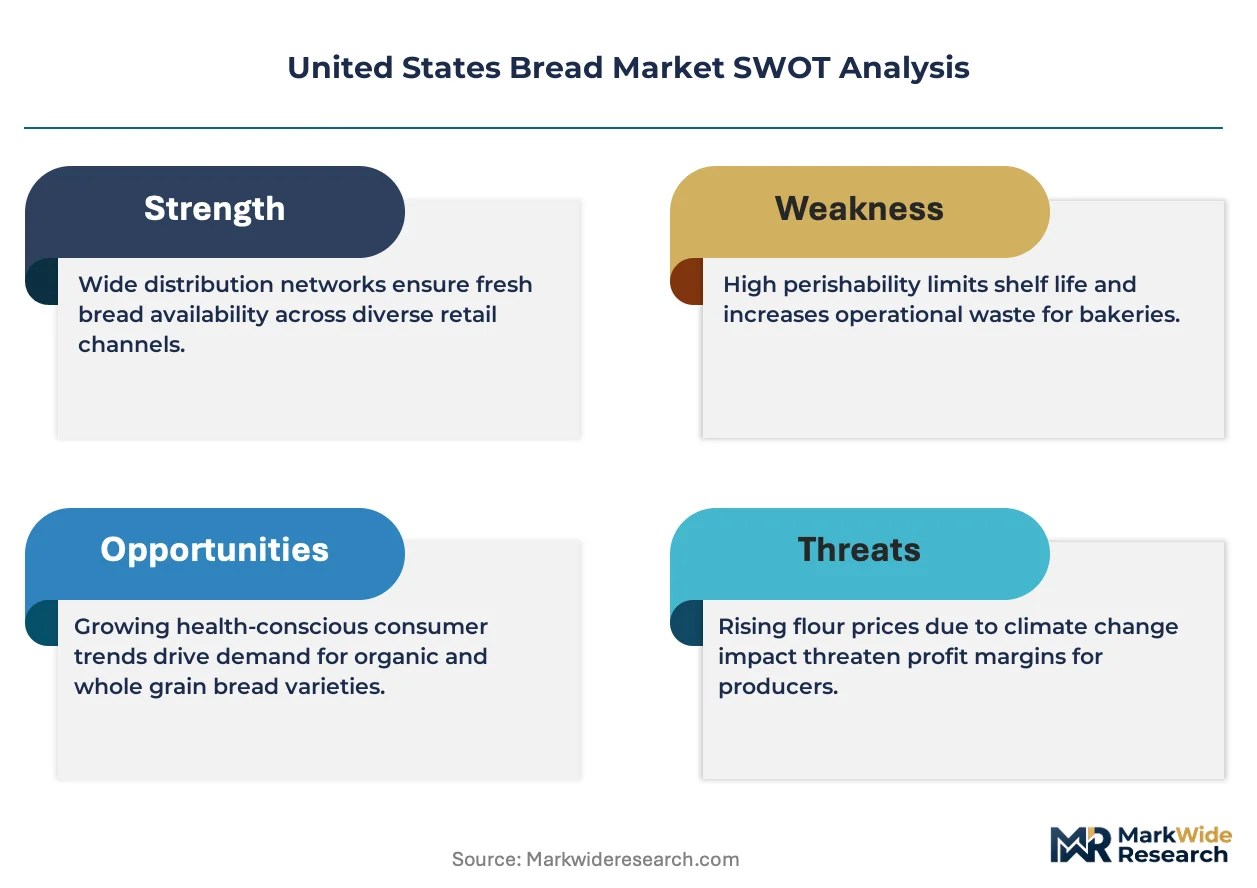
The FDA enforces food additive regulations and allergen labeling under the Food Safety Modernization Act, directly shaping ingredient sourcing and cross-contamination protocols in commercial bakeries. USDA grade standards for wheat and the FDA's forthcoming sodium reduction targets are tightening formulation requirements and elevating compliance costs for mid-tier producers. State-level cottage food laws and health department codes in California, Texas, and New York create fragmented oversight for artisan and small-batch entrants. Stakeholders must monitor labor automation trajectories and regulatory compliance thresholds to calibrate capital deployment between mass-market scale and premium specialization.
Market Dynamics
The FDA's sodium reduction mandates and updated Nutrition Facts labeling requirements are compressing formulation flexibility while accelerating capital deployment toward clean-label reformulation capabilities across commercial baking operations.
Growth Catalysts
- Clean-label migration:Consumer preference for simplified ingredient decks is pulling reformulation investment toward natural preservatives and fermented flavor enhancers in premium bread lines.
- Food service expansion:Quick-service chains and fast-casual operators are embedding artisan and specialty bread SKUs into limited-time offerings, expanding throughput requirements for regional bakers.
- Southeast population inflows:Interstate migration patterns into Florida, Georgia, and the Carolinas are concentrating per-capita consumption growth and retail square footage expansion.
Market Restraints
- Wheat input volatility:Hard red winter wheat futures and freight differentials expose margin compression risk for non-integrated bakers lacking captive milling capacity.
- Supply concentration:Consolidated enzyme and dough conditioner suppliers create single-source vulnerability for mid-tier producers reformulating for sodium reduction targets.
- Technical formulation barriers:Salt reduction beyond 15% degrades dough rheology and shelf stability without compensatory process modifications or expensive potassium chloride blends.
Strategic Opportunities
- Direct-to-consumer subscription:Online retail channels for gluten-free and specialty grain breads bypass traditional slotting fee structures and capture lifetime value data.
- Regulatory tailwind:The FDA's forthcoming front-of-pack labeling guidance creates first-mover advantage for brands already positioned around fiber content and whole grain certification.
- Technology convergence:Continuous mixing systems combined with real-time moisture sensing enable mass customization without sacrificing line throughput economics.
Industry Challenges
- Automation technician scarcity:Industrial bread plants face collapsing availability of PLC programmers and preventive maintenance specialists capable of servicing integrated packaging and inspection lines.
- Legacy system integration:ERP upgrades for lot traceability compliance under FSMA create data migration friction with decades-old batch recording infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Bread Market |
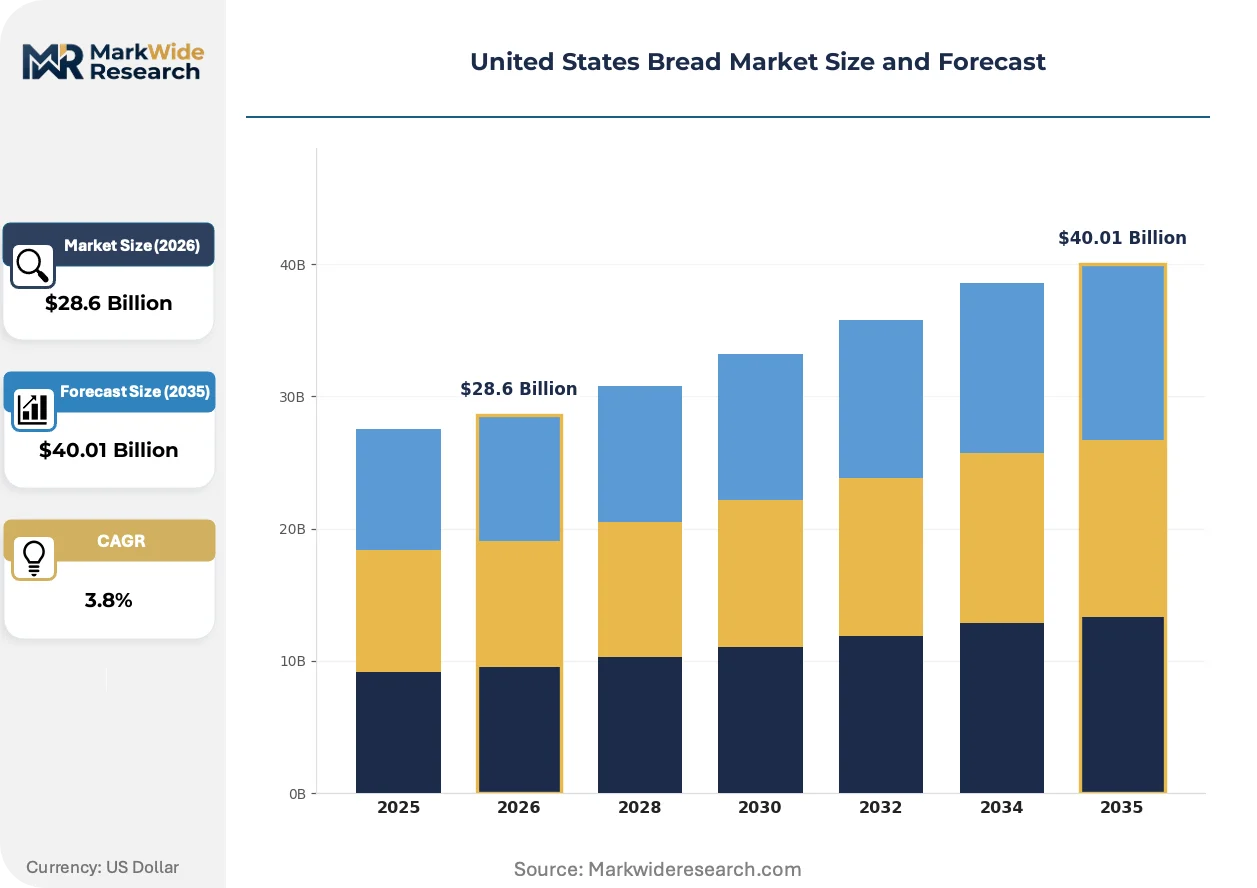
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $40.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Bread, Whole Wheat Bread, Multigrain Bread, Gluten-Free Bread Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Bakeries Price Tier: Premium, Mid-Range, Value, Discount End User: Households, Cafés, Restaurants, Food Services |
| Companies Covered | General Mills, Aryzta, Bimbo Bakeries USA, Associated British Foods, Lantmännen, Flowers Foods, Kraft Heinz, Britannia Industries, Harvest Moon Baking Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Bread Market Trends and Innovations
Reformulation chemistry, processing automation, and channel disintermediation are converging to reshape competitive economics across value-tier and premium bread segments simultaneously.
Sourdough and long-fermentation processing is fragmenting production scale assumptions in commercial baking. Mid-size regional bakers are adopting retarded fermentation and liquid levain systems to mimic artisan texture without full craft labor intensity. This technology is fragmenting the historical dichotomy between mass-market efficiency and premium positioning, enabling hybrid models that capture margin pools previously reserved for small-batch entrants.
The FDA's updated Nutrition Facts labeling requirements and draft sodium reduction targets are tightening formulation guardrails for commercial bakers. Compliance timelines are compressing reformulation windows while elevating R&D expenditure thresholds. Mid-tier producers without dedicated analytical laboratories or regulatory affairs staff face disproportionate adaptation costs relative to integrated national operators.
Food service procurement is consolidating bread sourcing decisions at the distributor level rather than individual operator discretion. Broadline distributors are deploying private-label bread programs that displace branded SKUs in institutional accounts and regional chain restaurants. This concentration is most visible in the Southeast, where distributor consolidation and direct-store-delivery network density create switching friction for incumbent suppliers.
United States Bread Market Segmentation
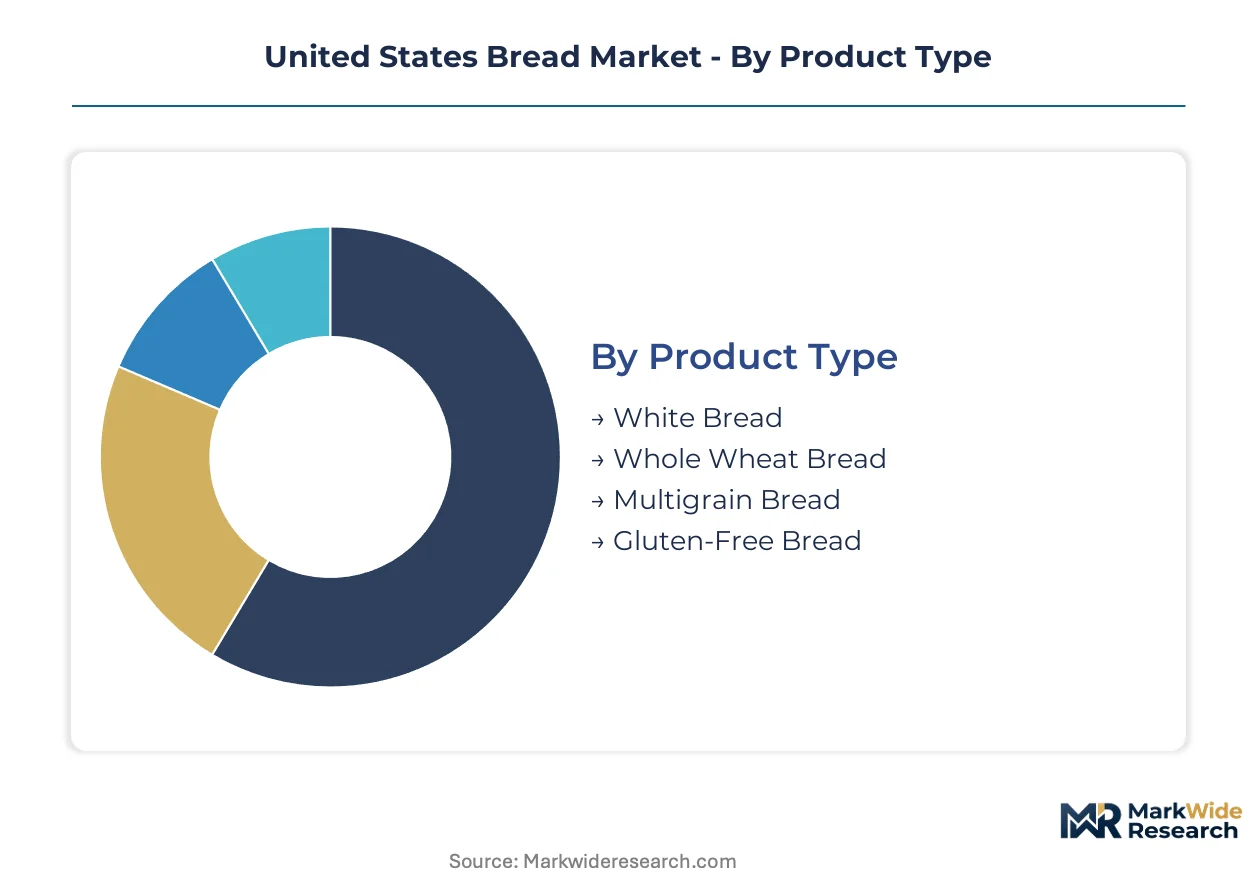
Bread market segmentation reveals divergent margin structures and channel economics across product types and price tiers. Understanding these divisions exposes where capital deployment yields differential returns and where regulatory pressures concentrate compliance burdens.
Product Type:
Channel-mix patterns vary sharply across bread types, with whole wheat and multigrain varieties commanding premium shelf placement in supermarkets while gluten-free SKUs migrate toward online direct-to-consumer channels.
- White Bread:Standardized loaf specifications with enriched flour formulations and 35-40% moisture content. Southeast retail chains and quick-service restaurants anchor volume demand as population inflows expand per-capita consumption in Florida and Georgia.
- Whole Wheat Bread:Milled from hard red winter wheat with bran and germ retention for fiber certification. Food service operators in the Mid-Atlantic are embedding whole wheat buns into limited-time offerings, pulling regional bakery capacity toward whole grain lines.
- Multigrain Bread:Composite formulations incorporating oats, flax, and sunflower seeds for texture differentiation. Clean-label positioning captures shelf-space premiums in California and Texas natural grocery channels.
- Gluten-Free Bread:Rice flour and tapioca starch bases with xanthan gum binding systems. Ingredient cost premiums and production complexity constrain profitability despite expanding household demand.
By volume, white bread leads. By growth pace, gluten-free varieties are climbing the fastest.
Distribution Channel:
Cost-tier stratification determines channel dominance, with value-tier products concentrating in high-velocity supermarket formats while premium SKUs fragment across specialty bakeries and subscription models.
- Supermarkets:High-throughput retail environments with centralized bakery procurement and slotting fee structures. Southeast and Mid-Atlantic chains leverage direct-store-delivery networks to minimize out-of-stock rates on high-rotation white and whole wheat lines.
- Convenience Stores:Grab-and-go oriented with limited SKU counts and compressed shelf life requirements. Interstate highway corridors and urban transit hubs in Texas and Florida drive morning daypart velocity for single-serve sandwich bread.
- Online Retail:Subscription and direct-to-consumer models bypass traditional distributor markups. Gluten-free and long-fermentation artisan varieties capture lifetime value data and repeat purchase loyalty.
- Bakeries:Service-counter and scratch-baking operations with localized production. California cottage food law exemptions and New York health department codes create fragmented oversight for small-batch entrants.
Supermarkets dominate absolute throughput. Online retail is expanding most quickly among emerging channels.
Price Tier:
Application-specific demand patterns separate tiers, with institutional food service anchoring value-tier volume and health-conscious households trading up toward fiber-certified premiums.
- Premium:Specialty grain formulations with organic certification and extended fermentation processing. Clean-label positioning and whole grain FDA certification command price multiples in coastal metropolitan markets.
- Mid-Range:Enriched wheat blends with simplified ingredient decks and natural preservative systems. Regional supermarket private labels concentrate share in the Southeast and Texas.
- Value:Standardized white bread with calcium propionate shelf-life extension. Quick-service chain procurement and school nutrition programs anchor volume in the Midwest and Southeast.
- Discount:Minimal-ingredient formulations with compressed distribution margins. Dollar store channels and food bank sourcing concentrate demand in rural markets and economically distressed urban zones.
By absolute volume, value-tier SKUs lead. By margin expansion, premium positioning is gaining share fastest.
End User:
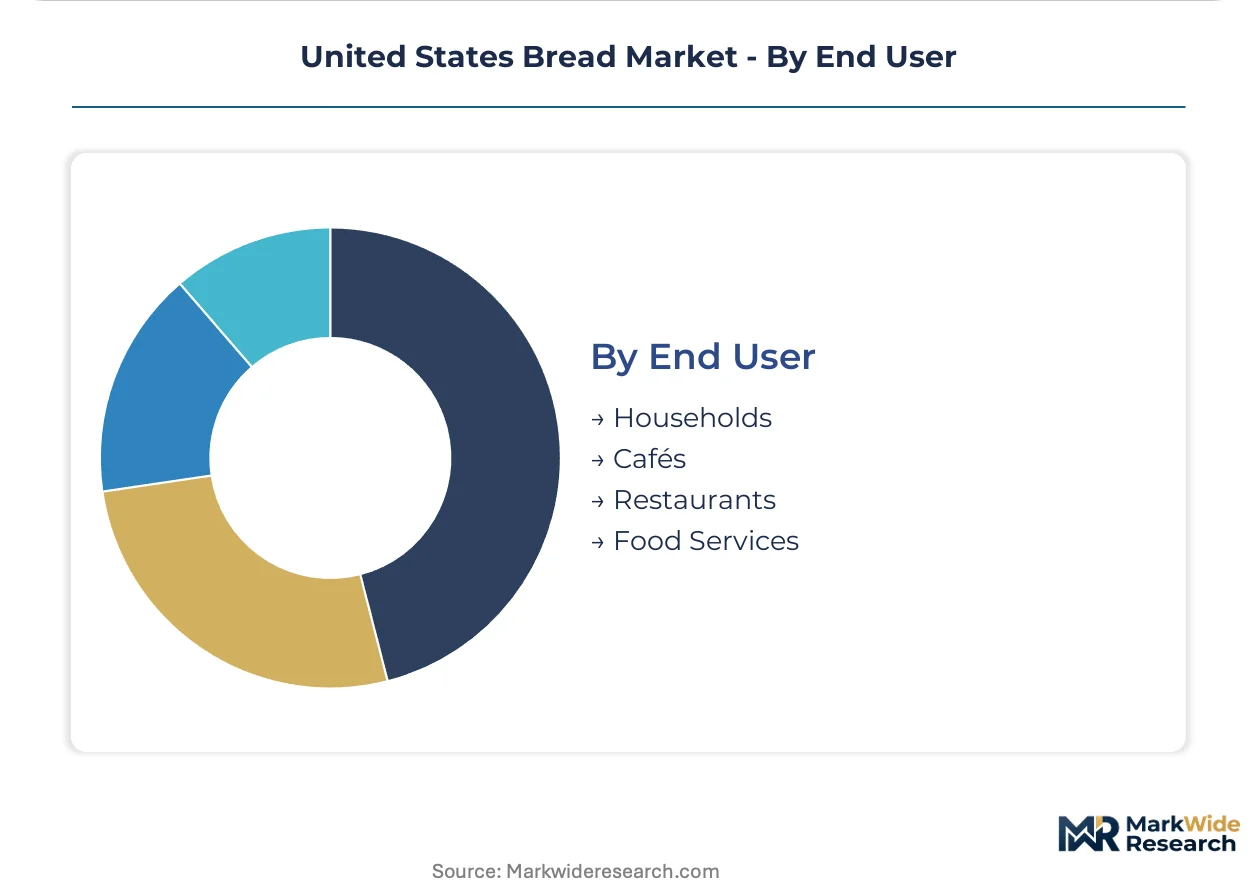
Customer-type concentration shapes product development priorities, with household purchasers driving clean-label reformulation and food service operators demanding extended holding tolerance and portion consistency.
- Households:Retail purchasers selecting for shelf stability, nutritional labeling, and child acceptance. Southeast migration patterns and dual-income time constraints are expanding demand for pre-sliced and resealable packaging formats.
- Cafés:Artisan and sourdough varieties for sandwich and toast applications. Independent operators in Portland, Austin, and Brooklyn differentiate through local bakery partnerships and limited-batch sourcing.
- Restaurants:Broadline distributor procurement with specification consistency requirements. Regional chain rollouts in Florida and Georgia are standardizing bun and roll specifications across franchise networks.
- Food Services:Institutional accounts including K-12, healthcare, and correctional facilities with cost-per-serving constraints. USDA commodity programs and FDA sodium reduction targets are tightening formulation guardrails for contracted suppliers.
Households dominate absolute consumption. Food services are expanding most quickly as institutional outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA sodium reduction mandates and updated Nutrition Facts labeling requirements anchor regulatory pressure across US commercial baking operations, reshaping formulation priorities and compliance investment geography.
Southeast
Population migration into Florida, Georgia, and the Carolinas concentrates per-capita consumption growth and retail square footage expansion. State health department codes in Florida and Georgia create fragmented oversight for artisan entrants while privileging established direct-store-delivery networks. Atlanta and Charlotte anchor industrial baking capacity serving quick-service chain procurement and institutional food service accounts.
Mid-Atlantic
Food service operators embed whole wheat and specialty grain SKUs into limited-time offerings, pulling regional bakery capacity toward reformulation. FDA allergen labeling enforcement under FSMA tightens cross-contamination protocols in Maryland and Virginia processing facilities. Philadelphia and Baltimore metropolitan clusters concentrate mid-tier producers serving school nutrition programs and healthcare institutional accounts.
California
Cottage food law exemptions and health department codes enable small-batch artisan proliferation alongside industrial scale operations. Clean-label positioning captures shelf-space premiums in natural grocery channels across Los Angeles and San Francisco metropolitan markets. Sacramento Valley wheat sourcing and Central Valley distribution hubs support both premium specialty and value-tier production lines.
Texas
Interstate highway corridors and urban transit hubs drive convenience store velocity for single-serve sandwich bread formats. State-level health department regulations create compliance friction for multi-state operators lacking localized regulatory affairs capacity. Dallas-Fort Worth and Houston anchor broadline distributor consolidation that concentrates bread sourcing decisions at the distributor level.
Midwest
Hard red winter wheat proximity reduces input freight differentials for integrated milling and baking operations. USDA commodity programs and FDA sodium targets tighten formulation guardrails for K-12 and correctional facility suppliers. Chicago and Minneapolis-St. Paul metropolitan areas concentrate legacy industrial baking infrastructure with decades-old batch recording systems requiring ERP migration for FSMA lot traceability compliance.
United States Bread Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in US bread manufacturing, with national scale operators commanding centralized milling networks and regional players occupying premium positioning through fermentation technology differentiation. The competitive structure rewards backward integration into wheat sourcing and captive distribution infrastructure. Three archetypes dominate: integrated national bakers with direct-store-delivery dominance, premium specialty fermenters leveraging extended proofing systems, and private-label suppliers to consolidating broadline distributors. Capacity consolidation and clean-label reformulation capability acquisition represent the two dominant competitive moves reshaping participant economics.
Within the integrated national tier, Flowers Foods, Bimbo Bakeries USA, and General Mills occupy positions reflecting scale-driven efficiency, centralized production geography, and premium specialty grain formulation respectively. Flowers Foods exemplifies direct-store-delivery network density sustaining shelf-space dominance in the Southeast and Mid-Atlantic. Bimbo Bakeries USA represents the archetype of national scale through centralized milling and baking operations spanning dozens of plants. General Mills sits within the premium positioning vector through specialty grain formulations and clean-label certification.
| Leading Market Players |
|---|
| General Mills |
| Aryzta |
| Bimbo Bakeries USA |
| Associated British Foods |
| Lantmännen |
| Flowers Foods |
| Kraft Heinz |
| Britannia Industries |
| Harvest Moon Baking Company |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between integrated millers and industrial bakeries lock in hard red winter wheat supply while anchoring flour cost visibility across multi-plant networks. These contracts insulate national operators from spot market volatility while compressing margin flexibility for non-integrated regional producers competing on price.
Pricing Analysis
Contract-based long-term offtake dominates procurement between captive milling operations and high-volume baking facilities, with spot purchasing filling formulation gaps. Price differentiation rests on organic certification tier and geographic delivery radius to Southeast retail clusters. Cost compression in value-tier white bread intensifies as school nutrition program bidding tightens per-serving thresholds. Quick-service chain procurement teams exhibit highest price sensitivity, while direct-to-consumer subscription buyers accept premiums for gluten-free and long-fermentation SKUs.
Supply Chain Analysis
Flour inventory cycles and harvest-to-mill lead times compress formulation windows for seasonal wheat variety switches. Hard red winter wheat concentrates in Kansas, Oklahoma, and Texas, while soft red winter supplies anchor East Coast operations. Production complexity hinges on enzyme and dough conditioner inputs from consolidated specialty chemical suppliers. Single-source vulnerability in potassium chloride blending for sodium reduction creates reformulation bottlenecks. Distribution runs through direct-store-delivery networks in the Southeast and broadline distributor consolidation in Texas and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring revenue from direct-to-consumer subscription models for gluten-free and artisan varieties expands faster than conventional retail throughput, creating service-attach economics that reward customer lifetime value capture over single-transaction margin.
For Market Incumbents: Shield shelf-space dominance in the Southeast by deepening backward integration into Central Valley wheat sourcing and accelerating clean-label certification across whole wheat lines. Automate packaging and inspection systems to offset collapsing PLC programmer availability. Consolidate regional bakery capacity to absorb mid-tier competitors facing FDA sodium compliance cost thresholds. For New Entrants and Emerging Players: FDA whole grain certification fast-tracks premium positioning in California natural grocery channels with compressed regulatory review timelines. White-space concentration sits in gluten-free direct-to-consumer subscription models bypassing slotting fee structures. Target Texas convenience store corridors with single-serve sourdough formats for interstate highway velocity. Launch through online retail partnerships capturing repeat purchase data before brick-and-mortar expansion. For Investors and Strategic Acquirers: Capital is best deployed toward regional fermenters with retarded proofing technology and established distributor relationships in the Southeast and Mid-Atlantic. Long-term viability favors assets with regulatory affairs staff capable of navigating FDA sodium reduction timelines without external consultancy. Monitor FDA front-of-pack labeling guidance publication as inflection signal for clean-label positioned brands.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Milling | Captive flour supply insulates margin from hard red winter wheat futures volatility. |
| Clean-Label Certification Investment | FDA whole grain certification commands shelf-space premiums in coastal metropolitan markets. |
| Direct-to-Consumer Channel Launch | Subscription models bypass distributor markups and capture lifetime value data. |
| Automation System Deployment | Continuous mixing with real-time moisture sensing enables mass customization without throughput sacrifice. |
| Regional Capacity Consolidation | Absorbing mid-tier Southeast bakeries concentrates direct-store-delivery network density. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with plant operations managers, flour procurement leads at integrated millers, category buyers at Southeast supermarket chains, and regulatory affairs directors at commercial bakeries; and secondary validation through USDA wheat grade standards documentation, FDA FSMA compliance guidance, SEC 10-K filings from publicly traded baking operations, and Nielsen retail audit data. Bottom-up volume modeling from plant capacity and utilization rates triangulated against top-down consumption estimates from household panel surveys.
Across the projection horizon, the analytical framework segmented volume and value outputs by product type, distribution channel, price tier, and end-user application, with regional regulatory clusters modeled separately. CAGRs were derived from trend-line extrapolation of historical consumption patterns adjusted for migration-driven per-capita growth in the Southeast. Forecast inputs incorporated FDA sodium reduction compliance timelines and automation adoption curves for packaging and inspection systems.
Decision-makers should treat outputs as directional under base assumptions of stable wheat input costs and unaltered FDA enforcement timelines; material deviation in commodity futures or regulatory acceleration would warrant model refresh. Specific risk factors include tariff exposure on Canadian wheat imports and labor automation adoption lag. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Gluten-Free Bakery Premixes Market
Bakery Products
Pancakes Market
Bakery Products
Packaged Bread Market
Bakery Products
Low Fat Bread Market
Bakery Products
Marzipan Market
Bakery Products
Baking Mats Market
Bakery Products
Vegan Donuts Market
Bakery Products
Dough Conveyor Market
Bakery Products
Global Cake Mix Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Bakers Yeast Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Bread Market
Bakery Products
Vegan Certified Cake Mixes Market
Bakery Products
North America Bakery Products Market
Bakery Products
Baked Foods Market